
 US Plastic Packaging Market | 2026-2036
US Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Plastic Packaging Market Analytics
Aftermarket collection and recycling services is reconfiguring margin pools away from virgin resin conversion toward closed-loop recovery systems. Amcor PLC leverages its North American recycling infrastructure to secure post-consumer feedstock streams. Sealed Air Corporation anchors its growth in automated packaging equipment tied to film-based formats. Berry Global Inc. competes through scale in injection-molded containers serving dairy and condiment brands.
US plastic packaging encompasses thermoformed, extruded, and molded polymer structures—typically ranging from 0.5 mil films to 50 mil rigid containers—engineered to protect, preserve, and distribute consumer and industrial goods. Polyethylene dominates material demand due to its versatility in both flexible films and blow-molded bottles, while polypropylene gains ground in hot-fill and retort applications requiring higher thermal tolerance. Flexible packaging captures the fastest expansion as brands reduce material intensity and shipping cube, though rigid containers sustain premium positioning in healthcare and personal care segments where barrier integrity and child-resistance command priority.
FDA food-contact regulations, EPA recycling and waste reduction frameworks, and state-level extended producer responsibility statutes collectively shape permissible resin compositions, recycled content thresholds, and end-of-life labeling requirements. OSHA workplace safety standards further influence blow-molding and thermoforming line configurations. Stakeholders must monitor how fragmented state legislation converges or diverges on recycled content mandates, as this will determine capital allocation between mechanical recycling upgrades and advanced chemical recycling technologies.
Market Dynamics
State-level extended producer responsibility mandates are forcing resin procurement pivots across US converters, redirecting capital from virgin polyethylene expansion toward mechanical recycling retrofits and advanced chemical recycling pilot plants.
Growth Catalysts
- Flexible Pouch Adoption:Food and beverage manufacturers are abandoning rigid formats for stand-up pouches with resealable closures, cutting material intensity and logistics costs simultaneously.
- EPA Recycling Frameworks:Evolving federal guidelines on post-consumer recycled content thresholds are creating compliant demand pools for rPET and rHDPE resins.
- Midwest Manufacturing Belt:Demand concentration across Ohio, Illinois, and Indiana is anchoring regional converter capacity expansions and co-located recycling infrastructure.
Market Restraints
- Ethylene Feedstock Volatility:Gulf Coast petrochemical corridor exposure to natural gas liquid price swings compresses margin predictability for blow-molded bottle producers.
- Mechanical Recycling Limits:Contamination tolerance thresholds in current sorting technology cap post-consumer resin quality for food-contact applications.
- Paperboard Substitution:E-commerce shippers are piloting fiber-based protective formats in secondary packaging, displacing polyethylene foam and air pillows in select channels.
Strategic Opportunities
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization investments in Texas and Louisiana promise food-grade resin outputs unconstrained by mechanical recycling contamination ceilings.
- Healthcare Barrier Films:Sterile pharmaceutical packaging demands are pulling multilayer coextrusion capacity toward high-barrier nylon-EVOH structures.
- California SB 54 Compliance:The state's 25% recycled content mandate by 2032 is generating premium offtake agreements for certified post-consumer resin suppliers.
Industry Challenges
- Polymer Chemist Shortage:Formulation expertise for compatibilizing mixed-polymer recycle streams is concentrating at a handful of compounders, constraining R&D velocity.
- Multi-Stream Sorting Complexity:MRF upgrades to handle flexible film collection require capital coordination between municipal waste authorities and private packaging producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Plastic Packaging Market |
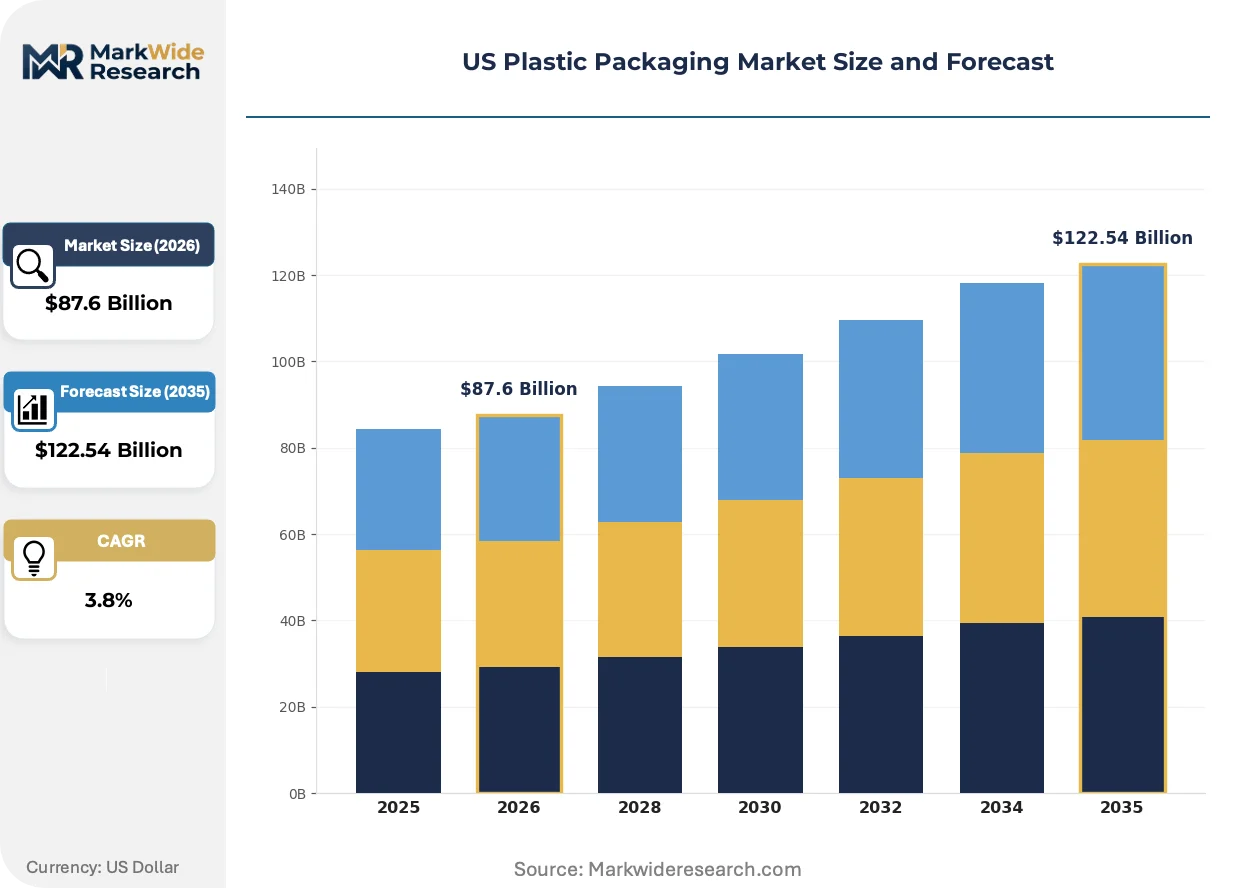
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $122.54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Films, Pouches Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Food & Beverage, Personal Care, Household Products, Healthcare Packaging Type: Flexible Packaging, Rigid Packaging, Resealable Packaging, Biodegradable Packaging |
| Companies Covered | Amcor PLC, Sealed Air Corporation, Sonoco Products Company, Berry Global Inc., Sigma Plastics Group Inc., ProAmpac LLC, Constantia Flexibles, Alpha Packaging Inc., Novolex Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Plastic Packaging Market Evolving Landscape
Active and intelligent packaging integration is redefining shelf-life extension beyond passive barrier properties, embedding sensors and indicators directly into film substrates.
Mono-material polyethylene films are migrating from niche sustainable packaging portfolios toward mainstream adoption by national grocery retailers. Walmart and Target's private-label suppliers are accelerating format conversions to simplify consumer recycling streams. This migration from multilayer complexity is compressing demand for adhesive lamination equipment and EVOH barrier coextrusion lines.
The EPA's forthcoming national recycling strategy is mandating standardized resin identification and recycled content labeling across interstate commerce. Converters face reformulation costs to meet divergent state thresholds while awaiting federal preemption clarity. Food-contact applications are most exposed, with dairy and ready-meal brands demanding third-party certification of post-consumer resin chains.
Brand procurement teams are consolidating supplier rosters to favor converters with integrated recycling operations and verified mass-balance accounting. This consolidation is displacing fragmented spot-market resin purchasing in favor of long-term offtake contracts tied to certified circular feedstock. The shift is most visible in personal care and household chemical segments, where Unilever and Procter & Gamble volume commitments are reshaping competitive access to post-consumer resin supply.
US Plastic Packaging Market Segmentation
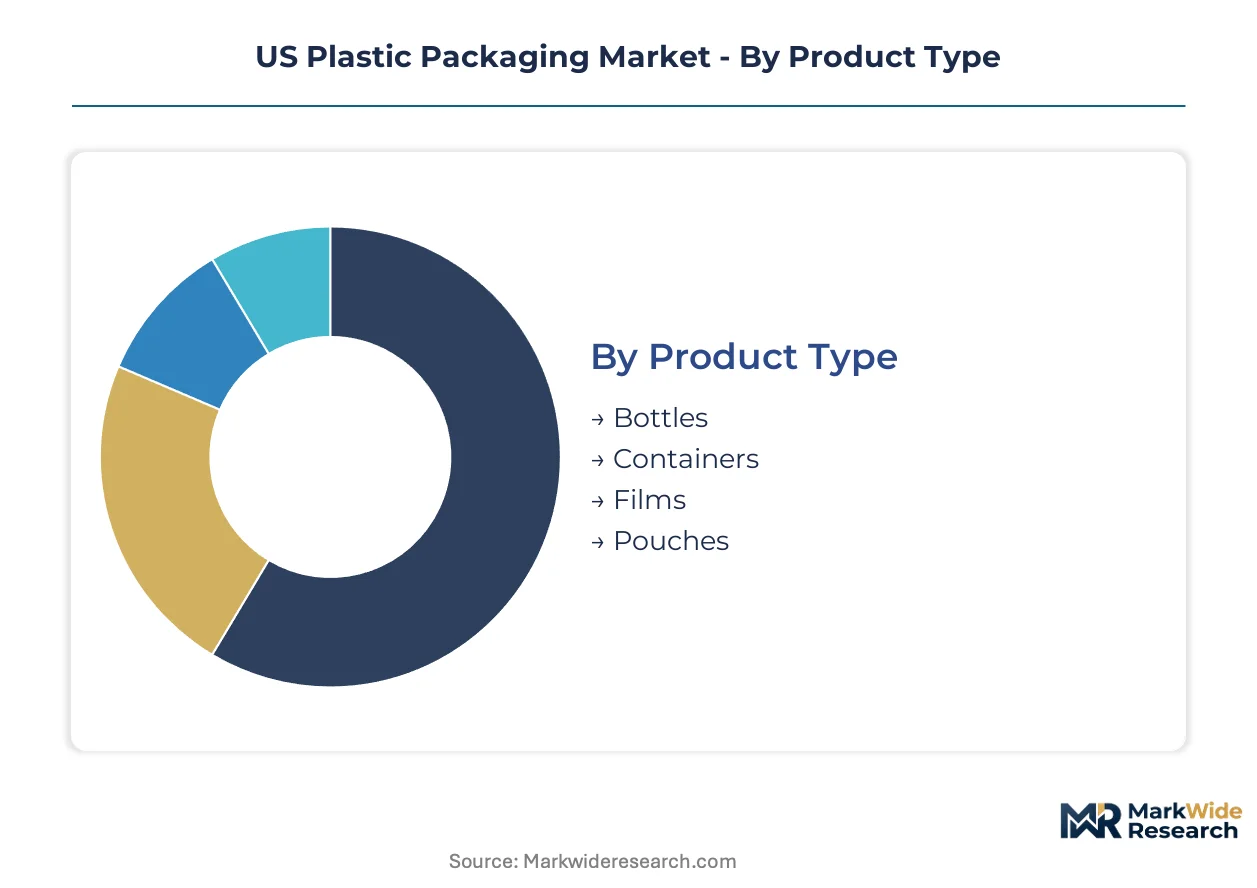
Segmentation in US plastic packaging reveals how resin selection, format engineering, and end-use compliance requirements stratify competitive positioning across converters. Material chemistry and regulatory exposure—not just volume scale—determine margin durability in each category.
Product Type:
Converters align capital equipment with the full spectrum of containment needs, from single-serve beverage units to bulk industrial totes.
- Bottles:Blow-molded HDPE and PET structures dominate carbonated beverages, dairy, and household chemicals. Demand concentrates in Texas and Ohio corridors where resin supply and dairy processing clusters overlap, though lightweighting mandates are compressing gram weights per unit.
- Containers:Injection-molded tubs and pails serve condiments, spreads, and industrial lubricants. Illinois and Indiana food manufacturers anchor regional demand, with tamper-evident closures now standard across dairy and ready-meal segments.
- Films:Cast and blown polyethylene films wrap palletized goods and form primary food contact layers.
- Pouches:Stand-up flexible formats with fitment closures are displacing rigid alternatives in sauces and pet food.
Established volume favors bottles; emerging adoption favors pouches.
Material:
Resin procurement strategies diverge sharply based on thermal performance needs, barrier requirements, and recycled content compliance exposure.
- Polyethylene:Linear low-density and high-density grades supply everything from stretch wrap to milk jugs. FDA food-contact approvals and EPA recycling framework alignment make this the default for converters serving Walmart and Target private-label mandates.
- Polypropylene:Higher melt temperatures suit hot-fill juices, retort pouches, and microwaveable trays. Personal care brands in New Jersey and California are specifying clarified PP for premium aesthetics, though compatibilization with PE recycle streams remains a formulation challenge.
- Polyvinyl Chloride:Medical blister packs and shrink sleeves leverage its clarity and sealability.
- Polystyrene:Foamed trays and hinged clamshells persist in protein packaging despite substitution pressure.
Polyethylene captures the steepest expansion trajectory in flexible formats; polypropylene climbs fastest in hot-fill and retort applications.
End User:
Customer procurement patterns split between price-sensitive commodity categories and specification-intensive regulated segments.
- Food & Beverage:Dairy processors, beverage bottlers, and ready-meal brands drive the majority of domestic resin offtake. Midwest manufacturing belt concentration—Ohio, Illinois, Indiana—creates regional procurement gravity, with shelf-life extension demands pulling multilayer film investment.
- Personal Care:Shampoo, lotion, and cosmetic brands specify heavy-wall bottles and airless pumps. California SB 54 compliance deadlines are forcing recycled content verification across Unilever and Procter & Gamble supply chains.
- Household Products:Bleach, detergent, and cleaner brands favor HDPE bottles with child-resistant closures.
- Healthcare:Sterile barrier systems for pharmaceuticals demand validated seal integrity and particulate control.
Food and beverage anchors absolute volume; healthcare commands premium pricing power.
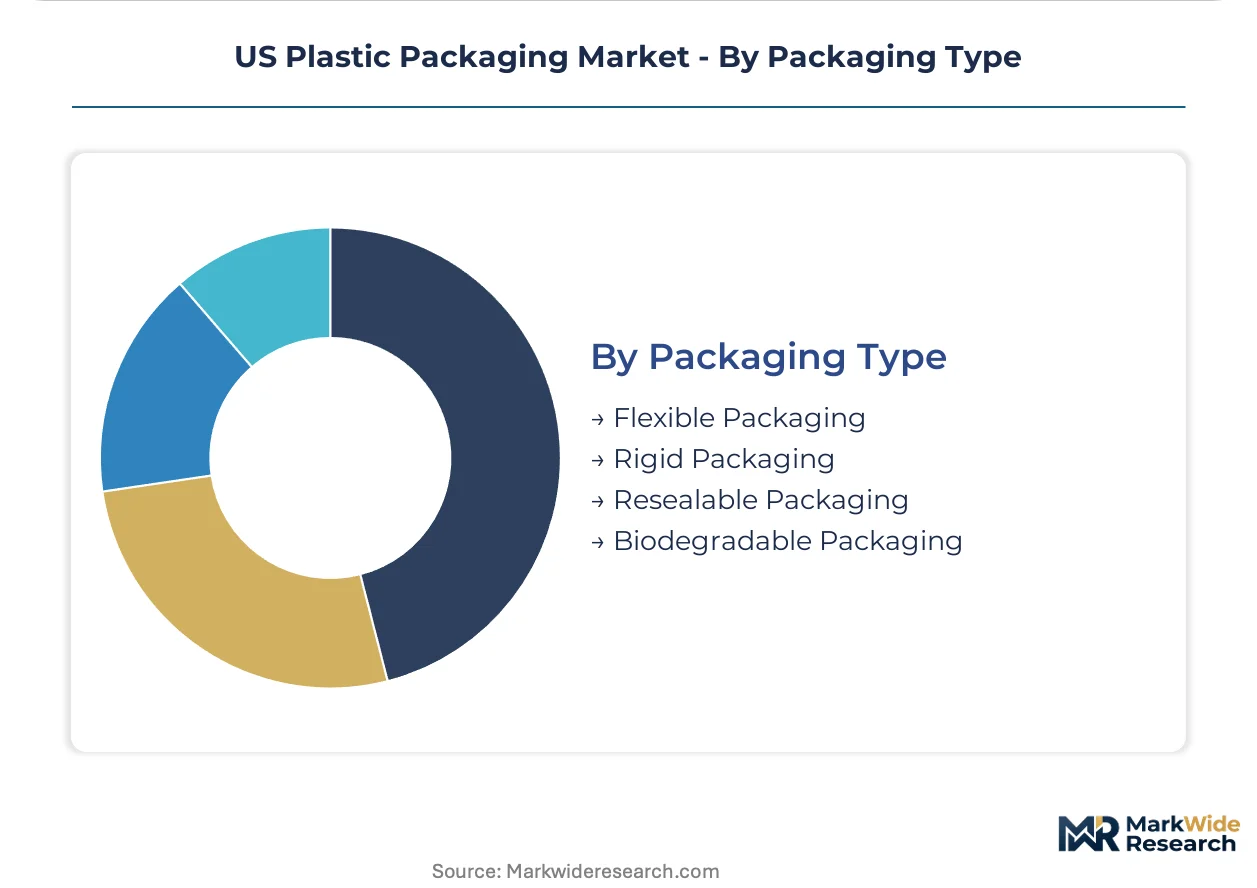
Packaging Type:
Format selection increasingly reflects end-of-life compliance exposure rather than purely functional performance.
- Flexible Packaging:Rollstock, pre-made pouches, and form-fill-seal films minimize material intensity and shipping cube. National grocery retailers are accelerating mono-material PE conversions to simplify consumer recycling streams and meet EPA labeling mandates.
- Rigid Packaging:Bottles, jars, and thermoformed trays sustain premium positioning where barrier integrity and stack strength matter. Healthcare and personal care segments in New Jersey and California maintain rigid format loyalty despite higher per-unit resin content.
- Resealable Packaging:Zipper fitments and press-to-close systems extend product usability in snacks and pet food.
- Biodegradable Packaging:PLA and PHA alternatives serve composting infrastructure pockets in California and Pacific Northwest municipalities.
Flexible formats gain share fastest in food and beverage; rigid structures defend position in healthcare and premium personal care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock access and converter density concentrate plastic packaging supply across three distinct US corridors. Texas Gulf Coast resin production, Midwest dairy and food processing clusters, and California regulatory innovation each shape regional competitive dynamics.
Texas Gulf Coast
Ethylene crackers and polyethylene production facilities anchor the nation's largest virgin resin supply basin. EPA Clean Air Act compliance costs and OSHA process safety management standards drive continuous emissions monitoring investments. Houston and Beaumont host integrated converter operations serving blow-molded bottle demand for beverage and household chemical brands.
Midwest Manufacturing Belt
Ohio, Illinois, and Indiana food processors generate concentrated demand for thermoformed containers and flexible films. State-level extended producer responsibility legislation in Illinois and proposed frameworks in Ohio compel recycled content integration. Chicago and Indianapolis converter clusters co-locate with dairy processing and ready-meal production facilities.
California
SB 54 mandates 25% recycled plastic content by 2032, forcing reformulation across personal care and food packaging supply chains. CalRecycle enforcement mechanisms and third-party certification requirements elevate compliance costs. Los Angeles and Central Valley converters pilot chemical recycling partnerships to secure food-grade post-consumer resin streams.
Southeast
Georgia and Florida beverage bottlers and protein processors drive rigid container demand. FDA food-contact facility registrations dominate regulatory exposure for converters serving national grocery retailers. Atlanta and Jacksonville distribution hubs position packaging suppliers for e-commerce fulfillment network access.
Pacific Northwest
Washington and Oregon municipal composting infrastructure supports limited biodegradable packaging adoption. State-level plastic bag bans and producer responsibility frameworks shape format selection away from single-use films. Seattle and Portland converters focus on fiber-plastic hybrid formats for regional grocery and foodservice channels.
US Plastic Packaging Market Competitive Landscape
Integrated resin-to-package conglomerates and specialized flexible film converters split the market along capital intensity lines. Three to five multinational suppliers control majority share in rigid containers and barrier films, while mid-tier regional players dominate commodity stretch wrap and industrial pails. Strategic archetypes include vertically integrated resin converters with captive recycling streams, equipment-anchored packaging system suppliers, and niche healthcare barrier specialists. Capacity expansion and mechanical recycling retrofit investments constitute the dominant competitive moves as brands consolidate supplier rosters around circular feedstock verification.
Among North American packaging conglomerates, Amcor PLC, Sealed Air Corporation, and Berry Global Inc. occupy positions across the integrated converter archetype. These entities exemplify scale-driven supply arrangements with national grocery and personal care brands, anchoring long-term offtake contracts tied to post-consumer resin certification requirements. Their market presence reflects capital deployment toward co-located recycling infrastructure and automated packaging equipment integration.
| Leading Market Players |
|---|
| Amcor PLC |
| Sealed Air Corporation |
| Sonoco Products Company |
| Berry Global Inc. |
| Sigma Plastics Group Inc. |
| ProAmpac LLC |
| Constantia Flexibles |
| Alpha Packaging Inc. |
| Novolex Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Gulf Coast ethylene cracker utilization running above 85 percent is compressing spot resin premiums while simultaneously pressuring converters toward long-term offtake commitments. This tightness in virgin polyethylene supply is accelerating margin bifurcation between integrated resin-to-package conglomerates and non-integrated regional players.
Pricing Analysis
Aftermarket collection and recycling service contracts now drive lifetime value for converter operations more than per-unit resin sales. Three-tier pricing structure across certified post-consumer resin, mass-balance attributed, and virgin-only tiers separates Amcor and Berry Global integrated operations from spot-market dependent competitors. Pricing pressure stems from California SB 54 compliance deadlines forcing premature recycled content adoption before supply scale. Food and beverage brands exhibit highest price sensitivity due to thin category margins, while pharmaceutical packaging buyers absorb premiums for barrier integrity certification.
Supply Chain Analysis
Extended payment terms from Walmart and Target private-label procurement teams are cascading liquidity pressure upstream to film extruders and blow-molding operations. Raw material sourcing concentrates in Texas and Louisiana petrochemical corridors, with mechanical recycling feedstock drawing from Midwest MRF networks and California curbside collection programs. Supply chain risk centers on single-source dependence for pyrolysis-derived food-grade resin pilot volumes. Distribution runs through regional converter clusters co-located with dairy processing in Ohio, Illinois, and Indiana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as destocking in consumer packaged goods channels reverses and resin inventory normalization restarts procurement velocity.
For Market Incumbents: Harden mechanical recycling infrastructure in the Midwest manufacturing belt against chemical recycling scale-up threats from Texas Gulf Coast pilots. Deepen captive post-consumer resin supply through municipal MRF partnership structures. Prioritize FDA food-contact certification for rHDPE streams to defend dairy and ready-meal contract renewals against emerging flexible pouch substitutes. For New Entrants and Emerging Players: Establish a beachhead in healthcare barrier films where EVOH-nylon multilayer coextrusion expertise remains scarce and premium pricing persists. Target Pacific Northwest biodegradable packaging pilots where municipal composting infrastructure creates differentiated demand pools. Lead with mass-balance accounting transparency to bypass capital-intensive mechanical recycling scale requirements. For Investors and Strategic Acquirers: Long-term, this sits as a circular feedstock infrastructure play because regulatory recycled content mandates are structurally permanent rather than cyclical. Acquisition targets should emphasize compounders with compatibilization R&D capabilities for mixed-polymer streams. The signal to watch is Illinois and Ohio EPR legislation progression, which would accelerate Midwest converter consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Retrofit | Ohio and Illinois converters secure CalRecycle-compliant rPET supply ahead of SB 54 enforcement. |
| Chemical Recycling Joint Venture | Louisiana pyrolysis partnerships unlock food-grade resin output unconstrained by contamination ceilings. |
| Mono-Material Film Conversion | Walmart private-label suppliers simplify consumer recycling streams and reduce adhesive lamination capital. |
| Healthcare Barrier Capacity Addition | New Jersey and California pharmaceutical packaging demands pull coextrusion investment toward nylon-EVOH structures. |
| Municipal MRF Partnership Structure | Chicago and Indianapolis converters anchor post-consumer feedstock security through waste authority coordination. |
Research Methodology
A standing panel of resin procurement directors, blow-molding plant managers, FDA regulatory affairs leads, and Walmart/Target category buyers provided ongoing calibration across primary fieldwork. Secondary validation drew from EPA recycling framework disclosures, CalRecycle SB 54 implementation documents, ACC resin production statistics, and SEC 10-K filings from packaging conglomerates. Bottom-up volume modeling across product type, material chemistry, and end-use segments triangulated against top-down petrochemical capacity assessments.
Scenario-bracketing framed low, base, and high cases across natural gas liquid price volatility, EPR legislation adoption timing, and chemical recycling commercialization pace. Segmentation dimensions modeled included packaging format, resin type, thermal performance tier, recycled content compliance exposure, and regional manufacturing cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories. Forecast inputs incorporated dairy processing capacity expansion in the Midwest and beverage bottler lightweighting targets.
Stress conditions across ethylene feedstock price spikes, mechanical recycling contamination rate deterioration, and California regulatory enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding policy continuity and technology cost curves. Macroeconomic recession, federal preemption of state EPR laws, or breakthrough paperboard barrier performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Global Plastic Pails Market