
 Thermoforming Plastic Market | 2026-2036
Thermoforming Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoforming Plastic Market Outlook
Healthcare procurement is rotating toward sterile, single-use thermoformed trays as hospital infection control protocols tighten worldwide. Berry Global Inc sustains R&D intensity in multilayer barrier films for pharmaceutical applications. Dart Container Corp dominates foodservice thermoforming with captive resin sourcing and high-throughput production networks across North America.
Thermoforming plastic involves heating thermoplastic sheets to pliable forming temperatures, then shaping them over molds via vacuum, pressure, or mechanical force to produce thin-gauge disposables or heavy-gauge structural parts with wall thickness typically ranging from 0.005 to 0.500 inches. The process serves primary industrial functions in protective packaging, sterile medical containment, and lightweight automotive interior panels. Polypropylene leads material consumption due to its chemical resistance and microwave compatibility in food packaging, while vacuum forming remains the most mature technology segment with established tooling economics. Pressure forming captures premium margin pools where cosmetic detail and dimensional precision exceed vacuum-formed capabilities.
The FDA enforces stringent sterility validation requirements for medical device thermoformed packaging under 21 CFR Part 820 quality system regulations. EPA guidelines on volatile organic compound emissions from thermoforming operations constrain solvent-based decorating processes and accelerate water-based ink adoption. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that will reshape post-consumer collection infrastructure and recycled content mandates.
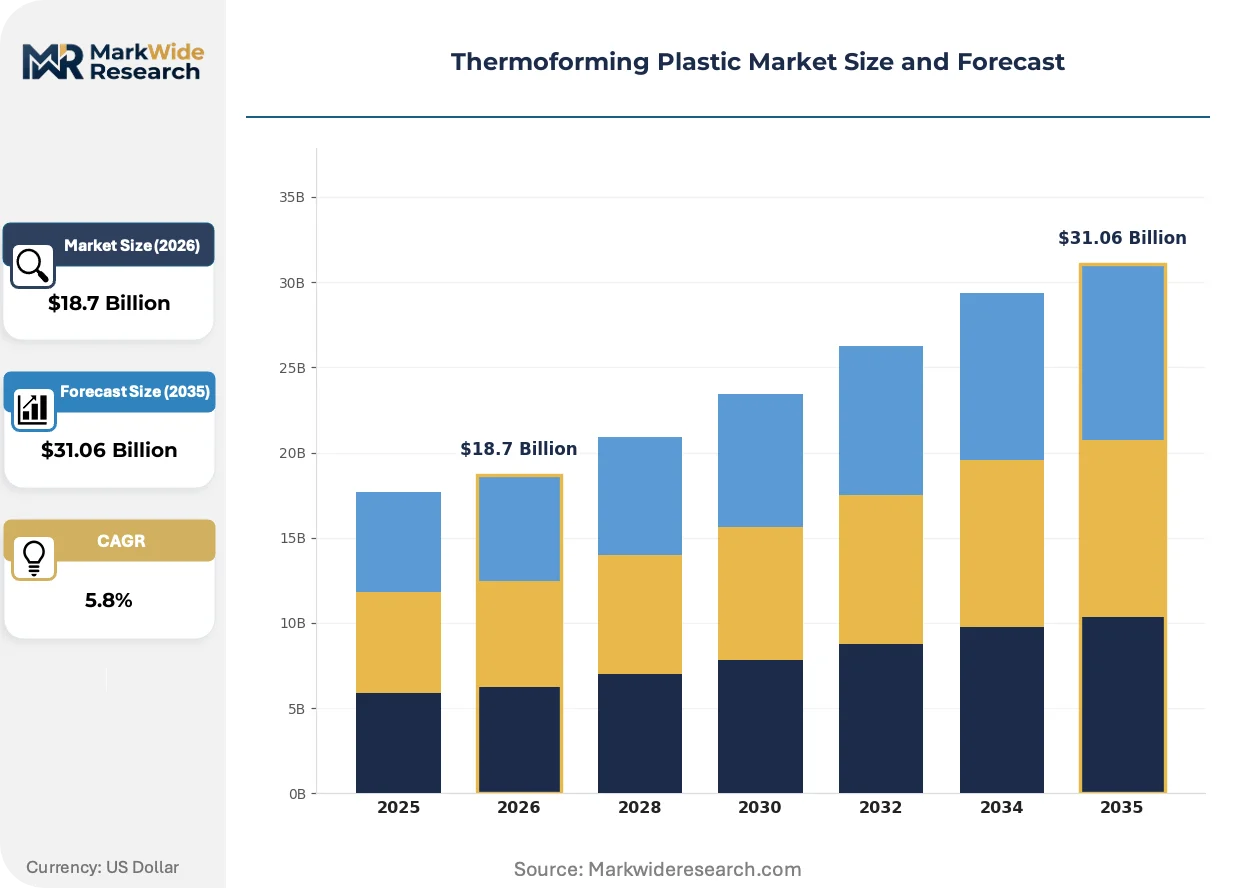
Market Dynamics
Healthcare sterile barrier requirements and Europe's F-Gas Regulation are forcing material transitions across thermoforming value chains, compressing virgin polymer demand while expanding bio-based and recycled feedstock qualification programs.
Growth Catalysts
- MDR sterility mandates:Europe's Medical Device Regulation tightens validation protocols for surgical tray packaging, accelerating multilayer film adoption in German and French medical device clusters.
- Automotive lightweighting:Polypropylene honeycomb panels displace heavier injection-molded components in electric vehicle battery housings and interior modules.
- California EPR infrastructure:Extended producer responsibility laws mandate post-consumer recycled content thresholds, stimulating domestic reprocessing capacity investment.
Market Restraints
- Propylene feedstock volatility:Crude oil and natural gas liquid price swings compress margins for commodity sheet producers without captive resin supply.
- Tooling cost barriers:Pressure forming aluminum molds require 3-5x capital outlay versus vacuum forming tooling, limiting mid-volume product launches.
- Thin-gauge substitution:Fiber-based molded pulp gains shelf space in chilled food segments where moisture resistance requirements moderate.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO quality upgrades and export-oriented contract manufacturing expansion create demand for ISO 15378-compliant barrier trays.
- Chemical recycling integration:Pyrolysis-derived feedstocks enable food-contact approval for recycled PP where mechanical reprocessing fails purity thresholds.
- Direct-to-hospital distribution:Sterile kit providers bypass traditional distributor markups through consignment inventory models anchored by RFID-tracked tray serialization.
Industry Challenges
- Tooling engineer scarcity:Mold flow simulation and CNC machining expertise concentrates among aging workforces in Midwest US and Stuttgart industrial zones.
- ISO 13485 certification timelines:Medical packaging qualification cycles extend 18-24 months, freezing supplier switches until contract renewal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoforming Plastic Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Biodegradable, Rigid Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Food Packaging, Medical Devices, Automotive Components, Consumer Goods Technology: Vacuum Forming, Pressure Forming, Drape Forming, Roll Forming |
| Companies Covered | Pactiv LLC, Berry Global Inc, Sonoco Products Company, Genpak LLC, D&W Fine Pack LLC, Amcor plc, Anchor Packaging LLC, Placon Corporation, Dart Container Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoforming Plastic Market Strategic Shifts
Active material science breakthroughs and regulatory chemistry restrictions are fragmenting thermoforming process development into parallel high-performance and circular-economy tracks.
Multilayer coextrusion technology is bifurcating thermoforming barrier film supply into pharmaceutical-grade EVOH-PP structures and simplified mono-material designs for retail recycling streams. German automotive suppliers adopt the former for fuel cell component protection, while Nordic grocery chains specify the latter to meet national deposit-return sorting requirements. This technical split is compressing mid-tier film converters lacking capital for dual qualification pathways.
REACH substance restrictions and F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon blowing agents in insulated thermoformed containers. European converters pivot to hydrocarbon and CO2-based alternatives, reformulating polystyrene foam density profiles for cold-chain pharmaceutical distribution. The regulatory friction falls heaviest on small-format foodservice disposables where insulation value must be preserved at lower material thickness.
Hospital supply chain rationalization is consolidating sterile tray procurement through integrated delivery networks and group purchasing organizations. Independent medical device manufacturers lose direct customer relationships as IDNs centralize specification authority, forcing thermoformers to qualify as approved vendor list suppliers rather than direct sellers. The concentration is most advanced in US metropolitan hospital systems and emerging in UK National Health Service supply hubs.
Thermoforming Plastic Market Segmentation
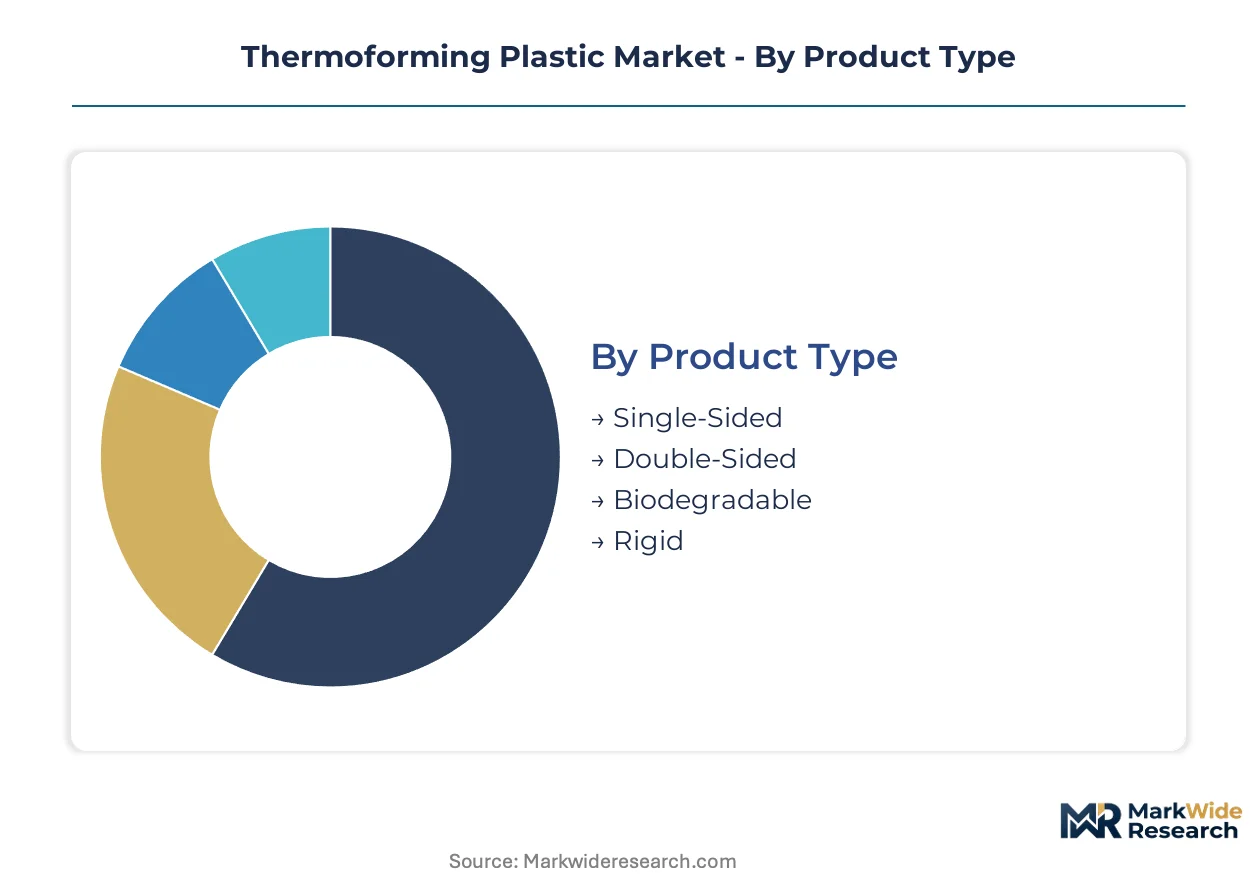
Thermoforming plastic segments map to distinct channel economics and customer procurement patterns. Product type and material specifications determine tooling investment levels, while end-use verticals dictate regulatory compliance pathways and sterilization requirements.
Product Type:
Channel mix varies sharply across product architectures, with single-sided and rigid formats dominating high-volume foodservice distribution while double-sided and biodegradable variants command premium positioning through specialty distributors and direct OEM relationships.
- Single-Sided:One-sided forming creates thin-gauge disposables with minimal material draw ratios. Quick-service restaurant chains and institutional foodservice distributors in Germany and the United States channel the bulk of volume through consolidated procurement platforms.
- Double-Sided:Symmetrical forming produces clamshell packaging and hinged containers with structural integrity on both faces. Pharmaceutical contract manufacturers in India and precision medical device clusters around Stuttgart specify these formats for sterile barrier validation under MDR protocols.
- Biodegradable:PLA and starch-based formulations serve Nordic grocery retailers meeting national deposit-return sorting requirements. Composting infrastructure gaps in most markets constrain channel expansion beyond premium organic food segments.
- Rigid:Heavy-gauge structural panels with wall thickness exceeding 0.125 inches. Automotive Tier 1 suppliers in Bavaria and battery housing manufacturers source through engineered plastics distributors with CNC trimming capabilities.
By volume, single-sided leads. By growth pace, biodegradable formats are expanding most quickly.
Material:
Cost tier stratification separates commodity resins from performance grades, with polypropylene and polyethylene anchoring high-throughput sheet extrusion while PVC and polystyrene serve defensible niche applications with specialized barrier or insulation requirements.
- Polypropylene:Semi-crystalline thermoplastic with chemical resistance and microwave compatibility. Food packaging converters across North American retail channels and German automotive interior panel producers represent the primary demand concentration.
- Polyethylene:LDPE and HDPE grades offer moisture barrier and low-temperature flexibility. Cold-chain pharmaceutical distributors and chilled dairy processors specify PE-lined multilayer structures for extended shelf stability.
- Polyvinyl Chloride:Rigid and plasticized formulations provide clarity and RF-sealability. Medical device blister packs and pharmaceutical unit-dose packaging retain PVC despite REACH substance scrutiny due to established sterilization validation libraries.
- Polystyrene:Crystal and high-impact grades enable thin-wall forming with insulation value. European cold-chain pharmaceutical distribution and foodservice disposables maintain demand despite F-Gas Regulation pressures on foam density profiles.
Polypropylene generates the highest absolute tonnage. Polystyrene faces the steepest substitution pressure from fiber-based alternatives.
End User:
Application-driven specification authority concentrates in food packaging procurement teams and hospital supply chain rationalization programs, with automotive and consumer goods representing project-based demand with longer qualification cycles.
- Food Packaging:Primary and secondary containment for fresh, frozen, and prepared foods. Quick-service restaurant chains and retail grocery private-label programs drive standardization toward mono-material recyclable designs.
- Medical Devices:Sterile barrier systems for surgical instruments, implants, and diagnostic equipment. German and French medical device clusters under MDR mandates specify multilayer EVOH-PP structures through integrated delivery network procurement.
- Automotive Components:Lightweight interior panels, battery housings, and fuel cell protection systems. Bavarian and Stuttgart-area OEMs pressure-form polypropylene honeycomb structures for electric vehicle platforms.
- Consumer Goods:Electronics clamshells, cosmetic trays, and toy packaging. Brand owners specify pressure-formed PETG and RPET for retail shelf presence through specialty packaging distributors.
Food packaging commands the largest volume share. Medical devices deliver the highest margin per kilogram processed.
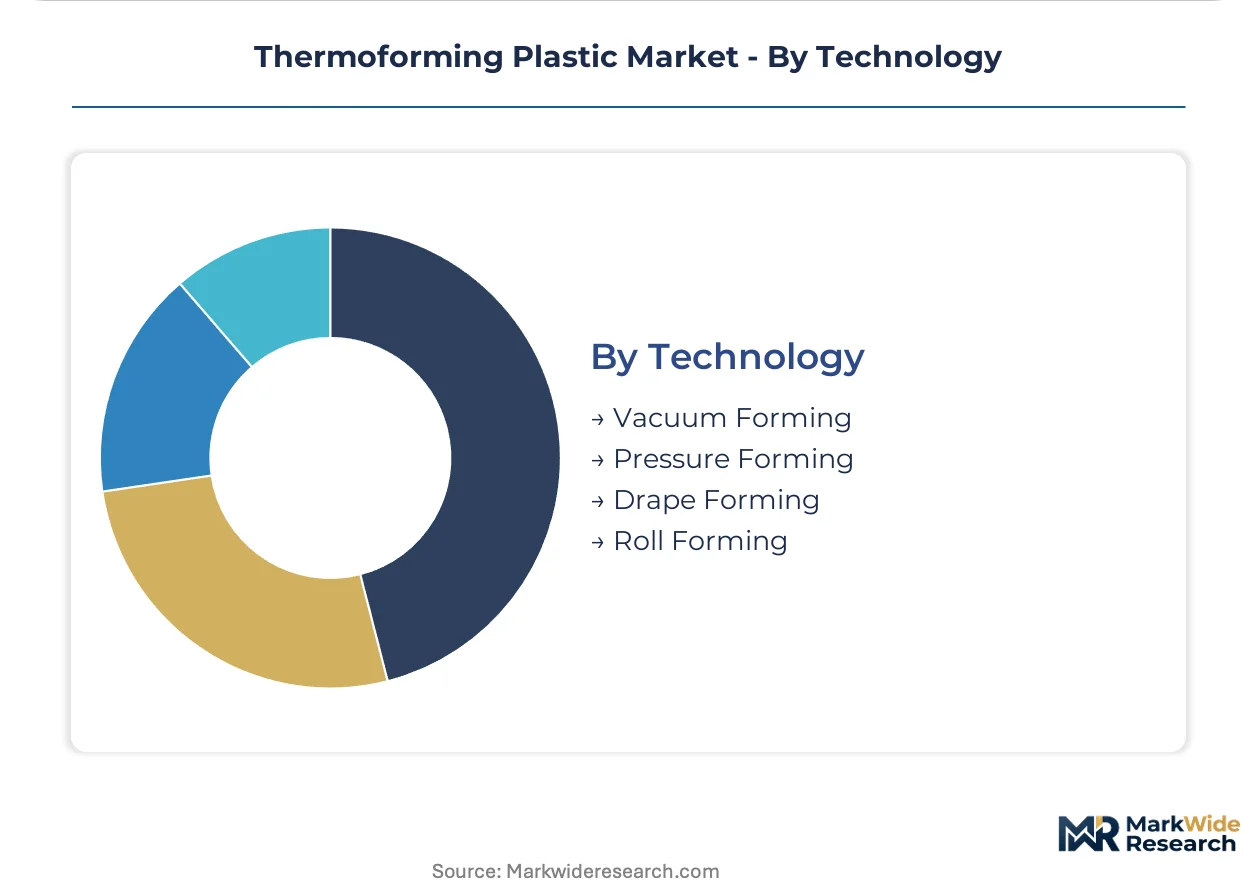
Technology:
Maturity gradients separate established vacuum forming infrastructure from capital-intensive pressure forming capacity, with drape and roll forming occupying specialized geometries and continuous processing niches respectively.
- Vacuum Forming:Negative pressure draws heated sheet over single-sided molds. Established tooling economics and aluminum pattern costs 3-5x below pressure forming enable mid-volume food packaging and industrial tray production.
- Pressure Forming:Positive air pressure plus vacuum delivers cosmetic detail and dimensional precision exceeding vacuum-formed capabilities. German automotive suppliers and medical device packaging converters invest in pressure forming for fuel cell components and pharmaceutical barrier trays.
- Drape Forming:Gravity and mechanical force shape sheet over simple male molds without vacuum. Aircraft interior panel manufacturers and bathtub producers utilize drape forming for large-format, low-cosmetic applications.
- Roll Forming:Continuous rotary thermoforming for high-speed thin-gauge production. Cup and lid manufacturers serving North American foodservice channels deploy roll forming for 24/7 operational intensity.
Vacuum forming retains the installed equipment base. Pressure forming is gaining share fastest in medical and automotive premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital supply chain rationalization concentrates procurement authority in German medical device clusters and US integrated delivery networks. Automotive lightweighting programs anchor demand in Bavaria and Stuttgart industrial zones. Food packaging standardization drives volume through North American retail consolidation platforms.
Germany
Medical device manufacturers in Baden-Württemberg and Bavaria specify multilayer EVOH-PP barrier trays under MDR sterility mandates. The F-Gas Regulation accelerates hydrocarbon blowing agent transitions in polystyrene foam cold-chain containers. Stuttgart-area automotive Tier 1 suppliers pressure-form polypropylene honeycomb panels for electric vehicle battery housings.
United States
Quick-service restaurant chains and institutional foodservice distributors channel single-sided thermoformed disposables through consolidated procurement platforms. California's extended producer responsibility laws mandate post-consumer recycled content thresholds. Midwest industrial zones concentrate vacuum forming capacity for mid-volume food packaging and industrial tray production.
India
CDSCO quality upgrades and export-oriented pharmaceutical contract manufacturing expansion create demand for ISO 15378-compliant barrier trays. Domestic reprocessing capacity investment lags behind regulatory ambition. Mumbai-Pune and Ahmedabad pharmaceutical clusters qualify multilayer film converters for sterile kit serialization programs.
France
Pharmaceutical contract manufacturers specify double-sided clamshell formats for MDR-compliant sterile barrier validation. ANSM enforces sterility validation protocols parallel to FDA 21 CFR Part 820 requirements. Lyon and Paris medical device clusters consolidate procurement through integrated delivery network centralization.
China
NMPA medical device packaging regulations tighten validation protocols for surgical tray exports to European markets. Yangtze River Delta automotive suppliers adopt pressure-formed polypropylene interior panels for domestic electric vehicle platforms. Shanghai and Suzhou thermoforming converters qualify pyrolysis-derived feedstocks for food-contact recycled PP applications.
Thermoforming Plastic Market Competitive Environment
Player mix skews toward diversified packaging conglomerates with captive resin sourcing and high-throughput production networks. The vendor base separates into three functional tiers: scale-driven foodservice specialists with continental distribution footprints, medical-grade converters with ISO 13485 certification libraries, and regional sheet extruders serving mid-volume industrial applications. Competitive moves concentrate on backward integration into resin compounding and strategic partnerships with chemical recycling technology providers.
Within the diversified packaging tier, Berry Global Inc and Amcor plc represent archetypal positions spanning pharmaceutical barrier films and foodservice disposables. Dart Container Corp exemplifies scale-driven North American foodservice concentration with captive polystyrene resin supply. Pactiv LLC occupies a mid-market position between commodity food packaging and specialty medical containment applications.
| Leading Market Players |
|---|
| Pactiv LLC |
| Berry Global Inc |
| Sonoco Products Company |
| Genpak LLC |
| D&W Fine Pack LLC |
| Amcor plc |
| Anchor Packaging LLC |
| Placon Corporation |
| Dart Container Corp |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification timelines gate both supplier qualification and price differentiation simultaneously, stretching medical packaging contract cycles to 18-24 months while compressing margin flexibility for converters serving German and French device clusters. Buyers with captive sterilization validation libraries command 15-20% price premiums over commodity sheet extruders lacking MDR-compliant barrier film capabilities.
Pricing Analysis
Cost-plus contracts with propylene indexation dominate resin-intensive segments, linking sheet extruder margins to crude oil and natural gas liquid benchmarks. Pricing stratifies across ISO 13485-certified medical grades, FDA-validated pharmaceutical tiers, and commodity foodservice disposables. Cost compression in thin-gauge food packaging intensifies as fiber-based molded pulp substitutes gain chilled-food shelf space. Quick-service restaurant chains exhibit highest price sensitivity, while sterile barrier pharmaceutical buyers prioritize supply assurance over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German automotive Tier 1 suppliers pressure-forming polypropylene honeycomb panels, whereas US Midwest foodservice converters maintain strategic resin stockpiles against propylene feedstock volatility. Supply concentrates in Germany, the United States, and China. Raw material flows draw from Saudi Arabian and US Gulf Coast propylene crackers, European polystyrene foam producers, and Chinese pyrolysis-derived recycled PP pilots. Single-source vulnerability concentrates in multilayer EVOH-PP film supply for MDR-compliant medical packaging. Distribution runs through integrated delivery networks for hospital systems and consolidated procurement platforms for North American foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where ISO 13485 certification libraries and MDR sterilization validation protocols create switching costs that freeze supplier relationships across multi-year contract windows.
For Market Incumbents: Secure backward integration into resin compounding to offset propylene feedstock volatility compressing commodity sheet margins. Expand pressure forming capacity in Stuttgart and Bavaria automotive clusters to capture electric vehicle battery housing demand. Defend against chemical recycling entrants by accelerating pyrolysis-derived food-contact PP qualification ahead of mechanical reprocessing purity thresholds.
For New Entrants and Emerging Players: Anchor in Indian pharmaceutical packaging white space created by CDSCO quality upgrades and export-oriented contract manufacturing expansion. Target ISO 15378-compliant barrier tray supply to Mumbai-Pune and Ahmedabad clusters underserved by multilayer film converters. Pursue direct-to-hospital distribution models with RFID-tracked tray serialization to bypass entrenched distributor markups.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pressure forming capacity for medical and automotive premium segments, favoring asset-heavy consolidators over sheet extrusion specialists. Over the projection horizon, acquisition value concentrates in mid-cap converters with dual qualification pathways for both pharmaceutical-grade EVOH-PP structures and mono-material retail recycling designs. Watch for inflection when California and New York extended producer responsibility laws trigger recycled content mandate thresholds that reshape domestic reprocessing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive propylene supply insulates Berry Global and Dart Container from feedstock volatility compressing commodity sheet margins. |
| Pressure Forming Capacity Expansion | Stuttgart-area automotive Tier 1 suppliers capture electric vehicle battery housing demand with cosmetic-grade polypropylene honeycomb panels. |
| Chemical Recycling Feedstock Qualification | Pyrolysis-derived PP enables food-contact approval where mechanical reprocessing fails purity thresholds under FDA 21 CFR Part 820. |
| Direct-to-Hospital Distribution Models | RFID-tracked tray serialization allows sterile kit providers to bypass traditional distributor markups in US integrated delivery networks. |
| Dual Pathway Film Converter Investment | Simultaneous qualification for pharmaceutical EVOH-PP and mono-material retail designs defends against Nordic grocery chain specification shifts. |
Study Parameters
The analysis maps single-sided disposables, double-sided clamshells, biodegradable formats, and rigid structural panels, each validated through thermoforming plant managers, medical device packaging procurement leads, automotive Tier 1 supplier engineers, and pharmaceutical contract manufacturing quality directors. Primary fieldwork combined with secondary validation from FDA 21 CFR Part 820 filings, EMA MDR submission databases, German KBA automotive component registrations, and ACC thermoplastics trade data. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Consistency checks validated outputs against customs trade flows, SEC 10-K resin sourcing disclosures, and hospital GPO contract award databases. Segmentation dimensions span product architecture, material grade tier, end-use vertical, and forming technology maturity. CAGRs derived from regression against propylene price elasticity, automotive lightweighting content-per-vehicle trends, and pharmaceutical packaging sterilization validation cycle frequencies. Forecast inputs incorporate electric vehicle platform adoption curves and extended producer responsibility law implementation schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained MDR enforcement stringency and California EPR threshold compliance; material deviation would warrant model refresh. Revision becomes warranted when propylene feedstock volatility exceeds historical bands or when fiber-based molded pulp substitution rates in chilled food segments cross critical shelf-space thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
CPET Trays Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
United States PET Packaging Market
Plastic Packaging
Polyethylene Terephthalate-Glycol (PETG) Market
Plastic Packaging
Plastic Shrink Wrap Market