
 Plastic Caulk Tube Market | 2026-2036
Plastic Caulk Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Caulk Tube Market Analytics
Residential renovation is restructuring the Plastic Caulk Tube Market as homeowners defer new construction and prioritize weatherproofing and energy-efficiency upgrades. Berry Global Inc. leverages its blown-film extrusion capabilities to supply multi-layer barrier tubes that extend sealant shelf life. Sonoco Products Company anchors North American distribution through its rigid packaging network serving big-box retailers. Silgan Holdings Inc. competes via high-speed injection-molded tube lines optimized for construction-grade adhesive volumes.
Plastic caulk tubes are cylindrical extruded or injection-molded containers, typically manufactured from high-density polyethylene or polypropylene, designed to dispense viscous sealants, adhesives, and caulking compounds through a tapered nozzle under manual or pneumatic pressure. Standard tubes dominate volume shipments across construction applications, while specialty tubes command margin premiums through integrated nozzles, dual-chamber designs, and compatibility with hybrid polymer sealants. Polyethylene leads material selection for cost-sensitive construction channels, whereas polypropylene gains traction in automotive and industrial segments requiring elevated temperature resistance.
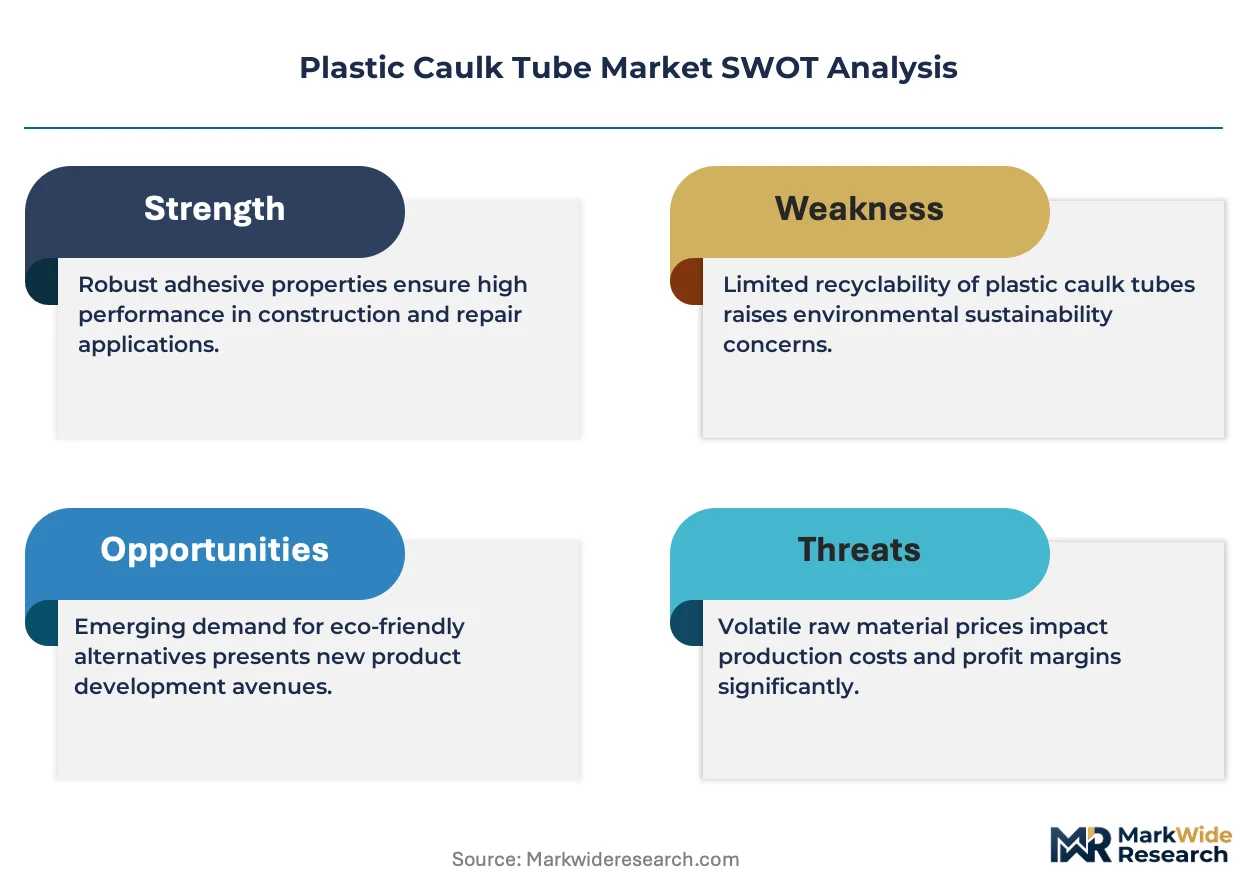
The EPA regulates volatile organic compound emissions in architectural sealants, directly influencing tube sealing performance requirements and compatibility testing protocols. REACH compliance in Europe restricts certain plasticizers and additives in polyethylene and polypropylene formulations, reshaping material sourcing decisions for exporters. FDA food-contact standards apply to caulk tubes used in commercial kitchen and food-processing facility applications, creating a certification tier that commands price premiums. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that threaten to impose packaging recovery fees on single-use plastic tubes.
Market Dynamics
Residential renovation cycles are compressing product lifecycles as homeowners prioritize weatherproofing over new construction, forcing tube manufacturers to align production schedules with volatile retrofit demand patterns rather than stable housing starts.
Growth Catalysts
- EPA VOC emission standards:Tightening limits on architectural sealant leakage are compelling manufacturers to engineer multi-layer barrier tubes that extend product shelf life and reduce environmental liability.
- Polypropylene temperature resistance:Automotive and industrial segments are adopting this material for elevated-heat applications, opening volume channels beyond traditional construction markets.
- United States housing stock age:Elevated retrofit rates in older residential inventory sustain above-average tube consumption as weatherization programs expand.
Market Restraints
- Polyethylene resin price volatility:Feedstock cost fluctuations compress margins for cost-sensitive construction-grade tube production.
- REACH plasticizer restrictions:European chemical regulations limit additive options in polyethylene and polypropylene formulations, complicating export compliance.
- Flexible aluminum-laminate substitutes:Collapsible metal tubes capture premium sealant segments requiring absolute oxygen and moisture barriers.
Strategic Opportunities
- FDA food-contact certification tier:Commercial kitchen and food-processing facility applications command price premiums for compliant tube designs.
- Dual-chamber tube technology:Hybrid polymer sealant compatibility enables value-added dispensing solutions for specialized construction chemicals.
- Extended producer responsibility laws:California and New York packaging recovery mandates create first-mover advantages for recyclable or take-back program infrastructure.
Industry Challenges
- Blown-film extrusion technician scarcity:Multi-layer barrier manufacturing requires specialized operator skills that outpace current vocational training pipeline output.
- High-speed injection-molded line capex:Construction-grade adhesive volume production demands capital-intensive equipment upgrades that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Caulk Tube Market |
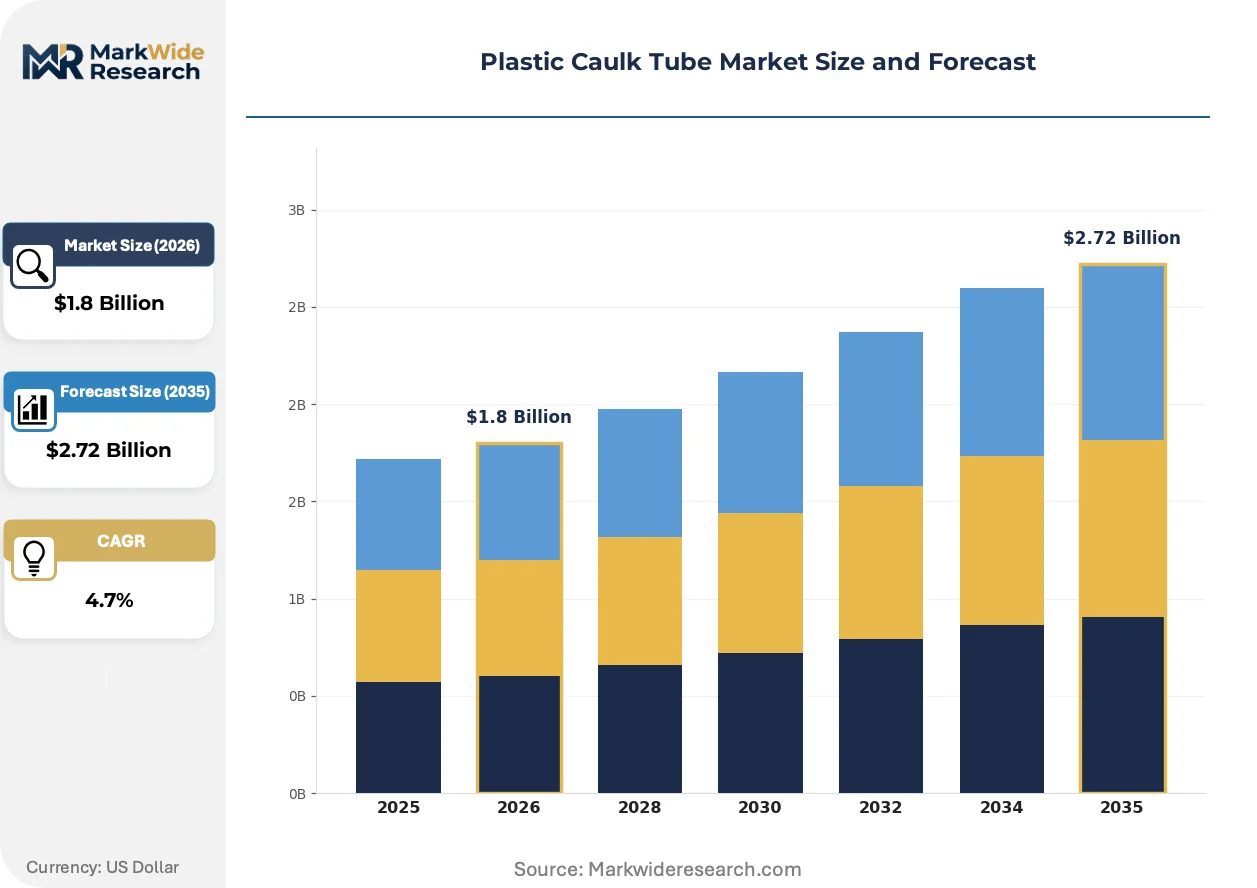
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubes, Specialty Tubes, Refillable Tubes, Squeeze Tubes End User: Construction Companies, DIY Enthusiasts, Retailers, Distributors Material: Polyethylene, Polypropylene, PVC, Rubber-Based Application: Construction, Home Improvement, Automotive, Industrial |
| Companies Covered | Berry Global Inc., Sonoco Products Company, Silgan Holdings Inc., Amcor plc, Huhtamaki Oyj, UFlex Limited, Albea Group, Ritter GmbH, Nordson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Caulk Tube Market Evolving Landscape
Tube engineering is pivoting from commodity containment toward functional performance as sealant chemistry complexity and regulatory shelf-life requirements intensify material science demands across the value chain.
Multi-layer coextruded barrier structures are absorbing moisture and oxygen ingress challenges that previously limited hybrid polymer sealant commercialization. Construction chemical formulators are specifying these tubes for silicone-modified polyurethane and silyl-terminated polymer products. The technology is absorbing margin from conventional monolayer polyethylene tubes in premium renovation channels.
REACH compliance deadlines are forcing reformulation of polyethylene and polypropylene additive packages across European supply chains. Manufacturers serving export markets must maintain parallel material specifications or abandon continental revenue streams. Construction-grade tube exporters are responding by qualifying alternative plasticizer systems through accelerated aging protocols.
Big-box retail private-label consolidation is compressing supplier counts as Home Depot and Lowe's rationalize their caulk tube vendor bases. Regional distributors are losing shelf access to direct manufacturer relationships with national purchasing teams. This concentration is most visible in United States residential renovation channels where housing stock age sustains volume but margin pressure intensifies.
Plastic Caulk Tube Market Segmentation
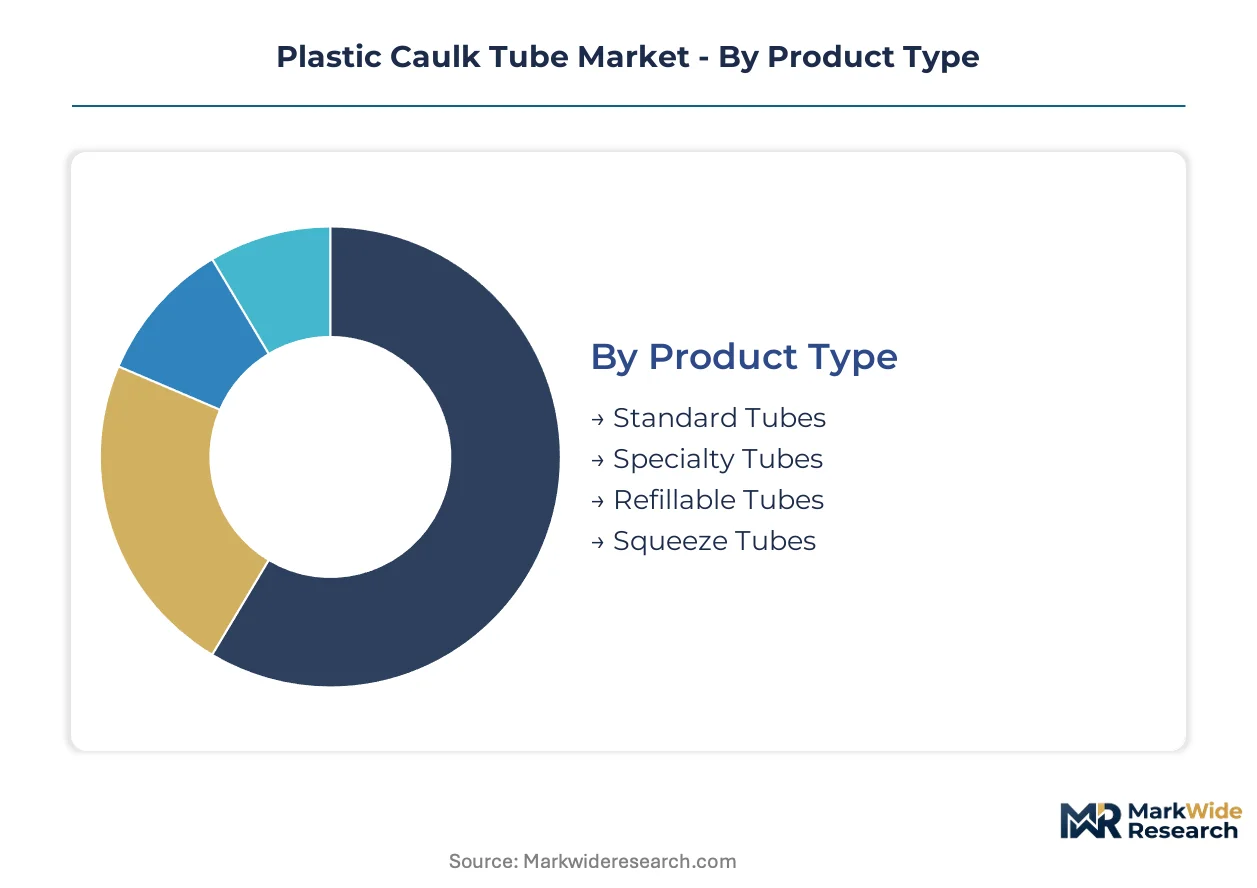
Plastic caulk tube segmentation reveals divergent margin profiles across construction, automotive, and food-processing channels. Material selection and barrier performance specifications now separate commodity volume from certified premium tiers as regulatory shelf-life requirements intensify.
Product Type:
Volume shipments concentrate in basic cylindrical formats, while engineered designs capture margin through integrated functionality and multi-layer construction.
- Standard Tubes:Monolayer high-density polyethylene construction dominates construction-grade sealant packaging. United States residential renovation channels absorb the bulk of shipments as weatherization program expansion sustains retrofit-driven consumption.
- Specialty Tubes:Coextruded barrier structures with integrated nozzles and dual-chamber designs address hybrid polymer sealant compatibility requirements. Automotive and industrial segments specify these for elevated-temperature and extended-shelf-life applications.
- Refillable Tubes:Reusable polyethylene formats target commercial kitchen and food-processing facilities requiring FDA food-contact compliance certification.
- Squeeze Tubes:Flexible low-density polyethylene variants serve small-volume DIY and touch-up applications through retail hardware channels.
Mature deployment sits with Standard Tubes. Newer deployment is concentrated in Specialty Tubes.
End User:
Procurement authority separates price-sensitive bulk purchasing from specification-driven technical sourcing.
- Construction Companies:Volume purchasers of standard polyethylene tubes for sealant and adhesive dispensing on commercial and residential job sites. Scheduling volatility from renovation cycle compression strains manufacturer production planning.
- DIY Enthusiasts:Small-quantity buyers of squeeze tubes and single-use formats through big-box retail channels. Home Depot and Lowe's vendor base consolidation limits supplier access.
- Retailers:Private-label program managers demanding direct manufacturer relationships with national purchasing teams.
- Distributors:Regional logistics intermediaries losing shelf access to consolidated retail procurement structures.
Volume concentration rests with Construction Companies. Margin expansion is climbing the fastest among Retailers.
Material:
Resin selection balances cost position against thermal performance and regulatory compliance burden.
- Polyethylene:Cost-optimized high-density and low-density grades dominate construction channel shipments. Feedstock price volatility compresses margins for volume producers.
- Polypropylene:Higher melt temperature and chemical resistance specifications attract automotive underhood and industrial adhesive applications. REACH plasticizer restrictions complicate European export formulations.
- PVC:Rigid extruded formats serve specialized construction chemical dispensing with specific compatibility requirements.
- Rubber-Based:Elastomeric formulations for extreme flexibility and chemical resistance in niche industrial sealant applications.
Cost-driven deployment dominates Polyethylene. Performance-driven conversion is expanding most quickly into Polypropylene.
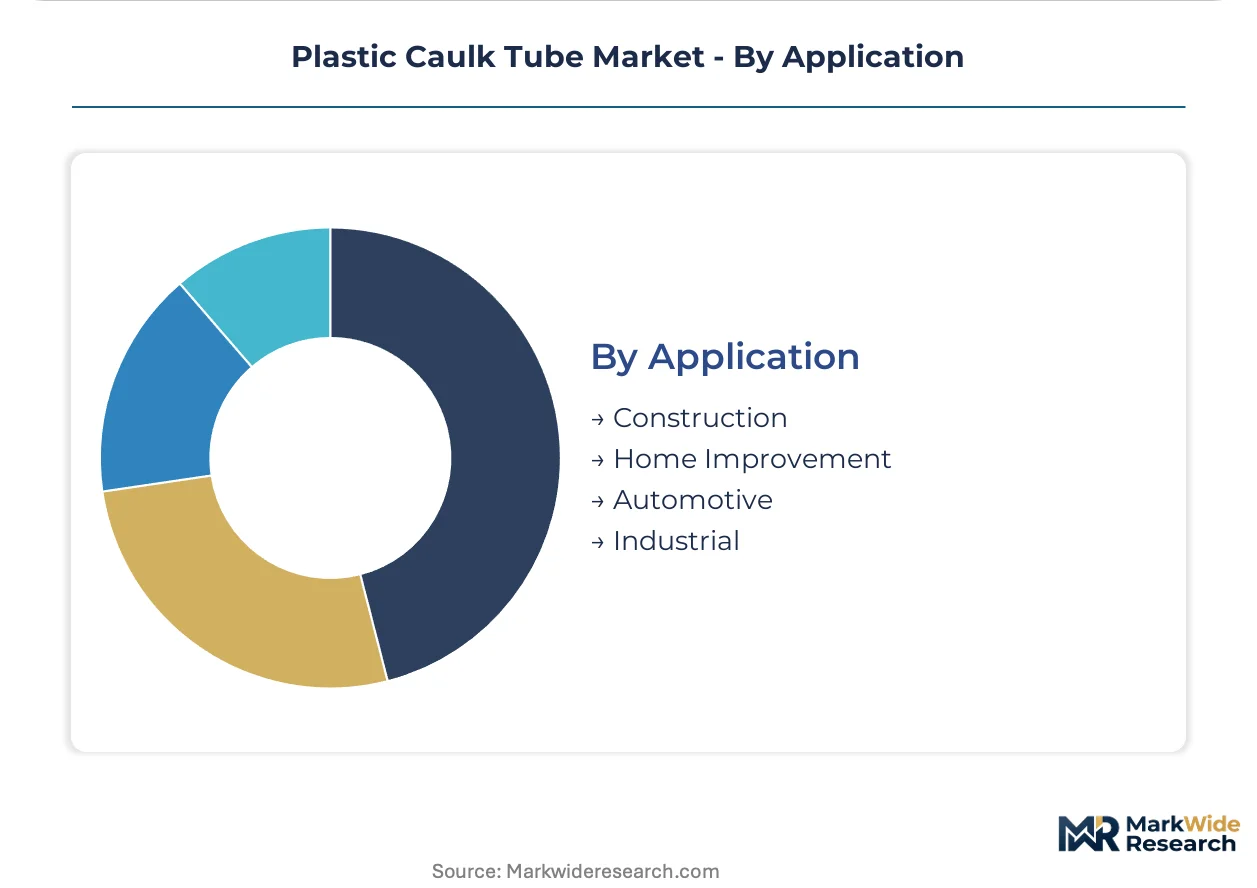
Application:
End-use thermal and barrier requirements dictate material specification and certification tier.
- Construction:Weatherproofing and energy-efficiency retrofits absorb standard polyethylene tube volumes. EPA VOC emission standards are compelling multi-layer barrier adoption for architectural sealant packaging.
- Home Improvement:DIY weatherization and repair projects drive squeeze tube and small-format demand through retail channels.
- Automotive:Underhood sealant and adhesive applications specify polypropylene for elevated temperature resistance. OEM qualification protocols extend product development cycles.
- Industrial:Hybrid polymer sealant compatibility requirements favor specialty tube designs with oxygen and moisture barrier properties.
Volume scale sits with Construction. Technical specification intensity is gaining share fastest in Automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the United Arab Emirates and special economic zones in China's coastal provinces concentrate plastic packaging manufacturing for Middle Eastern and Asian construction chemical supply chains.
United States
Housing stock averaging 40 years drives weatherization retrofit demand through Department of Energy Weatherization Assistance Program channels. EPA VOC emission standards under the Clean Air Act tighten architectural sealant packaging requirements. Texas Gulf Coast petrochemical clusters supply high-density polyethylene resin to tube extruders serving Home Depot and Lowe's national distribution networks.
Germany
Energy-efficient building renovation mandates under the Building Energy Act sustain construction chemical demand across residential retrofit channels. REACH restrictions on phthalate plasticizers force reformulation of polyethylene additive packages for export compliance. Baden-Württemberg automotive suppliers specify polypropylene tubes for underhood sealant applications requiring elevated temperature resistance.
China
Urban renewal programs in tier-two cities accelerate silicone sealant consumption for building envelope upgrades. GB standards for construction sealant packaging align with evolving volatile organic compound limits under Ministry of Ecology and Environment guidelines. Yangtze River Delta manufacturing zones host blown-film extrusion capacity serving domestic and Southeast Asian export markets.
India
Smart Cities Mission infrastructure spending expands commercial construction sealant procurement through municipal tendering systems. Bureau of Indian Standards certification requirements for construction chemicals create compliance barriers for imported tube formats. Gujarat petrochemical complexes feed downstream polyethylene processing for western India distribution networks.
Brazil
Minha Casa Minha Vida housing program restarts sustain residential construction chemical volumes through regional distributor channels. ANVISA pharmaceutical packaging regulations influence food-contact tube certification standards for commercial kitchen applications. São Paulo state industrial zones concentrate injection-molded packaging production for Mercosur regional supply.
Plastic Caulk Tube Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multi-layer barrier technology holders commanding premium positioning in renovation channels while commodity extruders compete on resin cost management. The vendor base organizes around three strategic archetypes: integrated packaging conglomerates with captive resin sourcing, regional extrusion specialists serving private-label programs, and precision injection molders targeting automotive qualification protocols. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers seek geographic coverage and technology access without full acquisition premiums.
Among North American packaging conglomerates, Berry Global Inc., Sonoco Products Company, and Silgan Holdings Inc. exemplify the scale-driven archetype. Berry Global Inc. occupies a position within multi-layer barrier technology development. Sonoco Products Company represents rigid packaging network concentration for big-box retail distribution. Silgan Holdings Inc. anchors the high-speed injection-molding capability segment for construction-grade adhesive volumes.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Sonoco Products Company |
| Silgan Holdings Inc. |
| Amcor plc |
| Huhtamaki Oyj |
| UFlex Limited |
| Albea Group |
| Ritter GmbH |
| Nordson Corporation |
| Others |
Value Network & Pricing Analysis
Barrier-to-commodity tube bifurcation separates multi-layer coextruded formats commanding shelf-life premiums from monolayer polyethylene constructions competing on resin cost. This tier divergence manifests in pricing through EPA VOC compliance certification ladders and in supply chain configurations through captive blown-film extrusion versus toll-manufactured spot supply.
Pricing Analysis
Short lead-time premiums accrue to manufacturers holding regional warehouse inventory for construction seasonality, while spot polyethylene resin purchases expose converters to margin compression. Three-tier pricing structure across premium barrier, standard monolayer, and economy refillable levels tracks certification intensity and volume scale. Pricing pressure stems from Home Depot and Lowe's consolidated procurement leverage over private-label suppliers. DIY enthusiasts through big-box retail channels exhibit highest price sensitivity; automotive OEM qualification programs demonstrate lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Regional distribution centers in Texas Gulf Coast petrochemical clusters feed blown-film extrusion capacity serving United States construction channels. Raw material dependencies center on high-density polyethylene resin, polypropylene pellets, and multi-layer adhesive tie-layers for barrier structures. Single-source vulnerability concentrates in Texas Gulf Coast resin supply following hurricane disruption patterns. Distribution runs through big-box retail direct-manufacturer relationships that have displaced regional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA VOC emission standards under the Clean Air Act erect barrier-to-entry moats favoring incumbents with validated multi-layer barrier manufacturing.
For Market Incumbents: Extend qualification protocols for hybrid polymer sealant compatibility to capture renovation channel specification lock-in. Deepen backward integration into polyethylene resin sourcing through Texas Gulf Coast petrochemical offtake agreements. Flexible aluminum-laminate substitutes threaten premium barrier tube positioning; defend through integrated nozzle technology differentiation. For New Entrants and Emerging Players: Dual-chamber tube technology offers a technology-first wedge into specialty construction chemical segments underserved by commodity extruders. Target FDA food-contact certification tiers for commercial kitchen applications where incumbent presence remains thin. Pursue direct relationships with regional construction distributors bypassed by big-box consolidation. For Investors and Strategic Acquirers: Re-rating potential sits with multi-layer barrier technology holders given EPA regulatory shelf-life requirement intensification. Long-term viability favors converters with captive blown-film extrusion technician training pipelines and California extended producer responsibility law compliance infrastructure. Watch California and New York packaging recovery mandate implementation timelines as inflection indicators for recyclable tube program economics.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Barrier Capacity Expansion | Captures EPA VOC compliance-driven specification upgrades in architectural sealant packaging. |
| Backward Integration into Resin Sourcing | Insulates margin from polyethylene feedstock volatility through Texas Gulf Coast petrochemical offtake. |
| FDA Food-Contact Certification Investment | Unlocks price premiums in commercial kitchen and food-processing facility applications. |
| Dual-Chamber Tube Technology Development | Enables hybrid polymer sealant compatibility for specialized construction chemical dispensing. |
| Extended Producer Responsibility Infrastructure | Positions for California and New York packaging recovery mandate first-mover advantages. |
Research Methodology
Document review covered customs and trade data, SEC 10-K filings from packaging conglomerates, and EPA regulatory dockets, complemented by interviews with blown-film extrusion plant managers, construction chemical procurement leads at Home Depot and Lowe's, distribution channel partners, and technical R&D directors at sealant formulators. Bottom-up volume estimates from resin consumption patterns and top-down market sizing from construction spending data were triangulated against primary interview intelligence.
Historical shipment patterns were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, material grade, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted construction spending forecasts and renovation cycle compression indicators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polyethylene resin price spike scenarios or accelerated extended producer responsibility law implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
United Kingdom Plastic Bottles Market