
 Poland Plastic Packaging Tubes Market | 2026-2036
Poland Plastic Packaging Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Plastic Packaging Tubes Market Insights
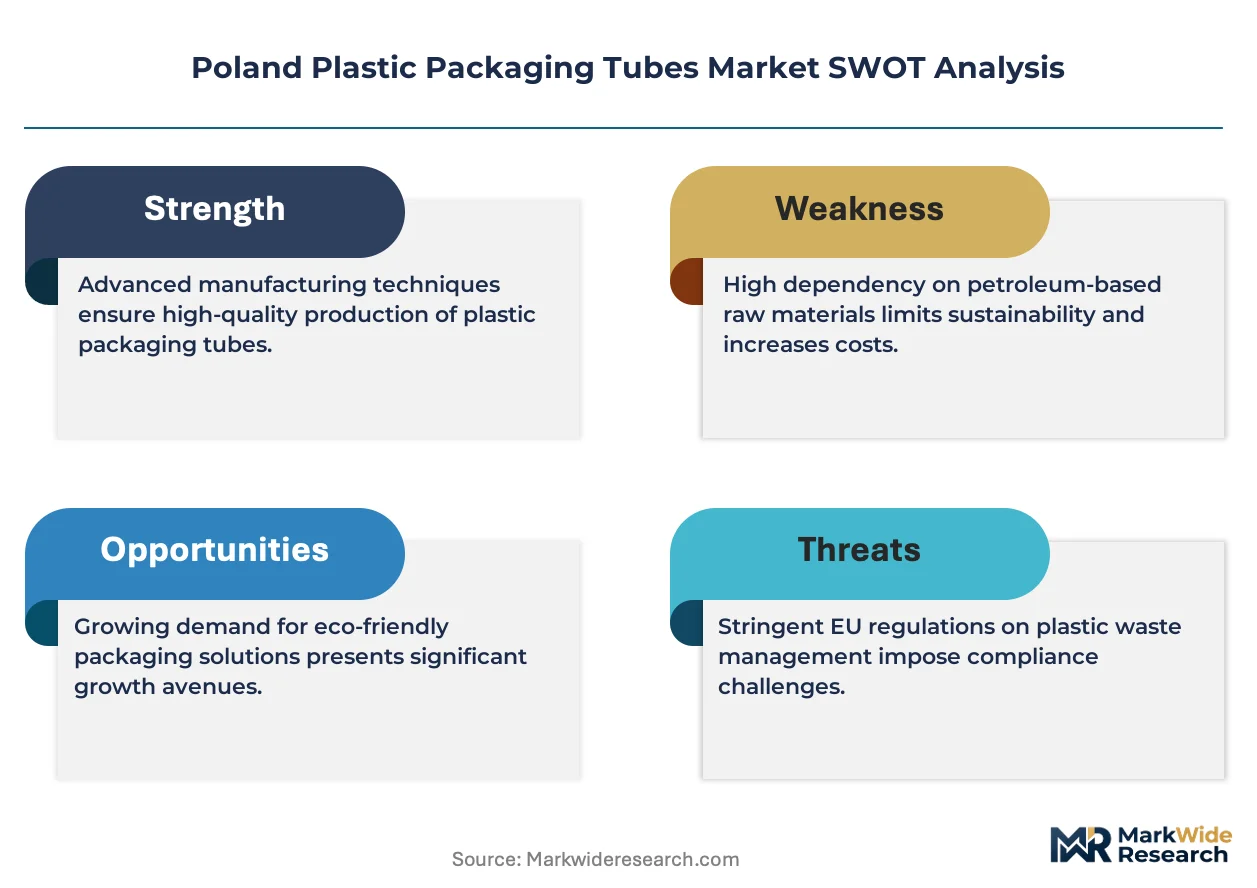
The EU Green Deal is recalibrating procurement priorities across Polish personal care supply chains. ALPLA Opakowania z Tworzyw Sztucznych Sp. z o.o. leverages integrated blow-molding and injection-stretch capabilities to serve multinational cosmetics brands from its Polish plants. MPACK POLAND Sp. z o.o. anchors flexible tube output for domestic pharmaceutical and household clients with specialized barrier-coating lines. Witoplast Kisielińscy Joint Stock Company dominates regional distribution through its long-standing relationships with Polish FMCG manufacturers and private-label retailers.
Poland plastic packaging tubes are cylindrical containers extruded or molded from thermoplastic resins, typically featuring diameters of 16–50 mm, wall thicknesses of 0.3–1.2 mm, and multi-layer coextrusion for oxygen or moisture barrier protection; they function as primary dispensing and protective packaging for semi-solid and viscous products across consumer and industrial sectors. Squeeze tubes lead volume in cosmetics end-use due to ergonomic dispensing and brand differentiation potential, while laminated tubes command premium positioning in pharmaceutical applications where product stability and shelf-life extension justify higher unit costs. Recyclable packaging types are gaining structural momentum as Polish converters re-engineer mono-material PE and PP constructions to meet EU circular economy targets without sacrificing barrier performance.
Poland's national regulator for packaging compliance aligns with EU REACH chemical safety requirements and the Packaging and Packaging Waste Directive, while BIS-equivalent Polish Committee for Standardization (PKN) norms govern material migration limits for food-contact tubes. The Polish Ministry of Climate and Environment enforces extended producer responsibility schemes that obligate tube manufacturers to finance collection and recycling infrastructure, directly influencing material selection and design-for-recycling investments. Stakeholders must monitor pending EU Packaging and Packaging Waste Regulation revisions that will mandate minimum recycled content thresholds and harmonize recyclability labeling across member states.
Market Dynamics
The EU Single-Use Plastics Directive is compressing material substitution timelines across Polish tube converters, forcing simultaneous re-engineering of barrier structures and recycling compatibility while Łódź-Warsaw manufacturing clusters absorb capacity reallocation from Western European suppliers.
Growth Catalysts
- EU Green Deal procurement mandates:Polish personal care brands now require recyclable mono-material PE tubes in supplier contracts, redirecting converter R&D budgets toward design-for-recycling protocols.
- Barrier coextrusion advances:Five-layer EVOH and polyamide constructions enable oxygen transmission rates below 0.5 cc/m²/day, opening pharmaceutical stability applications previously reserved for glass or aluminum.
- Łódź manufacturing corridor concentration:Proximity to Central European FMCG distribution hubs reduces finished tube freight costs by 15–20% versus Western European sourcing for Polish and Baltic brands.
Market Restraints
- Recycled polymer feedstock scarcity:Post-consumer PE and PP flake availability in Poland lags converter demand by 30–40%, forcing reliance on virgin resin or imported recyclate at premium pricing.
- Pharmaceutical barrier certification timelines:US FDA and EU EMA stability testing protocols require 24–36 month validation cycles for new tube constructions, locking converters into legacy material specifications.
- Aluminum laminate substitution in premium segments:Cosmetic brands seeking metallic aesthetic effects bypass plastic tubes entirely, ceding high-margin skincare positioning to European laminate specialists.
Strategic Opportunities
- Underpenetrated dermocosmetic pharmacy channel:Polish pharmacy chains are expanding private-label skincare ranges, creating demand for pharmaceutical-grade tubes with child-resistant closures and tamper-evident seals.
- Bio-based PE from sugarcane feedstock:Braskem's Brazilian bio-ethylene supply chain offers mass-balance certification pathways for converters seeking carbon footprint reduction without mechanical recycling infrastructure.
- Direct-to-brand converter relationships:Bypassing traditional packaging distributors, Łódź-area extruders are establishing captive design studios inside Warsaw cosmetic brand headquarters to compress development cycles.
Industry Challenges
- Multi-layer separation for mechanical recycling:Existing Polish recycling infrastructure cannot economically delaminate EVOH barrier layers from PE substrates, forcing converters to choose between performance and circularity.
- Digital printing integration with high-speed lines:HD flexography and direct-to-object inkjet retrofitting requires €2–4 million per production line, straining mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Plastic Packaging Tubes Market |
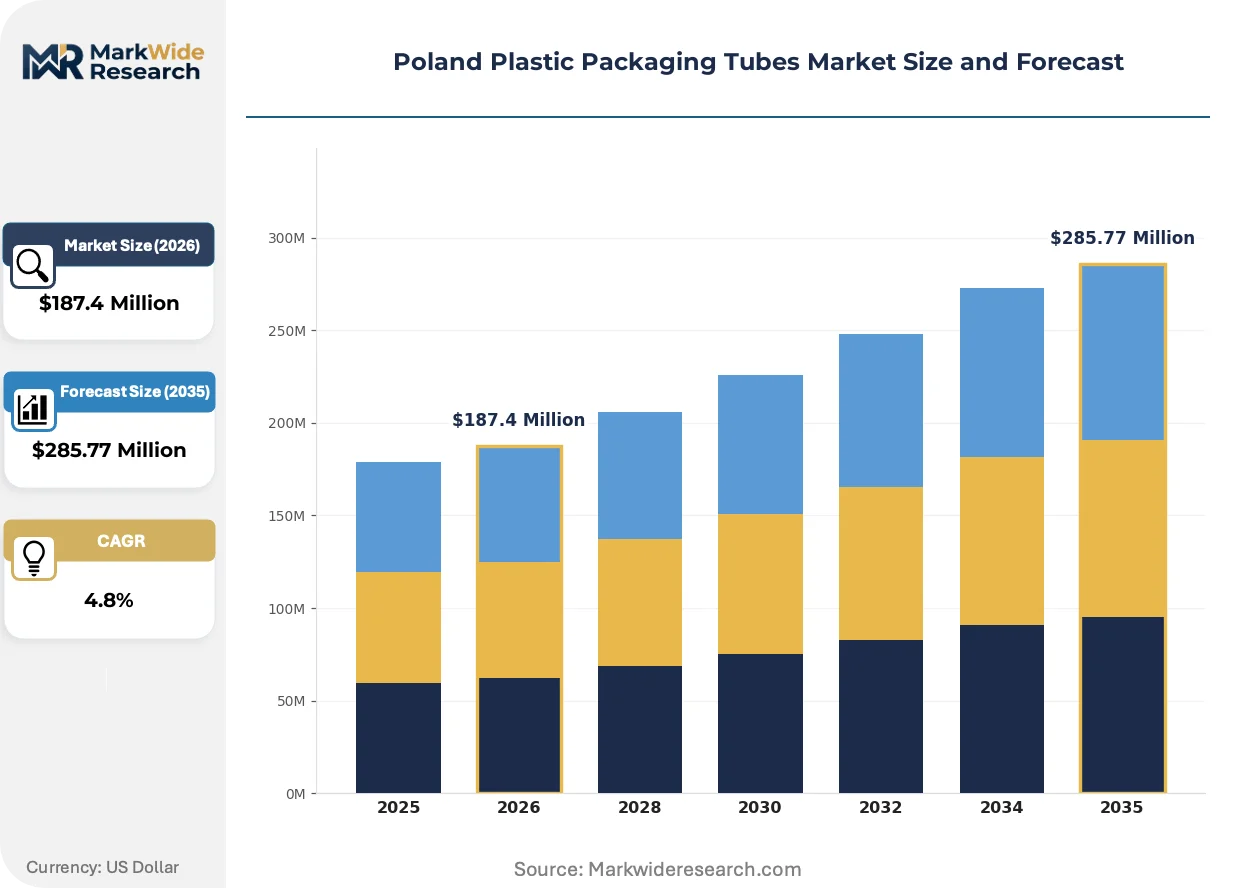
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Tubes, Squeeze Tubes, Twist-Up Tubes, Laminated Tubes Material: PE, PVC, PET, PP End Use: Cosmetics, Pharmaceuticals, Food, Household Products Packaging Type: Flexible Packaging, Rigid Packaging, Recyclable Packaging, Multi-layer Packaging |
| Companies Covered | ALPLA Opakowania z Tworzyw Sztucznych Sp. z o.o., MPACK POLAND Sp. z o.o., Witoplast Kisielińscy Joint Stock Company, Albéa Services S.A.S., GP Plast sp. z o.o., Berry Global Inc., Gerresheimer AG, PACCOR POLSKA Sp. z o.o., PLASTAN KACPRZYK SP. Z O.O. SP. K., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Plastic Packaging Tubes Market Trends and Innovations
Digital manufacturing workflows and material science convergence are collapsing traditional development cycles in Polish tube production, enabling mass customization without sacrificing the scale economies that sustain Łódź-Warsaw corridor competitiveness.
Digital sleeve printing with electron-beam curing is decentralizing short-run cosmetic tube production away from centralized gravure houses. Mid-size Polish skincare brands now order 10,000-unit batches with 48-hour turnaround, compressing inventory carrying costs and enabling seasonal limited editions. This capability is fragmenting volume concentration among Łódź converters previously dependent on 500,000-unit minimums.
REACH Article 33 substance disclosure requirements are forcing complete supply chain transparency for SVHC content above 0.1% w/w. Polish tube manufacturers now demand full material composition data from masterbatch and adhesive suppliers, documenting every additive through to finished goods. Pharmaceutical and infant care segments are responding fastest, implementing blockchain-traceable batch records to preempt regulatory enforcement.
Brand procurement teams are consolidating tube specifications across product lines to reduce SKU complexity and improve recycling stream purity. Warsaw-headquartered personal care multinationals are eliminating diameter variations below 5mm increments, standardizing on 25mm, 30mm, and 40mm formats with interchangeable closure platforms. This consolidation is most visible in mass-market haircare, where private-label penetration exceeds 35% and price competition rewards manufacturing efficiency over differentiation.
Poland Plastic Packaging Tubes Market Segmentation
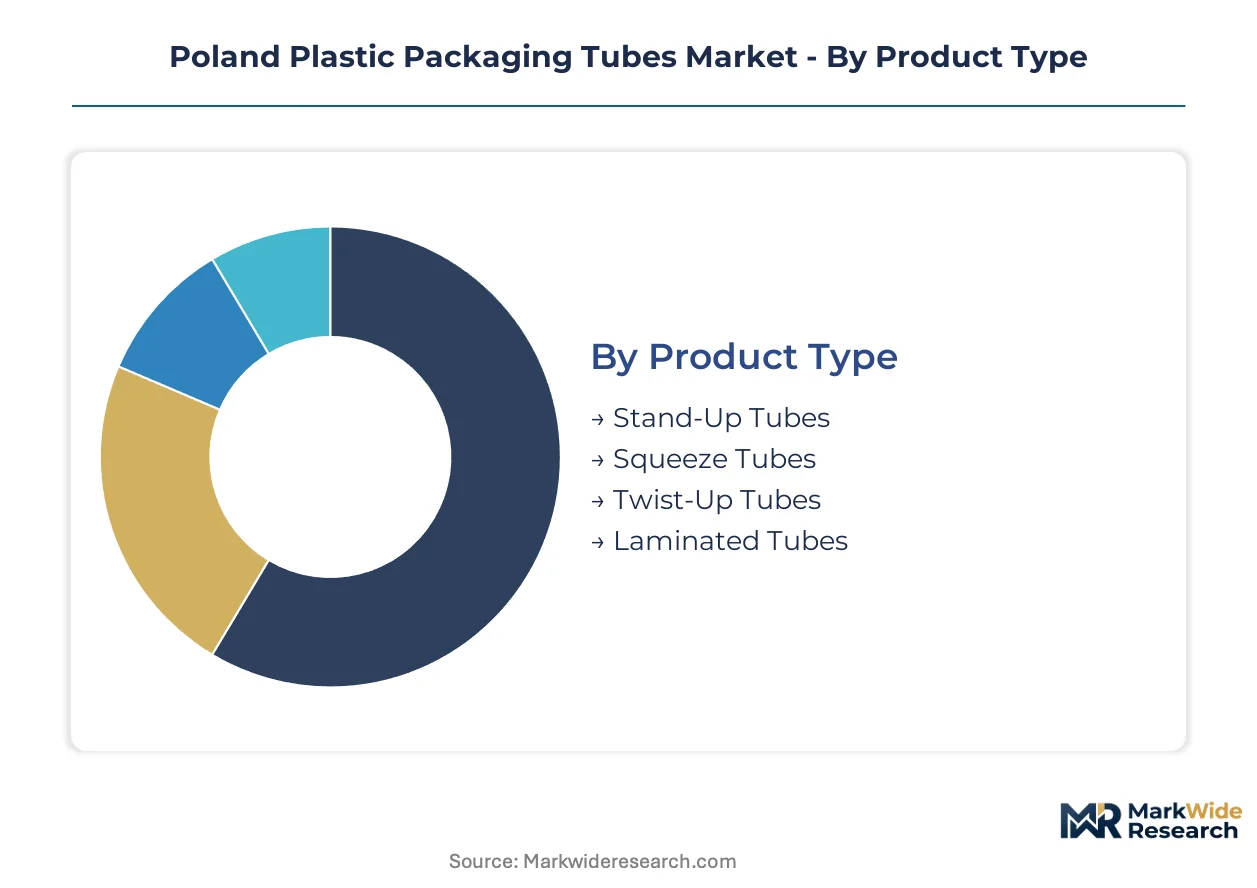
Tube format selection in Poland tracks closely with product viscosity, dispensing ergonomics, and shelf-impact requirements across personal care and pharmaceutical channels. Material and construction choices increasingly pivot on recycling compatibility mandates from the EU Packaging and Packaging Waste Directive.
Product Type:
Upgrade cycles in Polish cosmetics manufacturing are compressing as brands shift from stock formats to customized tube geometries that differentiate at point-of-sale.
- Squeeze Tubes:Mono-layer or coextruded PE constructions with flip-top or screw closures dominate mass-market skincare and haircare. Łódź converters supply squeeze tubes to Polish private-label cosmetics manufacturers seeking ergonomic dispensing with 15–20% freight cost advantages over Western European sourcing.
- Laminated Tubes:Five-layer aluminum-plastic laminates with EVOH barriers deliver oxygen transmission below 0.5 cc/m²/day for pharmaceutical stability applications. Demand concentrates in Warsaw-area dermocosmetic pharmacy chains expanding private-label skincare ranges.
- Stand-Up Tubes:Oval or rectangular profiles with stable bases enable vertical merchandising in retail environments. Polish household product brands utilize stand-up formats for viscous cleaning pastes.
- Twist-Up Tubes:Propellant-free solid formulations in stick format serve deodorant and lip care applications with precision dosing mechanisms.
Squeeze tubes sit at the top of the volume ranking, with laminated tubes climbing the fastest.
Material:
Cost tier differentiation across resin grades shapes converter procurement strategies as virgin PE premiums widen against recycled flake scarcity.
- PE:Low-density and linear low-density polyethylene dominate Polish tube extrusion for flexibility, sealability, and compatibility with existing recycling streams. LDPE squeeze tubes serve mass-market cosmetics from Łódź manufacturing corridors.
- PP:Higher stiffness and temperature resistance position polypropylene for pharmaceutical tubes requiring autoclave sterilization. Warsaw-headquartered personal care multinationals specify PP for premium skincare lines.
- PET:Clarity and barrier properties suit food-contact applications including condiment and sauce tubes. Polish food processors specify PET for visibility-driven retail categories.
- PVC:Declining share due to REACH SVHC scrutiny and mechanical recycling incompatibility. Remaining demand concentrates in legacy pharmaceutical specifications.
PE commands the volume base, with PP gaining share fastest in premium repositioning.
End Use:
Application-driven specifications fragment tube requirements across stability, aesthetic, and regulatory compliance dimensions.
- Cosmetics:Digital printing-enabled short runs of 10,000 units support seasonal limited editions. Polish mid-size skincare brands compress inventory carrying costs through Łódź converter partnerships.
- Pharmaceuticals:US FDA and EU EMA stability testing protocols demand 24–36 month validation cycles. Child-resistant closures and tamper-evident seals differentiate pharmacy-channel specifications.
- Household Products:Chemical resistance and squeeze resilience prioritize functional performance over barrier sophistication. Polish private-label cleaning brands drive volume.
- Food:Migration limits under EU food-contact regulations govern material selection. Condiment and sauce applications specify oxygen barriers for shelf-life extension.
Cosmetics anchors volume leadership, with pharmaceuticals expanding most quickly on dermocosmetic pharmacy channel growth.
Packaging Type:
Margin structures diverge sharply between commodity flexible formats and certified recyclable constructions commanding sustainability premiums.
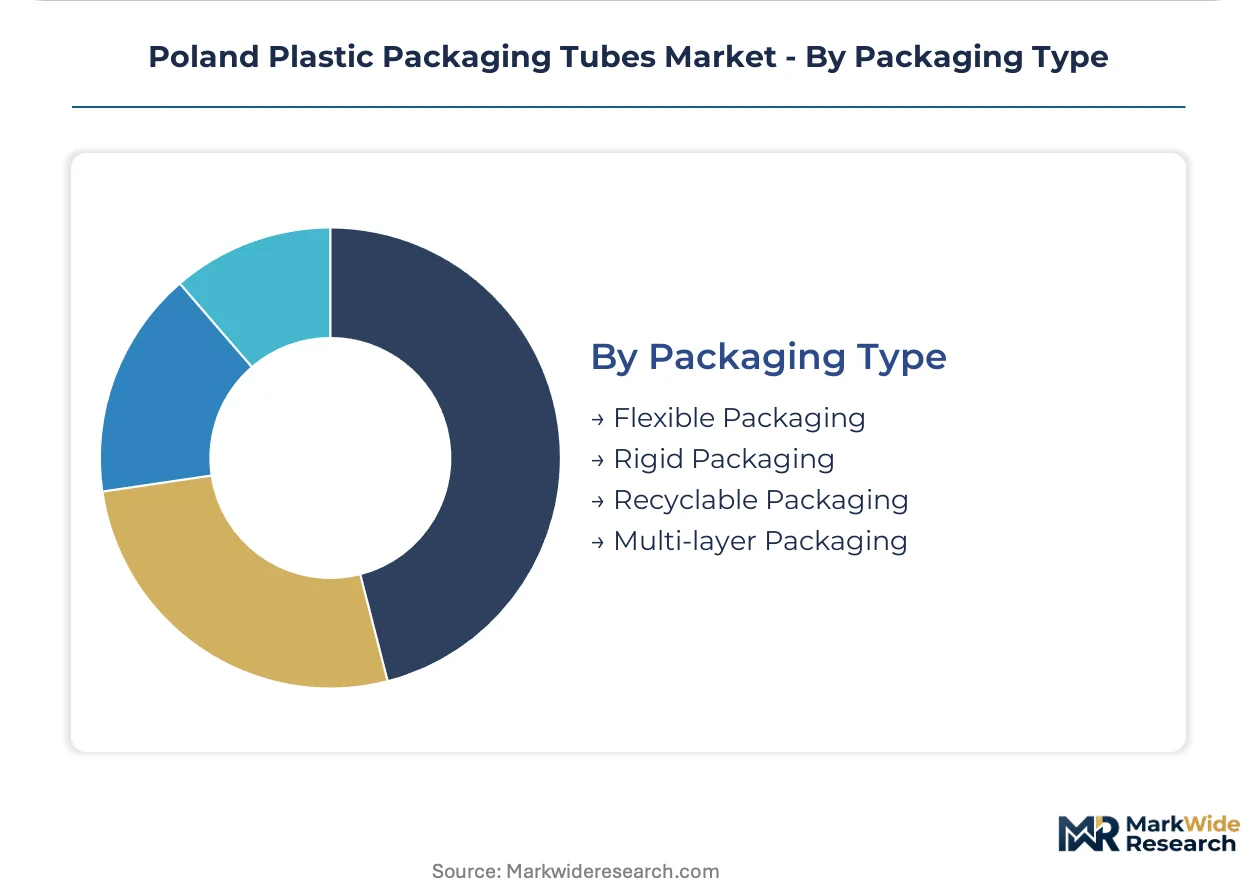
- Flexible Packaging:Collapsible PE and laminate tubes reduce residual product waste. Squeeze formats dominate Polish FMCG distribution through Łódź-Warsaw logistics corridors.
- Recyclable Packaging:Mono-material PE and PP constructions align with EU circular economy targets. Polish converters re-engineer barrier layers to maintain performance without EVOH delamination challenges.
- Multi-layer Packaging:Coextruded barriers with EVOH or polyamide cores protect oxygen-sensitive pharmaceuticals. Existing Polish recycling infrastructure cannot economically separate these layers.
- Rigid Packaging:Injection-molded PP tubes with integrated closures serve high-viscosity industrial applications. Limited penetration in Polish consumer markets.
Flexible packaging holds volume dominance, with recyclable packaging climbing fastest on EU Green Deal procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's plastic packaging tube industry traces its modern scale to post-2004 EU accession investments, when Western European converters established production corridors to exploit lower labor costs and central logistics positioning. The Łódź-Warsaw manufacturing belt now anchors national capacity, with regional specialization patterns reflecting end-use demand density and freight optimization.
Łódź Voivodeship
Central Poland's largest manufacturing cluster concentrates extrusion and printing capacity for mass-market cosmetics tubes. The Łódź Special Economic Zone offers 10-year corporate income tax exemptions that attracted German and Austrian packaging groups during 2010–2018 expansion waves. Local converters now supply squeeze tube formats to Baltic state distributors with 15–20% freight cost advantages over Western European sourcing.
Masovian Voivodeship
Warsaw-headquartered personal care multinationals drive demand for premium tube specifications with digital printing and mono-material recyclability. The Polish Ministry of Climate and Environment enforces extended producer responsibility schemes that obligate tube manufacturers to finance collection infrastructure. Warsaw-area design studios embedded in brand headquarters compress development cycles for seasonal limited editions.
Lesser Poland Voivodeship
Kraków's pharmaceutical manufacturing heritage supports demand for barrier-coated tubes with child-resistant closures and tamper-evident seals. Polish Committee for Standardization (PKN) norms govern material migration limits for pharmacy-channel specifications. Regional converters serve expanding dermocosmetic private-label ranges in pharmacy chains across southern Poland and Slovak border regions.
Silesian Voivodeship
Katowice-area industrial heritage has repurposed toward household product tube manufacturing, leveraging chemical resistance expertise from legacy mining supply chains. The EU Packaging and Packaging Waste Directive drives local investment in mono-material PE constructions compatible with existing mechanical recycling infrastructure. Converters here prioritize functional performance over aesthetic differentiation for cleaning paste applications.
Pomeranian Voivodeship
Gdańsk port access enables imported bio-based PE feedstock from Braskem's Brazilian supply chain, supporting carbon footprint reduction claims for export-oriented cosmetics brands. Baltic Sea logistics corridors connect Polish tube converters to Nordic markets with shorter lead times than Rhine-Alpine routes. Regional players specialize in mass-balance certified sustainable packaging for EU Green Deal procurement mandates.
Poland Plastic Packaging Tubes Market Competitive Landscape
Capital-heavy integrated converters compete with specialized tube finishers who outsource extrusion to third-party suppliers. The Polish market exhibits tiered concentration, with multinational packaging groups operating alongside mid-cap domestic specialists and private-label focused regional players. Three archetypes dominate: integrated resin-to-tube manufacturers with captive blow-molding lines, barrier-coating specialists serving pharmaceutical stability requirements, and digital-printing-enabled short-run converters for cosmetic limited editions. Competitive dynamics center on backward integration into resin compounding and strategic partnerships with Warsaw-based brand procurement teams.
Among Poland-based integrated manufacturers, ALPLA Opakowania z Tworzyw Sztucznych Sp. z o.o. represents the multinational scale archetype with diversified thermoplastics capabilities. MPACK POLAND Sp. z o.o. and Witoplast Kisielińscy Joint Stock Company exemplify domestic specialist positioning, with the former occupying flexible tube production for pharmaceutical and household segments and the latter anchoring regional distribution through long-standing FMCG relationships. These three entities collectively illustrate the market's structural segmentation between global scale, technical specialization, and commercial proximity to Polish private-label retailers.
| Leading Market Players |
|---|
| ALPLA Opakowania z Tworzyw Sztucznych Sp. z o.o. |
| MPACK POLAND Sp. z o.o. |
| Witoplast Kisielińscy Joint Stock Company |
| Albéa Services S.A.S. |
| GP Plast sp. z o.o. |
| Berry Global Inc. |
| Gerresheimer AG |
| PACCOR POLSKA Sp. z o.o. |
| PLASTAN KACPRZYK SP. Z O.O. SP. K. |
| Others |
Pricing and Supply Chain Analysis
Skilled extrusion technicians concentrated in the Łódź Voivodeship anchor Poland's cost-competitive tube manufacturing base, with labor-cost differentials of 40–50% versus Western European converters enabling three-tier pricing spreads that separate mass-market private-label supply from premium pharmaceutical-grade specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Polish tube procurement, with pharmaceutical-grade barrier tubes commanding 3–4x premiums over commodity squeeze formats due to EVOH coextrusion certification and 24–36 month FDA/EMA validation cycles. Price differentiation hinges on barrier performance tier and volume scale, with 500,000-unit minimums unlocking standard-tier economics while sub-50,000 digital-print runs sustain premium positioning. Cost compression in mass-market cosmetics is intensifying because Baltic and Polish private-label brands consolidate specifications around 25mm, 30mm, and 40mm diameter standards. Private-label retailers exhibit highest price sensitivity, whereas Warsaw-headquartered dermocosmetic multinationals prioritize stability certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Łódź and Warsaw operate hub-and-spoke patterns feeding Central European FMCG networks, with finished tube freight costs running 15–20% below Western European sourcing for Baltic state destinations. Geographic supply concentrates in Germany, Austria, and domestic Polish extrusion capacity established during post-2004 EU accession investment waves. Raw material dependencies rest on virgin PE and PP resin from Central European petrochemical complexes, EVOH barrier films from Asian and European specialty polymer suppliers, and mass-balance certified bio-PE imported through Gdańsk port facilities. Single-source vulnerability in pharmaceutical-grade EVOH supply creates structural risk. Distribution runs through converter-direct relationships with Warsaw brand headquarters, bypassing traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's plastic packaging tube market offers margin-expansion potential as EU Green Deal procurement mandates shift brand budgets toward certified recyclable mono-material constructions, compressing development cycles and rewarding converters with validated design-for-recycling protocols.
For Market Incumbents: Deepen backward integration into resin compounding and captive barrier-coating lines to defend against emerging digital-printing-enabled short-run specialists fragmenting volume concentration. ALPLA-scale integrated manufacturers should lock in long-term bio-PE offtake agreements through Braskem's mass-balance certification pathways before feedstock scarcity widens. Priority lever: establish embedded design studios inside Warsaw cosmetic brand headquarters to compress 48-hour turnaround capabilities into structural relationships.
For New Entrants and Emerging Players: The 35–40% price-point spread between premium pharmaceutical tubes and economy household formats creates white-space opportunity for mid-tier dermocosmetic specifications with pharmacy-channel child-resistant closures. Target the underpenetrated Polish pharmacy private-label segment, where expanding skincare ranges demand pharmaceutical-grade stability without multinational brand premiums. Go-to-market angle: partner with Kraków-area converters on barrier validation shortcuts leveraging existing PKN certification infrastructure.
For Investors and Strategic Acquirers: Personal care multinationals with Warsaw procurement headquarters are the most active acquirer in this space, seeking captive tube supply to secure EU Packaging and Packaging Waste Regulation compliance ahead of recycled content mandates. Long-term viability centers on converters with validated mono-material PE constructions and established brand-direct relationships. Signal to watch: Polish Ministry of Climate and Environment enforcement actions on extended producer responsibility financing obligations, which will accelerate consolidation among non-compliant mid-cap extruders.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-for-Recycling Protocol Investment | Validates mono-material PE constructions for EU circular economy procurement mandates from Warsaw-headquartered brands. |
| Embedded Design Studio Partnership | Compresses development cycles to 48-hour turnaround for seasonal limited editions, locking in mid-size skincare brand relationships. |
| Bio-Based PE Supply Agreement | Secures mass-balance certified feedstock through Gdańsk port access for carbon footprint reduction claims. |
| Pharmaceutical Barrier Certification | Opens 24–36 month FDA/EMA validation pathways for dermocosmetic pharmacy channel expansion. |
| Digital Printing Line Retrofit | Enables 10,000-unit short runs fragmenting volume concentration away from centralized gravure houses. |
Research Methodology
Bottom-up cosmetics and pharmaceutical end-use modeling reconciled against top-down extrusion capacity and resin import tracking forms the analytical core of this study. Primary interviews with tube converter plant managers, Warsaw-based brand procurement leads, Łódź Special Economic Zone investment officers, and Polish Committee for Standardization technical committee members combined with secondary validation from EU Packaging and Packaging Waste Directive implementation reports, Polish Ministry of Climate and Environment EPR scheme filings, and Central European petrochemical trade data. Triangulation across bottom-up SKU-level demand aggregation and top-down production facility utilization estimates ensures cross-verified outputs.
Input-output matrices mapping resin feedstock flows through extrusion, printing, and finishing stages to end-use segment demand drive the forecast framework. Segmentation dimensions modeled include tube format type, material construction, end-use application, and packaging recyclability tier across the projection horizon. CAGRs derive from elasticity-adjusted demand projections incorporating EU regulatory compliance cost pass-through assumptions and brand procurement consolidation patterns around standardized diameter formats. Industry-specific forecast inputs include EVOH barrier film supply constraints and digital printing adoption curves among Łódź corridor converters.
Caveats apply where EU Packaging and Packaging Waste Regulation revisions, recycled polymer feedstock availability shocks, or pharmaceutical stability certification timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and brand sustainability procurement commitment durability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market
Plastic Packaging
Russia Plastic Packaging Market