
 Plastic Liners Market | 2026-2036
Plastic Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Liners Market Analytics
India is reshaping competitive dynamics through capacity additions in flexible packaging and geomembrane extrusion. Berry Global leverages vertical integration across resin compounding and film conversion to sustain cost leadership in North American landfill applications. Novolex anchors its position through channel control with municipal waste management contracts. Mondi Group specializes in recycled-content barrier films, differentiating its offering for EU circular-economy procurement.
Plastic liners are impermeable synthetic membranes manufactured from polyethylene, polypropylene, PVC, or EPDM through calendering, extrusion, or blown-film processes, designed to prevent fluid migration in containment applications. Geomembranes dominate value capture due to thickness requirements and installation complexity in hazardous waste containment. Polyethylene leads material selection for chemical resistance and weldability, though EPDM gains traction in exposed pond applications for UV stability. Waste Management anchors end-user demand through landfill capping and leachate collection mandates, while Aquaculture represents the fastest-growing segment as intensive shrimp farming expands in Southeast Asia.
EPA Subtitle D regulations mandate composite liner systems for municipal solid waste landfills, directly specifying minimum thickness and permeability coefficients that shape product development. REACH restrictions on phthalate plasticizers in PVC formulations are redirecting European specification toward polyethylene alternatives. India's BIS certification requirements for geomembranes in water infrastructure projects are creating compliance barriers for uncertified imports. Stakeholders must monitor evolving extended producer responsibility frameworks and their impact on recycled-content mandates across multiple jurisdictions.
Market Dynamics
EPA Subtitle D landfill liner mandates and China's dual carbon targets are compressing material specifications while India's Jal Jeevan Mission accelerates geomembrane deployment for water conservation infrastructure.
Growth Catalysts
- Agricultural irrigation infrastructure:Polyethylene geomembranes are capturing reservoir lining contracts across India's Jal Jeevan Mission watershed projects. State water boards specify 1.5mm minimum thickness for canal seepage control.
- REACH phthalate restrictions:ECHA's plasticizer limitations in PVC formulations are redirecting European procurement toward polyethylene alternatives. Municipal waste authorities in Germany and France now specify HDPE for leachate collection systems.
- Intensive aquaculture expansion:Shrimp farming operations across Vietnam and Indonesia are adopting EPDM pond liners for UV stability in exposed installations. Hatchery operators prioritize weld seam reliability over initial material cost.
Market Restraints
- Resin price volatility:Ethylene feedstock costs fluctuate with naphtha cracking margins in the US Gulf Coast, compressing extrusion margins for geomembrane producers during Q2-Q3 procurement cycles.
- EPDM supply concentration:Synthetic rubber liner production clusters in Northeast Asia, creating single-source dependency for exposed pond applications requiring UV resistance specifications.
- Weld certification complexity:BIS geomembrane certification for Indian water infrastructure projects requires third-party seam testing, extending project timelines by 8-12 weeks for uncertified imports.
Strategic Opportunities
- Recycled-content barrier films:EU circular-economy procurement mandates are creating specification windows for post-consumer polyethylene in non-hazardous containment. Mondi Group has positioned its recycling stream for this segment.
- Carbon credit monetization:China's dual carbon goals enable landfill gas capture projects using composite liner systems. Provincial environmental bureaus offer tariff offsets for methane recovery installations.
- Modular installation services:Equipment leasing models for thermal wedge welding are emerging in Brazil's mining sector. Rental channels reduce capital barriers for mid-scale tailings pond operators.
Industry Challenges
- Certified welder scarcity:Geomembrane seam integrity depends on technician qualification under GSI standards. Training pipeline gaps in Southeast Asia delay project commissioning for aquaculture pond installations.
- Legacy PVC remediation liability:Landfill operators face replacement costs for aging PVC liners where phthalate degradation compromises impermeability. Asset owners struggle to scope contingent liabilities in financial disclosures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Liners Market |
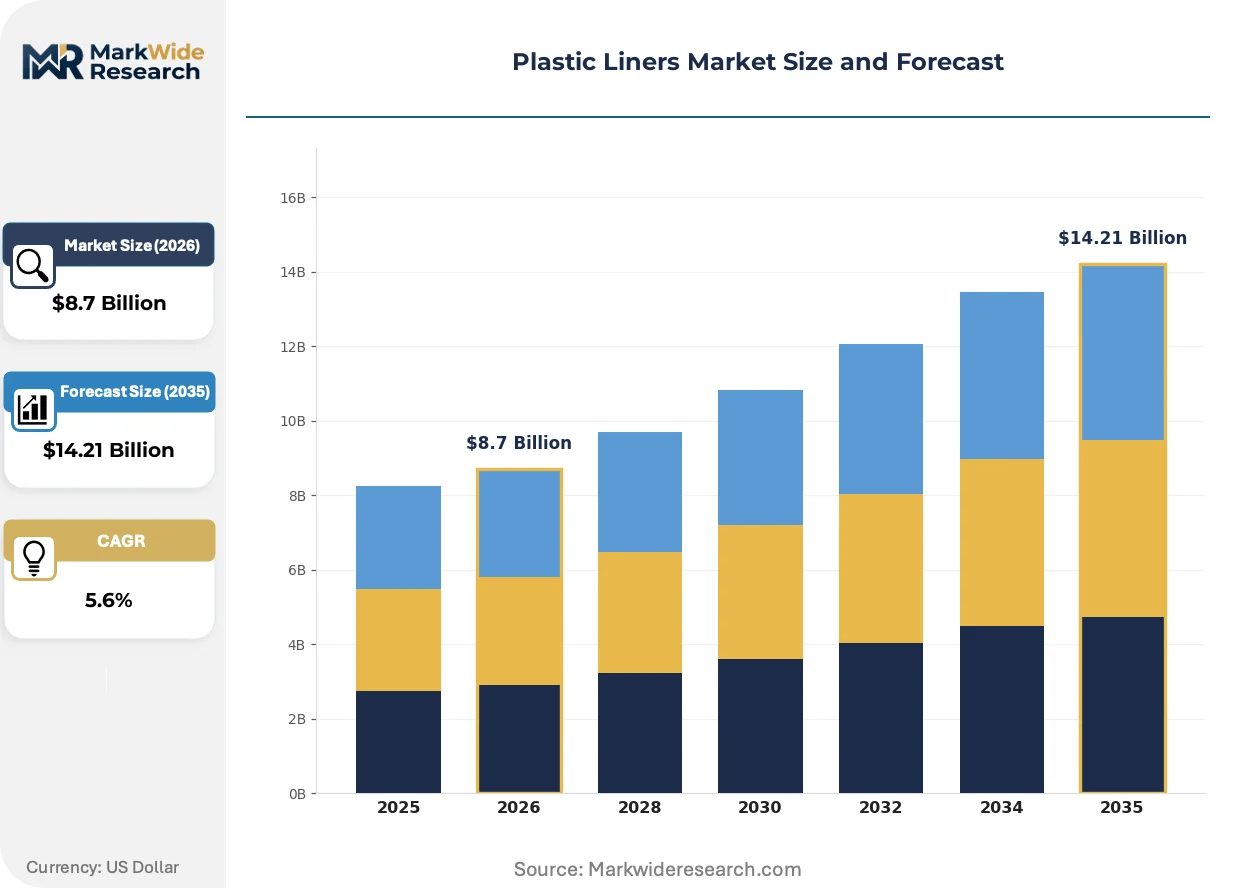
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geomembranes, Pond Liners, Vapor Barriers, Tank Liners End User: Agriculture, Construction, Waste Management, Aquaculture Material: Polyethylene, Polypropylene, PVC, EPDM Application: Landfill, Water Storage, Containment, Decorative |
| Companies Covered | Berry Global, Novolex, Mondi Group, Sealed Air Corporation, RKW Group, Amcor plc, UFlex, Winpak Ltd., Greif, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Liners Market Evolving Landscape
Material science convergence and regulatory tightening are reconfiguring competitive advantage around certification depth, recycled-content verification, and installation service bundling rather than commodity resin supply alone.
Multilayer coextrusion technology is hybridizing barrier performance with mechanical durability in single-pass manufacturing. Mining tailings operators in Chile and Peru are specifying 2.0mm textured HDPE with conductive layers for leak detection integration. This convergence is compressing the premium segment for standalone geomembrane installations by embedding sensing capabilities directly into membrane structure.
REACH authorization timelines for phthalate plasticizers are accelerating PVC displacement in European landfill applications. Germany's Federal Environment Agency now recommends polyethylene for all new leachate collection systems. French and Italian municipal waste authorities are revising tender specifications to exclude PVC alternatives, redirecting procurement volumes toward HDPE and LLDPE suppliers with established recycling partnerships.
Certification-driven specification is consolidating buyer decision criteria around third-party weld testing and installation warranty terms. Indian state water boards under Jal Jeevan Mission now require BIS-certified contractors for geomembrane deployment, displacing informal installation networks. Procurement officers in Maharashtra and Gujarat prioritize documented seam integrity over unit material pricing, compressing competitive differentiation toward service capability rather than resin cost alone.
Plastic Liners Market Segmentation
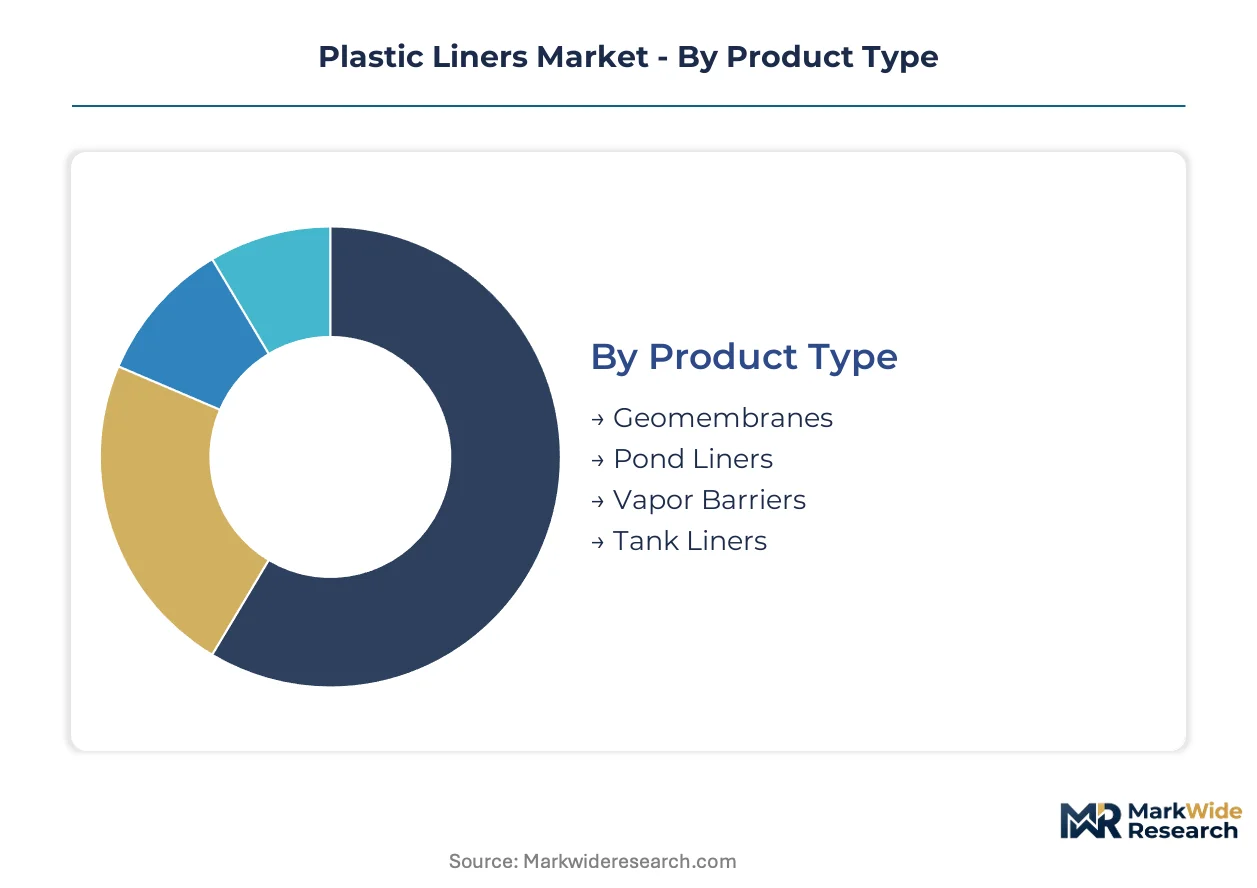
Plastic liner specifications diverge sharply across containment applications, with thickness, weldability, and chemical resistance requirements dictating material selection. Segmentation reveals how geomembrane producers balance commodity resin supply against project-specific certification demands.
Product Type:
After-sales service intensity concentrates in geomembrane and pond liner deployments, where installation warranties and seam integrity guarantees extend revenue capture beyond material supply.
- Geomembranes:Impermeable synthetic membranes manufactured through calendering or extrusion, typically 0.5mm to 2.5mm thickness. Mining tailings operators in Chile specify textured HDPE with conductive layers for leak detection integration, while India's state water boards mandate 1.5mm minimum thickness for canal seepage control under Jal Jeevan Mission watershed projects.
- Pond Liners:Flexible membranes designed for exposed aquatic installations, prioritizing UV stability and weld seam reliability. Intensive shrimp farming operations across Vietnam and Indonesia adopt EPDM formulations despite higher initial cost, as hatchery operators prioritize seam longevity over material pricing.
- Vapor Barriers:Thin-film membranes blocking moisture migration in building envelopes, commonly specified in below-grade construction.
- Tank Liners:Custom-fitted containment solutions for chemical and water storage vessels, requiring precise dimensional fabrication.
Geomembranes hold the largest share; momentum sits with pond liners.
End User:
Cost tier stratification separates municipal waste authorities with long-term contract security from price-sensitive agricultural operators.
- Waste Management:Landfill capping and leachate collection systems governed by EPA Subtitle D mandates in the United States. Germany's Federal Environment Agency now recommends polyethylene for all new leachate collection systems, redirecting procurement volumes toward HDPE suppliers.
- Aquaculture:The fastest-expanding demand segment as intensive shrimp farming proliferates across Southeast Asia. Vietnamese and Indonesian hatchery operators specify EPDM pond liners for UV stability in exposed installations, with weld certification complexity creating barriers for uncertified imports.
- Agriculture:Reservoir lining and irrigation canal applications, concentrated in India's Jal Jeevan Mission water conservation infrastructure.
- Construction:Vapor barrier and foundation waterproofing specifications in commercial and residential building envelopes.
Waste Management anchors volume demand; Aquaculture climbs the fastest.
Material:
Application requirements and regulatory constraints are redirecting specification away from legacy formulations toward weldable alternatives.
- Polyethylene:Dominant selection for chemical resistance, thermal weldability, and recycling compatibility. HDPE and LLDPE formulations capture European municipal waste procurement as REACH phthalate restrictions displace PVC alternatives in Germany and France.
- EPDM:Synthetic rubber membranes prized for UV stability and flexibility in exposed pond applications. Production concentration in Northeast Asia creates single-source dependency for aquaculture operators requiring UV resistance specifications.
- Polypropylene:Specialized applications demanding higher temperature resistance and chemical inertness.
- PVC:Legacy formulations facing displacement as phthalate plasticizer restrictions tighten across European jurisdictions.
Polyethylene commands the greatest share; EPDM gains share fastest.
Application:
Volume concentration in landfill and water storage installations contrasts with emerging decorative and secondary containment niches.
- Landfill:Composite liner systems mandated by EPA Subtitle D regulations specifying minimum thickness and permeability coefficients. China's dual carbon goals enable landfill gas capture projects using composite liner systems, with provincial environmental bureaus offering tariff offsets for methane recovery installations.
- Water Storage:Reservoir and canal lining contracts across India's Jal Jeevan Mission, where BIS certification requirements create compliance barriers for uncertified geomembrane imports.
- Containment:Hazardous material and industrial process containment in mining and chemical processing facilities.
- Decorative:Landscape and architectural water feature applications with lower technical specification requirements.
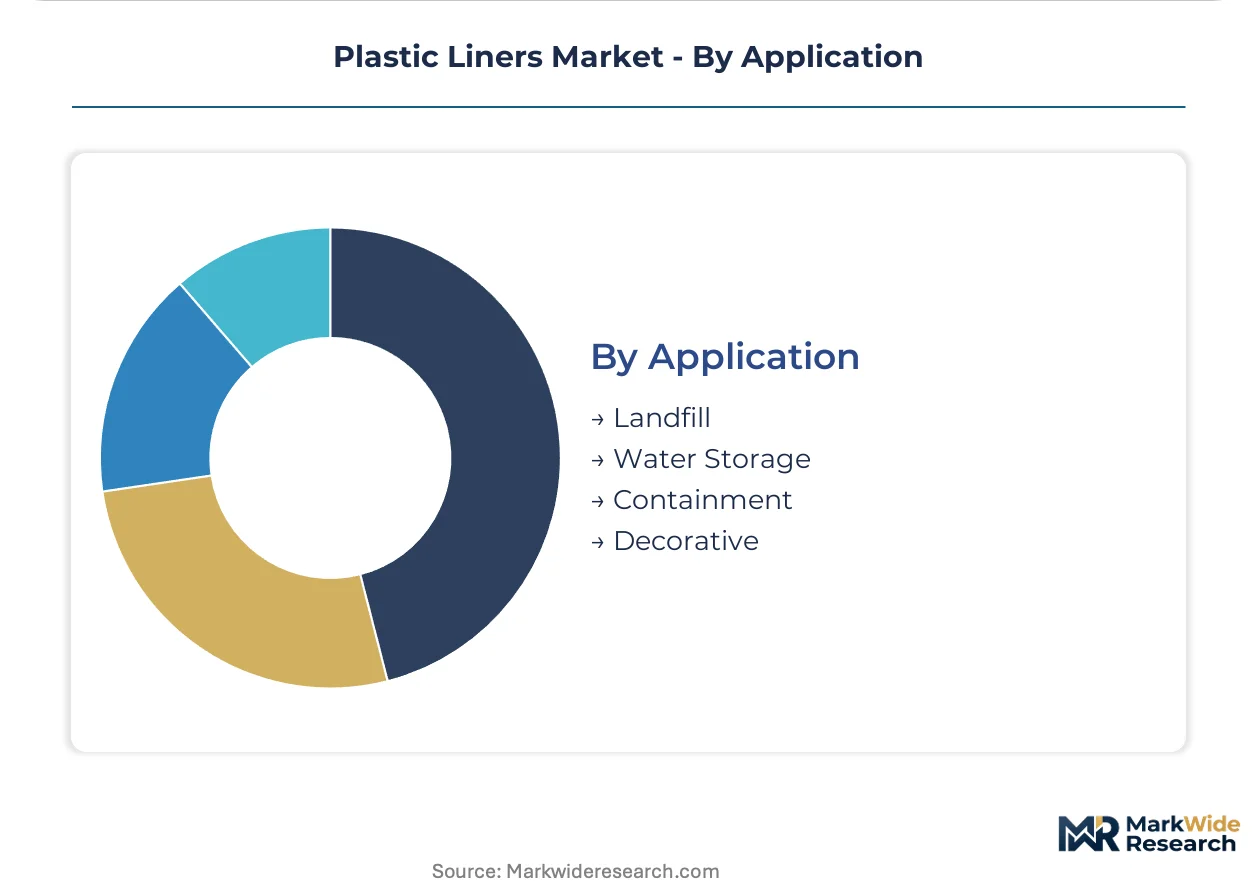
Landfill holds the largest share; momentum sits with water storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Subtitle D regulations in the United States anchor the most stringent geomembrane specifications worldwide, while India's Jal Jeevan Mission and China's dual carbon targets are redirecting procurement volumes toward certified polyethylene alternatives.
United States
Landfill capping and leachate collection systems drive polyethylene geomembrane demand under EPA Subtitle D mandates specifying minimum thickness and permeability coefficients. State environmental agencies in California and Texas enforce composite liner requirements for municipal solid waste facilities. The Houston-Gulf Coast corridor hosts extrusion capacity serving North American waste management contracts.
India
Reservoir lining and canal seepage control projects proliferate under the Jal Jeevan Mission watershed program. BIS certification requirements for geomembranes create compliance barriers for uncertified imports into water infrastructure tenders. State water boards in Maharashtra and Gujarat mandate 1.5mm minimum thickness specifications and third-party weld testing for canal rehabilitation contracts.
China
Provincial environmental bureaus offer tariff offsets for landfill gas capture installations using composite liner systems aligned with dual carbon goals. MEE standards tighten material specifications for hazardous waste containment in the Yangtze River Delta manufacturing belt. Shandong Peninsula extrusion clusters supply textured HDPE for mining tailings applications in Inner Mongolia.
Germany
The Federal Environment Agency now recommends polyethylene for all new leachate collection systems as REACH phthalate restrictions displace PVC alternatives. Municipal waste authorities in Bavaria and North Rhine-Westphalia revise tender specifications to exclude plasticizer-containing formulations. The Ruhr industrial corridor hosts fabrication capacity serving circular-economy procurement mandates across Benelux markets.
Vietnam
Intensive shrimp farming operations adopt EPDM pond liners for UV stability in exposed Mekong Delta installations. Hatchery operators prioritize weld seam reliability certification over unit material pricing in procurement decisions. The Cà Mau-Bạc Liêu aquaculture belt concentrates demand for synthetic rubber membranes with documented seam integrity guarantees.
Plastic Liners Market Competitive Landscape
Capability concentration sits with specialized geomembrane fabricators holding certified installation networks; scale advantage sits with diversified packaging conglomerates with captive resin supply. The market structures around three tiers: integrated resin-to-film producers, regional extrusion specialists, and installation-service bundlers. Strategic moves center on backward integration into resin compounding and certification depth expansion for water infrastructure tenders.
Among North American diversified packaging groups, Berry Global and Novolex occupy positions spanning resin supply through film conversion. Berry Global exemplifies the integrated archetype with vertical control across compounding and extrusion, while Novolex anchors municipal waste channel relationships. European specialists including RKW Group and Mondi Group represent the premium-tier vector, with Mondi Group positioning around recycled-content barrier films for EU circular-economy procurement windows.
| Leading Market Players |
|---|
| Berry Global |
| Novolex |
| Mondi Group |
| Sealed Air Corporation |
| RKW Group |
| Amcor plc |
| UFlex |
| Winpak Ltd. |
| Greif, Inc. |
| Others |
Value Network & Pricing Analysis
EPDM supply concentration in Northeast Asia determines both the premium spread for UV-stable pond liners and the geographic shape of resin sourcing networks. Procurement officers in Vietnam and Indonesia face extended lead times and tariff exposure when sourcing synthetic rubber membranes, compressing margins for hatchery operators while rewarding distributors with regional stocking capabilities.
Pricing Analysis
Price spreads between European and Southeast Asian geomembrane contracts reflect certification tier differentiation rather than resin cost alone. Three-tier pricing structure across premium certified, standard industrial, and economy ungraded levels separates BIS-validated Indian water infrastructure suppliers from informal extrusion operations. Cost compression in the economy tier is intensifying because state water boards under Jal Jeevan Mission now mandate third-party weld testing. Municipal waste authorities in Germany and France show the least price sensitivity, prioritizing REACH-compliant polyethylene over unit cost.
Supply Chain Analysis
Tariff exposure between Northeast Asian EPDM producers and Southeast Asian aquaculture operators dominates supply chain risk assessment for exposed pond applications. Geomembrane extrusion draws from ethylene feedstock clusters in the US Gulf Coast, Shandong Peninsula, and the Arabian Gulf, with naphtha cracking margins tethering resin cost volatility to regional petrochemical economics. Single-source vulnerability concentrates in conductive-layer HDPE for Chilean mining tailings, where textured membrane production rests on specialized coextrusion equipment. Distribution runs through project-specific contractor networks rather than commodity wholesale channels, with certified installation capability acting as the downstream gatekeeper.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around municipal waste authorities with multi-year contract security and state water boards with certification mandates, fragmenting price discovery across informal agricultural channels.
For Market Incumbents: Build certification depth as the primary moat against resin commoditization. Expand BIS-accredited welding training pipelines in Maharashtra and Gujarat to capture Jal Jeevan Mission tender volume. Deepen backward integration into post-consumer polyethylene recycling streams to satisfy EU circular-economy procurement windows and defend margin position against virgin resin volatility. For New Entrants and Emerging Players: Mid-scale Brazilian mining tailings operators represent the most penetrable entry point for equipment-leasing thermal wedge welding services. Uncertified EPDM imports into Vietnamese aquaculture face 8-12 week seam testing delays, creating white space for GSI-qualified installation partnerships. Lead with documented weld integrity guarantees rather than unit material pricing to displace informal contractor networks. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors certified installation-service bundlers over commodity resin suppliers. Long-term viability hinges on exposure to water infrastructure and landfill gas capture rather than discretionary agricultural demand. Monitor BIS geomembrane certification expansion into additional Indian states as the inflection signal for procurement formalization.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Unlocks access to Jal Jeevan Mission water infrastructure tenders in Maharashtra and Gujarat state boards. |
| Post-Consumer Recycling Stream Development | Positions suppliers for EU circular-economy procurement mandates displacing virgin polyethylene. |
| Thermal Wedge Welding Equipment Leasing | Reduces capital barriers for mid-scale Brazilian mining tailings pond operators. |
| GSI-Certified Welder Training Pipeline | Addresses technician scarcity delaying Southeast Asian aquaculture pond commissioning. |
| Conductive Layer Coextrusion Capacity | Captures Chilean and Peruvian mining demand for leak detection-integrated geomembranes. |
Research Methodology
Initial hypotheses were tested against primary input from geomembrane extrusion plant managers, state water board procurement officers, municipal waste authority technical directors, and GSI-certified welding contractors and refined through secondary validation. Trade data from customs authorities, EPA Subtitle D compliance filings, BIS certification registries, and ECHA REACH authorization timelines anchored supply-side and regulatory characterization. Bottom-up project pipeline analysis across Indian watershed programs and top-down resin demand modeling were triangulated against channel interviews.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material formulation, end-use industry, application thickness tier, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle analysis. Industry-specific forecast inputs incorporated Jal Jeevan Mission allocation trajectories and China's provincial landfill gas capture tariff offset programs.
Macroeconomic conditions sit as an overlay; deviation in ethylene feedstock costs, naphtha cracking margins, or rupee-dollar exchange rates would shift the trajectory for Indian water infrastructure deployment. Forecasts reflect assumptions regarding regulatory enforcement continuity and certification timeline stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
PCR Plastic Packaging Market