
 Plasma Protein Therapeutics Market | 2026-2036
Plasma Protein Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Protein Therapeutics Market Intelligence
The World Health Organization's push for improved plasma quality and safety is shifting demand towards therapeutics sourced from certified, high-standard collection centers. This focus on a sustainable and safe supply chain benefits large-scale operators. CSL Behring leverages its extensive global network of plasma collection facilities to ensure consistent supply. Grifols differentiates through its specialization in a broad portfolio of plasma-derived medicines. Takeda Pharmaceutical Company Limited competes with a highly integrated manufacturing and R&D infrastructure.
Plasma protein therapeutics are biological medicines derived from human blood plasma through a process called fractionation. This process isolates specific proteins, such as albumin and immunoglobulins, for therapeutic use. These therapies are essential for managing a range of rare and chronic conditions where patients have deficient or non-functional proteins. Immunoglobulin products command a significant market share, driven by their critical role in treating primary and secondary immunodeficiency disorders. The albumin segment, while mature, remains a high-volume category essential for applications in critical care and burn treatment.
The regulatory environment is stringent, with national and regional bodies setting high barriers to entry. The U.S. Food and Drug Administration (FDA), the European Medicines Agency (EMA), and China's National Medical Products Administration (NMPA) mandate rigorous clinical trials and adherence to Good Manufacturing Practices (GMP). These regulations ensure product safety, efficacy, and quality for patients worldwide. Stakeholders must now navigate the strategic allocation of R&D capital between advancing plasma fractionation technologies and investing in disruptive recombinant alternatives.
Market Dynamics
The central dynamic in the plasma protein therapeutics market is the tension between the escalating global need for plasma-derived medicines and the stringent regulatory frameworks governing plasma collection and safety, a pressure intensified by guidance from the World Health Organization.
Growth Catalysts
- Advanced Fractionation:Innovations in chromatography and filtration technologies are improving the yield and purity of proteins like immunoglobulin and albumin from source plasma, enhancing manufacturing efficiency.
- Diagnostic Improvements:Higher diagnostic rates for primary immunodeficiency (PID) and other rare diseases in developed nations are expanding the patient population eligible for immunoglobulin replacement therapy.
- Regulatory Harmonization:Efforts by bodies like the WHO to establish global standards for plasma quality and safety encourage investment in certified collection centers and secure supply chains.
Market Restraints
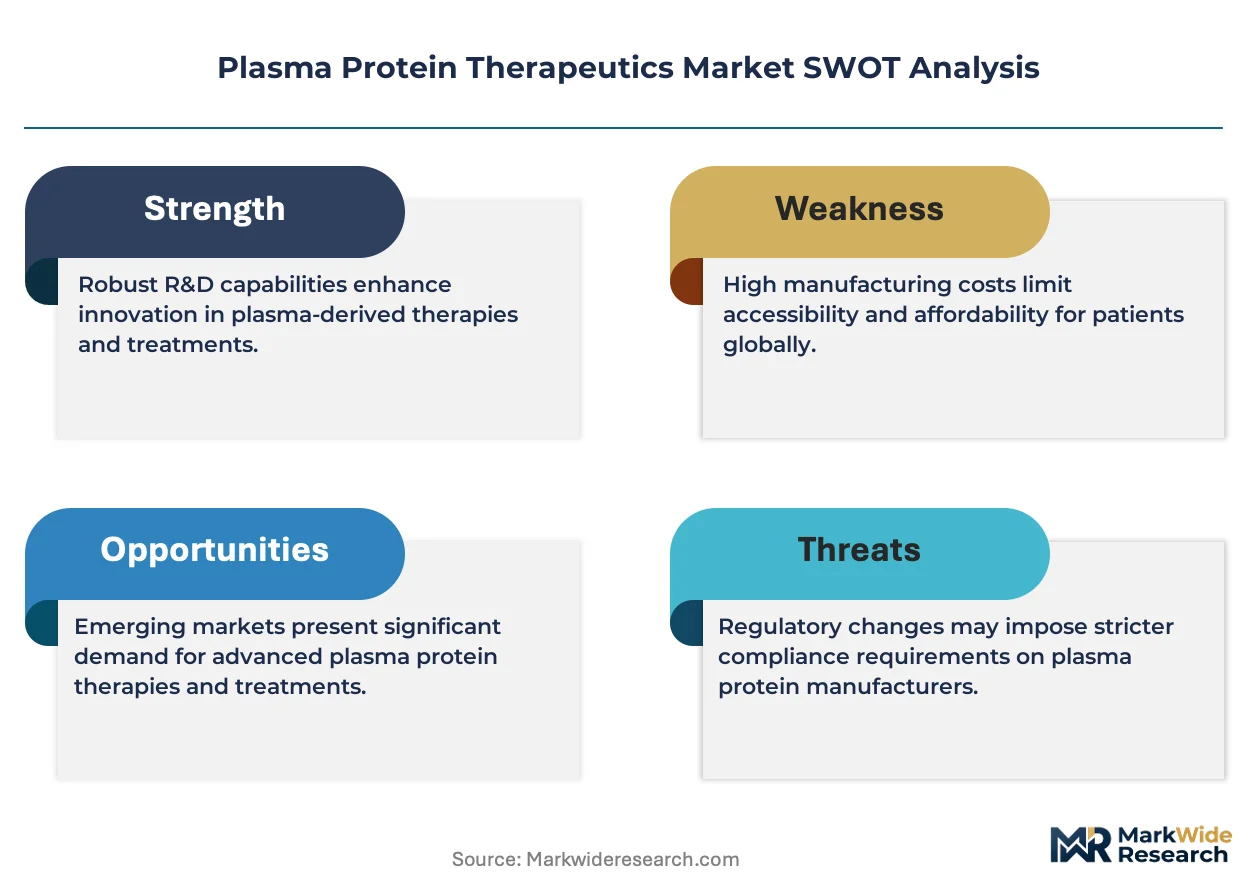
- Source Plasma Dependency:The industry's heavy reliance on a limited number of countries, chiefly the United States, for paid plasma donations creates significant geopolitical and logistical supply risks.
- High Production Costs:The capital-intensive nature of establishing and operating certified plasma collection centers and fractionation facilities results in a high cost of goods for final therapies.
- Recombinant Alternatives:The development of recombinant proteins, particularly for clotting factor disorders, presents a long-term substitution threat that bypasses the need for a human plasma supply chain.
Strategic Opportunities
- Geographic Expansion:Untapped markets in certain Asia-Pacific and Latin American countries represent a significant opportunity as healthcare infrastructure and diagnostic capabilities for rare diseases improve.
- New Therapeutic Indications:Research into the use of immunoglobulins for neurological conditions, such as Alzheimer's disease and multiple sclerosis, could open substantial new avenues for market growth.
- Subcutaneous Formulations:The development and promotion of subcutaneous immunoglobulin (SCIG) products offer greater patient convenience, support a shift to home-based care, and open new distribution channels.
Industry Challenges
- Regulatory Compliance Burden:Navigating the complex and lengthy approval processes of the FDA, EMA, and NMPA for new products, facilities, and manufacturing changes is a major operational hurdle.
- Specialized Labor Scarcity:A shortage of skilled technicians and quality assurance professionals trained in plasma fractionation and cGMP compliance can constrain production capacity expansion.
- Donor Base Management:Maintaining a large, consistent, and healthy donor pool requires significant logistical effort and investment in donor recruitment, retention, and health screening programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Protein Therapeutics Market |
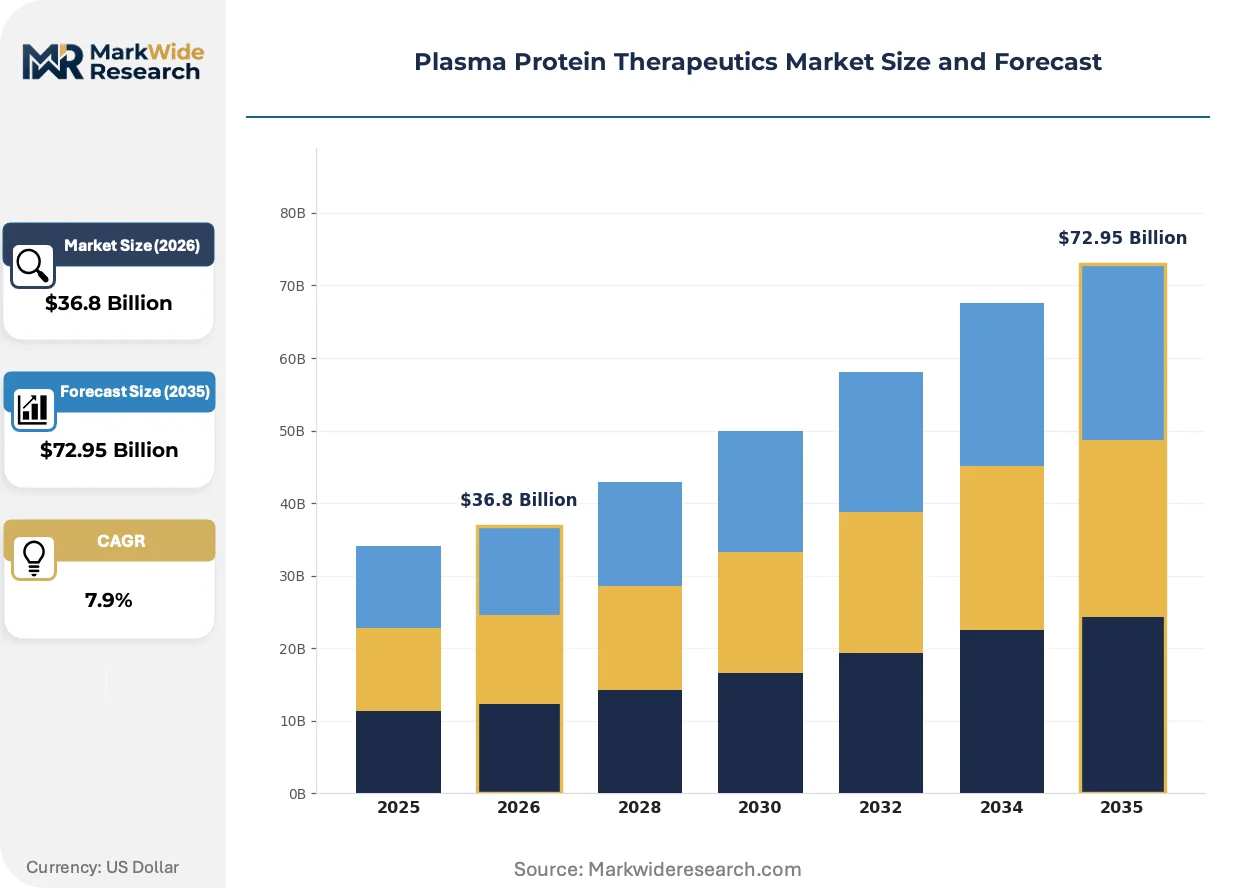
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $72.95 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
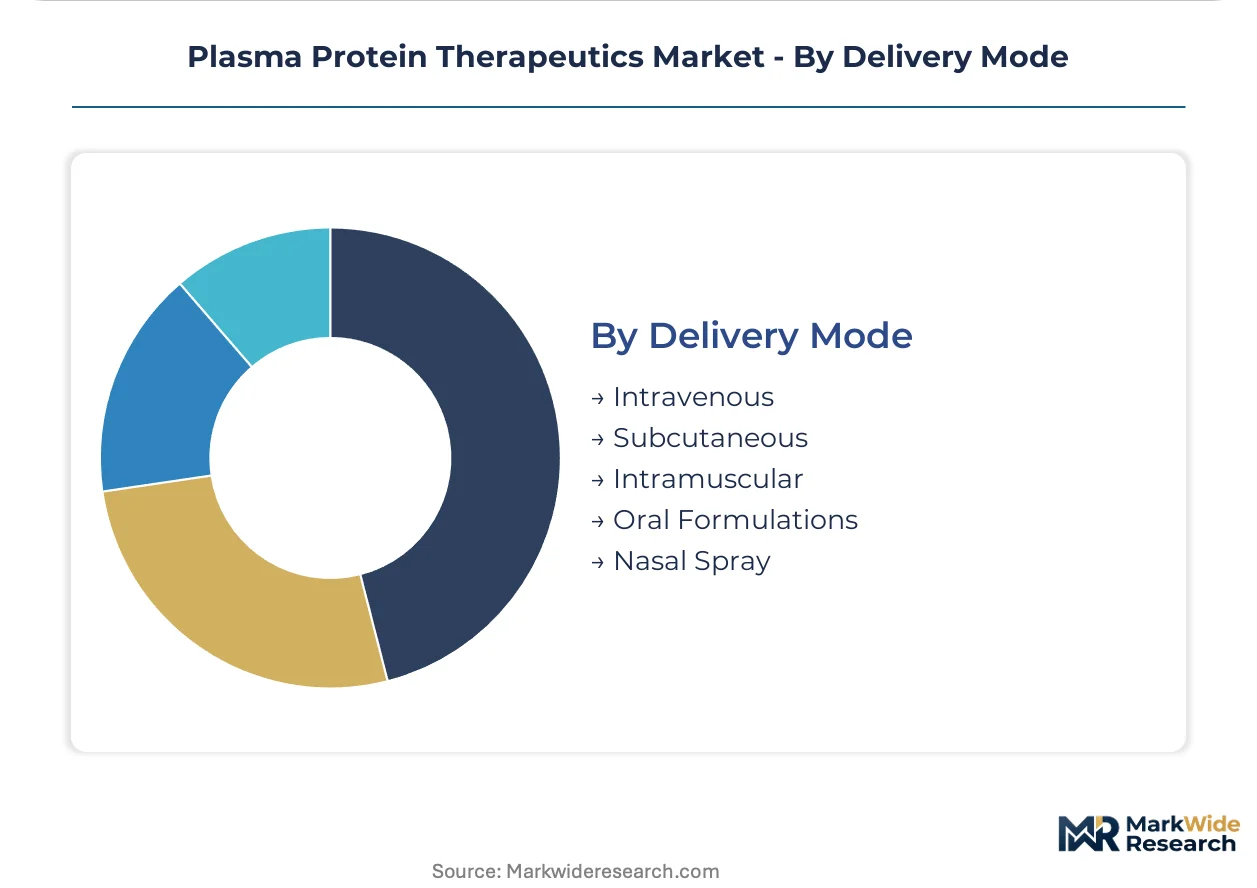
| Segmentation | Product Type: Albumin, Immunoglobulin, Factor VIII, Fibrinogen, Alpha-1 Antitrypsin Application: Immunodeficiency Disorders, Coagulation Disorders, Burn Treatment, Chronic Liver Disease, Autoimmune Diseases End User: Blood Banks, Diagnostic Laboratories, Specialty Clinics, Research Institutions, Home Healthcare Providers Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral Formulations, Nasal Spray |
| Companies Covered | CSL Behring, Takeda Pharmaceutical Company Limited, Grifols, Octapharma, Bayer AG, Biotest AG, Kedrion, Novo Nordisk A/S, Bio Products Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Protein Therapeutics Market Strategic Shifts & Innovations
A dual focus on optimizing the existing plasma-derived supply chain while simultaneously investing in disruptive, non-plasma technologies defines the market's trajectory. This creates a strategic imperative to balance evolutionary process improvements with revolutionary product development.
Recombinant protein technology provides a method to produce therapeutic proteins like clotting factors without requiring human plasma. It is being adopted by hematology and rare disease treatment centers, especially for managing hemophilia. The potential to bypass the entire plasma collection and fractionation process is electrifying the competitive landscape for specific factor concentrates.
European Medicines Agency (EMA) guidelines on plasma quality and donor management are reinforcing vein-to-vial traceability requirements. This compels manufacturers to invest in sophisticated tracking systems and quality management protocols across their collection networks. The immunoglobulin and albumin segments are most affected, as their production relies on large plasma pools, making compliance a significant operational undertaking.
Patient-administered therapies, specifically subcutaneous immunoglobulins (SCIG), are gaining significant traction. This model disrupts the traditional hospital or clinic-based infusion channel, empowering specialty pharmacies and home healthcare providers. The shift is most visible in the United States and Western Europe, supported by patient preference for convenience and favorable reimbursement for at-home care.
Plasma Protein Therapeutics Market Segmentation
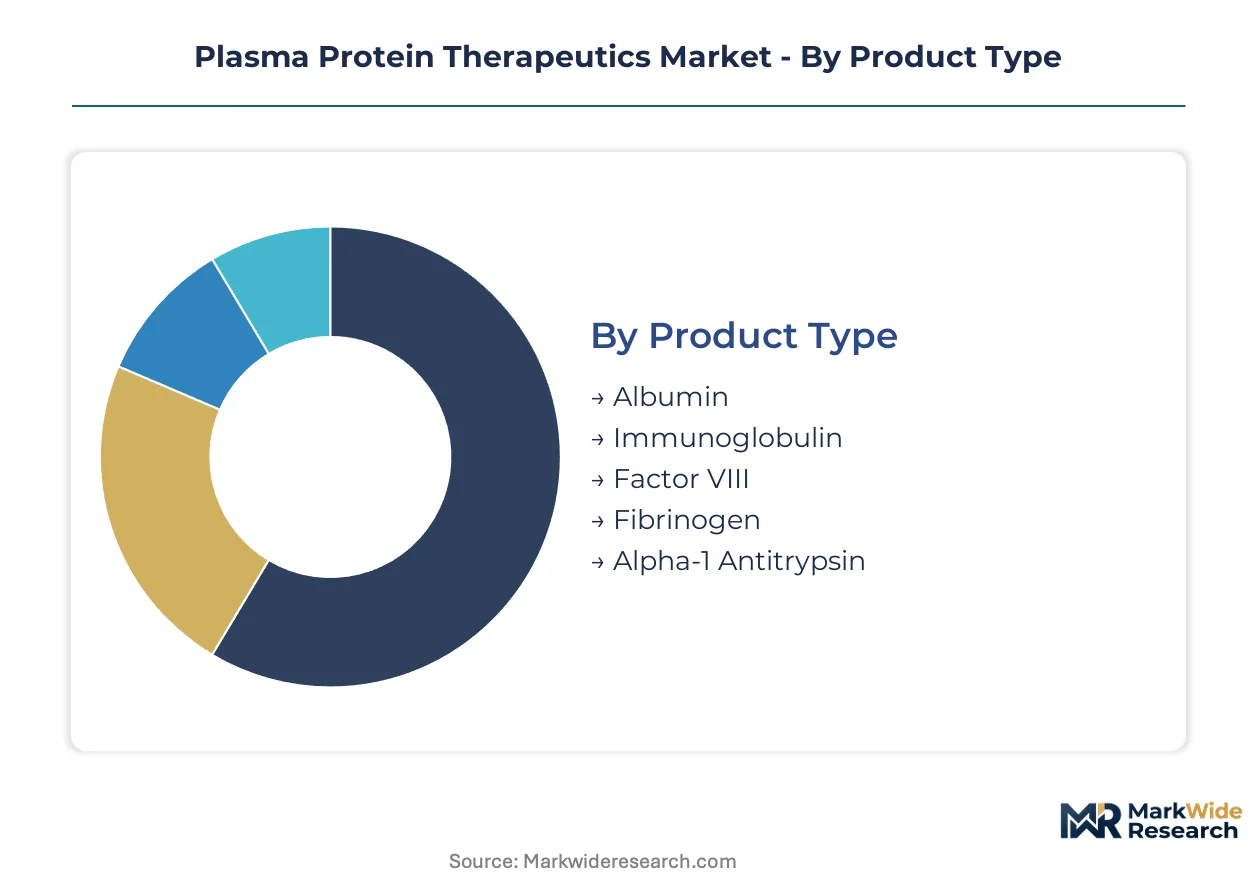
The Plasma Protein Therapeutics market is analyzed across several dimensions, providing a granular view of product utilization, therapeutic applications, and patient access pathways. Understanding these distinct segments is crucial for stakeholders to identify areas of concentration and emerging opportunities within this specialized pharmaceutical sector.
Product Type:
The Plasma Protein Therapeutics market segments by product type, reflecting the diverse biological medicines utilized as standalone treatments or in conjunction with other therapies.
- Albumin:This segment comprises a protein essential for maintaining oncotic pressure and transporting various substances in the blood. Demand concentrates in critical care settings and burn treatment, driven by its established efficacy in volume expansion and protein replacement.
- Immunoglobulin:These are antibody preparations used to treat a wide range of immunodeficiency disorders and autoimmune conditions. Their demand is high in developed nations like the United States, supported by robust diagnostic rates for primary immunodeficiencies and favorable reimbursement policies.
- Factor VIII:This protein is primarily used in the treatment of hemophilia A, a genetic bleeding disorder.
- Fibrinogen:A crucial protein involved in blood clotting, primarily used to manage bleeding in patients with congenital or acquired fibrinogen deficiencies.
- Alpha-1 Antitrypsin:This protein is administered to patients with Alpha-1 Antitrypsin Deficiency, a genetic disorder causing lung and liver disease.
Immunoglobulin leads volumes today; Factor VIII is gaining share fastest.
Application:
The market's application segments delineate the critical medical conditions addressed by plasma-derived therapies, ranging from acute interventions to long-term chronic disease management.
- Immunodeficiency Disorders:This application involves the use of immunoglobulin products to replace missing or non-functional antibodies in patients with primary or secondary immunodeficiencies. Demand is consistently high in Western Europe and North America, fueled by improved diagnostic capabilities and long-term patient management protocols.
- Coagulation Disorders:This segment includes therapies like Factor VIII and Fibrinogen concentrates, crucial for managing bleeding in patients with hemophilia and other clotting factor deficiencies.
- Burn Treatment:Albumin is a key therapy in burn treatment to restore fluid balance and prevent shock.
- Chronic Liver Disease:Albumin is also used in managing complications of chronic liver disease, such as ascites and spontaneous bacterial peritonitis.
- Autoimmune Diseases:High-dose immunoglobulin therapies are increasingly used to modulate the immune system in various autoimmune conditions. Research into new neurological indications, such as Alzheimer's disease, expands potential demand.
The primary application area remains Immunodeficiency Disorders, while Autoimmune Diseases demonstrate the steepest expansion trajectory.
End User:
End user segmentation highlights the diverse healthcare settings and professional groups responsible for administering or utilizing plasma protein therapies, reflecting varied patient access points.
- Blood Banks:These facilities are critical for the initial collection and processing of plasma, serving as upstream suppliers for fractionation.
- Diagnostic Laboratories:Laboratories utilize plasma derivatives for various diagnostic tests and research purposes.
- Specialty Clinics:These clinics, often hospital-affiliated, serve as primary administration sites for intravenous plasma protein therapies. Their role is central to patient care for complex and chronic conditions.
- Research Institutions:Academic and private research institutions use plasma proteins for scientific studies and drug development.
- Home Healthcare Providers:This segment is expanding due to the rise of patient-administered subcutaneous immunoglobulin (SCIG) products. Home healthcare providers facilitate at-home treatment, enhancing patient convenience, particularly in the United States.
Specialty Clinics constitute the largest end-user group, with Home Healthcare Providers expanding most quickly.
Delivery Mode:
Delivery mode segments reflect the maturity of administration methods, from established intravenous routes to newer patient-centric options.
- Intravenous:This is the traditional and most common method for administering plasma protein therapies, particularly for high-dose immunoglobulin. It requires administration by healthcare professionals, typically in a clinical setting.
- Subcutaneous:Subcutaneous delivery involves injecting the therapy under the skin, allowing for patient self-administration at home. This mode is gaining significant traction for immunoglobulins in Western Europe and the United States due to improved patient convenience and quality of life.
- Intramuscular:This mode involves injection directly into a muscle, used for specific plasma-derived products, though less common for high-volume therapies.
- Oral Formulations:Oral delivery represents a niche area, with limited application for plasma protein therapeutics due to protein degradation in the digestive system.
- Nasal Spray:Nasal spray delivery is an investigational or highly specialized route, not widely adopted for current plasma protein therapeutics.
Intravenous administration remains foundational, but Subcutaneous formulations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plasma protein therapeutics industry significantly scaled in the United States, driven by early advancements in fractionation technology and a robust commercial plasma collection infrastructure. This foundational development enabled widespread access to essential therapies. Today, demand for these specialized medicines continues to expand globally, with key regions contributing to both supply and consumption.
United States
High diagnostic rates for primary immunodeficiency disorders drive strong demand for immunoglobulin products. The U.S. Food and Drug Administration (FDA) enforces stringent quality and safety standards for plasma collection and manufacturing processes. Major biopharmaceutical hubs like Boston and San Francisco are centers for R&D into new therapeutic applications and advanced fractionation techniques.
Germany
Europe's largest market for plasma protein therapies benefits from comprehensive healthcare coverage and a strong focus on rare disease treatment. The European Medicines Agency (EMA) guidelines heavily influence plasma quality and donor management across the nation. Munich and Berlin host significant research institutions and manufacturing facilities for plasma-derived products, supporting regional supply.
Japan
An aging population and advanced healthcare system contribute to a steady demand for albumin and immunoglobulin products. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous oversight of product safety and efficacy, maintaining high market confidence. Osaka and Tokyo are key centers for pharmaceutical R&D and plasma fractionation operations, driving local innovation.
China
Expanding healthcare infrastructure and increasing awareness of rare diseases are stimulating demand for plasma protein therapeutics. China's National Medical Products Administration (NMPA) is tightening regulations on plasma collection and product approval, aiming for higher quality standards. Shanghai and Beijing are emerging as significant hubs for biotechnology investment and manufacturing capacity within the country.
India
Growing diagnostic capabilities and improving access to specialized treatments are increasing the patient pool for these therapies. The Central Drugs Standard Control Organization (CDSCO) regulates the import and domestic production of plasma-derived products, ensuring market access. Hyderabad and Bengaluru are developing as pharmaceutical manufacturing and R&D centers, attracting investment in biotherapeutics production.
Plasma Protein Therapeutics Market Key Industry Players
Premium-margin players sit above commodity-margin players across the plasma protein therapeutics value chain, reflecting significant investment in R&D and complex manufacturing processes. The market exhibits a tiered structure, with a few large, integrated biopharmaceutical companies dominating the high-value segments like immunoglobulin. These major players focus on strategic partnerships and expanding their global plasma collection networks to secure raw material supply. Portfolio diversification, particularly into specialized immunoglobulin products and advanced fractionation technologies, remains a dominant competitive move for these firms.
Within the highly integrated global biopharmaceutical segment, CSL Behring and Grifols exemplify companies with extensive plasma collection and fractionation capabilities. These entities leverage their large-scale operations to ensure consistent supply and broad product portfolios, often across multiple therapeutic areas. Takeda Pharmaceutical Company Limited further anchors this tier, known for its significant R&D investments and integrated manufacturing infrastructure that spans both plasma-derived and recombinant products. These companies strategically position themselves to meet stringent regulatory demands and global patient needs, often through continuous innovation in processing technologies and new therapeutic indications.
| Leading Market Players |
|---|
| CSL Behring |
| Takeda Pharmaceutical Company Limited |
| Grifols |
| Octapharma |
| Bayer AG |
| Biotest AG |
| Kedrion |
| Novo Nordisk A/S |
| Bio Products Laboratory |
| Others |
Cost & Logistics Intelligence
Skilled technicians and quality assurance professionals represent a concentrated workforce, impacting labor-cost differentials and influencing pricing-tier spreads across the plasma protein therapeutics market. High production costs for certified collection centers and fractionation facilities directly feed into the premium pricing of specialized therapies.
Pricing Analysis
Value-based pricing models dominate the plasma protein therapeutics market, reflecting the critical nature of these life-saving treatments. Price differentiation stems from the stringent quality grades enforced by bodies like the FDA and EMA, alongside the brand premium associated with established manufacturers. Pricing softness reflects the long-term threat of recombinant alternatives for specific indications. Healthcare systems managing rare diseases exhibit lower price sensitivity compared to those procuring high-volume albumin products for critical care.
Supply Chain Analysis
Human blood plasma supply relies heavily on collection centers, primarily concentrated in the United States for paid donations. Raw material dependencies include source plasma and specialized fractionation reagents. This reliance creates significant geopolitical and logistical supply risks for manufacturers. Distribution runs through a dual model, leveraging specialty clinics for intravenous administration and expanding into home healthcare providers for subcutaneous formulations in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plasma protein therapeutics market offers margin expansion opportunities, driven by advanced fractionation technologies improving yield and purity.
For Market Incumbents: Deploy advanced fractionation technologies to optimize protein yield and reduce manufacturing costs. Secure raw material supply through strategic expansion of global plasma collection networks, mitigating geopolitical risks. Invest in R&D for new therapeutic indications, particularly neurological conditions, to counter the long-term threat from recombinant alternatives. Strengthen regulatory affairs capabilities to navigate complex approval processes across multiple jurisdictions.
For New Entrants and Emerging Players: Enter via specialized product niches or underserved geographic markets, such as certain Asia-Pacific and Latin American countries, where healthcare infrastructure is improving. The home-based care segment for subcutaneous immunoglobulin products represents a penetrable entry point. Partner with local healthcare providers and specialty pharmacies to establish efficient distribution channels and patient support programs.
For Investors and Strategic Acquirers: Biopharmaceutical companies with extensive plasma collection capabilities are the most active acquirers in this space, seeking to secure supply and expand portfolios. The market presents strong long-term viability for specialized plasma-derived therapies over the next decade. Watch for successful clinical trial outcomes for new immunoglobulin indications or significant regulatory harmonization efforts that could streamline market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | New indications for immunoglobulins expand patient populations and market demand. |
| Regulatory Approval Pathway | Efficient navigation of FDA and EMA processes accelerates market access for novel therapies. |
| Manufacturing Scale-Up | Increased capacity ensures consistent supply for a growing global patient base. |
| Pipeline Diversification | Expanding product offerings reduces reliance on single therapeutic areas or product types. |
| Licensing Agreement | Access to proprietary fractionation technologies or novel drug candidates strengthens market position. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each major region. The analysis combines in-depth primary interviews with industry stakeholders, including plasma collection center managers, regulatory affairs specialists, biopharmaceutical R&D directors, and hospital pharmacists. Secondary validation draws from FDA filings, EMA guidelines, WHO reports, and company annual reports, triangulating findings through bottom-up and top-down approaches.
The forecast framework models market dynamics at a granular level, segmenting by product type, application, end-user, delivery mode, and regional market characteristics across the analysis window. Segmentation dimensions include immunoglobulin and albumin products, immunodeficiency and coagulation disorders, specialty clinics and home healthcare providers, and intravenous and subcutaneous delivery modes. Compound annual growth rates (CAGRs) derive from historical trends and projected future demand, incorporating plasma donation rates and diagnostic improvements for rare diseases as key inputs.
Inputs from industry reports and expert interviews were available through the study window; gaps in long-term R&D success rates for recombinant alternatives introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Unforeseen regulatory changes or geopolitical events affecting plasma supply represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Canada Specialty Pharmacy Market