
 Antiepilepsy Drugs Market | 2026-2036
Antiepilepsy Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antiepilepsy Drugs Market Outlook
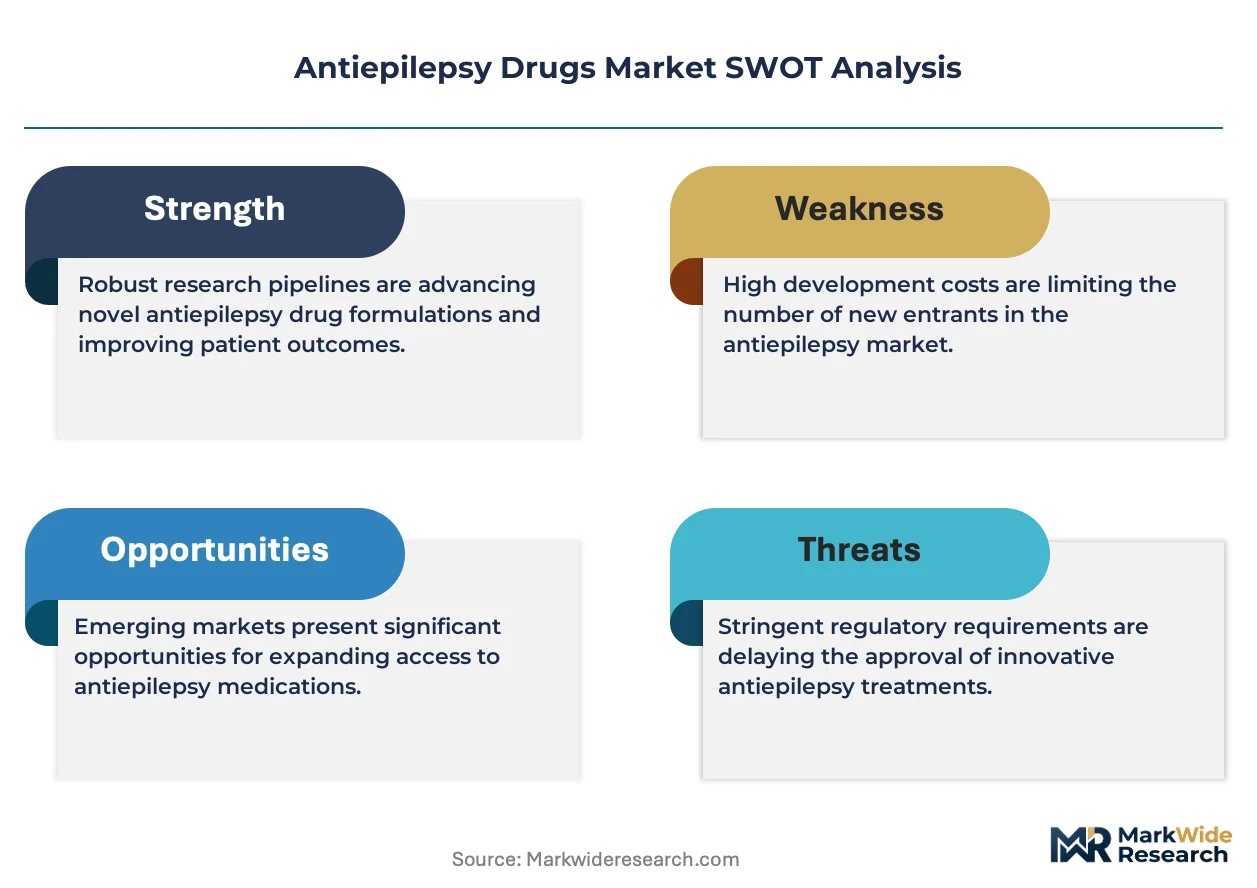
Fixed-dose combination packaging is consolidating as the dominant product-configuration pattern in antiepileptic therapy, reducing pill burden for patients on polytherapy regimens. Pfizer Inc. leverages its manufacturing scale to supply broad-spectrum agents across multiple dosage strengths. UCB S.A. anchors its position through sustained investment in refractory epilepsy R&D. Eisai Co., Ltd. differentiates via specialized expertise in pediatric seizure disorders.
Antiepilepsy drugs comprise pharmaceutical compounds that modulate neuronal excitability through mechanisms including sodium channel blockade, GABA potentiation, or glutamate antagonism, formulated to achieve precise plasma concentration targets measured in micrograms per milliliter. These agents serve the primary commercial purpose of preventing seizure recurrence while minimizing neurocognitive side effects in chronic therapy settings. The therapeutic class dimension shows first-line agents occupying the largest volume share due to established reimbursement pathways, while novel agents represent the fastest-expanding margin pool driven by biologics and gene-targeted small molecules. Levetiracetam within the drug type category sustains dominant prescribing frequency across adult populations, whereas the pediatric patient type segment generates disproportionate clinical trial investment from sponsors seeking orphan drug exclusivity.
The FDA maintains stringent bioequivalence standards for antiepileptic generics through its BCS-based biowaiver restrictions, while the EMA's orphan medicine designation framework incentivizes development for rare epilepsy syndromes. Health Canada and the TGA align with ICH E14 guidelines for QT prolongation risk assessment in new molecular entities. Stakeholders must monitor evolving pharmacovigilance requirements for suicidality boxed warnings and determine whether to prioritize biosimilar entry or next-generation mechanism-of-action programs.
Market Dynamics
Hospital neurology departments are expanding their epilepsy monitoring units as a core service line, concentrating demand for advanced therapeutic classes within tertiary care centers and reshaping how pharmaceutical manufacturers prioritize their commercial deployment strategies.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's orphan neurological indication programs compress development timelines for rare epilepsy syndromes, incentivizing sponsors to advance novel mechanisms toward commercialization.
- Fixed-Dose Combination Packaging:Pharmaceutical formulators are consolidating multi-drug regimens into single-pill configurations, reducing patient pill burden and improving adherence rates in polytherapy populations.
- Pediatric Orphan Exclusivity:Sponsors are channeling disproportionate clinical trial investment into pediatric seizure disorder indications to secure extended market exclusivity under orphan drug frameworks.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Supply of key antiepileptic raw materials concentrates among a limited set of specialized chemical manufacturers, creating vulnerability to single-source disruption.
- BCS-Based Biowaiver Restrictions:The FDA maintains stringent bioequivalence standards that limit generic substitution pathways for narrow therapeutic index antiepileptic compounds.
- Neurocognitive Side Effect Liability:Chronic therapy requirements impose elevated safety surveillance burdens that extend regulatory review cycles and post-market pharmacovigilance costs.
Strategic Opportunities
- Gene-Targeted Small Molecule Platforms:Biologics and precision genetic therapies represent unoccupied white space within the therapeutic class, offering differentiated mechanisms for refractory patient populations.
- EMA Orphan Medicine Designation:The European framework incentivizes development for rare epilepsy syndromes with protocol assistance and fee reductions, creating favorable economics for niche indications.
- Direct-to-Specialist Distribution:Bypassing traditional wholesale channels to serve tertiary epilepsy centers directly enables tighter inventory management and service-level differentiation.
Industry Challenges
- Suicidality Boxed Warning Compliance:Evolving pharmacovigilance requirements mandate extensive risk evaluation and mitigation strategies that consume regulatory affairs bandwidth.
- Plasma Concentration Target Precision:Achieving microgram-per-milliliter therapeutic windows requires sophisticated manufacturing process controls and analytical method validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiepilepsy Drugs Market |
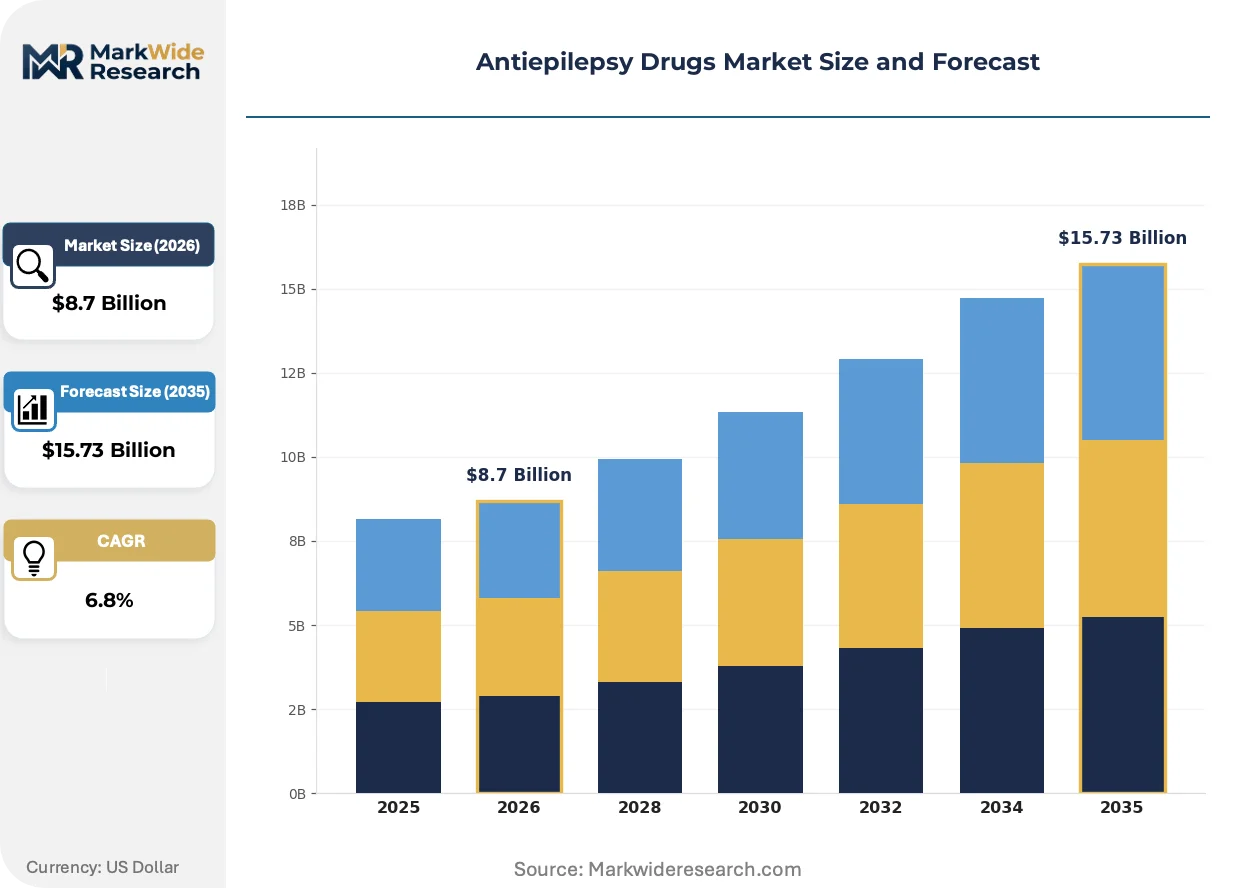
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Carbamazepine, Valproate, Lamotrigine, Levetiracetam Administration Route: Oral, Intravenous, Sublingual, Rectal Therapeutic Class: First-Line, Second-Line, Adjunctive, Novel Agents Patient Type: Pediatric, Adult, Geriatric, Others |
| Companies Covered | Novartis AG, Pfizer Inc., UCB S.A., Johnson & Johnson, Eisai Co., Ltd., GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Sanofi S.A., Jazz Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiepilepsy Drugs Market Strategic Shifts
Digital biomarker integration and mechanism-of-action diversification are actively transforming how antiepileptic therapies demonstrate value, shifting clinical trial endpoints beyond seizure frequency reduction toward functional outcome measures.
Closed-loop neurostimulation systems are integrating machine learning algorithms for real-time seizure prediction and responsive therapy delivery. Tertiary epilepsy centers in the United States are adopting these implantable devices at accelerating rates for drug-resistant patient cohorts. This convergence of neuromodulation hardware with predictive analytics is integrating a new standard of care that pharmaceutical developers must position against or partner with.
The FDA's suicidality boxed warning requirements for antiepileptic drug classes are mandating expanded risk evaluation and mitigation strategies across all new molecular entities. Sponsors must now incorporate prospective psychiatric monitoring into Phase III protocols, extending trial timelines and increasing safety database requirements. Pediatric and adolescent indications face the most stringent application of these standards, with regulators requiring dedicated suicidality assessment instruments.
Specialist procurement patterns are consolidating purchasing authority within hospital pharmacy and therapeutics committees at tertiary epilepsy centers. Academic medical centers are displacing individual prescriber discretion with protocol-driven formularies that prioritize agents with demonstrated health economic evidence. This concentration is most visible across the United States, where integrated delivery networks are standardizing antiepileptic selection across their neurology service lines.
Antiepilepsy Drugs Market Segmentation
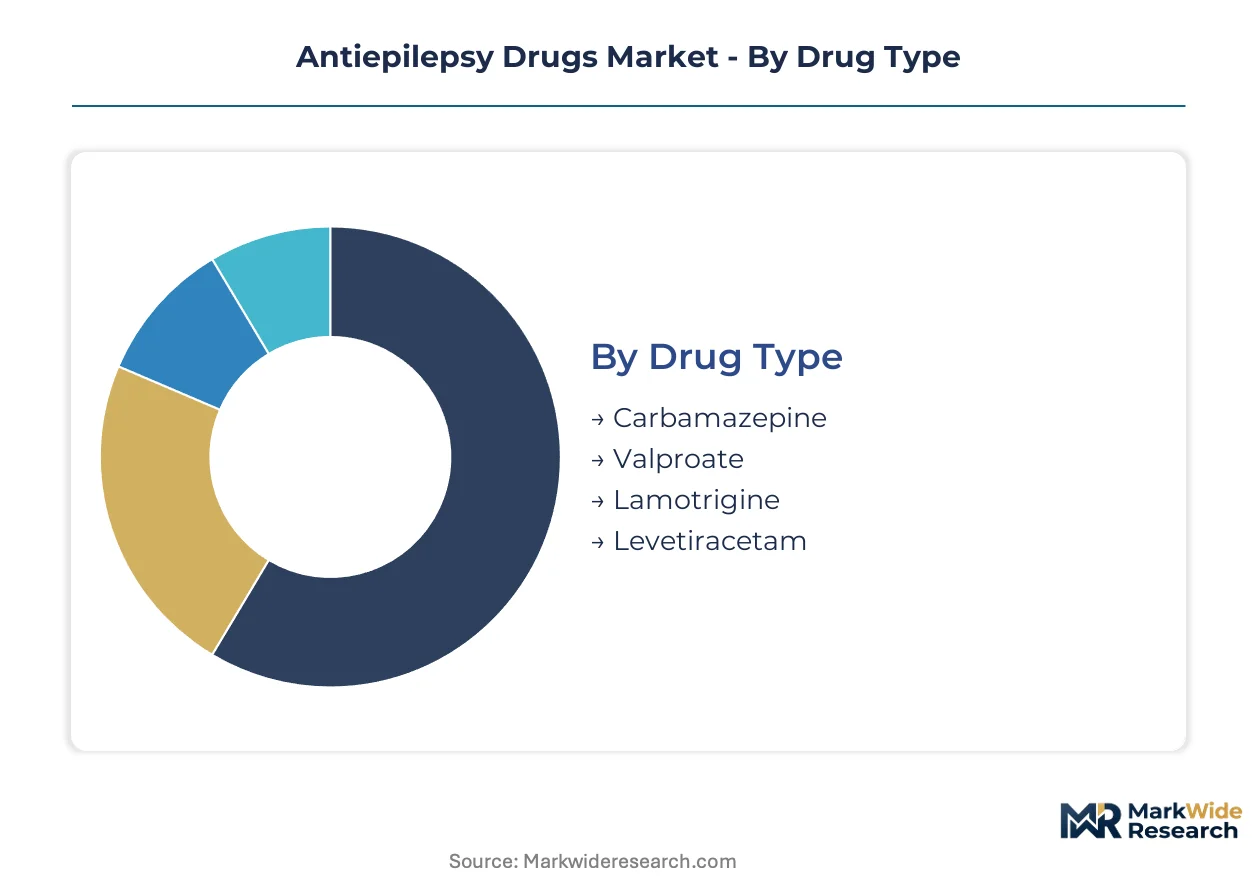
Antiepilepsy drug purchasing decisions hinge on precise alignment between seizure phenotype, comorbidity profile, and reimbursement tier. Manufacturers configure their portfolios across four intersecting dimensions to capture volume in polytherapy regimens and monotherapy initiations alike.
Drug Type:
Prescribers select agents based on mechanism specificity against partial versus generalized seizure patterns and established therapeutic drug monitoring protocols.
- Levetiracetam:A pyrrolidine derivative with unique SV2A binding kinetics that lacks enzyme-inducing properties, simplifying combination therapy. Demand concentrates in United States tertiary epilepsy centers where broad-spectrum efficacy drives protocol-driven formulary placement for both focal and generalized onset seizures.
- Lamotrigine:A phenyltriazine compound with voltage-dependent sodium channel blockade and glutamate release inhibition. Prescription volume skews toward adult populations requiring maintenance monotherapy with favorable cognitive side effect profiles, though titration complexity limits emergency department adoption.
- Carbamazepine:A tricyclic iminostilbene with established autoinduction pharmacokinetics requiring dose escalation over weeks.
- Valproate:A branched-chain fatty acid with histone deacetylase inhibition and multiple ion channel effects.
Levetiracetam leads on scale; Lamotrigine leads on momentum.
Administration Route:
Emergency neurology departments prioritize bioavailability speed and caregiver administration feasibility when selecting formulation.
- Oral:Immediate-release and extended-release tablets and capsules dominate chronic outpatient maintenance with precise dose titration capabilities. Volume concentrates in retail pharmacy channels serving stable ambulatory populations with established seizure control.
- Intravenous:Solution formulations enable rapid loading in status epilepticus and perioperative settings where enteral absorption is compromised. Demand clusters in academic medical center emergency departments and epilepsy monitoring units requiring therapeutic plasma concentration achievement within minutes.
- Sublingual:Rapidly dissolving films and tablets address breakthrough seizures in patients with impaired swallowing or gastric motility.
- Rectal:Gel formulations serve pediatric and institutionalized populations during acute seizure clusters when intravenous access is unavailable.
Oral formulations anchor maintenance therapy volume; Intravenous delivery commands acute care premium pricing.
Therapeutic Class:
Payer tier placement and step-therapy protocols determine prescriber access sequences across the treatment algorithm.
- First-Line:Established agents with decades of safety data and generic availability occupy the largest prescription volume tier due to mandatory prior authorization avoidance and preferred formulary status in commercial and government payers.
- Novel Agents:Mechanism-targeted small molecules and biologics represent the steepest expansion trajectory as sponsors secure orphan exclusivity for refractory syndromes and gene-defined patient subsets.
- Second-Line:Alternative monotherapy options reserved for first-line failure or intolerance with intermediate cost positioning.
- Adjunctive:Add-on therapies for polytherapy regimens in drug-resistant epilepsy with specialized monitoring requirements.
First-Line agents dominate prescription count; Novel Agents dominate pipeline investment intensity.
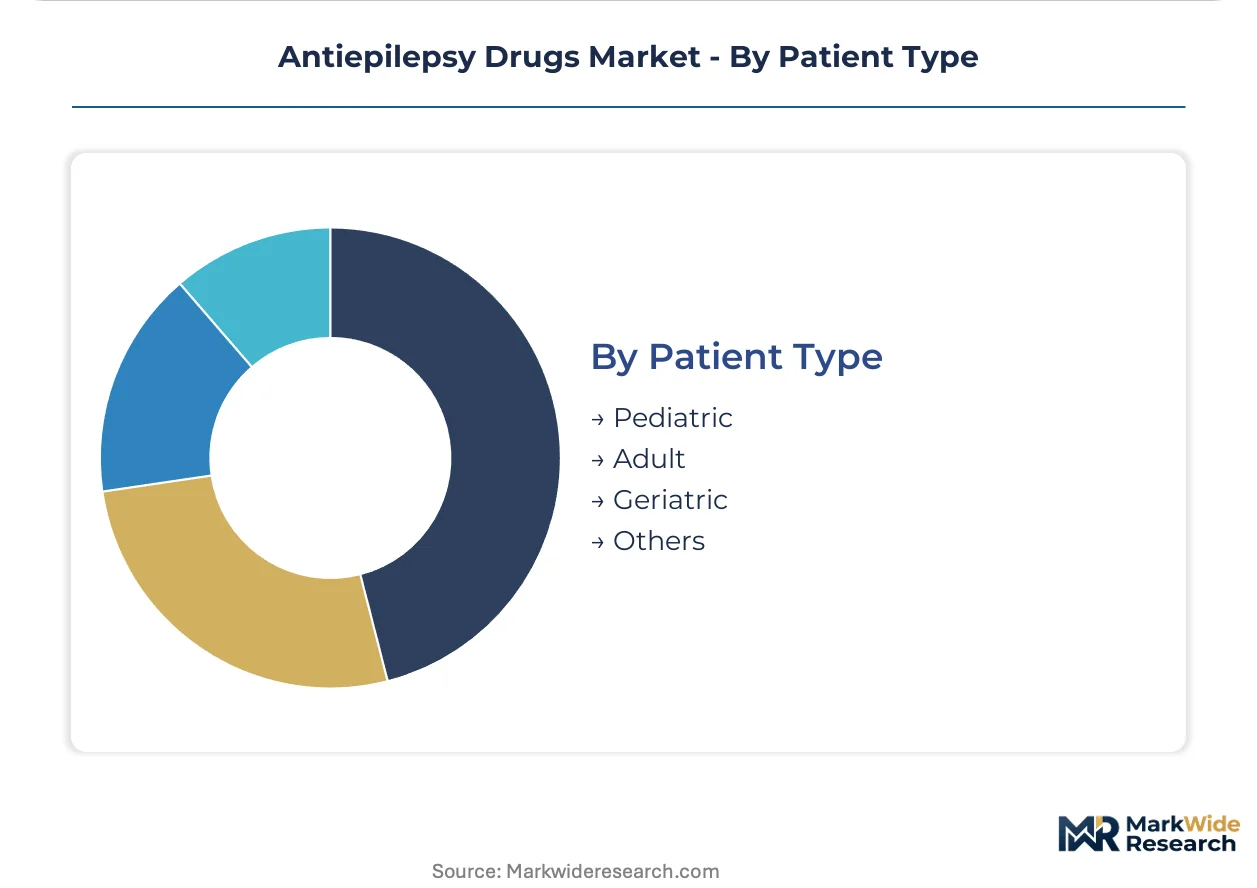
Patient Type:
Developmental neurobiology and age-specific pharmacokinetics dictate dosing complexity and regulatory submission strategy.
- Pediatric:Neonatal through adolescent populations require weight-based dosing, liquid formulations, and dedicated safety databases. Clinical trial investment concentrates here as sponsors pursue orphan drug exclusivity extensions and pediatric indication premiums.
- Adult:The 18-64 demographic sustains the largest absolute prescription volume with established employment-driven adherence patterns and employer-sponsored pharmacy benefit structures.
- Geriatric:Patients over 65 with polypharmacy and altered drug metabolism require modified dosing and heightened fall risk surveillance.
- Others:Pregnancy category considerations and institutionalized populations with specialized administration needs.
Adult patients anchor commercial volume; Pediatric indications anchor R&D allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern antiepilepsy pharmaceutical industry traces its commercial origins to Swiss and German chemical laboratories of the mid-twentieth century, where systematic screening of hydantoin derivatives yielded the first rationally designed seizure control agents. That European research foundation subsequently migrated to United States academic medical centers, where tertiary epilepsy centers now concentrate global prescription volume for advanced therapeutic classes.
United States
Tertiary epilepsy centers in Boston, New York, and Cleveland drive disproportionate demand for novel antiepileptic mechanisms and closed-loop neurostimulation systems. The FDA's accelerated approval pathways for orphan neurological indications compress development timelines for rare epilepsy syndromes. Philadelphia's cluster of contract research organizations supports specialized pediatric trial execution for sponsors seeking extended exclusivity.
Germany
University hospital neurology departments in Munich, Berlin, and Heidelberg anchor European demand for precision genetic therapies and refractory epilepsy interventions. The EMA's orphan medicine designation framework incentivizes development through protocol assistance and fee reductions. Baden-Württemberg's pharmaceutical manufacturing corridor hosts specialized active pharmaceutical ingredient production for narrow therapeutic index compounds.
Switzerland
Basel's concentrated pharmaceutical research ecosystem generates substantial early-stage neuroscience investment and biologics platform development. Swissmedic maintains stringent pharmacovigilance standards that align with ICH guidelines for QT prolongation risk assessment. The Lake Geneva region's contract manufacturing organizations supply high-purity chemical intermediates to global antiepileptic formulators.
Japan
PMDA regulatory frameworks for pediatric indication premiums attract disproportionate clinical trial investment into neonatal and adolescent seizure disorder programs. Tokyo and Osaka academic medical centers specialize in status epilepticus intervention protocols requiring intravenous formulation availability. The country's geriatric demographic sustains demand for modified-dose antiepileptic regimens with reduced neurocognitive liability.
India
CDSCO's streamlined generic approval pathways support domestic manufacturing of first-line antiepileptic agents for cost-sensitive markets. Mumbai and Hyderabad host contract research organizations executing bioequivalence studies under BCS-based biowaiver restrictions. The country's specialized chemical manufacturers supply key raw materials for sodium channel blockers and GABA potentiation compounds to global formulators.
Antiepilepsy Drugs Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with established neurology franchises rather than pure-play neuropsychiatric specialists. Scale advantages in manufacturing and distribution dominate procurement decisions at hospital pharmacy and therapeutics committees. Three archetypes occupy distinct positions: broad-spectrum manufacturers supplying multiple dosage strengths, refractory epilepsy specialists concentrating R&D investment, and pediatric indication sponsors pursuing orphan exclusivity. Competitive dynamics center on strategic partnerships with tertiary epilepsy centers and portfolio diversification into gene-targeted small molecule platforms.
Within the diversified pharmaceutical tier, Novartis AG and Pfizer Inc. represent scale-driven positions anchored by manufacturing breadth across multiple therapeutic categories. UCB S.A. exemplifies the refractory specialization archetype through sustained investment in drug-resistant epilepsy mechanisms. Eisai Co., Ltd. occupies the pediatric-focused position, with its corporate structure reflecting concentrated expertise in developmental seizure disorder indications. These three entities collectively illustrate how competitive positioning in antiepileptic therapy requires alignment between manufacturing scale, R&D specialization, and regulatory strategy for orphan designation pathways.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| UCB S.A. |
| Johnson & Johnson |
| Eisai Co., Ltd. |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| Jazz Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap active pharmaceutical ingredient manufacturers in India and China anchor upstream supply for narrow therapeutic index antiepileptic compounds, translating concentrated ownership into disciplined contract pricing for downstream formulators seeking long-term offtake security.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs antiepileptic procurement, with differentiation driven by FDA bioequivalence certification status and volume scale commitments from integrated delivery networks. Pricing pressure stems from mandatory generic substitution policies at United States pharmacy benefit managers, compressing margins for non-specialized manufacturers. Tertiary epilepsy centers exhibit lowest price sensitivity due to protocol-driven formularies prioritizing efficacy data, while retail pharmacy channels serving stable ambulatory populations demonstrate highest sensitivity to out-of-pocket cost differentials.
Supply Chain Analysis
Cold-chain logistics costs for intravenous antiepileptic solutions and controlled-substance security protocols add substantial freight premiums to finished product distribution, particularly for hospital pharmacy deliveries requiring validated temperature documentation. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, drawing from specialized chemical intermediates for sodium channel blockers and GABA potentiation compounds. Single-source vulnerability persists for SV2A-binding kinetics precursors used in levetiracetam synthesis. Distribution runs through wholesale distributors serving academic medical centers and integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antiepilepsy drugs market represents a late-cycle quality story as tertiary epilepsy centers shift procurement criteria toward health economic evidence and real-world outcome data, elevating premium-tier agents with demonstrated functional benefit profiles.
For Market Incumbents: Acquire gene-targeted small molecule platform capabilities to defend against biologic entrants in refractory epilepsy segments. Secure backward integration into active pharmaceutical ingredient production for narrow therapeutic index compounds to mitigate single-source supply disruption. Expand manufacturing capacity in Baden-Württemberg's pharmaceutical corridor to serve EMA orphan designation pathways. For New Entrants and Emerging Players: Begin with pediatric orphan indication development to access extended exclusivity frameworks and protocol assistance from FDA and PMDA. Target United States tertiary epilepsy centers with direct-to-specialist distribution models bypassing traditional wholesale channels. Leverage closed-loop neurostimulation partnerships to establish presence in drug-resistant patient cohorts. For Investors and Strategic Acquirers: Valuations sit cheapest among diversified pharmaceutical conglomerates with underutilized neurology manufacturing infrastructure relative to refractory-specialist pure-plays commanding scarcity premiums. Five-to-ten year viability favors entities with demonstrated FDA accelerated approval pathway execution and pediatric trial infrastructure. Monitor EMA orphan medicine designation grant velocity as inflection signal for pipeline value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Targeted Small Molecule Platform Development | Creates differentiated mechanisms for drug-resistant epilepsy populations underserved by existing sodium channel blockers. |
| Pediatric Orphan Indication Expansion | Secures extended market exclusivity under FDA and EMA frameworks while accessing protocol assistance and fee reductions. |
| Direct-to-Specialist Distribution Buildout | Bypasses wholesale intermediaries to serve tertiary epilepsy centers with tighter inventory management and service differentiation. |
| Closed-Loop Neurostimulation Partnership | Positions pharmaceutical portfolios alongside implantable devices integrating machine learning for real-time seizure prediction. |
| Active Pharmaceutical Ingredient Backward Integration | Captures supply security for narrow therapeutic index compounds subject to BCS-based biowaiver restrictions and single-source risk. |
Study Parameters
Coverage spans the United States, Germany, Switzerland, Japan, and India, with primary inputs from each market's tertiary epilepsy centers and regulatory agencies. The analysis combines structured interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down therapeutic class revenue estimates undergo iterative triangulation to reconcile segmentation outputs.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon, with analytical frameworks modeling drug type, administration route, therapeutic class, and patient population dimensions alongside regional regulatory cluster variations. CAGRs derive from fitted growth curves applied to historical prescription trends and pipeline probability-adjusted revenue contributions. Forecast inputs incorporate FDA accelerated approval pathway success rates and EMA orphan designation grant patterns specific to neurological indications.
Several conditions sit outside the modeled scope, including unforeseen regulatory safety warnings requiring boxed label changes and geopolitical disruptions to active pharmaceutical ingredient trade flows. Forecasts reflect assumptions about continued reimbursement stability for orphan neurological indications and sustained tertiary center investment in epilepsy monitoring unit infrastructure. Stakeholders should weight assumptions against their own operating context and pharmacovigilance surveillance capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Contract Dose Manufacturing Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market