
 Asia-Pacific Adenomyosis Drugs Market | 2026-2036
Asia-Pacific Adenomyosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Adenomyosis Drugs Market Outlook
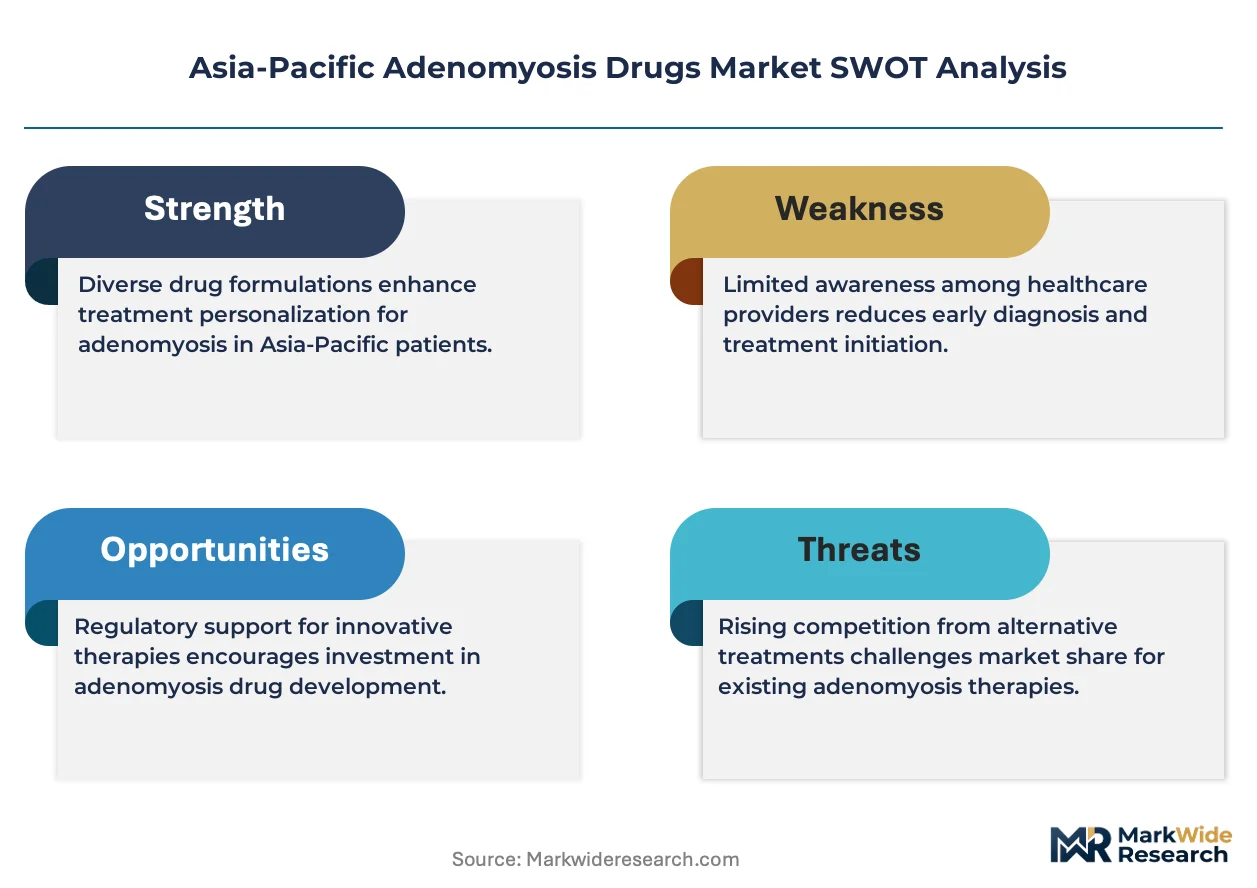
Japan's PMDA pharmacovigilance reforms for hormonal therapies is consolidating prescribing confidence among gynecologists across the region. AbbVie Inc. leverages its endometriosis franchise infrastructure to extend into adenomyosis indications. Bayer AG anchors its position through established oral contraceptive portfolios with proven adenomyosis off-label utilization. Pfizer Inc. competes via injectable formulation expertise developed across its broader women's health pipeline.
Adenomyosis drugs comprise pharmaceutical agents targeting ectopic endometrial tissue infiltration into the myometrium, primarily employing gonadotropin-releasing hormone agonists, progestins, and NSAIDs to modulate estrogen-driven proliferation and inflammatory pain signaling. Hormonal therapy dominates current prescribing patterns due to its disease-modifying effects on menstrual volume and pelvic pain, while pain relief medication captures acute episode management in outpatient and homecare settings where patients seek non-surgical alternatives.
Japan's PMDA, Australia's TGA, and South Korea's MFDS each enforce distinct bioequivalence and post-market surveillance requirements that shape product registration timelines and label expansion strategies for multinational sponsors. China's NMPA has tightened data localization mandates for clinical trials, compelling sponsors to establish domestic study infrastructure. Stakeholders must monitor evolving reimbursement negotiations across Australia's PBS, Japan's NHI price revisions, and China's volume-based procurement shifts to anticipate margin compression or access expansion.
Market Dynamics
Japan's PMDA pharmacovigilance reforms for hormonal therapies are consolidating prescribing confidence across Asia-Pacific, while China's NMPA data localization mandates force sponsors to build domestic clinical infrastructure rather than rely on foreign study networks.
Growth Catalysts
- GnRH Agonist Formulation Advances:Extended-release depot injections reduce injection frequency from monthly to quarterly, improving patient adherence in Australia's hospital outpatient settings.
- China's Tier-One Hospital Expansion:Dedicated endometriosis-adenomyosis treatment centers in Beijing and Shanghai concentrate specialist capacity and drive protocol standardization.
- PMDA Streamlined Reporting:Japan's reduced pharmacovigilance documentation requirements for established hormonal mechanisms accelerate supplemental indication approvals.
Market Restraints
- API Supply Concentration:Bulk hormone active pharmaceutical ingredients concentrate among Indian and Chinese contract manufacturers, exposing sponsors to single-source risk.
- Reimbursement Compression:Australia's PBS price revision cycles and China's volume-based procurement exert downward pressure on novel therapy margins before patent expiry.
- Diagnostic Underrecognition:Transvaginal ultrasound specificity limitations delay definitive adenomyosis diagnosis, restricting addressable patient pools to symptomatic severe cases.
Strategic Opportunities
- Southeast Asia Specialty Clinic Networks:Thailand and Vietnam gynecological service line expansions lack dedicated adenomyosis protocols, creating first-mover positioning for protocol sponsors.
- Digital Therapeutic Adjuncts:Pain-tracking applications paired with hormonal therapy are capturing patient-reported outcome data that supports label differentiation.
- MFDS Expedited Review Pathway:South Korea's fast-track designation for rare gynecological conditions offers twelve-month approval timelines for novel mechanisms.
Industry Challenges
- Specialist Sonographer Scarcity:Magnetic resonance imaging interpretation for adenomyosis staging requires radiology fellowship training unavailable outside Japan and Australia's tertiary centers.
- Legacy EHR Integration:Hospital information systems across China's provincial networks lack standardized fields for adenomyosis severity scoring, fragmenting real-world evidence collection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Adenomyosis Drugs Market |
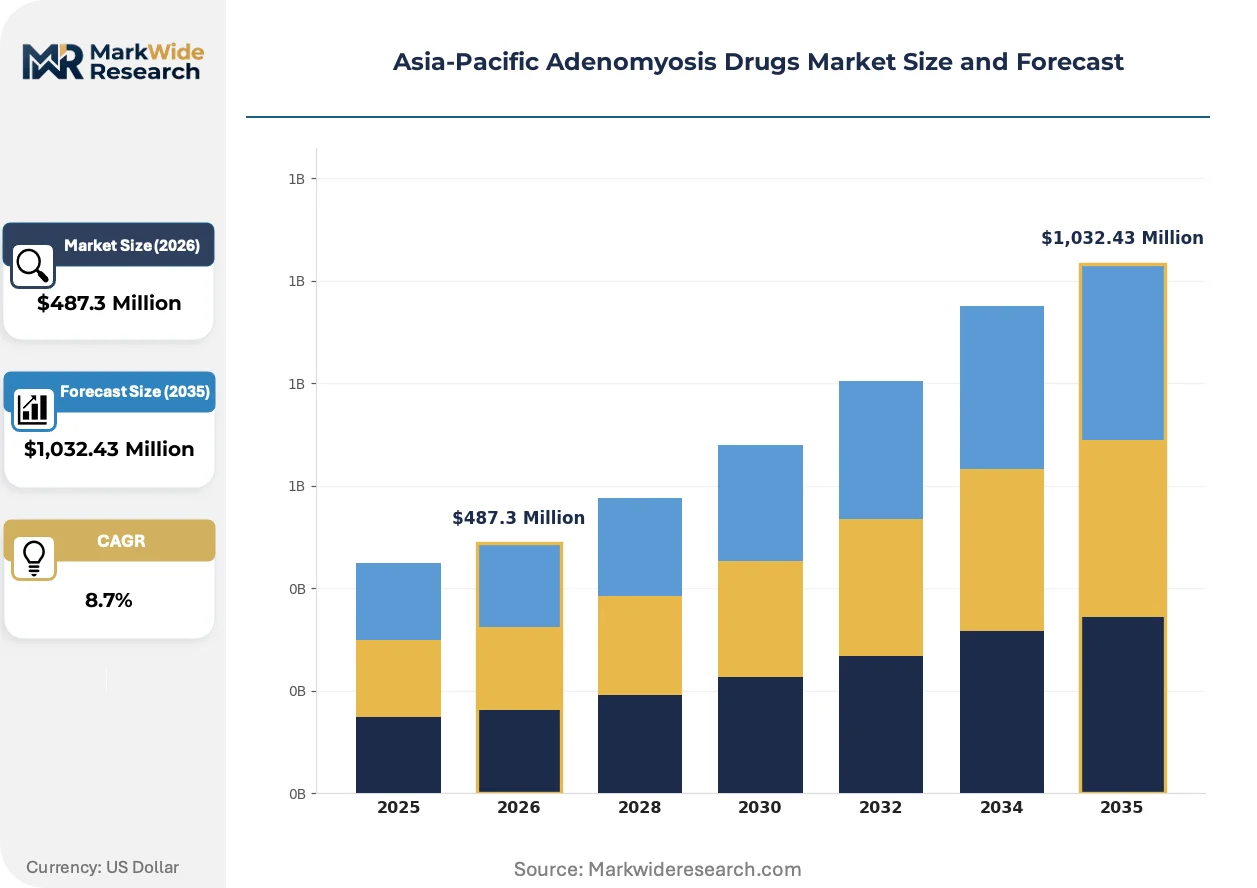
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Non-Hormonal Therapy, Pain Relief Medication, Surgical Options End User: Hospitals, Specialty Clinics, Outpatient Surgical Centers, Homecare Settings Delivery Mode: Oral, Injectable, Transdermal, Intranasal Application: Symptom Management, Disease Progression Prevention, Fertility Preservation, Pain Management |
| Companies Covered | Accord Healthcare, Tolmar Inc., Boehringer Ingelheim, AbbVie Inc., Pfizer Inc., Bayer AG, Teva Pharmaceutical Industries Ltd., Sanofi, Novartis AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Adenomyosis Drugs Market Strategic Shifts
Selective progesterone receptor modulator development is displacing legacy GnRH agonist dominance in Asia-Pacific prescribing protocols. Regulatory convergence around patient-reported outcome endpoints is reshaping trial design. Distribution through hospital-affiliated specialty pharmacies is consolidating channel control.
Artificial intelligence-assisted transvaginal ultrasound analysis is automating myometrial junction zone measurement that previously required specialist sonographer interpretation. Tertiary hospitals in Seoul and Tokyo are deploying these systems for routine screening. The technology is automating diagnostic standardization across facilities with uneven specialist density, compressing time-to-diagnosis variance between metropolitan and provincial centers.
PMDA's 2023 guidance on real-world evidence utilization for gynecological indications permits post-market surveillance data to support label expansion for hormonal therapies. Japanese sponsors are incorporating patient registry outcomes into supplemental new drug applications. This regulatory flexibility most affects progestin-class extensions where long-term safety databases already exist.
Patients in China's tier-one cities are migrating from hospital dispensing to internet hospital platforms with same-day delivery. Alibaba Health and JD Health are capturing chronic prescription refills for hormonal therapies through subscription models. This channel shift concentrates most visibly in Shanghai and Guangzhou, where 30-day refill automation reduces clinic visit burden for maintenance therapy patients.
Asia-Pacific Adenomyosis Drugs Market Segmentation
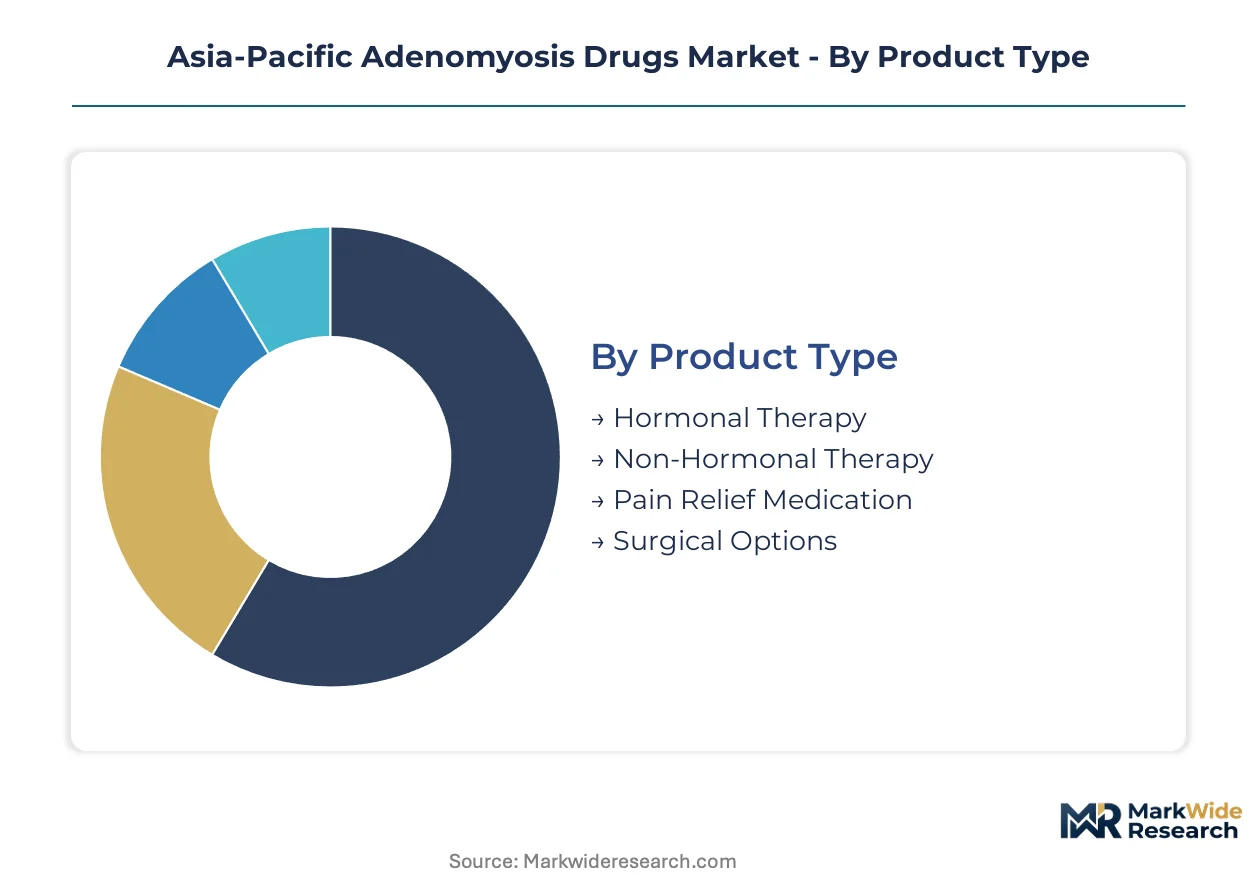
Adenomyosis treatment protocols diverge sharply across Asia-Pacific healthcare systems based on diagnostic capacity, reimbursement structures, and specialist availability. Segmentation reveals where pharmaceutical investment concentrates versus where unmet need persists.
Product Type:
Volume leadership sits with established hormonal mechanisms, while premium pricing attaches to novel non-hormonal alternatives addressing unmet safety profiles.
- Hormonal Therapy:GnRH agonists and progestins modulate estrogen-driven endometrial proliferation within the myometrium. China's tier-one hospital networks and Japan's NHI reimbursement system concentrate prescribing for these disease-modifying agents.
- Non-Hormonal Therapy:Selective progesterone receptor modulators and emerging anti-inflammatory mechanisms target patients contraindicated for estrogen suppression. Australia's TGA expedited pathways and South Korea's MFDS fast-track designations are accelerating access for these novel mechanisms in patients seeking fertility preservation.
- Pain Relief Medication:NSAIDs capture acute episode management in outpatient settings where patients defer hormonal initiation.
- Surgical Options:Pre-surgical pharmaceutical priming represents a discrete prescribing indication in Japan's tertiary centers.
Mature deployment sits with Hormonal Therapy. Newer deployment is concentrated in Non-Hormonal Therapy.
End User:
Channel configuration reflects Asia-Pacific's hospital-centric specialty care model, with divergent margin structures across institutional versus ambulatory settings.
- Hospitals:Tertiary medical centers in Beijing, Shanghai, Tokyo, and Seoul anchor complex adenomyosis management through dedicated endometriosis-adenomyosis treatment centers. China's NMPA volume-based procurement and Japan's NHI price revisions compress margins on chronic hormonal prescriptions.
- Specialty Clinics:Southeast Asia's expanding gynecological service lines in Thailand and Vietnam lack standardized adenomyosis protocols, creating first-mover positioning for protocol sponsors establishing referral networks.
- Outpatient Surgical Centers:Pre-operative pharmaceutical optimization occurs in Australia's day-surgery facilities integrated with hospital networks.
- Homecare Settings:China's internet hospital platforms—Alibaba Health and JD Health—are capturing maintenance therapy refills through subscription models with same-day delivery in Shanghai and Guangzhou.
Revenue concentration remains with Hospitals. Patient volume expansion is climbing fastest in Homecare Settings.
Delivery Mode:
Formulation innovation is reshaping adherence profiles, with extended-release technologies commanding premium positioning against conventional routes.
- Oral:Daily progestin tablets dominate maintenance therapy prescribing across China's provincial networks and Australia's PBS formulary.
- Injectable:Extended-release depot formulations reduce administration frequency from monthly to quarterly, improving adherence in Australia's hospital outpatient settings and Japan's clinic networks.
- Transdermal:Patch-based estrogen modulation offers alternative for patients with gastrointestinal intolerance, deployed in South Korea's dermatology-gynecology collaborative practices.
- Intranasal:Nasal spray GnRH antagonists represent emerging convenience positioning in Japan's PMDA review pipeline.
Injectable deployment is gaining share fastest through adherence advantages. Oral maintains volume leadership across price-sensitive markets.
Application:
Treatment intent stratifies prescribing patterns, with fertility-sparing protocols commanding specialized protocol development investment.
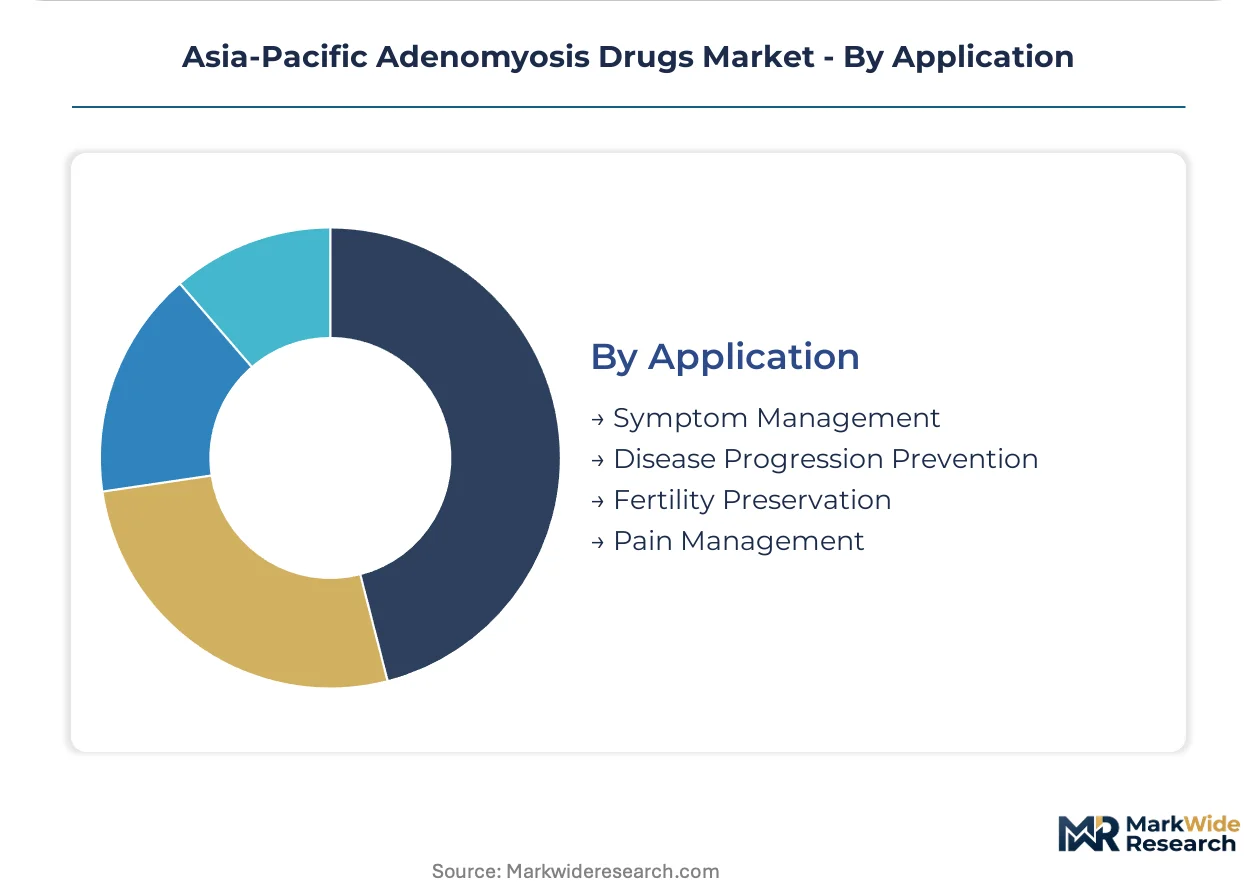
- Symptom Management:Menstrual volume reduction and pelvic pain control represent the dominant initial prescribing indication across Asia-Pacific gynecology practices.
- Disease Progression Prevention:Long-term hormonal suppression targets myometrial infiltration containment in Japan's aging patient demographics.
- Fertility Preservation:Pre-conception pharmaceutical optimization concentrates in China's tier-one reproductive medicine centers and South Korea's IVF-integrated gynecology practices.
- Pain Management:Acute episode protocols bridge to definitive therapy in Australia's emergency department referral pathways.
Symptom Management anchors current utilization. Fertility Preservation represents the steepest expansion trajectory as delayed childbearing patterns intensify across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors pharmaceutical demand concentration across the Asia-Pacific adenomyosis drugs market, with Beijing and Tokyo following as secondary prescription volume centers.
China
Tier-one hospital networks in Beijing and Shanghai are constructing dedicated endometriosis-adenomyosis treatment centers that concentrate specialist capacity. NMPA data localization mandates compel sponsors to establish domestic clinical trial infrastructure rather than rely on foreign study networks. Alibaba Health and JD Health subscription models in Shanghai and Guangzhou capture maintenance therapy refills through same-day delivery channels.
Japan
PMDA pharmacovigilance reforms for hormonal therapies accelerate supplemental indication approvals and consolidate prescribing confidence among gynecologists. Reduced documentation requirements for established hormonal mechanisms streamline product registration timelines. Tertiary centers in Tokyo deploy artificial intelligence-assisted transvaginal ultrasound systems for routine adenomyosis screening.
Australia
Extended-release depot injections reduce administration frequency in hospital outpatient settings, improving patient adherence profiles. PBS price revision cycles exert downward pressure on novel therapy margins before patent expiry. Day-surgery facilities in Sydney and Melbourne integrate pre-operative pharmaceutical optimization into hospital network referral pathways.
South Korea
MFDS fast-track designation for rare gynecological conditions offers twelve-month approval timelines for novel mechanisms targeting fertility preservation. Seoul's tertiary hospitals lead artificial intelligence-assisted diagnostic deployment for myometrial junction zone measurement. IVF-integrated gynecology practices in the capital region concentrate pre-conception pharmaceutical optimization demand.
Southeast Asia
Thailand and Vietnam specialty clinic expansions lack standardized adenomyosis protocols, creating first-mover positioning for protocol sponsors establishing referral networks. Diagnostic underrecognition due to transvaginal ultrasound specificity limitations restricts addressable patient pools to symptomatic severe cases. Bangkok and Ho Chi Minh City gynecological service lines represent priority expansion targets for hormonal therapy sponsors.
Asia-Pacific Adenomyosis Drugs Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory sophistication. The market structures around three tiers: multinational pharmaceutical conglomerates with established women's health franchises, regional generic manufacturers with API supply advantages, and emerging biotech specialists pursuing novel mechanisms. Consolidation pressure intensifies as volume-based procurement and national price revisions compress margins on legacy hormonal therapies. Dominant competitive moves include strategic partnerships with diagnostic technology developers and geographic expansion through specialty clinic network agreements.
Among multinational pharmaceutical conglomerates, AbbVie Inc., Bayer AG, and Pfizer Inc. occupy anchor positions across the hormonal therapy landscape. AbbVie leverages endometriosis franchise infrastructure to extend into adenomyosis indications. Bayer AG maintains positioning through established oral contraceptive portfolios with proven off-label utilization patterns. Pfizer Inc. competes via injectable formulation expertise developed across broader women's health pipeline investments. These three exemplify the premium-tier archetype where regulatory sophistication and formulation R&D capabilities create defensive positioning against generic erosion.
| Leading Market Players |
|---|
| Accord Healthcare |
| Tolmar Inc. |
| Boehringer Ingelheim |
| AbbVie Inc. |
| Pfizer Inc. |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Specialist sonographer concentration in Japan and Australia establishes labor-cost differentials that widen pricing-tier spreads between metropolitan diagnostic centers and provincial facilities dependent on generalist interpretation. NMPA data localization mandates in China add domestic clinical infrastructure costs that sponsors recover through premium positioning in tier-one hospital networks.
Pricing Analysis
Value-based pricing anchors on disease-modifying outcomes measured through menstrual volume reduction and pain score improvements. Three-tier pricing structure across premium, standard, and economy levels separates novel non-hormonal mechanisms from established GnRH agonists and generic progestins. Cost compression in China's volume-based procurement tier is intensifying because NMPA mandates force local trial investment before market access. Homecare subscription models through Alibaba Health and JD Health exhibit highest price sensitivity, while fertility-preservation protocols in Seoul and Tokyo IVF centers show lowest elasticity.
Supply Chain Analysis
Bulk hormone API supply rests on Indian and Chinese contract manufacturers, with secondary sourcing from European specialty chemical producers. GnRH agonist peptide precursors, progestin synthetic intermediates, and extended-release polymer matrices constitute critical input dependencies. Single-source vulnerability concentrates in high-potency hormone API production where regulatory qualification timelines deter supplier switching. Distribution runs through hospital-affiliated specialty pharmacies in Japan and Australia, while China's internet hospital platforms are capturing last-mile delivery for maintenance therapy refills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where PMDA pharmacovigilance reforms and NMPA data localization mandates erect barrier-to-entry moats favoring sponsors with established regional regulatory infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into API manufacturing to offset Indian and Chinese contract manufacturer concentration risk. Expand diagnostic technology partnerships with AI-assisted ultrasound developers to capture referral network control before provincial hospital adoption accelerates. Volume-based procurement in China and PBS price revisions in Australia threaten margin sustainability on legacy hormonal portfolios. For New Entrants and Emerging Players: MFDS fast-track designation in South Korea opens a window for novel mechanism sponsors targeting fertility preservation indications with twelve-month approval timelines. Southeast Asia specialty clinic networks in Thailand and Vietnam present penetrable white-space where standardized adenomyosis protocols remain undeveloped. Deploy digital therapeutic adjuncts with pain-tracking applications to differentiate through patient-reported outcome data collection supporting label expansion. For Investors and Strategic Acquirers: Re-rating potential sits with emerging biotech specialists possessing novel non-hormonal mechanisms given MFDS and TGA expedited pathway catalysts accelerating time-to-revenue across the analysis window. Target acquisition archetypes include regional generic manufacturers with API supply advantages seeking formulation R&D capabilities. Watch PMDA real-world evidence guidance implementation as inflection indicator for progestin-class extension valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | MFDS fast-track designation compresses twelve-month timelines for novel mechanisms in Seoul. |
| Diagnostic Technology Partnership | AI-assisted ultrasound alliances with Tokyo tertiary hospitals standardize staging protocols. |
| Manufacturing Scale-Up | Extended-release depot capacity expansion serves Australia's quarterly injection adherence gains. |
| Digital Therapeutic Development | Pain-tracking application integration captures patient-reported outcomes for PMDA label differentiation. |
| Geographic Expansion | Specialty clinic network agreements in Bangkok and Ho Chi Minh City establish first-mover protocols. |
Study Parameters
Document review covered PMDA regulatory filings, NMPA clinical trial registrations, PBS formulary databases, and MFDS approval records, complemented by interviews with drug development executives at multinational sponsors, regulatory affairs leads navigating Asia-Pacific submission pathways, hospital procurement managers in China's tier-one networks, and payer access specialists advising on reimbursement strategy. Secondary validation drew from ClinicalTrials.gov protocol disclosures, Japan's NHI price revision bulletins, Australia's TGA safety updates, and customs trade data on hormone API flows. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Historical prescription volume trajectories cross-referenced against expert panel input on protocol adoption curves shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled encompassed treatment line, hormonal versus non-hormonal mechanism, delivery mode, end-user channel configuration, and regional regulatory cluster. CAGRs derived from fitted adoption curves applied to diagnosed patient prevalence estimates, with fertility preservation demand intensity and diagnostic AI deployment pace serving as key forecast sensitivity inputs.
Caveats apply where reimbursement negotiation outcomes, diagnostic technology diffusion rates, or API supply disruptions could materially shift the outlook. Forecasts reflect assumptions on regulatory pathway stability and specialist training pipeline adequacy. A small set of named triggers—PMDA real-world evidence guidance expansion, NMPA volume-based procurement scope extension, and transvaginal ultrasound AI validation studies—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Non-Sterile Liquids/Suspensions Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Unit Dose Manufacturing Market