
 Global Shingles Vaccine Market | 2026-2036
Global Shingles Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shingles Vaccine Market Foresight
The gap between institutional procurement and retail pharmacy demand is collapsing as government immunization programs absorb larger vaccine volumes. GlaxoSmithKline plc. leverages its recombinant subunit expertise to dominate supply contracts with national health services. Merck & Co., Inc. sustains manufacturing scale for live attenuated alternatives in markets with cost-sensitive procurement frameworks. SK bioscience competes through geographic concentration in Asia-Pacific manufacturing clusters.
Shingles vaccines are biologic preparations designed to induce varicella-zoster virus-specific immunity, with recombinant subunit formulations containing glycoprotein E combined with AS01B adjuvant systems that amplify cellular immune responses in older adults. Their primary purpose is preventing herpes zoster reactivation and postherpetic neuralgia in individuals aged fifty years and above. Recombinant subunit vaccines command premium positioning due to superior efficacy profiles in immunosenescent populations, while live attenuated alternatives retain residual demand in cost-constrained distribution channels. Hospital pharmacies function as the dominant fulfillment node for institutional contracts, whereas retail and online channels serve residual private-pay segments with limited reimbursement penetration.
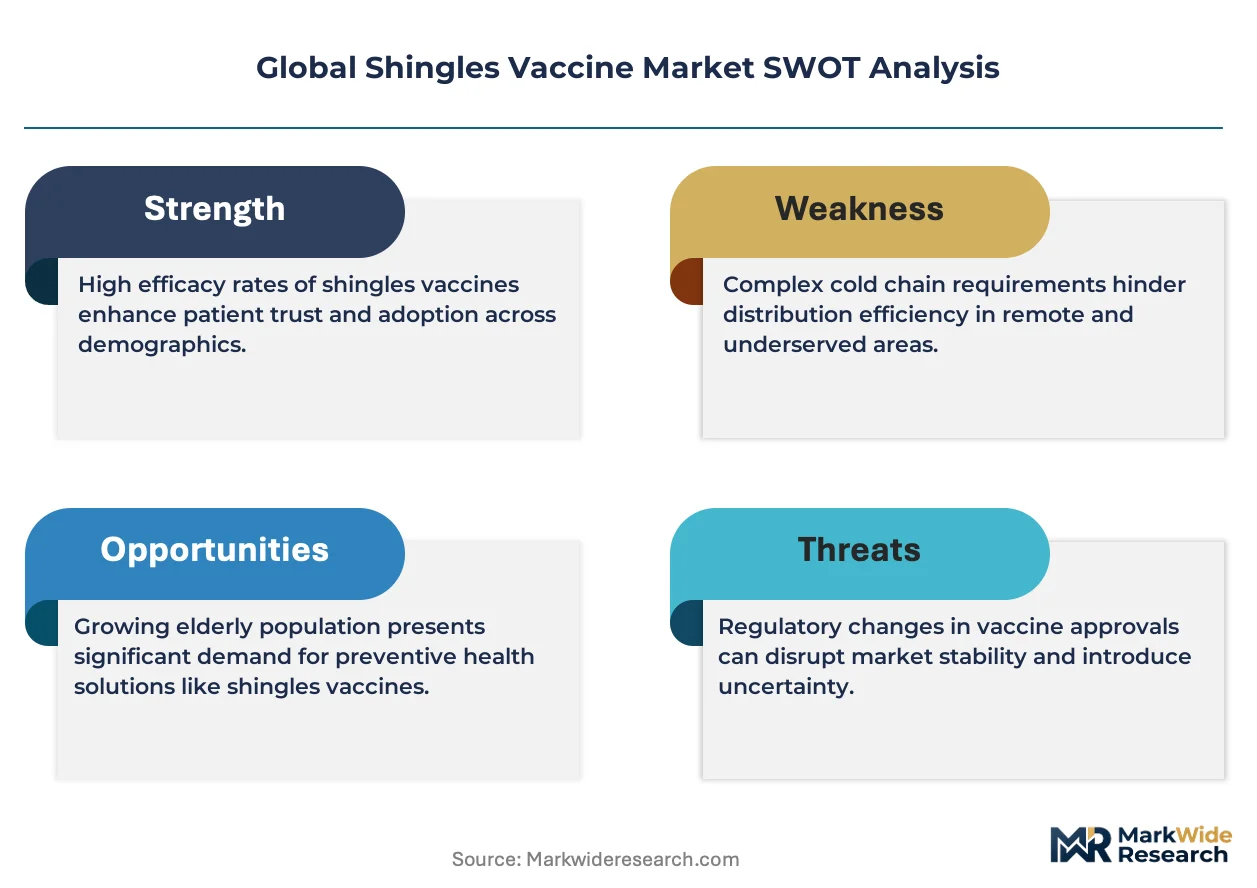
FDA biologics licensing requirements and EMA's Good Manufacturing Practice standards for adjuvanted vaccines shape product development timelines and facility qualification costs across manufacturing networks. The EU Green Deal's sustainable pharmaceutical production directives are forcing supply chain recalibration for single-use bioreactor systems and cold-chain logistics. WHO prequalification pathways determine access to government immunization programs in lower-income markets. Stakeholders must monitor adjuvant raw material sourcing constraints and evolving national reimbursement thresholds for adult immunization.
Market Dynamics
Recombinant subunit technology is fragmenting procurement patterns as national health services rewrite immunization schedules around superior efficacy data in aging populations. This platform shift collapses legacy supply relationships and forces manufacturing network requalification across three continents.
Growth Catalysts
- EMA adjuvanted vaccine GMP standards:These protocols accelerate facility qualification timelines for recombinant subunit production, compressing time-to-market for next-generation formulations.
- Hospital pharmacy consolidation:Centralized procurement by integrated health systems concentrates volume commitments and locks in multi-year supply agreements with preferred manufacturers.
- AS01B adjuvant systems:This immunostimulant complex amplifies cellular responses in immunosenescent patients, expanding addressable populations beyond prior age-restricted indications.
Market Restraints
- QS-21 saponin supply concentration:Botanical extraction of this critical adjuvant raw material depends on Chilean soapbark harvest cycles, creating input cost volatility and qualification bottlenecks.
- Cold-chain infrastructure gaps:Last-mile distribution in tropical climates lacks validated 2-8°C maintenance capacity, limiting program expansion in lower-income markets.
- WHO prequalification timelines:Extended review pathways for novel adjuvanted biologics delay access to government immunization programs in procurement-dependent regions.
Strategic Opportunities
- Japan's geriatric immunization subsidy expansion:METI-aligned prefectural programs are extending reimbursement to 50-64 age brackets, opening new volume pools beyond traditional 65+ targeting.
- Retail pharmacy channel integration:Vaccination-certified community pharmacies in Germany are capturing residual private-pay demand outside institutional procurement frameworks.
- mRNA platform convergence:Combination with synthetic antigen delivery systems offers potential for rapid strain-adaptable manufacturing responses.
Industry Challenges
- Bioreactor operator skill scarcity:Single-use system qualification and perfusion culture management require specialized training programs that outpace current workforce development pipelines.
- Legacy cold-chain asset stranding:Existing -20°C distribution infrastructure faces devaluation as 2-8°C formulations dominate new product pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shingles Vaccine Market |
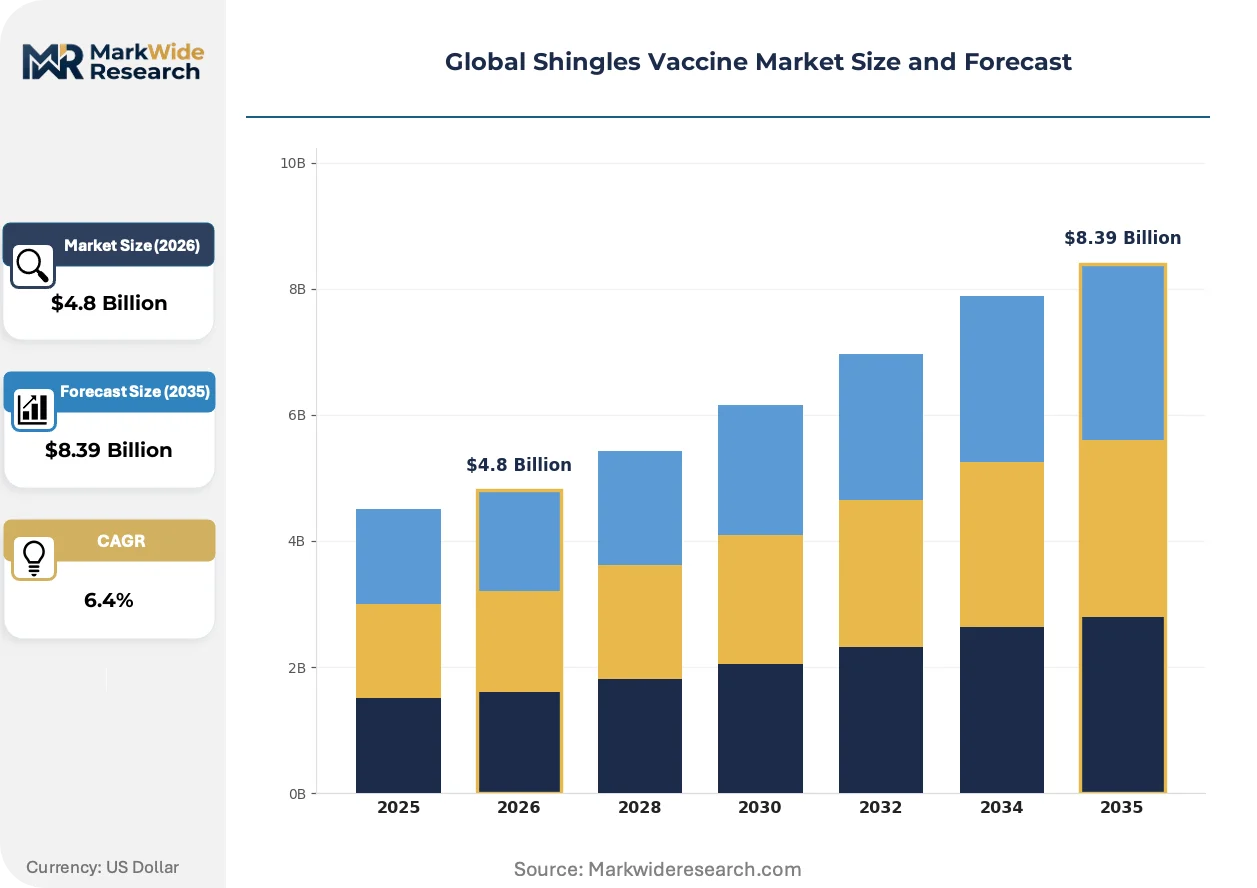
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated Vaccines, Recombinant Subunit Vaccines, DNA Vaccines, Inactivated Vaccines Application: Postherpetic Neuralgia Prevention, Acute Shingles Treatment, Immunocompromised Patient Care, Geriatric Immunization End User: Hospitals, Specialty Clinics, Pharmacies, Geriatric Care Facilities Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Government Immunization Programs |
| Companies Covered | GlaxoSmithKline plc., Merck & Co., Inc., Pfizer Inc., CanSinoBIO, Vaccitech, Green Cross Corp, GeneOne Life Science, SK bioscience, Moderna Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shingles Vaccine Market Shifts & Advancements
Platform diversification is compressing technology cycles as manufacturers hedge between established recombinant methods and emerging synthetic biology approaches. This acceleration forces parallel investment in incompatible production assets.
Adjuvant formulation science is fragmenting competitive positioning as second-generation immunostimulants challenge AS01B dominance. Regional health authorities in Germany and Japan are prioritizing head-to-head immunogenicity data in tender evaluations. This scrutiny compresses margin structures for products lacking differentiated cellular response profiles.
The EU Green Deal's sustainable pharmaceutical production directives are mandating carbon footprint disclosures for single-use bioreactor consumables. EMA's updated environmental risk assessment frameworks now require lifecycle analysis submissions for adjuvanted vaccine approvals. German manufacturing clusters are responding with closed-loop solvent recovery systems and renewable energy procurement commitments.
Pharmacy-administered vaccination is displacing physician-office delivery in United States commercial channels. Large retail chains are deploying standing-order protocols that bypass traditional prescription requirements. This channel shift concentrates volume with formulary-managed procurement teams rather than individual provider preference.
Global Shingles Vaccine Market Segmentation
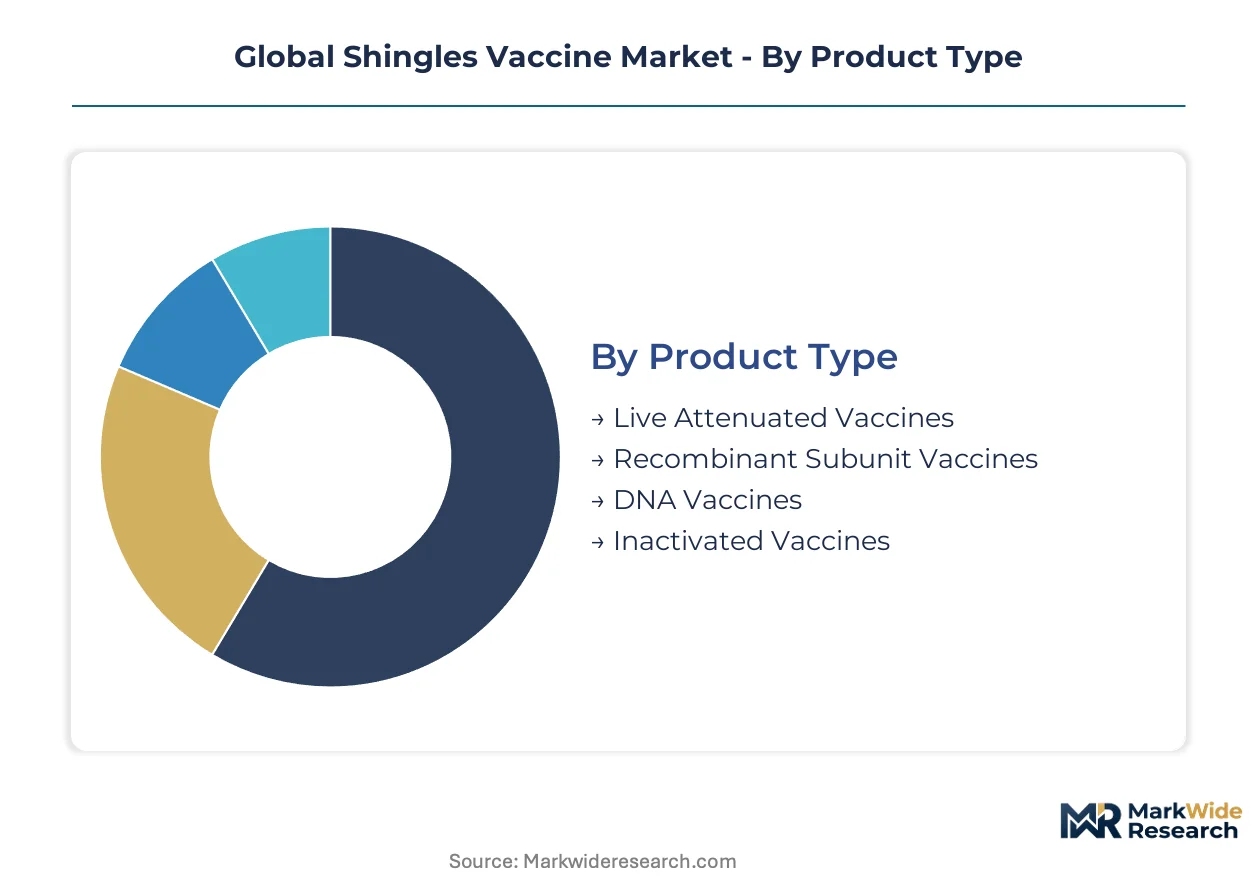
Segmentation in the shingles vaccine market reveals how procurement concentration and clinical indication specificity reshape competitive positioning. Technology platforms, patient risk profiles, and fulfillment infrastructure each generate distinct margin architectures that manufacturers must navigate simultaneously.
Product Type:
Margin pools concentrate heavily where adjuvant sophistication commands premium pricing in aging populations.
- Recombinant Subunit Vaccines:Glycoprotein E antigens combined with AS01B adjuvant systems deliver superior cellular immunity in immunosenescent patients. Procurement in Japan, Germany, and the United States now prioritizes these formulations for expanded geriatric indications, displacing legacy alternatives through national tender processes.
- Live Attenuated Vaccines:Oka strain-based formulations retain manufacturing scale advantages and established cold-chain compatibility. Demand persists in cost-sensitive procurement frameworks where single-dose regimens and storage flexibility outweigh efficacy differentials.
- DNA Vaccines:Synthetic antigen platforms enable rapid strain adaptation without cell culture dependencies.
- Inactivated Vaccines:Heat-killed formulations serve niche applications where live virus contraindications apply.
The dominant share belongs to recombinant subunit vaccines, while DNA platforms are gaining share fastest through synthetic biology investment cycles.
Application:
Volume concentration tracks directly to reimbursement expansion for preventive indications versus reactive treatment protocols.
- Geriatric Immunization:Population-scale prevention programs targeting adults aged fifty and above now absorb the majority of procurement volumes. Japan's METI-aligned prefectural subsidies and German statutory health insurance expansions are extending eligibility to younger age brackets, amplifying addressable populations.
- Postherpetic Neuralgia Prevention:Clinical focus on neuropathic pain avoidance drives preferential formulary placement for high-efficacy adjuvanted products. Hospital pharmacy procurement in the United States weights total cost-of-care reductions heavily in therapeutic equivalency evaluations.
- Acute Shingles Treatment:Therapeutic vaccination protocols remain limited to specialized immunology centers.
- Immunocompromised Patient Care:Recombinant platforms bypass safety constraints that restrict live attenuated alternatives in oncology and transplant populations.
Geriatric immunization commands the dominant share, though postherpetic neuralgia prevention is climbing the fastest as value-based contracting matures.
End User:
Customer type segmentation exposes a structural shift from physician-administered delivery toward pharmacy-certified vaccination infrastructure.
- Hospitals:Integrated health systems centralize procurement through formulary committees, locking in multi-year supply agreements with preferred manufacturers. EMA GMP qualification requirements and FDA biologics licensing standards shape vendor selection criteria.
- Pharmacies:Standing-order protocols in United States retail chains and German community pharmacy networks bypass traditional prescription requirements, concentrating residual private-pay demand outside institutional frameworks.
- Specialty Clinics:Immunology and infectious disease centers manage complex patient stratification.
- Geriatric Care Facilities:On-site vaccination programs reduce transportation barriers for mobility-limited populations.
Hospital procurement holds the dominant share, while pharmacy channels are expanding most quickly through regulatory streamlining.
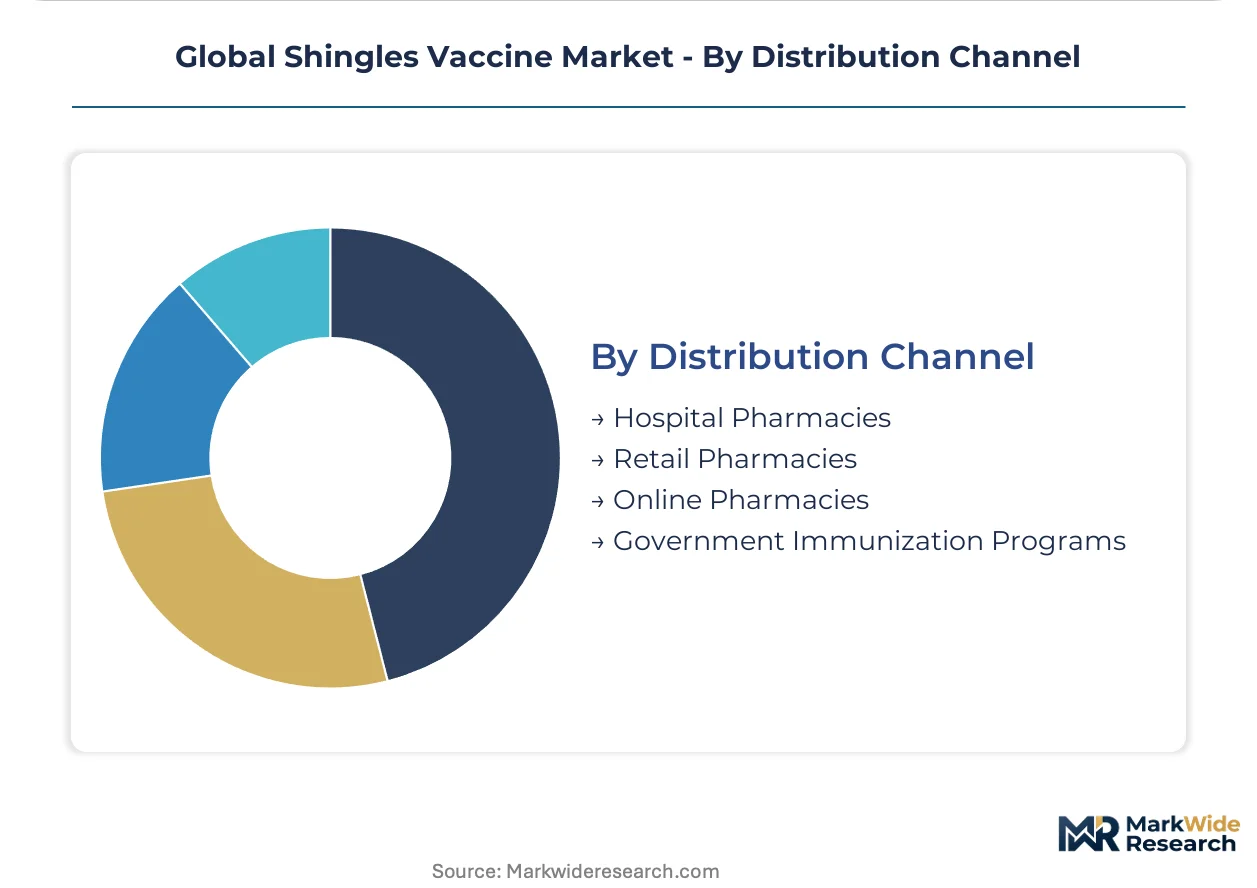
Distribution Channel:
Fulfillment pathway selection increasingly determines product accessibility and margin capture across reimbursement environments.
- Government Immunization Programs:National health services in Japan, Germany, and the United States now absorb the majority of volume through centralized tender mechanisms. WHO prequalification pathways determine access to procurement-dependent regions, though extended review timelines delay market entry for novel adjuvanted formulations.
- Hospital Pharmacies:Institutional fulfillment nodes manage cold-chain integrity for temperature-sensitive biologics, with 2-8°C validated storage replacing legacy -20°C infrastructure.
- Retail Pharmacies:Private-pay segments with limited reimbursement penetration depend on community accessibility and patient out-of-pocket willingness.
- Online Pharmacies:Digital fulfillment remains constrained by cold-chain last-mile capabilities and prescription verification requirements.
Government immunization programs dominate volume allocation, with hospital pharmacies representing the steepest expansion trajectory as integrated delivery networks consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cold-chain logistics networks connecting Rotterdam, Hamburg, and Singapore anchor vaccine distribution across three continents. These maritime hubs validate temperature integrity for adjuvanted biologics moving between manufacturing clusters and immunization programs.
United States
Medicare Part D reimbursement expansion drives procurement volumes for adults aged fifty-plus. FDA biologics licensing requirements shape vendor qualification timelines for recombinant subunit production. The Research Triangle Park cluster in North Carolina concentrates formulation science expertise for next-generation adjuvant development.
Germany
Statutory health insurance expansions extend shingles vaccine eligibility to younger age brackets. EMA Good Manufacturing Practice standards for adjuvanted vaccines accelerate facility qualification timelines. The Rhine-Main biotech corridor around Frankfurt hosts multiple fill-finish operations serving European immunization programs.
Japan
METI-aligned prefectural subsidies accelerate geriatric immunization program scale-up. PMDA regulatory pathways prioritize head-to-head immunogenicity data in tender evaluations. The Kansai manufacturing belt around Osaka concentrates domestic fill-finish capacity for recombinant subunit formulations.
United Kingdom
NHS England centralized procurement absorbs volume through multi-year supply agreements with preferred manufacturers. MHRA post-Brexit regulatory autonomy creates parallel qualification pathways distinct from EMA procedures. The Oxford-Cambridge biotech arc anchors adjuvant research partnerships between academic and commercial entities.
South Korea
MFDS accelerated review pathways for novel adjuvanted biologics compress time-to-market for domestic manufacturers. Government immunization program procurement concentrates volume through national tender mechanisms. The Songdo biotech cluster near Incheon hosts contract manufacturing organizations serving Asia-Pacific distribution networks.
Global Shingles Vaccine Market Competitive Landscape
Listed leaders compete with private specialists across technology platform diversification and geographic coverage. The vendor base consolidates around recombinant subunit expertise while live attenuated alternatives retain residual manufacturing scale. Three archetypes dominate: multinational pharmaceutical conglomerates with integrated biologics divisions, regional vaccine specialists with concentrated geographic presence, and emerging platform technology developers pursuing synthetic biology approaches. Competitive dynamics center on M&A activity targeting adjuvant formulation capabilities and strategic partnerships securing raw material supply chains.
Within the multinational tier, GlaxoSmithKline plc. and Merck & Co., Inc. exemplify divergent platform strategies—one anchoring recombinant subunit dominance, the other sustaining live attenuated manufacturing scale. SK bioscience occupies a position representing Asia-Pacific geographic concentration in contract manufacturing and regional supply relationships.
| Leading Market Players |
|---|
| GlaxoSmithKline plc. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| CanSinoBIO |
| Vaccitech |
| Green Cross Corp |
| GeneOne Life Science |
| SK bioscience |
| Moderna Inc. |
| Others |
Supply & Pricing Matrix
FDA biologics licensing requirements and EMA Good Manufacturing Practice standards for adjuvanted vaccines simultaneously gate supply qualification timelines and price differentiation between recombinant subunit and live attenuated formulations. This dual-gating mechanism concentrates premium pricing power with manufacturers holding validated AS01B adjuvant production capabilities while cost-sensitive procurement frameworks sustain residual demand for legacy alternatives.
Pricing Analysis
Volume-discount tiering structures dominate government immunization program procurement, with national health services extracting scaled commitments for expanded geriatric indications. Price differentiation rests on AS01B adjuvant sophistication and cold-chain validation certification tiers, separating premium recombinant subunit positioning from standard live attenuated alternatives. Cost compression in the live attenuated segment is intensifying as tender evaluations weight head-to-head immunogenicity data more heavily. Hospital pharmacy procurement teams demonstrate lowest price sensitivity due to total cost-of-care contracting frameworks, while retail pharmacy private-pay segments exhibit highest sensitivity to out-of-pocket exposure.
Supply Chain Analysis
Chile and the United States anchor QS-21 saponin extraction and adjuvant formulation science respectively, with Belgian fill-finish operations completing the recombinant subunit production triangle. Raw material dependencies center on Chilean soapbark harvest cycles, synthetic lipid nanoparticle stocks, and single-use bioreactor consumables. Single-source vulnerability in botanical adjuvant inputs creates qualification bottlenecks when harvest yields fluctuate. Distribution runs through validated 2-8°C cold-chain networks connecting Rotterdam, Singapore, and Memphis hub operations to institutional pharmacy nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA platform convergence threatens incumbent recombinant subunit positioning as synthetic antigen delivery systems enable rapid strain-adaptable manufacturing responses with potentially simplified supply chains.
For Market Incumbents: Secure captive supply of QS-21 saponin through long-term offtake agreements with Chilean extraction operations to defend against input cost volatility. Expand backward integration into AS01B adjuvant formulation capacity in the Research Triangle Park cluster to maintain premium positioning against emerging mRNA substitutes. For New Entrants and Emerging Players: MFDS accelerated review pathways in South Korea offer fastest regulatory entry for novel adjuvanted biologics seeking Asia-Pacific market access. Target immunocompromised patient care segments where live attenuated contraindications create unmet need, deploying hospital pharmacy direct contracting as the primary go-to-market angle. For Investors and Strategic Acquirers: WHO prequalification pathway streamlining reshapes the acquisition landscape toward assets with emerging market government program eligibility. Five-to-ten year viability favors contract manufacturing organizations with validated adjuvant formulation capabilities and geographic concentration in Asia-Pacific manufacturing clusters. Watch for EMA environmental risk assessment framework updates as the signal indicating sustainable production asset revaluation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | WHO prequalification unlocks government immunization program procurement in procurement-dependent regions. |
| Manufacturing Scale-Up | Single-use bioreactor qualification in the Kansai belt addresses Japanese METI-aligned prefectural subsidy expansion. |
| Backward Integration | Captive QS-21 saponin sourcing mitigates Chilean soapbark harvest cycle volatility for AS01B production. |
| Strategic Partnership | Hospital pharmacy standing-order protocols in German community networks bypass prescription requirement friction. |
| Pipeline Diversification | mRNA platform convergence hedges against recombinant subunit technology displacement risk in tender evaluations. |
Research Methodology
Desk research of FDA biologics licensing filings, EMA GMP inspection reports, and ClinicalTrials.gov protocol registries preceded structured interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists. Secondary validation drew from WHO prequalification status databases, national immunization program tender documents, and customs trade data on adjuvant raw material flows. Bottom-up patient population modeling and top-down procurement volume aggregation enabled cross-verification.
Variance decomposition across technology platform, patient risk profile, and fulfillment infrastructure dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectory modeling incorporating reimbursement expansion schedules, regulatory approval timelines, and manufacturing capacity commissioning patterns. Forecast inputs included geriatric demographic projections, adjuvant raw material supply elasticity estimates, and cold-chain infrastructure investment pipelines.
Underlying assumptions cover sustained Medicare Part D reimbursement expansion, EMA environmental risk assessment stability, and Chilean soapbark harvest yield consistency, with deviation risk concentrated in WHO prequalification timeline extensions and mRNA platform clinical validation acceleration. Recalibration cycles align with material shifts in national immunization schedule updates and adjuvant formulation science breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Depression Drugs Market