
 Canada Specialty Pharmacy Market | 2026-2036
Canada Specialty Pharmacy Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Specialty Pharmacy Market Outlook
Market Context
A capital-intensity divergence between centralized distribution hubs and community-based specialty networks is unwinding competitive assumptions across Canada. McKesson Canada leverages its national cold-chain infrastructure to anchor hospital and homecare contracts. Shoppers Drug Mart Specialty Health Network differentiates through its integrated telehealth and patient-support platform. Bayshore HealthCare competes via clinical-services depth in oncology and rare-disease categories.
Technical Definition and Segments
Specialty pharmacy encompasses the dispensing, management, and clinical monitoring of high-cost, complex medications—typically biologics requiring refrigeration between 2°C and 8°C, sterile compounding, or patient-specific dosing protocols—serving populations with chronic, rare, or life-threatening conditions. Injectable therapies command premium margin pools due to administration complexity and reimbursement navigation requirements, while biologics represent the fastest-growing product type under Health Canada's biosimilar transition framework. Telehealth solutions are displacing traditional intake models, with EHR integration becoming a baseline expectation among hospital and clinic purchasers.
Regulatory Framework
Health Canada, the Patented Medicine Prices Review Board, and provincial formularies collectively shape market access, pricing ceilings, and biologics substitution rules across Canadian jurisdictions. The PMPRB's amended pricing guidelines force manufacturers and pharmacies to restructure rebate and patient-assistance programs. Stakeholders must monitor provincial biosimilar switching policies and Health Canada's evolving digital-health guidance to anticipate reimbursement and channel shifts.
Market Dynamics
Oncology infusion centers across Ontario and British Columbia are consolidating their specialty pharmacy partnerships around vendors with integrated cold-chain logistics and EHR connectivity, compressing the competitive set for hospital and homecare contracts.
Growth Catalysts
- Health Canada Biosimilar Transition Framework:Provincial switching policies in Ontario and British Columbia accelerate biologics substitution, expanding dispensing volumes for pharmacies with clinical-monitoring capabilities.
- Telehealth Platform Integration:Virtual intake and adherence-monitoring systems reduce patient dropout rates in remote and rural jurisdictions, extending specialty pharmacy reach beyond urban hospital corridors.
- Ontario Greater Toronto Area Demand Concentration:Population density and tertiary-care hospital clustering generate patient volumes sufficient to justify centralized compounding and same-day delivery infrastructure.
Market Restraints
- Patented Medicine Prices Review Board Pricing Ceilings:The PMPRB's amended guidelines compress manufacturer rebate pools, constraining pharmacy margin on high-cost biologics and forcing restructuring of patient-assistance programs.
- Refrigerated Distribution Infrastructure Concentration:Cold-chain compliance requirements limit viable third-party logistics partners to McKesson Canada and two regional operators, creating single-source vulnerability for temperature-sensitive injectables.
- Provincial Formulary Fragmentation:Non-uniform reimbursement criteria across Quebec, Ontario, and Western provinces force pharmacies to maintain jurisdiction-specific prior-authorization workflows, elevating administrative cost per prescription.
Strategic Opportunities
- Atlantic Canada Geographic White Space:Nova Scotia and New Brunswick lack dedicated specialty pharmacy networks, presenting first-mover advantage for operators with mobile nursing and home-infusion capabilities.
- Health Canada Digital Health Guidance Evolution:Anticipated regulatory clarity on remote therapeutic monitoring and e-prescribing validation creates pathway for fully virtual specialty pharmacy models in rural Quebec and Manitoba.
- Oncology-Immunology Convergence:Combination therapies requiring simultaneous biologic dispensing and immune-monitoring create demand for pharmacies with in-house clinical-trial coordination and biomarker logistics.
Industry Challenges
- Sterile Compounding Certification Bottlenecks:Health Canada's updated GMP standards for hazardous drug handling extend facility accreditation timelines, delaying revenue recognition for new market entrants.
- EHR Integration Complexity:Provincial health information exchanges operate on non-interoperable data standards, forcing pharmacies to maintain multiple API connections for hospital and clinic referral networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Specialty Pharmacy Market |
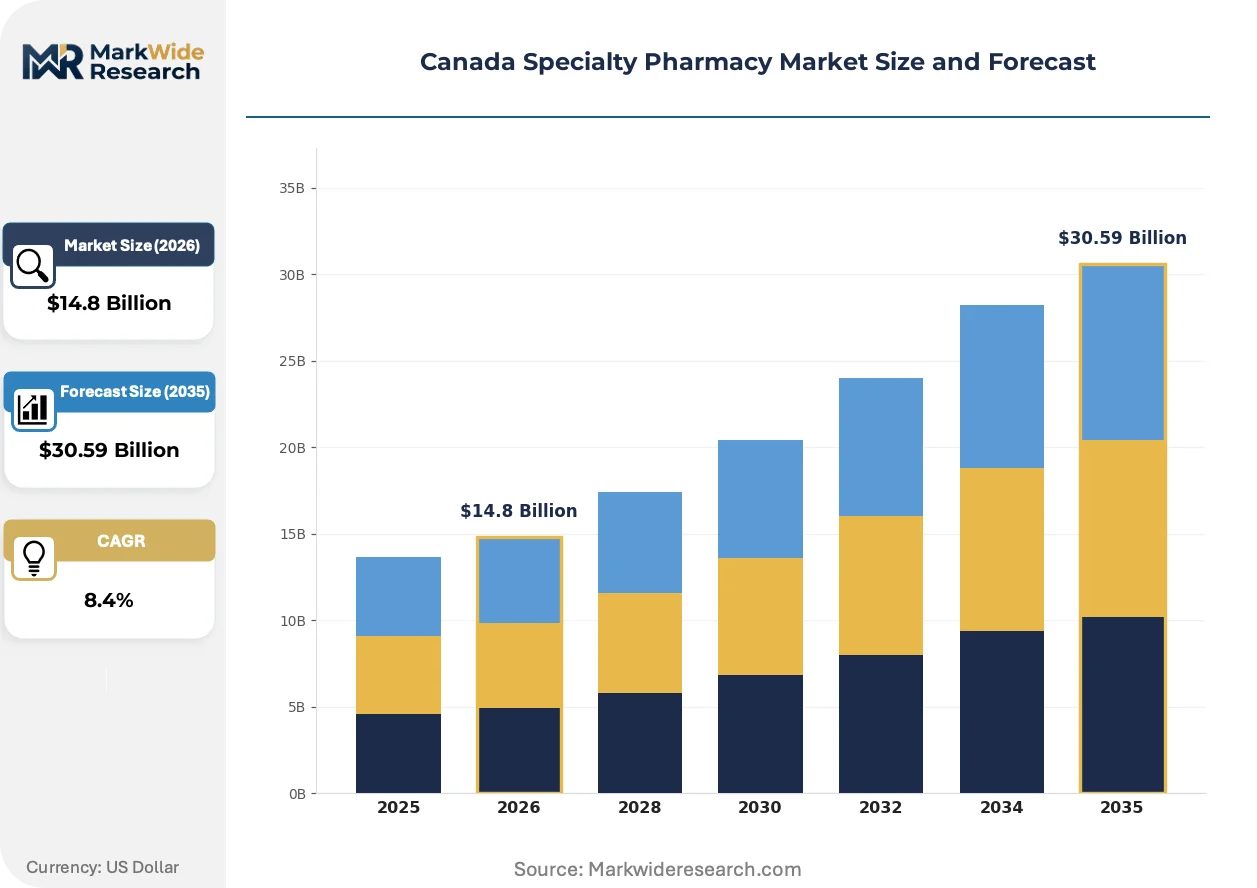
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Oral Medications, Injectable Therapies, Specialty Drugs End User: Hospitals, Retail Pharmacies, Homecare Providers, Clinics Service Type: Medication Management, Patient Support, Clinical Services, Distribution Technology: Telehealth Solutions, EHR Integration, RFID Tracking, Mobile Health Apps |
| Companies Covered | Sobeys Inc., PharmaChoice Canada Inc., McKesson Canada, PHARMASAVE, London Drugs, Shoppers Drug Mart Specialty Health Network Inc., Bayshore HealthCare, Concord Specialty Pharmacy, Rexall Pharmacy Group Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Specialty Pharmacy Market Strategic Shifts
Digital infrastructure is compressing traditional intake and adherence-monitoring workflows, while regulatory pressure on biologics pricing accelerates channel consolidation around vertically integrated pharmacy-hospital networks.
Automated temperature-monitoring systems with real-time GPS tracking and blockchain-based chain-of-custody documentation are displacing manual cold-chain verification processes. Hospital procurement departments in Ontario and British Columbia mandate these systems for injectable biologics contracts. This technology is displacing smaller regional distributors lacking capital for sensor-network deployment, concentrating hospital supply agreements among national operators.
Health Canada's evolving guidance on biosimilar interchangeability establishes substitution protocols that accelerate provincial formulary adoption. The PMPRB's parallel pricing reforms force manufacturers to restructure rebate mechanisms, compressing net prices. Oncology and immunology therapeutic categories face the steepest margin pressure, with pharmacies restructuring patient-support programs to maintain access.
Home-infusion service bundling is replacing clinic-based administration for stable chronic therapies. Patients in Vancouver's health-tech corridor and Toronto's suburban ring increasingly prefer nursing-supported home delivery over hospital day-unit visits. British Columbia's provincial health authority has expanded reimbursement for home biologic administration, validating this channel shift.
Canada Specialty Pharmacy Market Segmentation
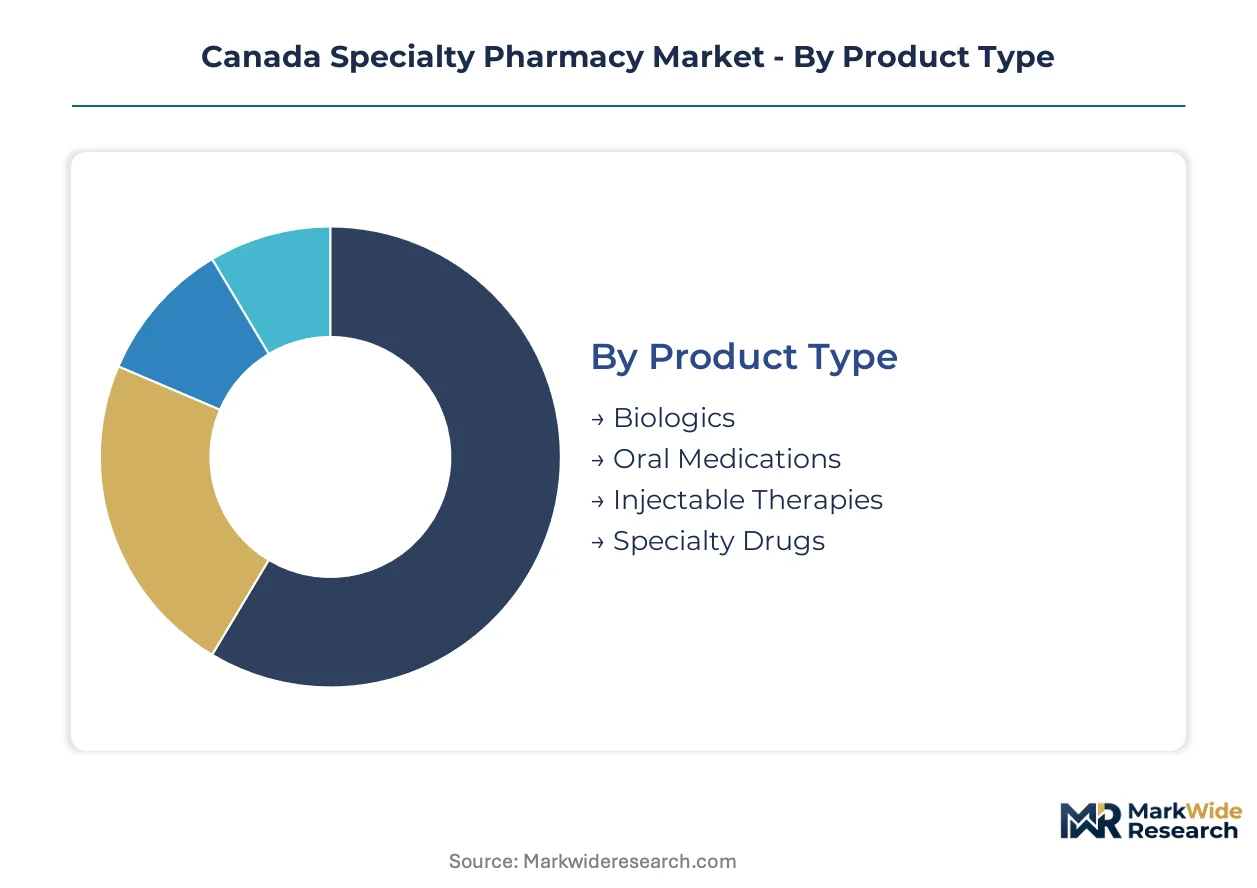
Segmentation in Canada's specialty pharmacy market reveals how cold-chain infrastructure, clinical service bundling, and digital integration determine which channels capture margin across biologics dispensing. Understanding these divides exposes where procurement power concentrates and where new entrants face capital barriers.
Product Type:
Channel-mix dynamics vary sharply across product categories, with temperature requirements and administration complexity dictating whether volumes flow through hospital infusion centers, retail specialty networks, or direct-to-patient homecare channels.
- Biologics:Complex protein-based therapeutics requiring continuous 2°C to 8°C cold-chain integrity from manufacturer to patient. Demand clusters in Ontario's Greater Toronto Area and Vancouver's health-tech corridor, where tertiary hospitals and oncology centers generate sufficient volume to justify dedicated refrigerated distribution infrastructure.
- Injectable Therapies:Parenteral formulations including monoclonal antibodies and specialty vaccines demanding sterile handling and patient-specific dosing protocols. Homecare administration is displacing clinic-based delivery in British Columbia, where provincial reimbursement now covers nursing-supported home infusion for stable chronic conditions.
- Oral Medications:High-cost small-molecule specialty drugs with simpler storage requirements that flow through retail specialty pharmacy networks.
- Specialty Drugs:Broad category encompassing all high-cost, complex medications requiring prior authorization and clinical monitoring.
Biologics dominate installed base. Injectable therapies are where expansion concentrates.
End User:
Cost-tier stratification separates capital-intensive hospital contracts from margin-focused homecare relationships, with procurement scale determining which end users negotiate rebate structures directly with manufacturers.
- Hospitals:Tertiary-care centers and oncology infusion hubs purchasing biologics through centralized procurement with EHR-integrated dispensing workflows. Ontario and British Columbia hospital systems are consolidating vendor relationships around operators with real-time temperature monitoring and blockchain chain-of-custody documentation.
- Homecare Providers:Nursing-supported administration services for stable chronic therapies, expanding fastest in Vancouver's suburban ring and Toronto's exurban corridors where patients prefer avoiding hospital day-unit visits.
- Retail Pharmacies:Community-based specialty networks handling oral medications and limited injectable dispensing with patient-support program integration.
- Clinics:Specialist outpatient facilities referring patients to partnered specialty pharmacies for biologics access and adherence monitoring.
Hospitals anchor procurement volume. Homecare providers are climbing the fastest.
Service Type:
Application focus separates commodity distribution from high-margin clinical services, with patient complexity determining which service bundles pharmacies must assemble to win contracts.
- Clinical Services:In-house nursing, biomarker logistics, and immune-monitoring for oncology-immunology combination therapies. Demand concentrates among hospital systems requiring trial coordination capabilities for investigational biologics.
- Patient Support:Adherence coaching, financial assistance navigation, and virtual intake systems reducing dropout rates in remote jurisdictions.
- Medication Management:Prior authorization processing, drug interaction screening, and dosing protocol optimization.
- Distribution:Cold-chain logistics and same-day delivery infrastructure, increasingly automated with GPS-tracked temperature sensors.
Clinical services command premium pricing. Patient support is gaining share fastest.
Technology:
Maturity divides separate established EHR integration requirements from emerging remote monitoring capabilities, with regulatory clarity from Health Canada determining adoption timelines for virtual-first models.
- EHR Integration:Mandatory API connectivity to provincial health information exchanges, complicated by non-interoperable data standards forcing pharmacies to maintain multiple connection protocols across Ontario, Quebec, and Western provinces.
- Telehealth Solutions:Virtual intake and adherence-monitoring platforms extending specialty pharmacy reach into rural Quebec and Manitoba, pending anticipated Health Canada guidance on remote therapeutic monitoring validation.
- RFID Tracking:Automated inventory and cold-chain verification systems displacing manual processes in hospital procurement contracts.
- Mobile Health Apps:Patient-facing adherence tools and appointment scheduling interfaces.
EHR integration dominates installed base. Telehealth solutions are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario commands pricing leverage over Atlantic Canada due to tertiary-care hospital clustering and volume concentration, while Quebec's formulary autonomy creates procurement fragmentation that elevates administrative costs for cross-provincial operators.
Ontario
Toronto's health-tech corridor and Ottawa's research hospitals generate biologics dispensing volumes sufficient to justify same-day delivery infrastructure. Health Canada coordinates with Ontario's public drug programs on biosimilar switching mandates. The Greater Toronto Area anchors McKesson Canada's cold-chain distribution network and Shoppers Drug Mart's integrated telehealth platform.
British Columbia
Vancouver's suburban ring and Victoria's aging population drive home-infusion service expansion for stable chronic therapies. The provincial health authority expanded reimbursement for nursing-supported home biologic administration in 2024. Vancouver's health-tech corridor concentrates oncology infusion centers consolidating vendor relationships around EHR-integrated operators.
Quebec
Montreal's hospital networks and Quebec City's research institutions sustain demand for clinical-trial coordination services. The province maintains autonomous formulary criteria distinct from Health Canada's federal guidance, forcing pharmacies to maintain separate prior-authorization workflows. Laval's pharmaceutical manufacturing cluster feeds regional distribution networks with temperature-controlled logistics.
Alberta
Calgary's private health services and Edmonton's academic medical centers split demand between retail specialty networks and hospital-anchored dispensing. The Patented Medicine Prices Review Board's pricing ceilings compress rebate pools available to provincial purchasers. Calgary's energy-sector demographics create pockets of employer-sponsored coverage for high-cost biologics.
Atlantic Canada
Nova Scotia and New Brunswick lack dedicated specialty pharmacy infrastructure, forcing patients toward Quebec or Ontario for complex therapies. Provincial formularies lag Ontario and British Columbia in biosimilar adoption timelines. Halifax's emerging health-tech startup scene presents first-mover opportunity for mobile nursing and remote monitoring capabilities.
Canada Specialty Pharmacy Market Competitive Environment
Concentration sits with national distributors possessing cold-chain infrastructure and hospital procurement relationships. McKesson Canada leverages refrigerated distribution networks to anchor institutional contracts, while retail pharmacy banners compete through patient-support program integration. Three archetypes dominate: vertically integrated national distributors, retail-banner specialty networks with telehealth platforms, and clinical-services specialists in oncology and rare disease. Competitive moves center on EHR integration partnerships and home-infusion service expansion.
Among national-scale operators, McKesson Canada and Shoppers Drug Mart Specialty Health Network exemplify the distributor-retail divergence in channel strategy. Bayshore HealthCare occupies a position within the clinical-services specialist tier, anchoring homecare relationships through nursing-supported administration capabilities. These three entities represent how capital intensity and service bundling separate market access winners from regional challengers.
| Leading Market Players |
|---|
| Sobeys Inc. |
| PharmaChoice Canada Inc. |
| McKesson Canada |
| PHARMASAVE |
| London Drugs |
| Shoppers Drug Mart Specialty Health Network Inc. |
| Bayshore HealthCare |
| Concord Specialty Pharmacy |
| Rexall Pharmacy Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Ontario hospital systems and cold-chain distributors lock in both biologics supply access and price visibility across multi-year procurement windows. The Patented Medicine Prices Review Board's pricing ceilings compress rebate pools available for renegotiation, forcing pharmacies to absorb margin erosion through operational restructuring rather than contract rebalancing.
Pricing Analysis
The customization-premium spread separates standard biologics dispensing from patient-specific dosing protocols with clinical monitoring bundled. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain certification grade and EHR integration depth. Cost compression in the economy tier is intensifying because provincial formularies mandate biosimilar substitution, eroding originator margins. Retail specialty networks show highest price sensitivity due to rebate-dependent revenue models, while hospital procurement committees prioritize supply security over unit cost.
Supply Chain Analysis
Inventory lead times for temperature-sensitive biologics stretch across 14-21 day windows from manufacturer to patient, with cold-chain integrity checkpoints at every transfer node. Domestic production draws from Quebec's Laval pharmaceutical cluster and Ontario's compounding facilities, while active pharmaceutical ingredients feed from India and Switzerland. Single-source vulnerability concentrates in refrigerated third-party logistics, where McKesson Canada and two regional operators control viable cold-chain certification. Distribution runs through hospital-anchored centralized hubs for high-volume oncology centers, with direct-to-patient nursing delivery expanding fastest in British Columbia's homecare reimbursement environment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through Health Canada GMP certification creates switching costs that protect incumbent positioning against new capital inflows.
For Market Incumbents: Compound cold-chain infrastructure advantages by acquiring Atlantic Canada mobile nursing capabilities before formulary harmonization accelerates. Deepen backward integration into sterile compounding facilities to offset PMPRB margin compression. Prioritize EHR integration partnerships with Ontario Health and BC Provincial Health Services Authority to lock out regional challengers lacking API connectivity resources.
For New Entrants and Emerging Players: Home-infusion service gaps in Nova Scotia and New Brunswick represent the most penetrable white-space, where incumbent underinvestment in rural nursing networks leaves stable chronic therapy patients underserved. Target Quebec's autonomous formulary environment with French-language patient-support platforms that incumbent national operators have neglected. Pursue clinical-trial coordination capabilities as the go-to-market angle, anchoring relationships with Montreal's research hospitals before expanding dispensing services.
For Investors and Strategic Acquirers: Regional clinical-services specialists with oncology-immunology biomarker logistics capabilities offer the strongest acquisition target archetype for portfolio diversification. Long-term viability rests on regulatory entrenchment through Health Canada facility certifications that require 18-24 month accreditation timelines. Watch for Health Canada digital health guidance finalization as the inflection indicator validating fully virtual specialty pharmacy models.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | McKesson Canada's sensor-network deployment anchors hospital procurement contracts requiring real-time temperature verification. |
| EHR Integration Partnership | API connectivity to Ontario Health's provincial exchange locks in referral network access for specialty pharmacies. |
| Home-Infusion Service Launch | British Columbia's expanded reimbursement validates nursing-supported biologic administration outside hospital day-units. |
| Biosimilar Transition Program | Health Canada's interchangeability protocols accelerate provincial formulary adoption and dispensing volume shifts. |
| Clinical-Trial Coordination Capability | Montreal's research hospitals generate investigational biologics demand requiring in-house biomarker logistics expertise. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, specialty pharmacy operations directors, Health Canada regulatory affairs leads, and provincial formulary committee members. Secondary validation drew from Health Canada GMP inspection databases, Patented Medicine Prices Review Board pricing guidance documents, provincial drug program formularies, and hospital supply chain disclosure records. Bottom-up prescription volume modeling and top-down market sizing triangulated across these data streams.
Across the analysis window, the quantitative framework segmented by product type, end user, service tier, and technology adoption pattern to isolate growth vectors. CAGRs were derived from trend extrapolation of biosimilar substitution rates, telehealth platform penetration curves, and home-infusion reimbursement expansion trajectories. Forecast inputs incorporated Health Canada regulatory timeline assumptions and provincial health authority budget allocation patterns.
Forecasts assume regulatory continuity in Health Canada biologics guidance and provincial formulary frameworks; material policy shifts would require re-modeling. Specific risks include PMPRB pricing ceiling revisions, biosimilar interchangeability protocol changes, and provincial reimbursement rate adjustments for homecare administration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Global Caspofungin Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Atorvastatin API Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Global Pharmaceuticals Market