
 Cancer Therapeutics and Biotherapeutics Market | 2026-2036
Cancer Therapeutics and Biotherapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Therapeutics and Biotherapeutics Market Analysis
China is reconfiguring biologics manufacturing capacity through government-backed industrial parks in Suzhou and Shanghai. Hoffmann-La Roche AG anchors European biologics production with integrated antibody development and fill-finish operations. Bristol-Myers Squibb differentiates through its immuno-oncology franchise, while Amgen Inc. leverages recombinant protein engineering platforms to sustain pipeline productivity.
Cancer therapeutics and biotherapeutics comprise pharmaceutical agents and biological products designed to inhibit malignant cell proliferation, including monoclonal antibodies engineered for target specificity and immunotherapy modalities that activate host immune recognition. These products undergo mammalian cell culture production, purification via protein A chromatography, and formulation at specified concentrations for clinical administration. Immunotherapy commands premium positioning as checkpoint inhibitors demonstrate durable responses in solid tumors, while targeted therapy segments expand through kinase inhibitor portfolios. Intravenous delivery dominates hospital-based administration, though subcutaneous formulations gain traction in outpatient and homecare settings.
FDA breakthrough therapy designation and EMA priority medicines pathways compress regulatory review timelines, directly shaping manufacturer development prioritization and launch sequencing. China's NMPA reform of biologics approval standards aligns domestic requirements with ICH guidelines, accelerating multinational market entry. REACH and RoHS frameworks in Europe impose material traceability requirements on single-use bioprocessing components. Stakeholders must monitor evolving biosimilar interchangeability standards and their impact on reference product defense strategies.
Market Dynamics
FDA breakthrough therapy designation and EMA priority medicines pathways compress regulatory review timelines, directly reshaping manufacturer development prioritization and launch sequencing strategies across oncology portfolios.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy and EMA PRIME designations compress Phase III-to-launch timelines from 48 months to under 24 months for qualifying immuno-oncology assets.
- China:NMPA reform of biologics approval standards aligns domestic requirements with ICH guidelines, accelerating multinational market entry for antibody-drug conjugates.
- Subcutaneous Formulation Engineering:Halozyme's ENHANZE platform enables IV-to-subcutaneous conversion, expanding outpatient administration capacity and reducing infusion center bottlenecks.
Market Restraints
- Plasmid DNA Supply Concentration:Contract manufacturing for gene therapy starting materials concentrates among three North American suppliers, creating single-source vulnerability for CAR-T developers.
- Protein A Resin Cost Volatility:Chromatography media represents 15-20% of downstream processing costs, with agarose bead supply constrained by marine harvest variability.
- Interchangeability Standards Uncertainty:FDA biosimilar interchangeability guidance creates reference product defense complexity, delaying automatic substitution adoption in US pharmacy benefit management.
Strategic Opportunities
- Brazil:ANVISA's streamlined biologics licensing pathway and expanding private oncology networks create first-mover positioning for biosimilar portfolios in Latin America's largest market.
- Homecare Infusion:Subcutaneous checkpoint inhibitor formulations enable administration outside hospital settings, capturing margin from site-of-care reimbursement differentials.
- Dual Carbon Goals:China's MEE emissions mandates for pharmaceutical manufacturing drive demand for single-use bioprocessing systems that reduce water and energy intensity versus stainless steel.
Industry Challenges
- Cell Therapy Manufacturing Workforce Gap:Vector production and aseptic processing for autologous CAR-T requires GMP-qualified personnel that academic training programs have not scaled to match pipeline expansion.
- Multi-Product Facility Contamination Risk:Campaign switching between antibody and viral vector production demands extensive cleaning validation, extending changeover timelines and constraining capacity utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Therapeutics and Biotherapeutics Market |
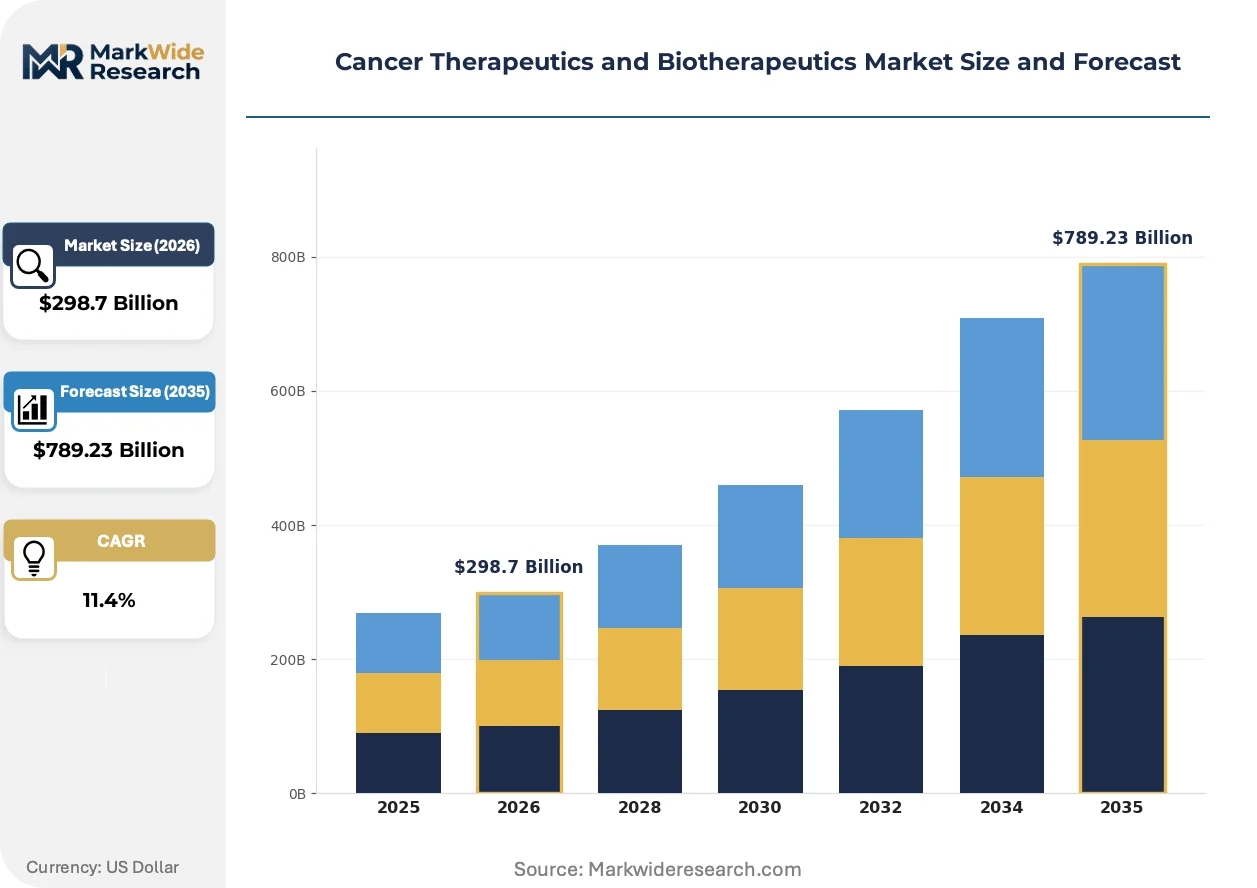
| Market Size in 2026 | $298.7 Billion |
| Market Size in 2035 | $789.23 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy, Targeted Therapy, Immunotherapy Application: Oncology, Hematology, Breast Cancer, Lung Cancer Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Cancer Research Institutes, Clinics, Homecare |
| Companies Covered | Amgen Inc., Bristol-Myers Squibb, Novartis, Merck & Co Inc., Pfizer Inc., Johnson & Johnson, Hoffmann-La Roche AG, ELI Lilly and Company, Celgene Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Therapeutics and Biotherapeutics Market Emerging Trajectories
Continuous manufacturing platforms and AI-driven target identification are compressing development cycles while reshaping competitive differentiation in oncology biologics.
Bispecific antibody engineering is migrating from proof-of-concept to registrational trials, with T-cell engagers demonstrating activity in hematologic malignancies previously refractory to monospecific checkpoint blockade. Large pharmaceutical manufacturers have advanced eight bispecific assets into Phase III since 2022, prioritizing fixed-dose combinations that reduce resistance mechanisms. This modality shift is compressing the addressable patient pool for sequential monotherapy regimens.
REACH and RoHS frameworks impose material traceability requirements on single-use bioprocessing components used in European manufacturing facilities. ECHA substance of very high concern listings now cover phthalate plasticizers common in tubing assemblies, forcing suppliers to validate alternative elastomer formulations. Biologics manufacturers with EU fill-finish operations are qualifying replacement materials ahead of 2026 sunset dates for legacy components.
Hospital systems are consolidating oncology purchasing through specialty pharmacy carve-outs and 340B program optimization, concentrating formulary decision-making among fewer procurement entities. Integrated delivery networks in the United States now direct 60% of infused biologics through captive specialty pharmacies, displacing traditional wholesale distribution for oncolytic agents. This channel consolidation is most advanced in Medicare-dependent markets where reimbursement rate differentials favor hospital-based administration.
Cancer Therapeutics and Biotherapeutics Market Segmentation
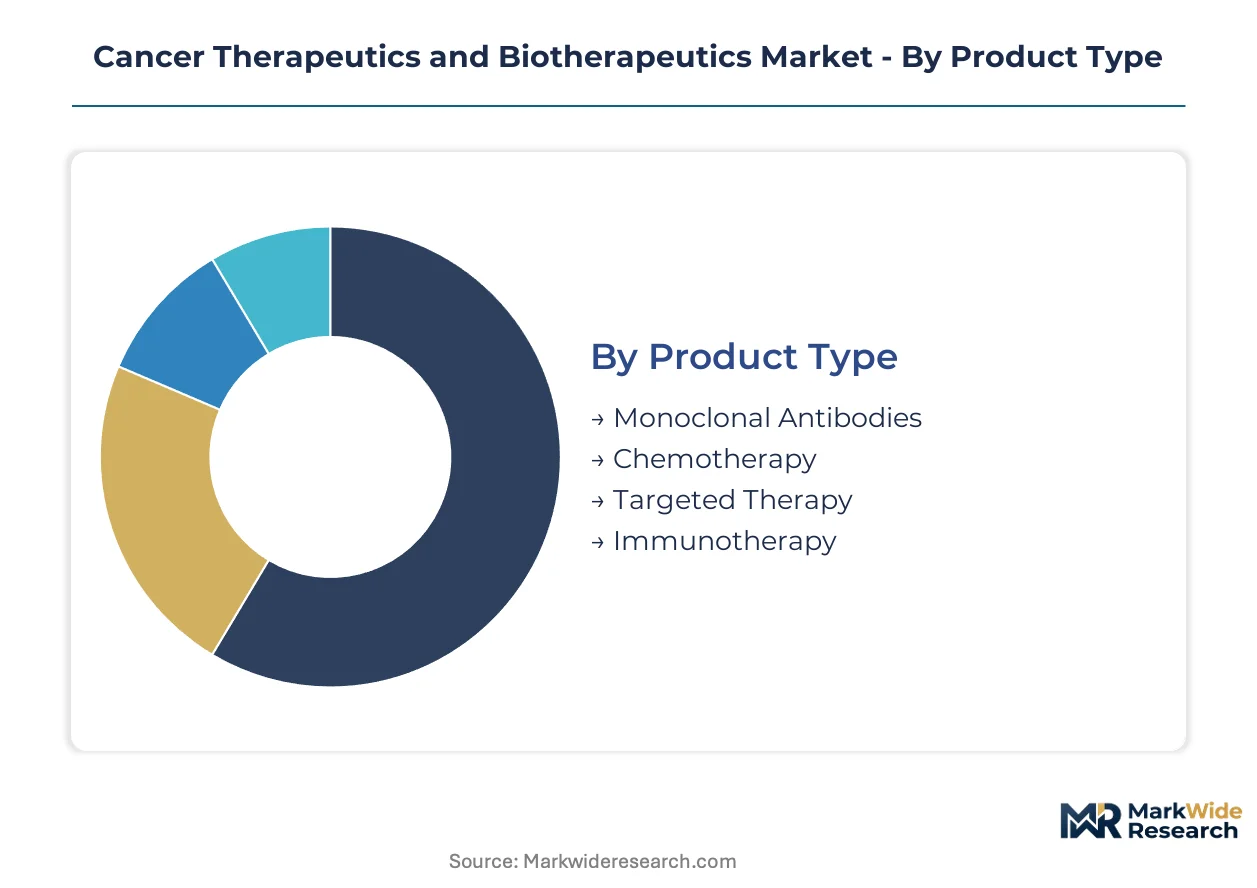
Cancer therapeutics and biotherapeutics segment along four critical dimensions that determine manufacturing scale, regulatory pathway, and commercial strategy. Product type dictates bioprocessing infrastructure investment. Application shapes clinical trial design and prescriber targeting. Delivery mode determines site-of-care economics and patient adherence profiles. End user concentration influences distribution channel selection and reimbursement negotiation leverage.
Product Type:
After-sales service intensity varies dramatically across modalities, with cell therapy requiring cryogenic logistics support and monoclonal antibodies demanding cold chain maintenance protocols.
- Monoclonal Antibodies:Engineered immunoglobulins targeting specific tumor antigens via Fc-mediated effector functions and direct signaling blockade. Manufacturing employs mammalian cell culture with protein A chromatography purification. Demand concentrates in United States hospital systems where Medicare reimbursement for infused biologics exceeds physician office rates.
- Immunotherapy:Checkpoint inhibitors and cytokine therapies that activate host immune recognition against malignant cells. Subcutaneous formulation engineering is expanding outpatient administration capacity and reducing infusion center bottlenecks.
- Chemotherapy:Cytotoxic small molecules disrupting DNA replication and mitotic spindle formation. Generic competition has compressed pricing power for alkylating agents and antimetabolites.
- Targeted Therapy:Small molecule kinase inhibitors and hormone antagonists designed for specific oncogenic driver mutations. Oral bioavailability enables home administration with lower service intensity requirements.
By volume, chemotherapy leads due to broad tumor applicability and established protocols. By growth pace, immunotherapy is climbing the fastest as checkpoint inhibitors expand into earlier treatment lines.
Application:
Cost tier stratification separates curative-intent regimens in hematologic malignancies from chronic management protocols in solid tumors.
- Oncology:Comprehensive treatment of solid tumors across anatomical sites including colorectal, prostate, and pancreatic malignancies. Multidisciplinary tumor boards drive regimen selection at academic medical centers.
- Breast Cancer:HER2-directed therapies and CDK4/6 inhibitors dominate the adjuvant and metastatic settings. Demand concentrates in United States integrated delivery networks with captive specialty pharmacies.
- Lung Cancer:EGFR, ALK, and PD-L1 biomarker testing directs therapy selection in non-small cell histologies. China NMPA reform has accelerated approval timelines for next-generation tyrosine kinase inhibitors.
- Hematology:Leukemia, lymphoma, and multiple myeloma treatments including CAR-T cellular therapies. Academic medical centers anchor demand due to specialized apheresis and lymphodepletion infrastructure requirements.
By patient volume, lung cancer leads given incidence prevalence. By revenue concentration, hematology is ahead due to cellular therapy pricing.
Delivery Mode:
Volume throughput differs by administration complexity, with intravenous delivery requiring specialized infrastructure versus oral self-administration.
- Intravenous:Infusion center-based administration of monoclonal antibodies and cytotoxic agents requiring vascular access and monitoring. Hospital systems are expanding dedicated oncology infusion centers to accommodate rising patient volumes.
- Subcutaneous:Halozyme's ENHANZE platform enables IV-to-subcutaneous conversion for multiple oncology biologics. Homecare infusion is capturing margin from site-of-care reimbursement differentials.
- Oral:Small molecule kinase inhibitors and hormone therapies enabling patient self-administration. Retail pharmacy distribution dominates with lower service intensity.
- Intramuscular:Depot formulations for hormonal agents and certain supportive care medications. Limited oncology application relative to other therapeutic areas.
By administration frequency, intravenous leads. By patient preference and adherence, subcutaneous is expanding most quickly.
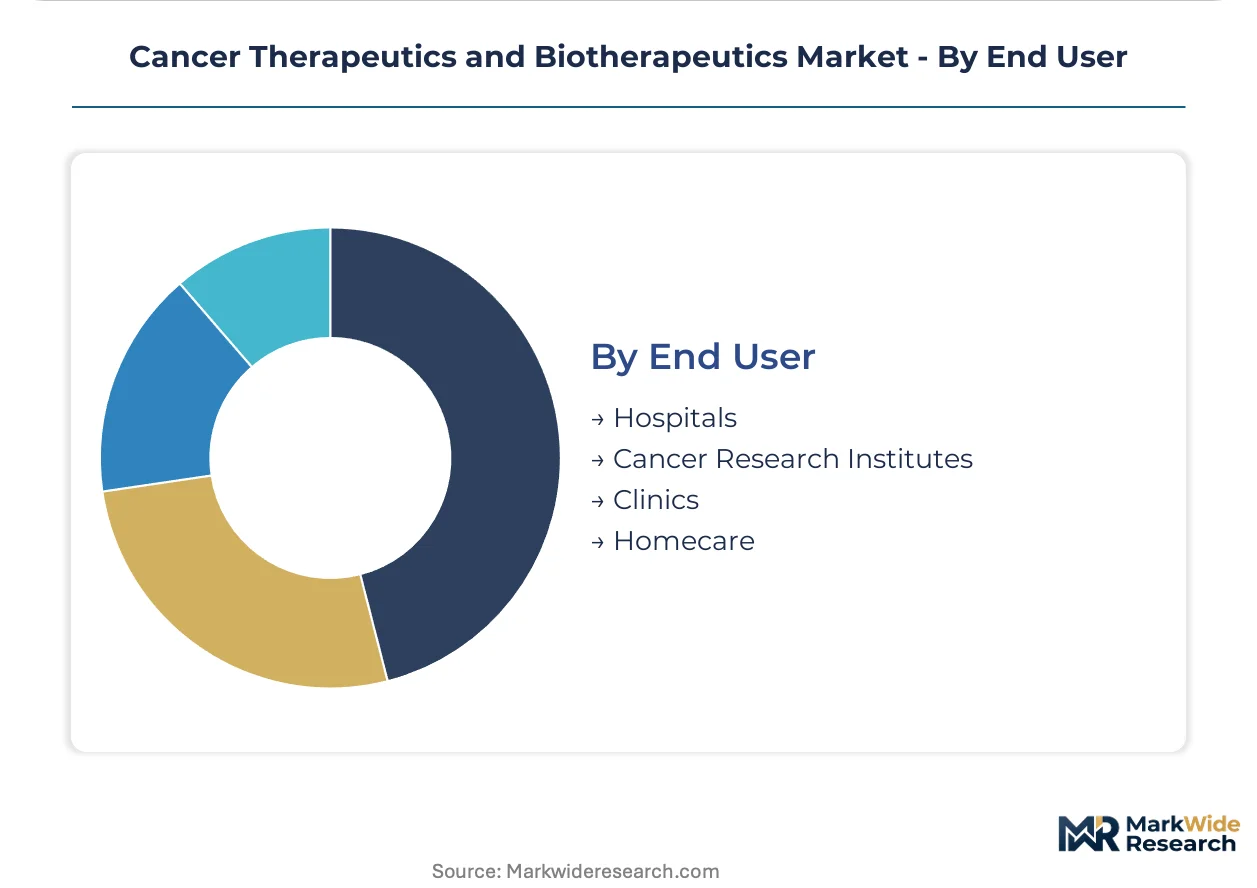
End User:
Customer type determines procurement complexity, with hospital systems consolidating purchasing through specialty pharmacy carve-outs.
- Hospitals:Inpatient and outpatient infusion services with 340B program optimization driving formulary decision-making. Integrated delivery networks now direct the majority of infused biologics through captive channels.
- Cancer Research Institutes:Early-phase clinical trial sites and academic medical centers with specialized cellular therapy manufacturing capabilities. Cell therapy manufacturing workforce gaps constrain capacity expansion.
- Clinics:Community oncology practices facing reimbursement pressure from site-of-care differentials. Consolidation into hospital-owned networks is accelerating.
- Homecare:Subcutaneous administration and oral therapy management outside institutional settings. Brazil ANVISA streamlined biologics licensing is creating first-mover positioning for homecare-capable portfolios.
By prescription volume, hospitals lead. By growth trajectory, homecare is gaining share fastest as subcutaneous formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing capacity clusters among three national jurisdictions, with regulatory pathway harmonization creating divergent market entry timelines across developed and emerging economies.
United States
Medicare reimbursement differentials favor hospital-based infusion, concentrating prescribing power within integrated delivery networks. FDA breakthrough therapy designation compresses Phase III-to-launch timelines below 24 months for qualifying immuno-oncology assets. Greater Boston and San Francisco Bay Area anchor cell therapy manufacturing, with specialized apheresis infrastructure expanding at academic medical centers.
China
Government-backed industrial parks in Suzhou and Shanghai reconfigure domestic biologics capacity toward export-ready production. NMPA reform of biologics approval standards aligns domestic requirements with ICH guidelines, accelerating multinational market entry for antibody-drug conjugates. Yangtze River Delta bioclusters attract contract development organizations serving both domestic and international sponsors.
Germany
EMA priority medicines pathways reshape manufacturer launch sequencing across European oncology portfolios. REACH and RoHS frameworks impose material traceability requirements on single-use bioprocessing components used in fill-finish operations. Baden-Württemberg and Bavaria host integrated antibody development facilities with captive fill-finish capabilities.
Switzerland
Swissmedic alignment with EMA centralized procedures enables simultaneous EU and domestic market authorization. Basel anchors European biologics production with integrated development and manufacturing operations. The country's bilateral agreements with the EU preserve pharmaceutical trade flow continuity despite non-member status.
Brazil
ANVISA streamlined biologics licensing pathway creates first-mover positioning for biosimilar portfolios in Latin America's largest market. Expanding private oncology networks absorb subcutaneous formulation capacity from multinational suppliers. São Paulo and Rio de Janeiro concentrate infusion center infrastructure serving both public and private reimbursement channels.
Cancer Therapeutics and Biotherapeutics Market Vendor Landscape
Integrated pharmaceutical conglomerates and specialized biologics developers split the market along manufacturing scale and therapeutic focus vectors. Consolidation prevails in mature modalities, with monoclonal antibody production requiring billion-dollar cell culture infrastructure investments that exclude mid-cap entrants. Three archetypes dominate: diversified conglomerates with oncology franchises, recombinant protein engineering specialists, and immuno-oncology platform companies. Competitive moves center on subcutaneous formulation licensing and cell therapy manufacturing partnerships.
Among diversified conglomerates with oncology franchises, Hoffmann-La Roche AG, Bristol-Myers Squibb, and Amgen Inc. exemplify distinct strategic positioning. Hoffmann-La Roche AG represents integrated European biologics production with captive development-to-manufacturing capabilities. Bristol-Myers Squibb occupies a position within the immuno-oncology platform archetype, reflecting checkpoint inhibitor portfolio concentration. Amgen Inc. anchors the recombinant protein engineering specialist tier, with manufacturing heritage in mammalian cell culture systems.
| Leading Market Players |
|---|
| Amgen Inc. |
| Bristol-Myers Squibb |
| Novartis |
| Merck & Co Inc. |
| Pfizer Inc. |
| Johnson & Johnson |
| Hoffmann-La Roche AG |
| ELI Lilly and Company |
| Celgene Corporation |
| Others |
Supply Flow & Price Mechanics
Trans-Atlantic cold chain corridors connecting Belgian fill-finish facilities to United States distribution hubs carry cost premiums that compound with protein A resin price volatility, concentrating margin pressure on biosimilar developers while originator manufacturers leverage captive manufacturing to sustain tiered pricing power across hospital systems and specialty pharmacy networks.
Pricing Analysis
Medicare reimbursement differentials dictate the pricing tier structure across administration settings, with hospital-based infusion commanding premium rates over physician office administration. Pricing stratifies across originator biologics, designated biosimilars, and interchangeable products based on FDA approval pathway and automatic substitution eligibility. Cost compression in the biosimilar tier is intensifying as formulary exclusion clauses and rebate contracting favor established reference products. Community oncology practices exhibit highest price sensitivity due to site-of-care reimbursement disadvantages, while integrated delivery networks leverage captive specialty pharmacies to capture margin from administration differentials.
Supply Chain Analysis
Contract manufacturing for gene therapy starting materials concentrates among North American suppliers, with plasmid DNA production and viral vector capacity anchoring United States bioclusters. Mammalian cell culture draws from Chinese stainless steel and single-use component supply bases, while chromatography media production rests on agarose harvest from marine sources in Japan and Scandinavia. Single-source vulnerability for CAR-T vector inputs creates supply chain risk for autologous cell therapy developers. Distribution runs through hospital-owned specialty pharmacies displacing traditional wholesale channels for infused oncology biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designation compresses development timelines below traditional oncology benchmarks, creating acceleration advantages for manufacturers with regulatory affairs infrastructure and biomarker-driven patient selection capabilities.
For Market Incumbents: Build manufacturing scale moats through single-use bioprocessing investments in Yangtze River Delta industrial parks, securing dual-source resin supply agreements to defend against protein A cost volatility. Consolidate formulary position by acquiring community oncology practices facing site-of-care reimbursement pressure, converting them to hospital-owned infusion centers. Priority lever rests on subcutaneous formulation licensing to capture outpatient administration margin. For New Entrants and Emerging Players: Pursue ANVISA streamlined biologics licensing in Brazil, where private oncology network expansion outpaces biosimilar penetration. Target homecare infusion segments enabled by Halozyme ENHANZE platform partnerships, capturing margin from site-of-care reimbursement differentials. Go-to-market angle centers on subcutaneous checkpoint inhibitor formulations for outpatient administration outside hospital settings. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting mature oncology franchises to refocus on immuno-oncology platforms. Long-term viability favors recombinant protein engineering specialists with mammalian cell culture heritage and biosimilar interchangeability defense capabilities. Signal to watch is FDA biosimilar interchangeability guidance finalization, which will determine automatic substitution adoption velocity in pharmacy benefit management.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Licensing | Halozyme ENHANZE partnerships enable IV-to-subcutaneous conversion, expanding outpatient capacity. |
| Cell Therapy Manufacturing Scale-Up | GMP-qualified personnel gaps constrain autologous CAR-T expansion at academic medical centers. |
| Biosimilar Interchangeability Defense | FDA guidance uncertainty delays automatic substitution, preserving reference product pricing power. |
| 340B Program Optimization | Hospital systems consolidate oncology purchasing through captive specialty pharmacy carve-outs. |
| China NMPA Regulatory Alignment | ICH guideline convergence accelerates multinational antibody-drug conjugate market entry. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interviews across these stakeholder roles combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue reconciliation anchored the quantitative framework.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeling spanning treatment line, administration route, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to base-year sizing, cross-referenced against pipeline progression timelines and approval pathway assumptions. Forecast inputs incorporated Medicare reimbursement rate differentials and NMPA reform implementation pace.
Sensitivities concentrate around FDA biosimilar interchangeability guidance finalization and protein A resin supply disruptions. Forecasts reflect documented assumptions regarding checkpoint inhibitor expansion into earlier treatment lines and subcutaneous formulation adoption curves. Quarterly review of formulary exclusion decisions and 340B program litigation outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Global Dementia Drugs Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market