
 Esophageal Achalasia Drug Market | 2026-2036
Esophageal Achalasia Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Esophageal Achalasia Drug Market Foresight
Modular treatment bundling—pairing botulinum toxin injections with sequential calcium channel blocker trials—is recalibrating how physicians stage pharmacological intervention before considering pneumatic dilation or myotomy. WorldMeds leverages its neuromodulator portfolio to anchor botulinum toxin supply chains across North American specialty clinics. AstraZeneca sustains R&D intensity in gastrointestinal motility disorders through its broader acid-related disease franchise. Merck Sharp & Dohme competes on manufacturing scale for generic nitrates used in symptomatic relief protocols.
Esophageal achalasia drugs comprise pharmacological agents that modulate lower esophageal sphincter tone through calcium channel antagonism, nitric oxide pathway potentiation, or neuromuscular junction blockade, with formulations ranging from sublingual isosorbide dinitrate to endoscopically injected botulinum toxin type A. These therapies aim to reduce functional obstruction at the gastroesophageal junction, delaying or replacing invasive mechanical interventions in patients with confirmed manometric diagnosis. Botulinum toxin dominates the drug type segment due to its targeted mechanism and repeatability, while phosphodiesterase inhibitors represent the fastest-growing category as off-label use expands in refractory cases. Gastroenterology practices command the largest end user share, though outpatient centers are capturing incremental volume as same-day injection protocols proliferate.
The FDA evaluates botulinum toxin products under biologics licensing requirements with post-market pharmacovigilance mandates, while the EMA's MDR framework governs device-drug combination delivery systems used in endoscopic administration. These regulatory structures shape clinical trial design, label expansion pathways, and reimbursement negotiations across jurisdictions. Stakeholders must monitor evolving orphan drug exclusivity interpretations and compounding pharmacy enforcement actions that could reshape supply dynamics for nitrates and phosphodiesterase inhibitors.
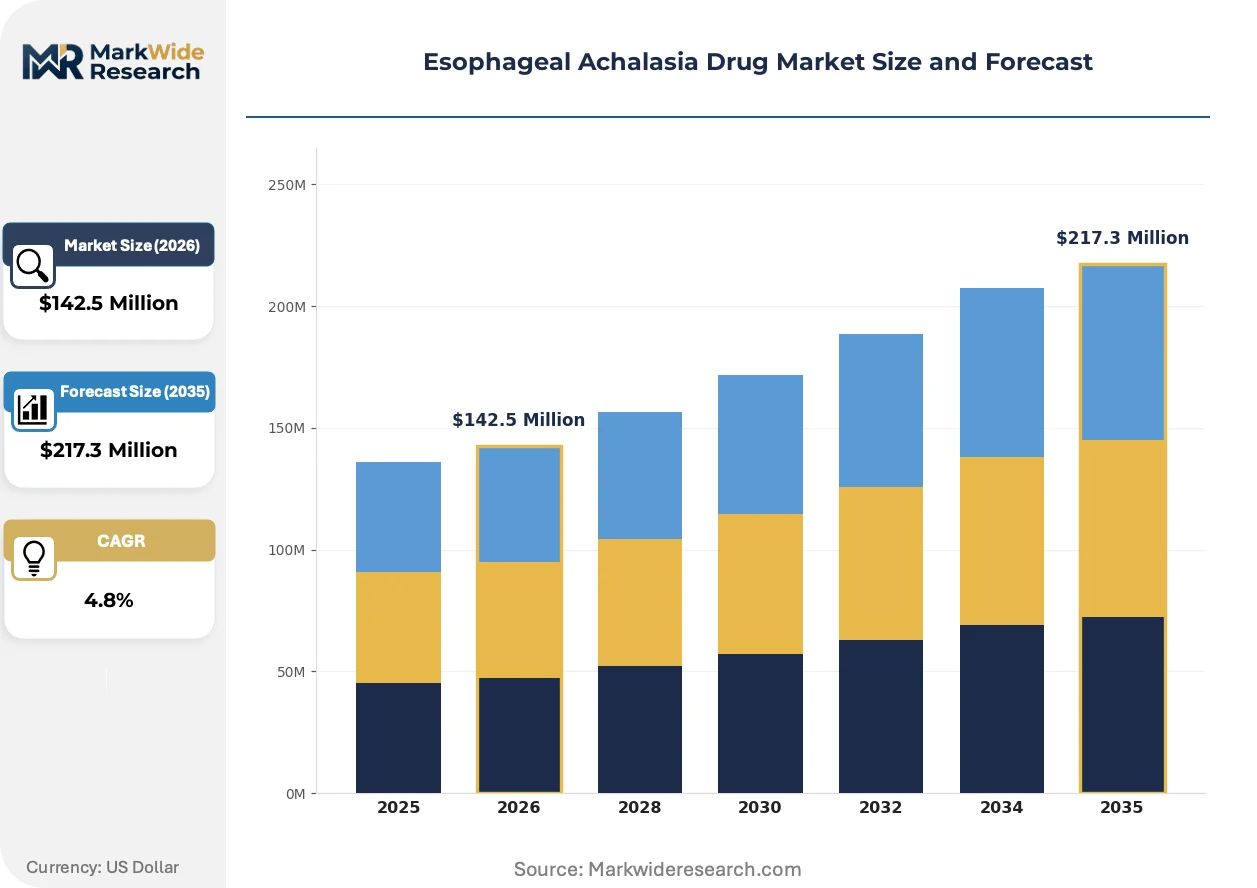
Market Dynamics
The esophageal achalasia drug market pivots on the tension between endoscopic intervention expansion and pharmacological maintenance protocols, as gastroenterology practices recalibrate patient staging algorithms to delay invasive surgical procedures.
Growth Catalysts
- FDA Orphan Drug Designation:The accelerated approval pathway compresses development timelines for novel neuromodulator candidates targeting lower esophageal sphincter dysfunction.
- Botulinum toxin repeatability:Endoscopic injection protocols enable iterative treatment without cumulative tissue damage, extending the therapeutic window before myotomy consideration.
- Specialized motility center proliferation:Concentration of diagnostic expertise in tertiary referral networks standardizes manometric confirmation and treatment initiation.
Market Restraints
- Botulinum toxin supply concentration:Manufacturing capacity constraints for type A neurotoxin concentrate among a limited supplier base create batch allocation vulnerabilities.
- Phosphodiesterase inhibitor regulatory friction:Off-label prescribing for achalasia encounters payer scrutiny and prior authorization barriers in commercial insurance frameworks.
- Calcium channel blocker efficacy ceiling:Sublingual nifedipine demonstrates tachyphylaxis within 12-18 months, limiting durable symptom control in progressive disease.
Strategic Opportunities
- Outpatient center channel expansion:Same-day endoscopic injection protocols capture volume migration from hospital-based gastroenterology suites.
- EMA MDR device-drug convergence:Combination product designation for injection delivery systems creates exclusivity extensions and pricing leverage.
- Refractory case phosphodiesterase adoption:Sildenafil and tadalafil protocols for failed botulinum responders represent an underserved subpopulation.
Industry Challenges
- Manometric technician specialization:High-resolution esophageal pressure topography interpretation requires certified operators, constraining diagnostic throughput.
- Compounding pharmacy enforcement variability:State-level regulatory divergence on sterile preparation of botulinum dilutions creates compliance fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esophageal Achalasia Drug Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Calcium Channel Blockers, Nitrates, Botulinum Toxin, Phosphodiesterase Inhibitors Indication: Primary Achalasia, Secondary Achalasia, Esophageal Spasm, Gastroesophageal Reflux End User: Specialty Clinics, Outpatient Centers, Gastroenterology Practices, Research Institutes Delivery Mode: Oral, Subcutaneous Injection, Intravenous Injection, Topical Administration |
| Companies Covered | WorldMeds, AstraZeneca, Allergan, Eisai, Merck Sharp & Dohme, Ipsen Pharma, Pfizer, Cipla, Merz Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esophageal Achalasia Drug Market Shifts & Advancements
Pharmacological intervention in achalasia is bifurcating toward precision neuromodulation and pathway-agnostic smooth muscle relaxation, with delivery mechanism innovation outpacing molecular discovery.
High-resolution manometry-guided botulinum toxin placement is overtaking landmark-based injection protocols in tertiary care settings. Gastroenterology fellows now train exclusively on pressure topography targeting, abandoning anatomical reference points. This precision shift compresses the dose-response variability that previously plagued standard endoscopic administration.
The FDA's post-market pharmacovigilance mandates for biologics licensing have tightened adverse event reporting thresholds for botulinum toxin products. Manufacturers now maintain dedicated safety databases tracking dysphagia progression and systemic spread incidents. Specialty clinics in the United States have responded by implementing standardized 30-day follow-up protocols to satisfy REMS-equivalent obligations.
Integrated care contracts now bundle diagnostic confirmation, injection procedures, and symptom monitoring into single-episode reimbursement. Gastroenterology practices in metropolitan clusters negotiate these arrangements with regional payers, displacing fee-for-service billing for discrete encounters. This consolidation concentrates patient volume among accredited motility centers with capitalized endoscopy infrastructure.
Esophageal Achalasia Drug Market Segmentation
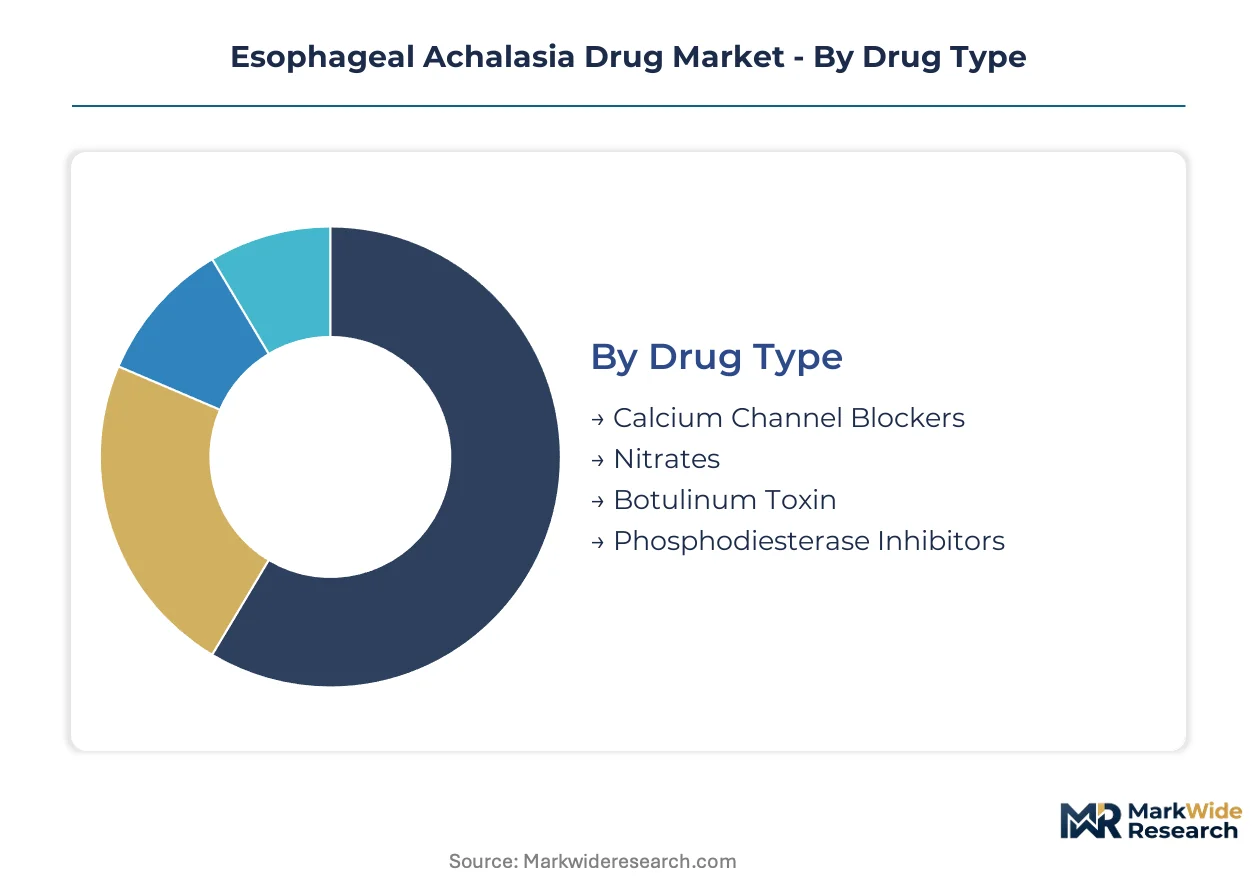
Segmentation in the esophageal achalasia drug market reveals how treatment selection cascades from mechanism of action through delivery logistics to site-of-care economics. Each dimension captures distinct procurement patterns and reimbursement negotiations that shape commercial strategy.
Drug Type:
Physicians stage therapy based on invasiveness tolerance and expected durability, creating clear preference hierarchies across mechanism classes.
- Botulinum Toxin:Type A neurotoxin blocks acetylcholine release at the lower esophageal sphincter neuromuscular junction, producing reversible chemical denervation. Demand clusters in United States tertiary motility centers where endoscopic injection expertise concentrates and prior authorization pathways for repeat dosing are established. Manufacturing batch allocation constraints periodically disrupt supply security.
- Phosphodiesterase Inhibitors:Sildenafil and tadalafil potentiate nitric oxide-mediated smooth muscle relaxation through cGMP pathway modulation. Off-label prescribing in refractory cases is expanding fastest in academic medical centers with established compounding pharmacy relationships. Payer scrutiny of erectile dysfunction drug diversion creates prior authorization friction.
- Calcium Channel Blockers:Sublingual nifedipine provides acute sphincter relaxation through L-type calcium channel antagonism.
- Nitrates:Isosorbide dinitrate generates nitric oxide-mediated vasodilation with rapid onset but limited duration.
Botulinum toxin leads on scale; phosphodiesterase inhibitors lead on momentum.
Indication:
Diagnostic coding specificity determines reimbursement tier and treatment protocol intensity across the achalasia spectrum.
- Primary Achalasia:Idiopathic degeneration of myenteric plexus neurons drives classic presentation with absent peristalsis and non-relaxing sphincter. Volume concentrates in United States metropolitan clusters with high-resolution manometry infrastructure. Diagnostic confirmation requirements limit treatment initiation to certified motility centers.
- Secondary Achalasia:Malignancy-associated or post-surgical pseudoachalasia presents diagnostic complexity requiring endoscopic ultrasound exclusion. Case volume localizes to comprehensive cancer centers with integrated gastroenterology services. Misdiagnosis risk elevates malpractice exposure and documentation requirements.
- Esophageal Spasm:Hypercontractile disorders with intermittent sphincter dysfunction respond variably to pharmacological intervention.
- Gastroesophageal Reflux:Overlap syndromes with achalasia-like features create diagnostic ambiguity and treatment selection challenges.
Primary achalasia dominates procedure volume; secondary achalasia commands premium pricing per case.
End User:
Capital requirements and reimbursement differentials concentrate prescribing authority across distinct practice configurations.
- Gastroenterology Practices:Hospital-affiliated specialty groups maintain endoscopy suites with fluoroscopy capability for injection guidance. United States urban markets show consolidation into multi-physician groups with dedicated motility fellows. Integrated care contracts now bundle diagnosis through injection into single-episode payments.
- Outpatient Centers:Ambulatory surgery facilities capture same-day injection volume through streamlined scheduling and lower facility fees. Growth concentrates in states with favorable site-of-service differentials for endoscopic procedures. Capital-light models appeal to private equity-backed practice aggregators.
- Specialty Clinics:Standalone motility centers with manometry interpretation certification.
- Research Institutes:Academic centers running interventional trials with investigational neuromodulators.
Gastroenterology practices anchor current volume; outpatient centers capture the steepest expansion trajectory.
Delivery Mode:
Route selection balances onset speed, duration requirements, and procedural complexity against patient compliance patterns.
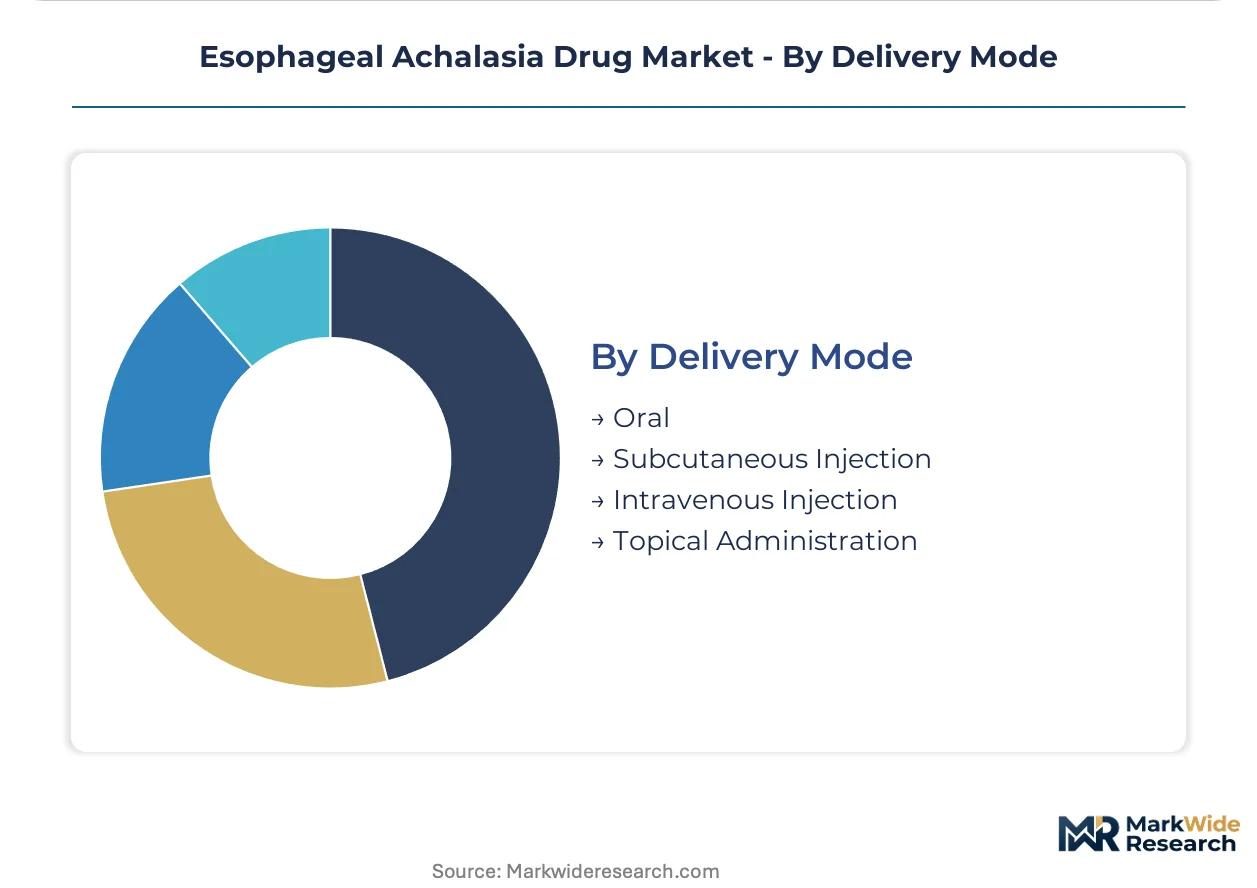
- Subcutaneous Injection:Botulinum toxin administration via endoscopic injection needle delivers precise sphincter targeting with 3-6 month duration. Protocol standardization around high-resolution manometry guidance is displacing landmark-based techniques in United States teaching hospitals. Reimbursement coding distinguishes diagnostic from therapeutic endoscopy.
- Oral:Sublingual nifedipine and isosorbide dinitrate enable patient-administered acute symptom management without facility encounter. Prescription volume concentrates in regions with limited access to interventional gastroenterology services. Tachyphylaxis limits long-term utility.
- Intravenous Injection:Reserved for perioperative sphincter relaxation in surgical myotomy preparation.
- Topical Administration:Experimental formulations targeting mucosal drug delivery remain investigational.
Subcutaneous injection commands the highest revenue per patient; oral routes sustain the broadest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Botulinum toxin therapy for achalasia originated in European academic centers during the 1990s before migrating to United States tertiary care networks, where high-resolution manometry standardization and endoscopic injection protocols achieved scale.
United States
Specialized motility centers in Boston, Chicago, and Houston drive diagnostic throughput and protocol standardization. The FDA's orphan drug designation pathway compresses development timelines for novel neuromodulator candidates targeting lower esophageal sphincter dysfunction. Cleveland Clinic and Mayo Clinic anchor referral networks that concentrate patient volume and shape off-label prescribing patterns for phosphodiesterase inhibitors.
Germany
Comprehensive cancer centers in Munich and Heidelberg integrate achalasia management into esophageal oncology pathways, elevating secondary achalasia case complexity. The EMA's MDR framework governs device-drug combination delivery systems used in endoscopic administration. Baden-Württemberg's medical device cluster supports precision injection system development for manometry-guided placement.
Japan
Aging demographics expand the addressable patient pool for minimally invasive alternatives to surgical myotomy. The PMDA maintains stringent biologics licensing requirements for botulinum toxin products with post-market pharmacovigilance mandates. Tokyo and Osaka metropolitan areas concentrate gastroenterology fellowship programs that train high-resolution manometry interpretation.
United Kingdom
NHS England's specialized commissioning framework routes achalasia cases through designated esophageal motility centers, consolidating prescribing authority. NICE technology appraisal processes evaluate cost-effectiveness of botulinum toxin against pneumatic dilation. London's tertiary referral network absorbs complex secondary achalasia cases from regional cancer centers.
India
Expanding private gastroenterology chains in Delhi-NCR and Mumbai adopt endoscopic injection protocols as alternatives to surgical intervention. The CDSCO regulates botulinum toxin imports under biologics licensing with batch-specific release requirements. Hyderabad's pharmaceutical manufacturing base supplies generic nifedipine for symptomatic relief protocols in resource-constrained settings.
Esophageal Achalasia Drug Market Competitive Landscape
Premium-margin players sit above commodity-margin players across mechanism-of-action differentiation, with botulinum toxin specialists commanding pricing leverage against generic nitrate and calcium channel blocker suppliers. Market structure bifurcates between neuromodulator innovators with biologics exclusivity and pharmaceutical manufacturers competing on manufacturing scale for symptomatic relief agents. Three archetypes dominate: dedicated neurology-neuromodulator firms, diversified gastrointestinal therapy portfolios, and generic API-scale suppliers. Competitive moves concentrate on orphan drug exclusivity extensions and outpatient center channel partnerships.
Within the neuromodulator tier, WorldMeds and Allergan occupy positions anchoring botulinum toxin supply chains across North American specialty clinics, while AstraZeneca exemplifies the diversified gastrointestinal therapy archetype through its broader acid-related disease franchise. These configurations reflect how R&D intensity and manufacturing scale distribute across mechanism classes.
| Leading Market Players |
|---|
| WorldMeds |
| AstraZeneca |
| Allergan |
| Eisai |
| Merck Sharp & Dohme |
| Ipsen Pharma |
| Pfizer |
| Cipla |
| Merz Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Clostridium botulinum type A neurotoxin bulk pricing indices cascade through pharmaceutical supply chains into tiered therapeutic cost structures, with fermentation-derived raw material volatility compressing margins for generic nitrate manufacturers while concentrating pricing power among biologics licensors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by regulatory exclusivity status and delivery mechanism complexity. FDA orphan drug designation commands premium positioning for novel neuromodulators, while compounded phosphodiesterase formulations compete on accessibility. Price erosion runs through generic calcium channel blocker segments as Indian API manufacturers expand volume. Hospital-affiliated gastroenterology practices demonstrate lowest price sensitivity due to bundled reimbursement contracts; resource-constrained outpatient centers in secondary markets exhibit highest elasticity.
Supply Chain Analysis
Cold-chain logistics costs for botulinum toxin biologics concentrate distribution economics around metropolitan medical corridors with validated temperature-controlled infrastructure. Manufacturing capacity clusters in the United States, Ireland, and Japan for type A neurotoxin fermentation, while generic nifedipine API production centers on India and China. Supply chain risk hinges on single-source vulnerability for neurotoxin bulk drug substance given limited qualified fermentation facilities. Distribution runs through specialty pharmaceutical wholesalers with GMP-certified warehousing before hospital and clinic administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as patient selection criteria tighten around manometric-confirmed diagnosis, driving demand-shift toward high-resolution guided injection protocols that command premium reimbursement.
For Market Incumbents: Lock in exclusive supply agreements with certified compounding pharmacies to forestall phosphodiesterase generic substitution. Secure backward integration into high-resolution manometry device supply chains to control diagnostic throughput that precedes therapeutic selection. The FDA's tightening biologics pharmacovigilance mandates threaten smaller competitors with compliance cost burdens that scale advantages can absorb. For New Entrants and Emerging Players: Ambulatory surgery center partnerships offer the most penetrable channel for same-day injection volume capture. Target refractory case protocols in academic medical centers where off-label sildenafil adoption outpaces formal indication development. A compounding pharmacy alliance strategy bypasses traditional wholesale distribution barriers while building prescriber relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with neuromodulator platform companies possessing FDA orphan drug exclusivity extensions and established REMS infrastructure. Long-term viability favors assets with demonstrated repeat-dosing revenue visibility rather than acute symptomatic relief molecules. Watch for CDSCO batch release delays signaling Indian API supply tightening that would compress generic competitor margins.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA's accelerated pathway compresses development timelines for novel lower esophageal sphincter modulators. |
| Outpatient Center Partnership Network | Same-day endoscopic protocols capture volume migration from hospital-based gastroenterology suites. |
| High-Resolution Manometry Integration | Precision injection guidance reduces dose variability and extends therapeutic window before surgical referral. |
| Compounding Pharmacy Alliance | State-certified sterile preparation relationships enable phosphodiesterase protocol standardization outside traditional distribution. |
| EMA MDR Combination Product Filing | Device-drug designation for injection delivery systems creates exclusivity extensions in European markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gastroenterology practice directors, formulary access managers at regional payers, regulatory affairs leads at biologics manufacturers, and compounding pharmacy operators with secondary validation against FDA orphan drug designations, ClinicalTrials.gov entries, CMS Medicare procedure databases, and EMA MDR filings. Bottom-up prescription volume modeling and top-down therapeutic category sizing were cross-checked for consistency.
Historical reference periods anchored the projection horizon through manometric procedure volume trends and prior authorization approval rate trajectories. The analytical framework modeled segmentation across drug mechanism class, indication severity, end-user site-of-care, and delivery mode complexity. CAGRs were derived from fitted growth curves calibrated to tertiary center expansion rates and outpatient center licensing patterns. Forecast inputs incorporated FDA review queue status for pipeline neuromodulators and EMA MDR transition timelines for injection device reclassification.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA biologics manufacturing inspection frequency and state-level compounding pharmacy enforcement variability. A model refresh is warranted upon material change in CMS site-of-service reimbursement differentials.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Global Antiemetic Drugs Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Benzodiazepine Drugs Market
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Asia Pacific Drug Development Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market