
 Blood Plasma Market | 2026-2036
Blood Plasma Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Plasma Market Intelligence
New guidance from the World Health Organization on plasma quality and safety is rebalancing the cost-of-entry calculus for collection center operators. This environment favors large-scale operators like CSL, which leverages its extensive global network of collection centers. Grifols sustains its market position through significant investment in fractionation capacity. Takeda competes on the basis of a diversified portfolio that includes treatments for rare diseases.
Blood plasma is the straw-colored liquid component of blood, comprising approximately 92% water and 8% proteins like albumin and globulins. Its primary commercial purpose is for direct transfusion and as the starting material for manufacturing life-saving plasma-derived therapies. Plasma derivatives, particularly immunoglobulins, constitute the highest value product segment. Within applications, treatments for immunodeficiency disorders represent a significant growth area, while trauma care remains a high-volume use case.
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA dictates market access and product standards. These agencies enforce strict guidelines on donor screening, plasma collection, and the manufacturing of plasma derivatives to ensure patient safety. Stakeholders must navigate the ethical and logistical challenges of increasing plasma collection volumes without compromising donor health or product quality.
Market Dynamics
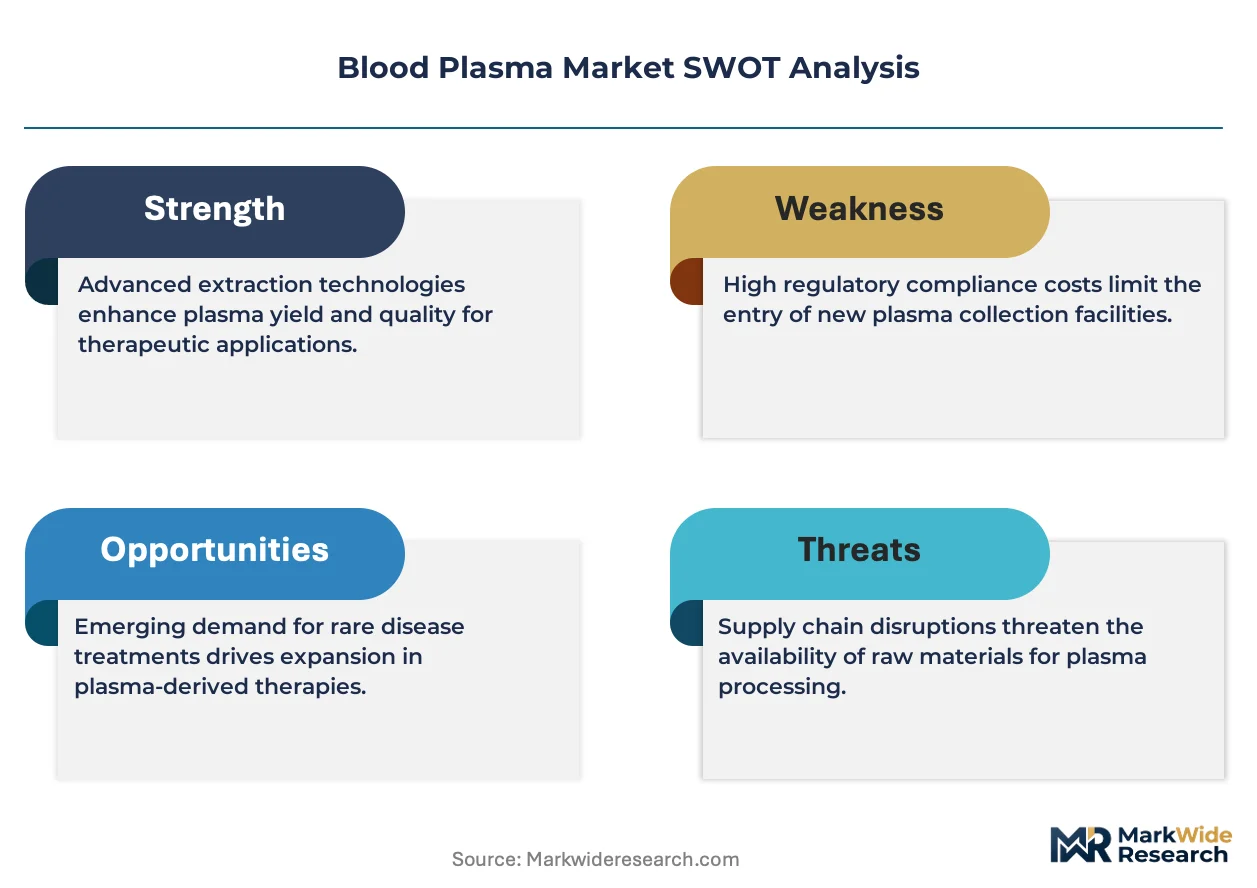
The central dynamic shaping the blood plasma market is the tightening of global quality and safety standards, exemplified by new WHO guidance. This pressure elevates the operational complexity and cost of plasma collection, directly influencing supply availability for fractionation and favoring large-scale operators.
Growth Catalysts
- Advanced Fractionation:Improvements in chromatography and filtration technologies are increasing the yield and purity of plasma derivatives, particularly immunoglobulins, from a fixed volume of source plasma.
- Immunodeficiency Treatment:A rising incidence of primary and secondary immunodeficiency disorders provides a sustained demand driver for immunoglobulin replacement therapies, a core application segment.
- Collection Infrastructure:The high density of plasma collection centers in the United States, supported by a defined regulatory framework, creates a concentrated source of raw material for the global supply chain.
Market Restraints
- Donor Screening Regulations:Stringent donor eligibility criteria enforced by agencies like the FDA and EMA limit the available donor pool, directly constraining the volume of source plasma that can be collected.
- Fractionation Capex:The substantial capital investment required to construct and validate plasma fractionation facilities that meet cGMP standards acts as a significant barrier to new market entrants.
- Source Plasma Reliance:The market's dependence on a few countries, primarily the United States, for a large portion of its source plasma creates geopolitical and logistical vulnerabilities in the supply chain.
Strategic Opportunities
- Emerging Market Infrastructure:Building out plasma collection and fractionation capabilities in large, under-served markets within Asia-Pacific presents a long-term growth pathway to diversify global supply sources.
- Novel Albumin Uses:Expanding the application of albumin as an excipient in drug formulation and a component in advanced cell culture media opens new, non-traditional revenue streams for fractionators.
- Recombinant Technologies:Investment in the development of recombinant alternatives to plasma-derived clotting factors and immunoglobulins offers a path to mitigate source plasma supply constraints.
Industry Challenges
- Donor Health Management:Collection centers face the continuous operational challenge of managing donor health, ensuring compliance with donation frequency limits, and mitigating the risk of long-term health impacts.
- Regulatory Harmonization:Manufacturers must navigate significant differences in product approval and facility inspection protocols between the FDA, EMA, and China's NMPA, delaying market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Plasma Market |
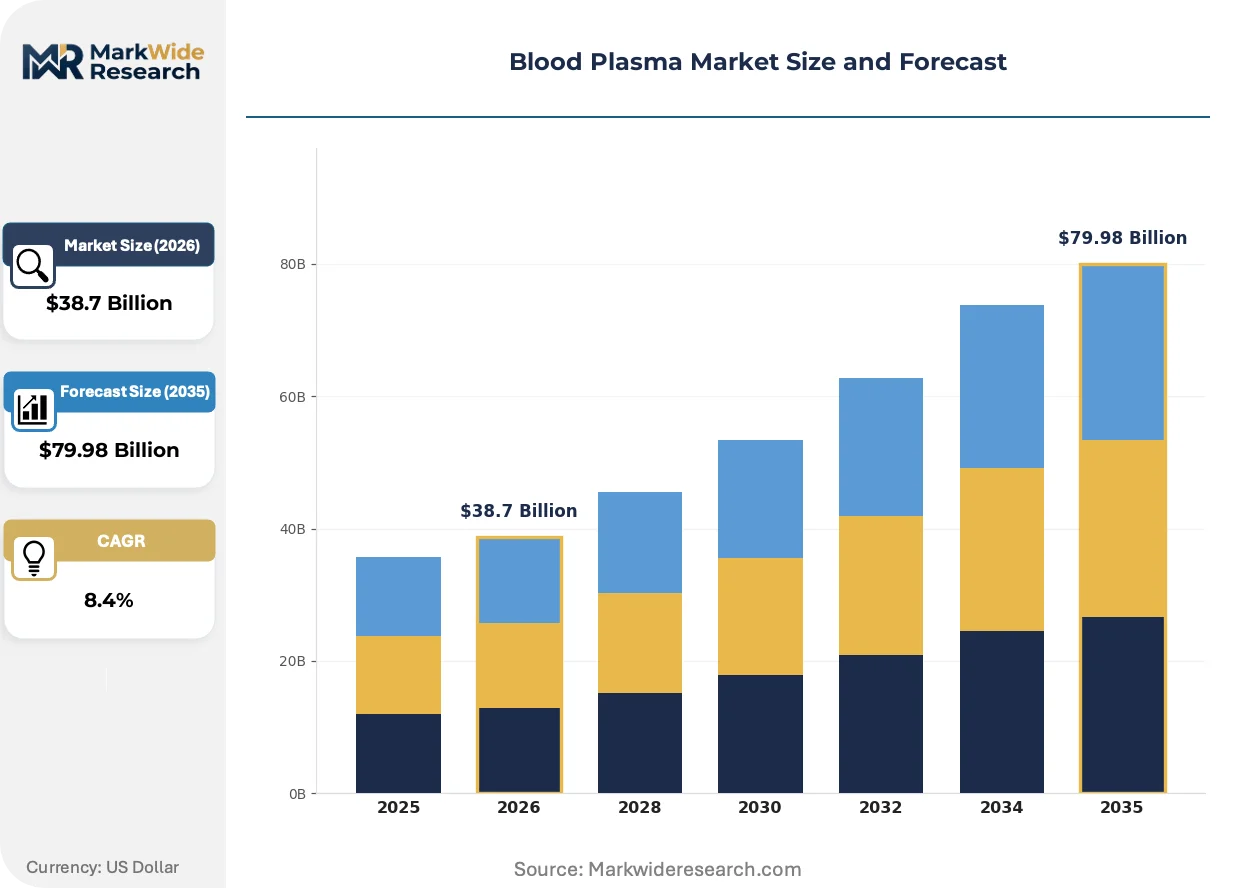
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Frozen Plasma, Cryoprecipitate, Plasma Derivatives, Prothrombin Complex Concentrates End User: Hospitals, Blood Banks, Academic Research Institutes, Diagnostic Laboratories Application: Blood Transfusion, Hemophilia Treatment, Trauma Care, Immunodeficiency Disorders Distribution Channel: Direct Sales, Retail Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | CSL, Grifols, Takeda, Octapharma, Kedrion Biopharma, Biotest, LFB, SK Plasma, GC Biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Plasma Market Strategic Shifts & Innovations
Technological advancements in plasma processing are converging with stricter regulatory mandates for quality and safety. This convergence is driving a market-wide push for greater efficiency in fractionation and more sophisticated methods of ensuring product traceability from donor to patient.
Automated apheresis technologies and integrated digital donor management software are being deployed to streamline the collection process. Large, multi-center plasma operators are the primary adopters, seeking to improve throughput and data accuracy. The high capital cost of these integrated systems is consolidating the collection segment around operators with significant scale and financial resources.
The World Health Organization's updated guidance on the quality and safety of plasma for fractionation is setting a new global benchmark. This guidance pressures national regulatory bodies like the EMA and NMPA to harmonize their standards for donor management and material traceability. Small, independent collection centers are most impacted, facing higher operational costs to meet these more stringent international requirements.
A notable shift in care delivery is moving the administration of immunoglobulin therapies from hospital infusion centers to home care settings. This trend disrupts traditional hospital distribution channels, favoring specialty pharmacies and direct-to-patient service providers. This model is most advanced in the United States, driven by patient preference and cost-containment initiatives from payers.
Blood Plasma Market Segmentation
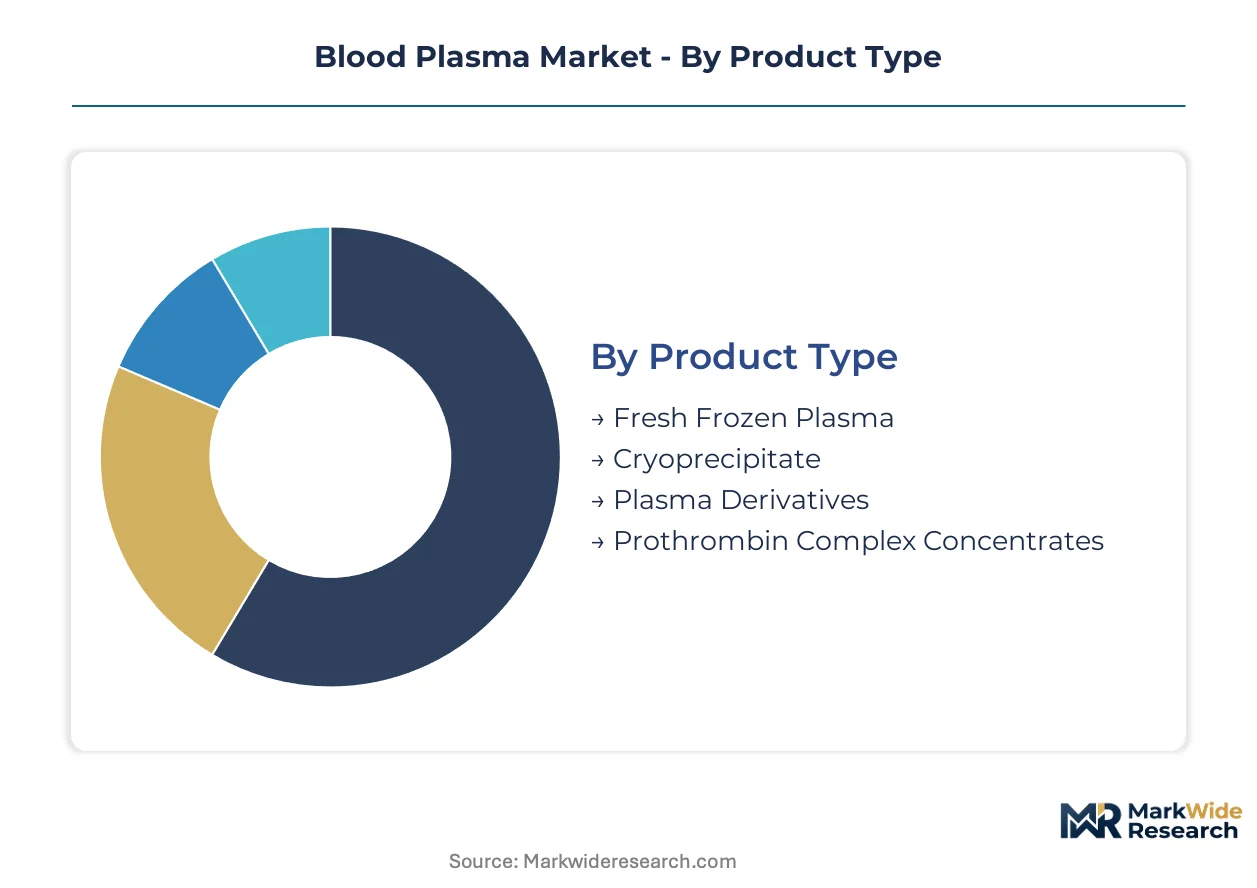
The blood plasma market segments reveal distinct value propositions and regulatory pathways for various products and end-users. Understanding these divisions helps stakeholders identify areas of high growth, specialized demand, and operational complexity. Each segment navigates specific regulatory requirements and market dynamics.
Product Type:
The certification burden significantly differentiates product types, with plasma derivatives requiring extensive regulatory approvals from bodies like the US FDA and European Medicines Agency. These approvals cover manufacturing processes and clinical efficacy.
- Plasma Derivatives:These highly processed therapeutic products include immunoglobulins, albumin, and clotting factors, derived through complex fractionation processes. Demand for immunoglobulins is concentrating in the United States, driven by the rising incidence of primary and secondary immunodeficiency disorders.
- Prothrombin Complex Concentrates:These products contain vitamin K-dependent coagulation factors (II, VII, IX, X) and are used for rapid reversal of anticoagulant effects. Their demand is increasing in trauma care settings across Europe, where rapid intervention for bleeding disorders is critical.
- Fresh Frozen Plasma:This component of whole blood contains all coagulation factors and plasma proteins, requiring strict storage conditions.
- Cryoprecipitate:Derived from fresh frozen plasma, this concentrate is rich in Factor VIII, von Willebrand factor, and fibrinogen for specific bleeding conditions.
Plasma Derivatives sit at the top of the volume ranking, with Prothrombin Complex Concentrates climbing the fastest.
End User:
The functional application of blood plasma products varies significantly across end-user segments, dictating the volume and type of plasma components required. Each setting addresses distinct patient populations and medical needs.
- Hospitals:These institutions represent the primary point of care for acute and chronic conditions requiring plasma transfusions and derivative therapies. Demand is particularly high in major medical centers in Germany for managing severe trauma and surgical interventions.
- Blood Banks:These facilities are critical for the collection, processing, and storage of whole blood and plasma components for various medical applications. Their operational efficiency in Canada directly impacts the availability of source plasma for fractionation.
- Academic Research Institutes:These entities utilize plasma components for scientific study, drug discovery, and the development of novel diagnostic assays.
- Diagnostic Laboratories:These facilities employ plasma for various diagnostic tests, including coagulation panels and disease marker detection.
Hospitals command the largest share of plasma product consumption, while Diagnostic Laboratories are expanding their utilization at a notable rate.
Application:
The scale of patient need and therapeutic impact defines the various applications for blood plasma, influencing demand patterns and product development priorities. These applications range from life-saving interventions to chronic disease management.
- Immunodeficiency Disorders:Treatments for these conditions, primarily using immunoglobulin replacement therapies, represent a significant growth area due to rising diagnoses. Demand for these therapies is concentrating in the United States, driven by comprehensive diagnostic capabilities and patient access programs.
- Trauma Care:This application involves rapid administration of plasma products to manage severe bleeding and shock in emergency situations. High-volume demand exists in military hospitals and major urban trauma centers in France for immediate patient stabilization.
- Blood Transfusion:This traditional application involves replacing lost blood volume or specific blood components in patients with anemia or surgical blood loss.
- Hemophilia Treatment:This application utilizes plasma-derived clotting factors to manage bleeding episodes in individuals with inherited bleeding disorders.
Trauma Care applications account for substantial plasma volumes, while Immunodeficiency Disorders are driving the steepest expansion trajectory.
Distribution Channel:
The customer type and geographic reach significantly influence the choice and effectiveness of distribution channels for blood plasma products. Each channel caters to specific logistical requirements and patient access models.
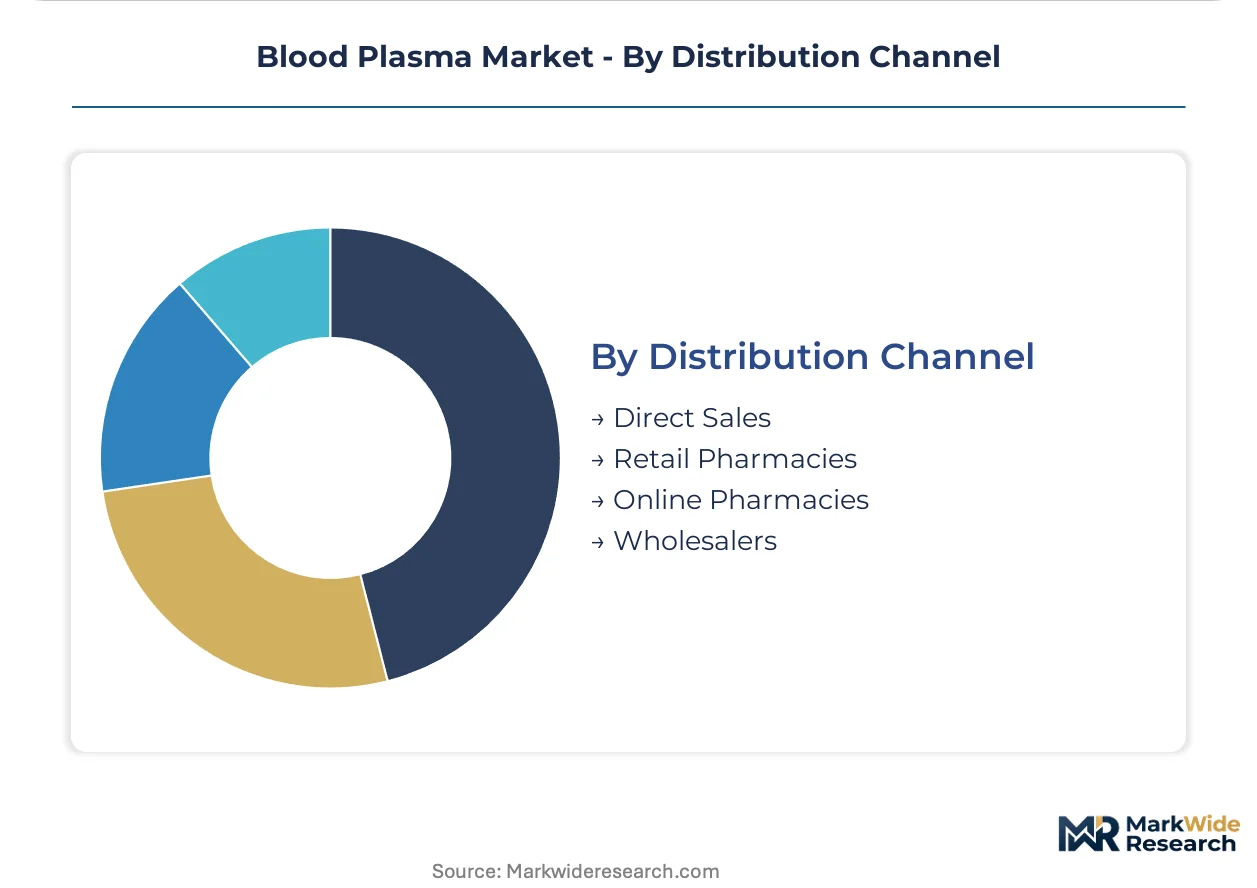
- Direct Sales:Manufacturers directly supply large institutional clients like hospitals and major blood banks, ensuring controlled logistics and product integrity. This channel is crucial for high-value plasma derivatives in Japan, where specialized cold chain management is paramount.
- Wholesalers:These intermediaries manage bulk distribution to a wide network of smaller hospitals, clinics, and pharmacies, providing extensive market penetration. Their network is vital for reaching diverse healthcare providers across rural areas of Australia.
- Retail Pharmacies:These outlets dispense plasma-derived therapies, particularly immunoglobulins for home care, to individual patients with prescriptions.
- Online Pharmacies:This emerging channel offers convenience and discrete delivery of certain plasma products to patients, especially for chronic conditions.
Direct Sales channels facilitate the largest volume of specialized plasma product delivery, with Online Pharmacies demonstrating rapid growth in patient accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The highly specialized medical and scientific workforce anchoring key geographies drives innovation and operational excellence in the blood plasma market. These regions exhibit robust demand for plasma-derived therapies and possess established regulatory frameworks. Strategic investments in collection and fractionation infrastructure further solidify their market positions.
United States
A high incidence of chronic diseases and a comprehensive healthcare system fuel significant demand for plasma derivatives. The US FDA enforces strict guidelines on donor screening and product manufacturing, ensuring patient safety. Major metropolitan areas like Houston and Los Angeles host extensive networks of plasma collection centers, providing critical raw material for global supply.
Germany
Strong demand for trauma care and advanced medical interventions supports the consumption of plasma products in Germany. The European Medicines Agency (EMA) sets rigorous standards for the approval and quality of plasma-derived therapies across the region. Medical centers in cities such as Berlin and Munich are significant end-users for prothrombin complex concentrates.
France
Trauma care and emergency medicine applications represent a high-volume use case for blood plasma products in France. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) regulates the collection and distribution of plasma, ensuring national health security. Military hospitals and major urban trauma centers in Paris and Lyon maintain substantial demand for immediate patient stabilization.
Canada
The efficient operational structure of blood banks in Canada ensures a steady supply of source plasma for various medical applications. Health Canada oversees donor eligibility and the processing of plasma components, impacting national availability. Plasma collection centers in provinces like Ontario and Quebec are vital contributors to the global fractionation supply chain.
Japan
Specialized cold chain management and a focus on high-value plasma derivatives characterize the Japanese market. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures stringent quality control for all plasma products entering the healthcare system. Major hospitals in Tokyo and Osaka are primary recipients of advanced immunoglobulin therapies, requiring precise logistical support.
Blood Plasma Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the blood plasma market. The industry structure exhibits a tiered consolidation, with large-scale operators dominating collection and fractionation. Strategic archetypes include integrated global players, regional specialists, and niche therapeutic developers. Competitive moves center on capacity expansion to meet rising demand and portfolio diversification into novel plasma-derived therapies.
Within the integrated global player archetype, CSL and Grifols exemplify companies with extensive global networks and significant investment in fractionation capacity. CSL, an Australian-headquartered biopharmaceutical company, leverages its broad collection infrastructure to maintain market leadership in plasma-derived therapies, ensuring a consistent supply of raw material. Grifols, a Spanish multinational, sustains its market position through substantial capital expenditure in advanced fractionation technologies and a strategic focus on expanding its plasma collection footprint globally. Takeda, a Japanese pharmaceutical giant, occupies a position as a diversified portfolio player, including treatments for rare diseases, further illustrating the varying strategic approaches within the sector.
| Leading Market Players |
|---|
| CSL |
| Grifols |
| Takeda |
| Octapharma |
| Kedrion Biopharma |
| Biotest |
| LFB |
| SK Plasma |
| GC Biopharma |
| Others |
Cost & Logistics Intelligence
The value divergence between highly processed plasma derivatives and less refined plasma components significantly shapes both pricing models and specialized supply chain configurations. This stratification reflects varying manufacturing and regulatory complexities.
Pricing Analysis
Bundled service models for high-value plasma derivatives contrast sharply with unbundled, transactional pricing for fresh frozen plasma. The dominant pricing structure is contract-based long-term offtake for derivatives, driven by quality certification levels from agencies like the US FDA and EMA, and by volume scale. Pricing pressure stems from stringent donor screening regulations that constrain source plasma availability. Hospitals, requiring life-saving therapies, exhibit lower price sensitivity compared to diagnostic laboratories acquiring plasma for routine testing.
Supply Chain Analysis
National regulatory frameworks, particularly in the United States and Canada, effectively mandate domestic sourcing for a significant portion of the global plasma supply. The market draws from source plasma primarily concentrated in the United States, Germany, and Canada. Key raw material dependencies include specialized collection bags and donor screening reagents. A structural risk involves the geopolitical vulnerabilities associated with this heavy reliance on a few countries for source plasma. Distribution runs through direct sales channels for high-value derivatives to institutional clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood plasma market presents a late-cycle quality story, driven by a pronounced demand-shift towards premium immunoglobulin therapies for immunodeficiency disorders. This evolution emphasizes product purity, safety, and advanced therapeutic applications over raw volume.
For Market Incumbents: Anchor existing market share by expanding plasma collection infrastructure in underserved markets within Asia-Pacific, mitigating source plasma supply constraints. Invest in advanced fractionation technologies to improve yield and purity of high-value derivatives like immunoglobulins, countering the threat from recombinant alternatives. Control over the donor-to-patient value chain through certification investment ensures compliance with evolving WHO guidance.
For New Entrants and Emerging Players: A price-point gap exists between established premium plasma derivatives and more accessible, basic plasma components, offering an entry point. Target emerging markets with nascent healthcare infrastructure for building out plasma collection and fractionation capabilities. Focus on novel albumin uses as an excipient in drug formulation, leveraging a specific go-to-market angle through partnerships with biopharmaceutical companies.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory complexity and capital expenditure for fractionation facilities create high barriers to entry. Long-term viability over a 5-10 year window favors integrated global players with extensive collection networks and advanced processing capabilities. Target archetype: mid-sized, vertically integrated specialists with strong regional collection assets or unique fractionation technologies. A signal to watch is the pace of regulatory harmonization across major markets, indicating reduced operational friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Global Plasma Collection Network | Secures raw material supply for fractionators, reducing geopolitical supply chain vulnerabilities. |
| Invest in Advanced Fractionation Technologies | Improves yield and purity of immunoglobulins, meeting stricter WHO quality standards. |
| Develop Recombinant Alternatives | Mitigates dependence on human plasma, addressing donor pool limitations and ethical concerns. |
| Pursue Emerging Market Entry | Diversifies supply sources and taps into underserved patient populations in Asia-Pacific. |
| Strengthen Regulatory Compliance | Ensures market access and product acceptance across diverse agencies like the US FDA and EMA. |
Research Approach
Multiple input streams — industry executive interviews, regulatory affairs specialist consultations, and clinician perspectives — were reconciled with extensive secondary research. Primary insights from leaders at CSL and Grifols informed market dynamics. Secondary data sources included WHO guidance documents, US FDA and EMA regulatory submissions, and relevant academic literature. This approach integrated bottom-up market intelligence with top-down industry validations.
Historical market trends were cross-referenced with expert panel input to construct the analytical framework across the analysis window. Segmentation dimensions modeled included product type, end user, application, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from a blend of past performance and projected demand drivers. Key forecast inputs included immunodeficiency disorder incidence rates and plasma fractionation capacity expansions.
Caveats apply where unforeseen advancements in recombinant technologies or significant geopolitical supply disruptions could materially shift the outlook. Forecasts reflect prevailing regulatory environments and current R&D pipelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Neutropenia Treatment Market
Hematology
Apheresis Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Rare Hematology Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Anemia Drugs Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market