
 Ampicillin Drugs Market | 2026-2036
Ampicillin Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Ampicillin Drugs Market Outlook
Specialized fermentation technologist availability is collapsing across Western antibiotic manufacturing hubs, constraining batch consistency and yield optimization for sterile injectable output. Fresenius Kabi leverages captive parenteral manufacturing infrastructure to sustain supply commitments to European hospital networks. Cipla anchors its position through backward integration into active pharmaceutical ingredient synthesis, securing cost leverage on oral solid doses. Shandong Lukang Pharmaceutical Group dominates bulk ampicillin trihydrate production, occupying the upstream tier that feeds formulation specialists globally.
Ampicillin drugs comprise beta-lactam antibacterial agents synthesized through fermentation-derived 6-aminopenicillanic acid followed by acylation with D-phenylglycine, formulated across multiple dose strengths and release profiles for gram-positive and select gram-negative pathogen coverage. The injection segment leads hospital procurement volumes due to severe infection protocols requiring rapid serum concentration attainment, while oral suspension formulations serve pediatric and geriatric populations where swallowing compliance limits tablet utilization. Retail pharmacy channels capture margin pools on outpatient respiratory and urinary tract infection scripts, though hospital tenders concentrate volume leverage and exert downward pressure on unit economics.
FDA cGMP enforcement and EMA's penicillin allergen labeling mandates shape product standards and cross-border market access conditions for manufacturers seeking multi-jurisdictional registration. India's CDSCO and China's NMPA impose divergent bioequivalence and stability testing protocols that fragment regulatory submission requirements for generic entrants. Stakeholders must monitor evolving antimicrobial stewardship protocols and resistance surveillance thresholds that determine formulary inclusion and reimbursement tiers for first-line penicillin-class therapies.
Market Dynamics
Hospital procurement consolidation across emerging health systems is compressing margins for sterile injectable manufacturers while simultaneously locking in multi-year supply commitments that reshape capacity planning cycles.
Growth Catalysts
- WHO Prequalification Programs:National essential medicines lists in low-income countries increasingly require WHO-prequalified ampicillin suppliers, expanding addressable demand for certified manufacturers.
- Injectable Protocol Dominance:Severe sepsis and pneumonia treatment guidelines in tertiary hospitals mandate IV ampicillin as first-line therapy, sustaining volume pull through institutional channels.
- China's NMPA Streamlining:Accelerated generic approval pathways for essential antibiotics reduce time-to-market for domestic producers targeting hospital tenders.
Market Restraints
- Fermentation Input Volatility:Corn steep liquor and soybean meal price swings directly impact 6-aminopenicillanic acid production economics, squeezing batch-level margins for fermentation-dependent manufacturers.
- Western Technologist Scarcity:Retiring antibiotic fermentation specialists in Germany and Italy constrain knowledge transfer for sterile injectable yield optimization.
- Carbapenem Substitution Pressure:Extended-spectrum beta-lactamase prevalence in Indian and Chinese hospital settings drives formulary displacement of ampicillin for severe gram-negative infections.
Strategic Opportunities
- Pediatric Oral Suspension Gap:Underpenetrated African markets lack stable supply of palatable ampicillin suspensions for childhood pneumonia protocols, creating white space for taste-masked formulation specialists.
- EMA Green Procurement Incentives:Environmental manufacturing footprint scoring in European hospital tenders rewards fermentation facilities with renewable energy integration and solvent recovery systems.
- Continuous Manufacturing Convergence:Integration of process analytical technology with traditional batch fermentation enables real-time release testing that compresses sterile injectable lead times.
Industry Challenges
- Specialized Fermentation Talent Pipeline Collapse:University microbiology programs in the United States and United Kingdom have shuttered industrial antibiotic fermentation tracks, forcing manufacturers to internalize multi-year apprenticeship programs.
- Dual cGMP-EMA Compliance Burden:Simultaneous FDA and European inspections for sterile penicillin facilities require redundant quality systems and documentation protocols that extend facility qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ampicillin Drugs Market |
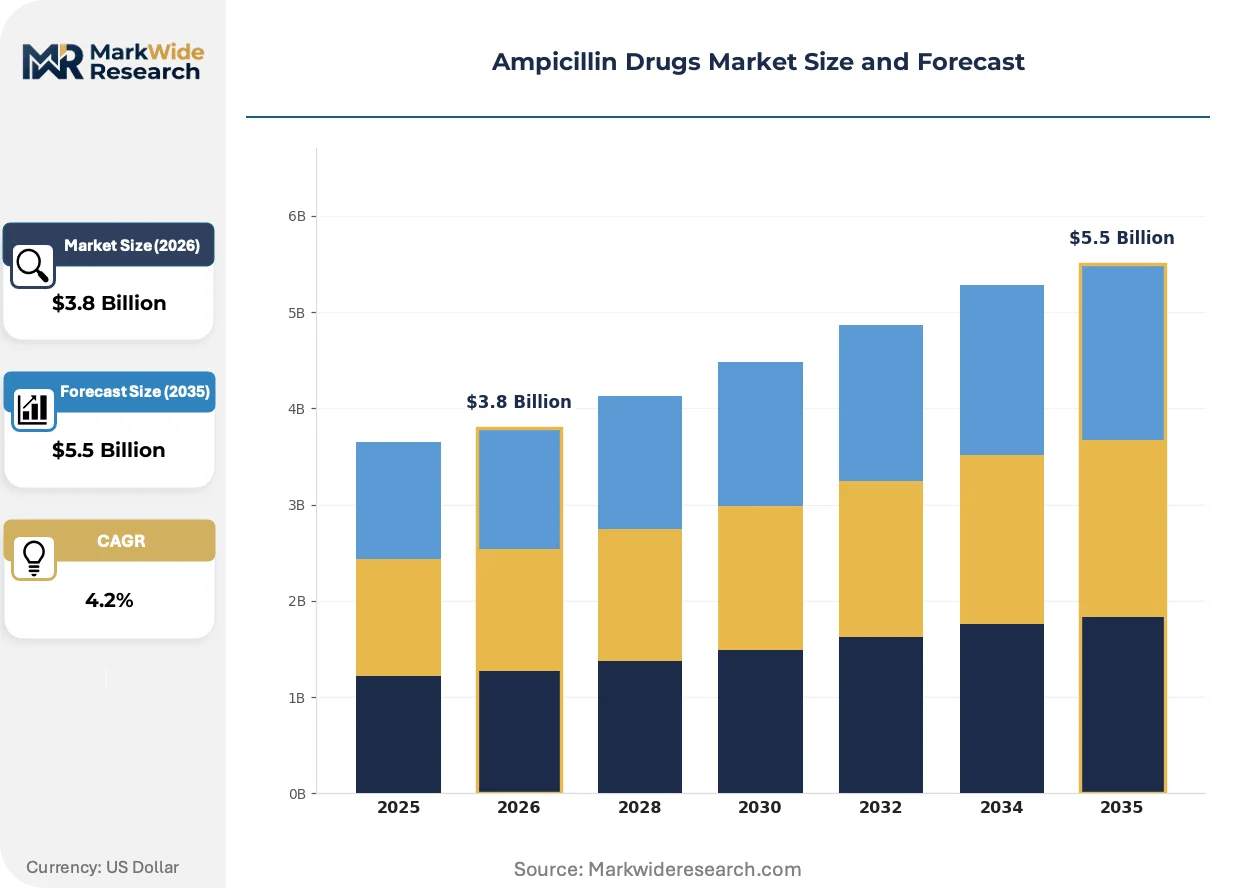
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injections, Oral Suspension Application: Respiratory Infections, Gastrointestinal Infections, Skin Infections, Urinary Tract Infections End User: Hospitals, Clinics, Retail Pharmacies, Homecare Dose Form: Standard Dose, High Dose, Extended Release, Syringe |
| Companies Covered | Pfizer, Fresenius Kabi, Cipla, Viatris, Sanofi, ACS Dobfar, DSM (Koninklijke DSM N.V.), Shandong Lukang Pharmaceutical Group, North China Pharmaceutical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ampicillin Drugs Market Strategic Shifts
Antimicrobial stewardship protocols and manufacturing technology migration are jointly restructuring how ampicillin is produced, procured, and prescribed across institutional settings.
Continuous processing technology for sterile injectable formulation is bifurcating competitive positioning between capital-intensive integrated manufacturers and traditional batch-oriented compounders. European hospital networks with centralized pharmacy operations are piloting unit-dose ready-to-administer bags that eliminate ward-level reconstitution. This technology compression is marginalizing smaller compounders lacking blow-fill-seal infrastructure while rewarding Fresenius Kabi and similar parenteral specialists with tender advantages.
EMA's penicillin allergen labeling mandates under the Medical Device Regulation framework now require explicit cross-reactivity warnings on secondary packaging. Manufacturers serving European markets must redesign carton inserts and implement serialization systems that track lot-specific allergen batch testing. Oral solid dose exporters to Germany and France face the steepest compliance costs, with reformulation requirements for excipient disclosure extending registration timelines.
Hospital purchasing consortiums in India are consolidating antibiotic procurement through state-level tendering platforms that disaggregate traditional distributor networks. Tamil Nadu and Rajasthan medical services corporations now aggregate demand across district hospitals, compressing price discovery cycles from quarterly to monthly intervals. This channel concentration is most visible in southern Indian states where public sector volumes exceed private hospital consumption.
Ampicillin Drugs Market Segmentation
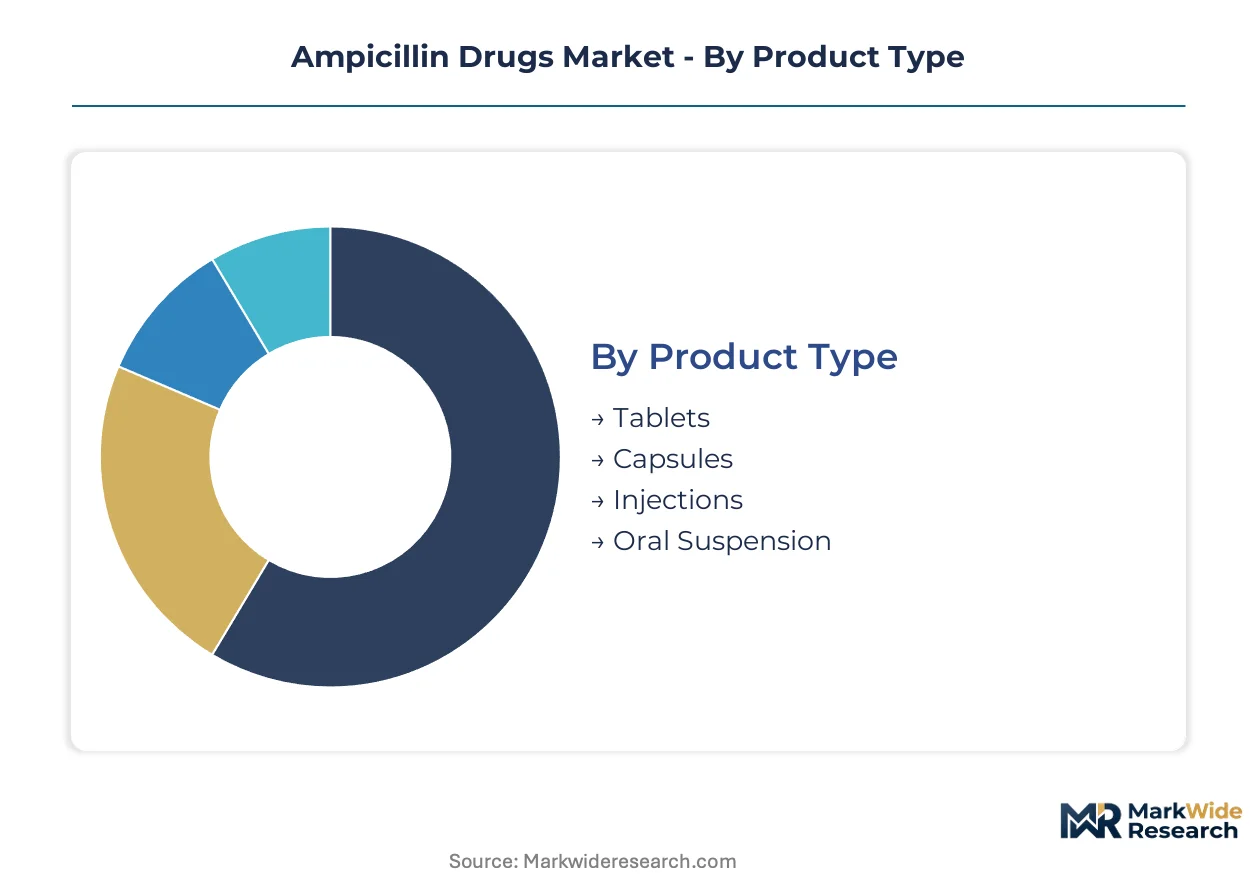
Ampicillin's therapeutic versatility necessitates granular segmentation across formulation physics, clinical protocols, and procurement channels. Each dimension reveals distinct margin structures and regulatory compliance burdens that shape manufacturer specialization.
Product Type:
Domestic production dominates oral solid doses in India and China, while export markets pull sterile injectables from European contract manufacturers.
- Tablets:Compressed ampicillin trihydrate with standard excipient matrices for adult outpatient compliance. Demand concentrates in Indian retail pharmacy chains where state tendering platforms aggregate district hospital procurement, compressing unit economics through volume consolidation.
- Injections:Sterile parenteral formulations requiring aseptic processing and endotoxin-controlled water systems for rapid serum concentration attainment. European hospital networks with centralized pharmacy operations drive specifications for unit-dose ready-to-administer bags, marginalizing compounders lacking blow-fill-seal infrastructure.
- Capsules:Gelatin-encapsulated powder blends offering taste masking for adult patients with tablet swallowing difficulties. Brazilian and Mexican distributors favor this format for private clinic channels.
- Oral Suspension:Palatable liquid formulations with suspension stabilizers for pediatric and geriatric populations. Supply gaps persist in African markets where cold chain limitations constrain stability.
Injections command the established base in institutional procurement. The steepest expansion runs through oral suspension as WHO prequalification programs expand childhood pneumonia protocol access.
Application:
Cost tier stratification separates premium hospital-grade specifications from economy retail formats across infection type indications.
- Respiratory Infections:Community-acquired pneumonia and bronchitis protocols drive first-line penicillin-class prescribing. Tertiary hospitals in Tamil Nadu and Rajasthan medical services corporations aggregate demand through state-level tendering platforms.
- Urinary Tract Infections:Uncomplicated cystitis and pyelonephritis treatment where rapid bacterial clearance outweighs resistance surveillance concerns. Retail pharmacy chains in Germany and France capture outpatient script volumes.
- Gastrointestinal Infections:Typhoid fever and enteric fever protocols in South Asian and sub-Saharan African settings. CDSCO bioequivalence requirements fragment generic submission pathways for enteric-coated variants.
- Skin Infections:Cellulitis and wound infection coverage where gram-positive pathogen dominance sustains ampicillin relevance. Dermatology clinics in São Paulo and Mexico City favor combination therapy approaches.
Respiratory applications anchor volume commitments. Urinary tract infection segments are climbing fastest as outpatient diagnostic accessibility expands.
End User:
Customer type determines packaging specifications, cold chain requirements, and regulatory documentation intensity.
- Hospitals:Tertiary and secondary institutions with centralized pharmacy operations and antimicrobial stewardship committees. EMA penicillin allergen labeling mandates under Medical Device Regulation framework require explicit cross-reactivity warnings on secondary packaging.
- Retail Pharmacies:Community dispensaries and chain drugstores serving outpatient respiratory and urinary tract infection scripts. Margin pools exceed hospital tenders but volume fragmentation complicates inventory planning.
- Clinics:Primary care and specialty outpatient settings with limited on-site pharmacy capabilities. NMPA streamlined generic approval pathways accelerate domestic producer access.
- Homecare:Post-discharge IV therapy and long-term antibiotic prophylaxis requiring patient or caregiver administration training. Fresenius Kabi's captive parenteral manufacturing infrastructure sustains supply commitments to European networks.
Hospitals dominate procurement leverage. Homecare segments are expanding most quickly as centralized pharmacy outsourcing extends post-acute coverage.
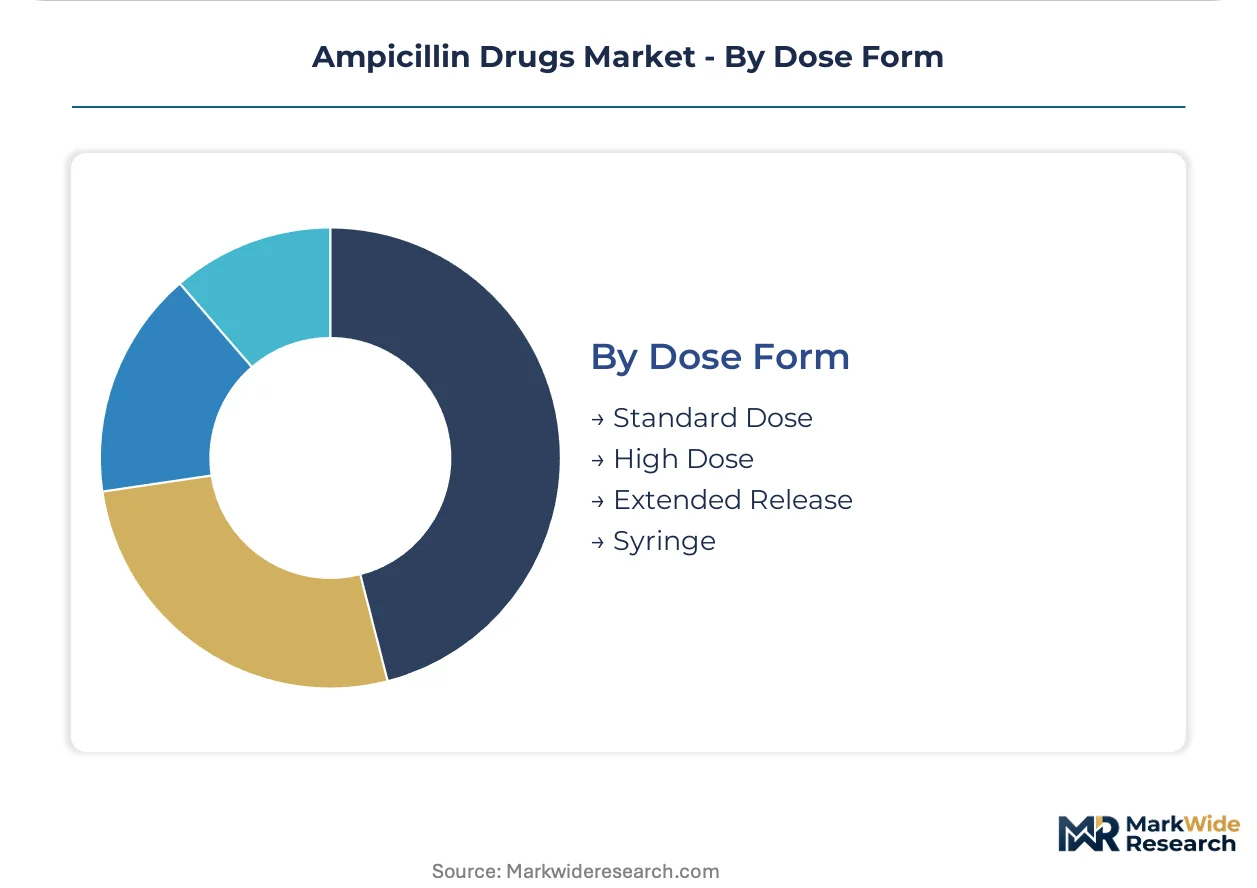
Dose Form:
Supply concentration in bulk API production shapes downstream formulation economics across release profile variants.
- Standard Dose:Conventional immediate-release formulations with established pharmacokinetic profiles for susceptible pathogen coverage. Shandong Lukang Pharmaceutical Group's bulk ampicillin trihydrate production feeds global formulation specialists.
- High Dose:Elevated strength presentations for severe sepsis protocols and penicillin-resistant organism coverage. FDA cGMP enforcement shapes product standards for multi-jurisdictional registration seekers.
- Extended Release:Modified-release matrix technologies for prolonged serum concentration maintenance. Cipla's backward integration into API synthesis secures cost leverage on development timelines.
- Syringe:Pre-filled delivery systems eliminating ward-level reconstitution for emergency and anesthesia settings. Dual FDA-EMA compliance burden extends facility qualification timelines for sterile penicillin manufacturers.
Standard dose formulations anchor the volume base. Extended release variants are gaining share fastest as compliance optimization drives formulation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European hospital networks extract pricing concessions through centralized tenders that Indian state procurement platforms replicate at lower absolute levels, creating a dual-tier margin structure across developed and emerging health systems.
United States
FDA cGMP enforcement drives sterile injectable facility qualification costs upward, consolidating procurement among tertiary hospitals with centralized pharmacy operations. The IRA's drug pricing provisions exert indirect pressure on generic antibiotic reimbursement tiers. New Jersey and North Carolina host the densest clusters of parenteral manufacturing infrastructure serving institutional channels.
Germany
EMA penicillin allergen labeling mandates under the Medical Device Regulation framework impose secondary packaging redesign costs on exporters. The country's hospital purchasing consortiums pilot environmental manufacturing footprint scoring that rewards renewable energy integration. Bavaria anchors European fermentation expertise despite retiring technologist cohorts constraining knowledge transfer.
China
NMPA streamlined generic approval pathways accelerate domestic producer access to hospital tenders aggregating demand across provincial medical services corporations. Shandong Province dominates bulk ampicillin trihydrate synthesis feeding global formulation specialists. The country's dual carbon goals pressure fermentation facilities toward solvent recovery system investments.
India
CDSCO bioequivalence requirements fragment generic submission pathways for extended-release variants. Tamil Nadu and Rajasthan medical services corporations consolidate antibiotic procurement through state-level platforms disaggregating traditional distributor networks. Maharashtra hosts backward-integrated API manufacturers securing cost leverage on oral solid dose exports.
Brazil
ANVISA stability testing protocols for tropical climate zones extend registration timelines for oral suspension formulations. São Paulo's private clinic channels favor capsule formats for outpatient respiratory infection coverage. The country's national pharmaceutical regulator imposes divergent documentation requirements that complicate multi-jurisdictional filings.
Ampicillin Drugs Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with sterile injectable specialists commanding premium positioning while bulk API producers capture upstream margin pools. The market structures around three tiers: integrated parenteral manufacturers with captive infrastructure, backward-integrated generic houses controlling API synthesis, and formulation-dependent compounders sourcing active ingredients externally. Dominant competitive moves include capacity expansion in blow-fill-seal infrastructure and strategic partnerships bridging fermentation expertise gaps.
Among European parenteral specialists, Fresenius Kabi occupies a position exemplifying captive manufacturing infrastructure deployment. Indian generic houses Cipla and Viatris represent archetypes of backward integration into active pharmaceutical ingredient synthesis, securing cost structures that underpin oral solid dose competitiveness. Shandong Lukang Pharmaceutical Group anchors the upstream tier as a bulk ampicillin trihydrate producer feeding formulation specialists globally.
| Leading Market Players |
|---|
| Pfizer |
| Fresenius Kabi |
| Cipla |
| Viatris |
| Sanofi |
| ACS Dobfar |
| DSM (Koninklijke DSM N.V.) |
| Shandong Lukang Pharmaceutical Group |
| North China Pharmaceutical Corporation |
| Others |
Value Chain & Pricing Dynamics
Multi-year hospital tender contracts lock in supply access for sterile injectable manufacturers while compressing unit economics through volume aggregation. These arrangements tether pricing visibility to fermentation input cost trajectories and regulatory compliance burdens across FDA, EMA, and NMPA jurisdictions.
Pricing Analysis
The customization-premium spread separates standard oral solid doses from configured-to-order sterile injectables with blow-fill-seal packaging and unit-dose ready-to-administer specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from Indian state-level tendering platforms compressing price discovery cycles. Hospital procurement committees exhibit highest price sensitivity; homecare channels with patient training bundles show lowest.
Supply Chain Analysis
Inventory cycles for 6-aminopenicillanic acid extend lead times when corn steep liquor and soybean meal prices spike. Supply concentrates in China and India for bulk ampicillin trihydrate, with European contract manufacturers handling sterile formulation. Raw material dependencies center on fermentation substrates, D-phenylglycine acylation reagents, and endotoxin-controlled water systems. Single-source vulnerability runs through Shandong Province's bulk API dominance. Distribution runs through hospital purchasing consortiums and state medical services corporations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ampicillin's early-cycle expansion story rests on WHO prequalification programs unlocking low-income country procurement channels previously inaccessible to certified manufacturers.
For Market Incumbents: Shield market position through captive parenteral manufacturing infrastructure investments that marginalize batch-oriented compounders lacking blow-fill-seal capabilities. Deepen backward integration into active pharmaceutical ingredient synthesis to offset fermentation input volatility. Carbapenem substitution pressure in Indian and Chinese hospital settings demands defensive formulary retention strategies.
For New Entrants and Emerging Players: Lead with pediatric oral suspension formulations for underpenetrated African markets where cold chain limitations constrain stability and palatability gaps persist in childhood pneumonia protocols. Target taste-masked formulation specialization as the most penetrable segment. Pursue WHO prequalification as the primary go-to-market credential.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated parenteral manufacturers with fermentation expertise and captive sterile processing infrastructure. Long-term viability hinges on antimicrobial stewardship protocol alignment and resistance surveillance threshold compliance. Watch EMA green procurement incentives as the signal for environmental manufacturing footprint scoring becoming tender-determinative.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks national essential medicines list inclusion across low-income country procurement systems. |
| Blow-Fill-Seal Capacity Expansion | Secures tender advantages in European hospital networks piloting unit-dose ready-to-administer bags. |
| Backward API Integration | Insulates margin structures from 6-aminopenicillanic acid fermentation input volatility. |
| Green Manufacturing Certification | Captures EMA environmental footprint scoring incentives in centralized European tenders. |
| Pediatric Formulation Development | Addresses supply gaps in African markets lacking stable ampicillin suspension for childhood pneumonia protocols. |
Study Parameters
Initial hypotheses were tested against primary input from hospital procurement managers, regulatory affairs leads, fermentation technologists, and formulary directors and refined through secondary validation. Primary fieldwork drew from FDA filings, EMA submissions, CDSCO bioequivalence databases, and national essential medicines list documentation. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Variance decomposition across product type, application, end user, dose form, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from fitted growth curves applied to base-year estimates across the projection horizon. Forecast inputs incorporated antimicrobial stewardship protocol adoption curves and hospital procurement consolidation trajectories.
Forecasts assume regulatory continuity in FDA cGMP enforcement, EMA penicillin allergen labeling mandates, and NMPA streamlined generic approval pathways; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Asia Pacific Drug Development Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Italy OTC Drugs Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Efinaconazole Market