
 India Plasma Fractionation Market | 2026-2036
India Plasma Fractionation Market Size, Share, and Industry Trends Forecast 2026-2036
India Plasma Fractionation Market Insights
The India plasma fractionation landscape is recalibrating around a widening split between premium albumin and immunoglobulin products and commodity-grade coagulation factors. PlasmaGen BioSciences leverages its Bangalore facility to dominate domestic albumin supply for critical care units. Reliance Life Sciences anchors its position through backward integration into plasma collection networks across western India. Intas Pharmaceuticals competes by specializing in niche immunoglobulin formulations for neurological indications.
Plasma fractionation is the industrial separation of blood plasma into purified therapeutic proteins through ethanol precipitation, chromatography, or membrane filtration, yielding albumin, immunoglobulins, clotting factors, and fibrinogen for treating immunodeficiency, hemophilia, burn trauma, and liver disease. Chromatography-based purification commands premium positioning due to higher yield and viral safety margins compared to legacy precipitation methods. Hospitals represent the dominant end-user channel, absorbing the bulk of albumin and factor concentrates through centralized procurement tenders, while blood banks are emerging as a faster-growing outlet as the government expands plasma collection infrastructure under the National Blood Policy.
CDSCO mandates strict viral inactivation and Good Manufacturing Practice compliance for all plasma-derived products sold in India, raising barriers for imported substitutes and favoring domestic manufacturers with certified facilities. The PLI scheme for pharmaceuticals provides production-linked incentives that offset capital costs for fractionation plants, while BIS quality standards enforce batch consistency and cold-chain integrity across the distribution network. Stakeholders must monitor how state-level plasma donor registry expansion and evolving CDSCO biosimilar guidance reshape competitive access and pricing power in therapeutic proteins.
Market Dynamics
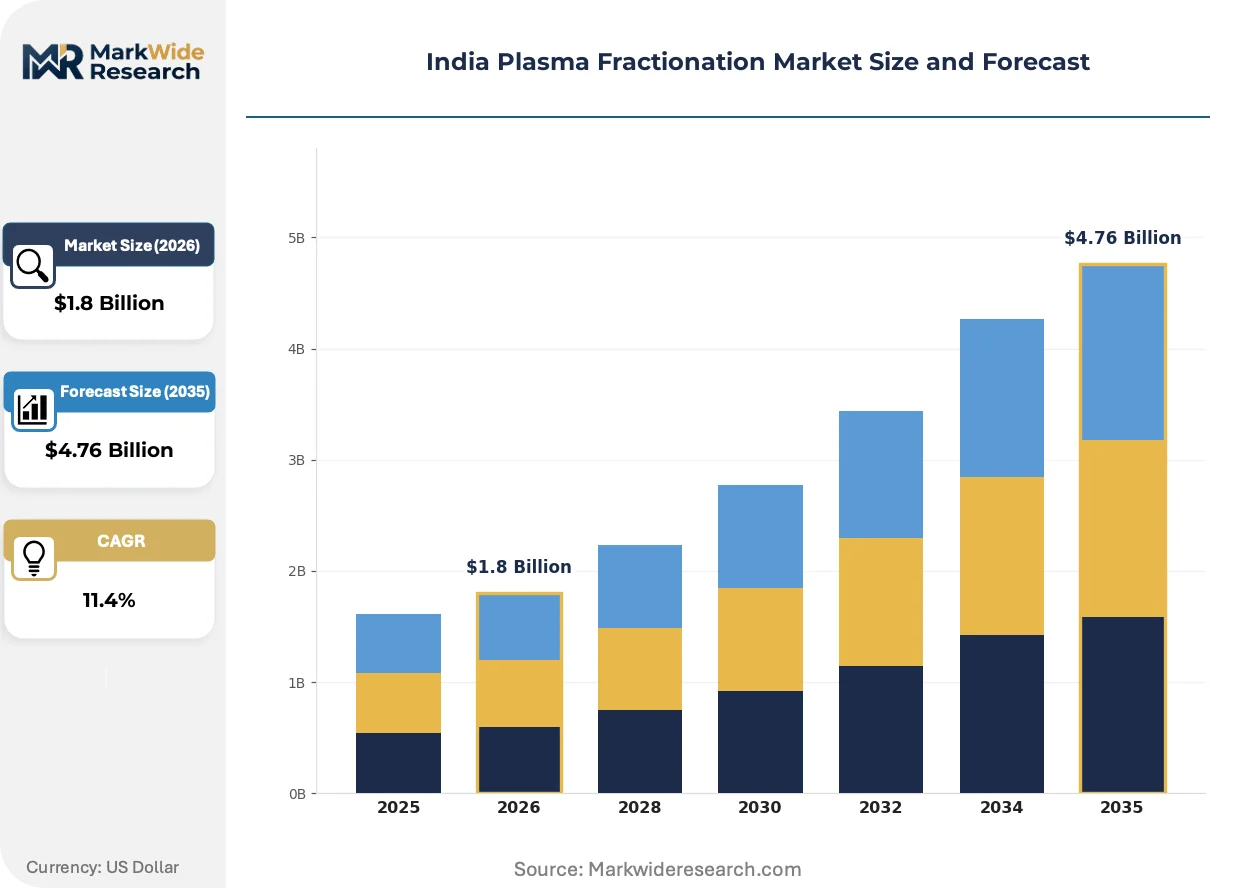
The India plasma fractionation market is recalibrating around CDSCO's tightened import guidelines and the PLI scheme's domestic manufacturing incentives, which together redirect capital toward in-house fractionation capacity and compress reliance on foreign-sourced plasma derivatives.
Growth Catalysts
- PLI scheme for domestic biologics:Production-linked incentives offset capital costs for fractionation plants, accelerating greenfield capacity announcements across western India.
- Surgical volume expansion:Tier-2 and tier-3 hospitals are scaling albumin and immunoglobulin procurement as elective procedure rates climb in Maharashtra and Gujarat.
- Cold-chain infrastructure maturation:Dedicated plasma collection and processing networks now support continuous operation at scale in high-density tertiary care corridors.
Market Restraints
- Import dependency for source plasma:Domestic collection volumes remain insufficient for fractionation feedstock, forcing reliance on US and European plasma suppliers subject to export quota volatility.
- Ethanol precipitation yield limitations:Legacy fractionation methods deliver lower protein recovery rates compared to chromatography, constraining unit economics for commodity-grade coagulation factors.
- CDSCO viral safety compliance costs:Mandatory inactivation protocols and GMP certification requirements raise fixed cost barriers for new market entrants.
Strategic Opportunities
- Neurological immunoglobulin applications:CIDP and myasthenia gravis treatment protocols are expanding off-label utilization, creating premium positioning for specialized formulations.
- Blood bank channel development:Government plasma collection infrastructure under the National Blood Policy is converting blood banks into direct supply nodes for fractionators.
- Chromatography-purification upgrade cycles:Viral safety margin advantages are driving hospital procurement preference toward higher-yield processing methods.
Industry Challenges
- Fractionation chemist scarcity:Specialized expertise in protein purification and viral inactivation protocols remains concentrated among a limited pool of trained practitioners.
- Batch certification timelines:CDSCO lot release procedures and BIS quality verification create working capital intensity across extended approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Plasma Fractionation Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Albumin, Immunoglobulin, Fibrinogen, Coagulation Factor Concentrates End User: Hospitals, Blood Banks, Individual Patients, Research Institutions Technology: Chromatography, Precipitation, Membrane Filtration, Ion Exchange Application: Therapeutic Use, Diagnostic Use, Research Use, Clinical Trials |
| Companies Covered | PlasmaGen BioSciences Pvt. Ltd., Reliance Life Sciences, Intas Pharmaceuticals Ltd., Virchow Biotech Private Limited, Bharat Serums and Vaccines Limited, Taj Pharmaceuticals Limited, Biocon Limited, Fusion Healthcare, Hemarus Therapeutics Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Plasma Fractionation Market Trends and Innovations
Technological substitution in purification methods, regulatory pressure on import dependency, and procurement centralization at hospital network level are together compressing traditional supply arrangements and rewarding integrated domestic operators.
Chromatography-based purification is absorbing market preference from ethanol precipitation across albumin and immunoglobulin production. Tertiary care hospitals in Mumbai, Ahmedabad, and Pune are specifying chromatography-derived products in centralized tenders. The technology is absorbing premium positioning as yield advantages and viral safety margins justify 15-20% price differentials in critical care procurement.
CDSCO's 2023 tightening of plasma import guidelines mandates enhanced documentation of donor traceability and viral screening for all imported source material. Foreign plasma suppliers face extended approval timelines and batch testing requirements. Domestic fractionators with certified collection networks are capturing share as hospital procurement committees prioritize supply security over unit cost.
Hospital network procurement consolidation is compressing distributor margins and favoring direct manufacturer relationships. Large hospital chains in Maharashtra and Gujarat are unbundling after-sales service from product supply and negotiating multi-year albumin and factor concentrate agreements. This pattern is most visible in corporate hospital groups operating across tier-1 and tier-2 cities where volume concentration enables price-volume tradeoffs.
India Plasma Fractionation Market Segmentation
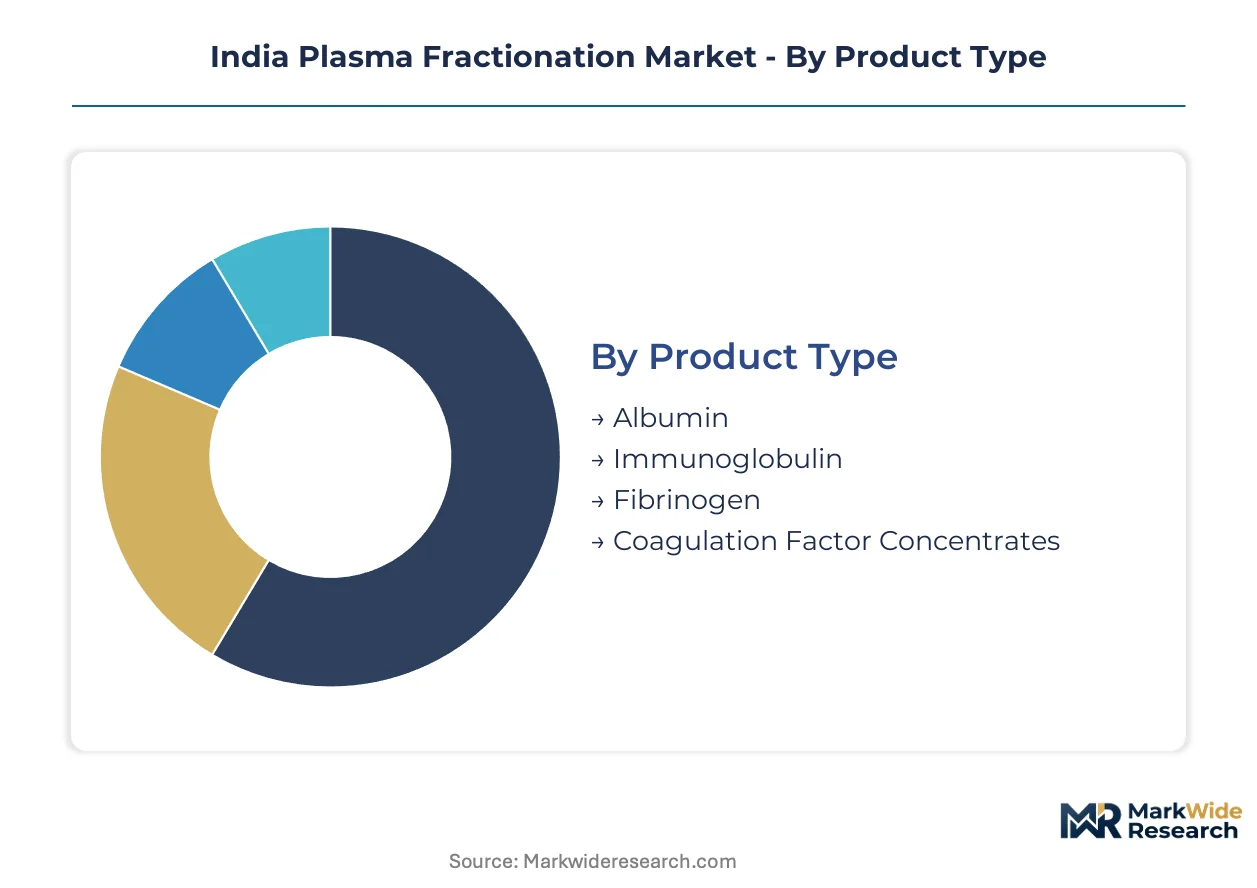
India's plasma fractionation market segments along four axes that determine pricing power and margin capture. Product type and technology choices dictate viral safety profiles and yield economics, while end-user channel selection shapes working capital intensity and procurement leverage.
Product Type:
Supply concentration in Maharashtra and Gujarat fractionation corridors favors products with established cold-chain distribution and tertiary care anchoring.
- Albumin:Human serum albumin constitutes the volume anchor for domestic fractionators, with 5% and 20% formulations dominating critical care fluid resuscitation. Demand concentrates in Mumbai and Ahmedabad corporate hospital chains where surgical volumes and burn trauma cases drive centralized tendering.
- Immunoglobulin:Intravenous and subcutaneous immunoglobulin products command premium positioning through neurological indication expansion in CIDP and myasthenia gravis protocols. Maharashtra specialty hospitals are scaling procurement as neurology departments expand immunomodulatory therapy access.
- Fibrinogen:Concentrated fibrinogen supports perioperative coagulation management in cardiac and trauma surgery suites across western India tertiary centers.
- Coagulation Factor Concentrates:Factor VIII and Factor IX products serve hemophilia treatment centers with CDSCO-mandated viral inactivation certification requirements.
Albumin absorbs the bulk of installed capacity; immunoglobulin is expanding most quickly.
End User:
Channel selection determines margin structure, with institutional procurement favoring volume discounts and blood bank direct supply compressing distributor layers.
- Hospitals:Corporate hospital networks in tier-1 and tier-2 cities dominate albumin and factor concentrate absorption through centralized tenders unbundling after-sales service from product supply.
- Blood Banks:National Blood Policy infrastructure expansion is converting government blood banks into direct collection nodes for fractionators, shortening plasma sourcing chains.
- Individual Patients:Out-of-pocket immunoglobulin purchases for chronic neurological conditions create specialty pharmacy channel development in urban Maharashtra.
- Research Institutions:Academic medical centers in Bangalore and Hyderabad source plasma derivatives for cell culture and assay development applications.
Hospitals retain dominant procurement volume; blood banks are gaining share fastest through government collection infrastructure buildout.
Technology:
Purification method selection determines yield economics and CDSCO certification pathway complexity for domestic manufacturers.
- Chromatography:Affinity and size-exclusion chromatography deliver superior viral clearance margins and protein recovery rates. Mumbai and Pune tertiary care procurement committees specify chromatography-derived products despite 15-20% price premiums.
- Precipitation:Ethanol precipitation remains the legacy workhorse for commodity-grade albumin production, constrained by lower yield and extended processing timelines.
- Membrane Filtration:Tangential flow filtration supports plasma protein concentration steps with reduced solvent exposure and gentler protein handling.
- Ion Exchange:Charge-based separation refines immunoglobulin purity for specialized neurological formulations with enhanced safety profiles.
Chromatography commands premium positioning; membrane filtration is climbing fastest as mid-tier fractionators upgrade legacy precipitation lines.
Application:
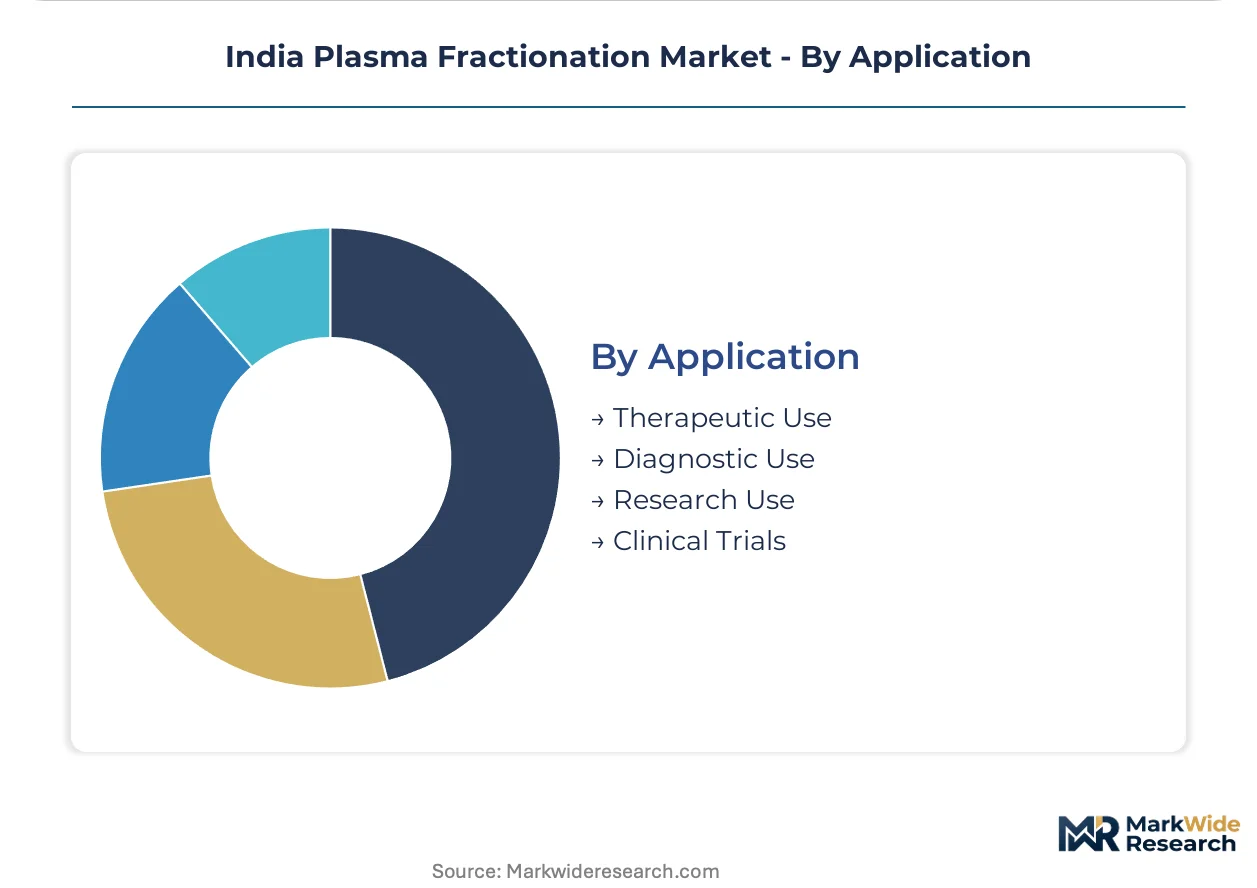
Application mix shapes regulatory burden and reimbursement pathway, with therapeutic use carrying CDSCO lot release requirements and diagnostic use facing faster batch certification.
- Therapeutic Use:Clinical administration of albumin, immunoglobulin, and coagulation factors for immunodeficiency, hemophilia, burn trauma, and liver disease represents the revenue core.
- Diagnostic Use:Plasma protein controls and calibrators for immunoassay platforms serve pathology laboratory networks in urban hospital chains.
- Research Use:Cell culture media supplementation and biochemical reagent applications support biotechnology research clusters in Bangalore and Hyderabad.
- Clinical Trials:Investigational plasma derivatives for biosimilar development programs require CDSCO clinical trial authorization and enhanced donor traceability documentation.
Therapeutic use anchors revenue; clinical trials are expanding most quickly as domestic manufacturers pursue biosimilar registration pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai-Pune corridor anchors India's plasma fractionation capacity, with tertiary care density and cold-chain maturity concentrating procurement power in Maharashtra's corporate hospital networks.
Maharashtra
Mumbai's corporate hospital chains drive albumin and immunoglobulin procurement through centralized tenders as surgical volumes expand across tier-1 and tier-2 cities. CDSCO's tightened import documentation requirements favor domestic manufacturers with certified collection networks. Pune's specialty neurology centers are scaling CIDP and myasthenia gravis immunoglobulin protocols.
Gujarat
Ahmedabad's burn trauma and cardiac surgery suites anchor perioperative albumin demand, with hospital procurement committees prioritizing supply security over unit cost. The PLI scheme for domestic biologics manufacturing accelerates greenfield fractionation announcements across the western corridor. Surat and Vadodara tertiary centers are consolidating multi-year factor concentrate agreements.
Karnataka
Bangalore's biotechnology research clusters generate plasma derivative demand for cell culture and assay development applications. BIS quality standards enforce batch consistency across the state's emerging blood bank collection infrastructure. The city's critical care units specify chromatography-purified albumin despite price premiums.
Telangana
Hyderabad's pathology laboratory networks absorb plasma protein controls for immunoassay platforms, with diagnostic use facing faster batch certification than therapeutic applications. State-level plasma donor registry expansion shortens sourcing chains for fractionators. Academic medical centers support biosimilar development programs requiring enhanced donor traceability.
Delhi-NCR
The National Capital Region's hemophilia treatment centers mandate CDSCO-certified viral inactivation for all coagulation factor concentrates. Government blood banks under the National Blood Policy are converting into direct collection nodes, compressing distributor layers. Cold-chain infrastructure gaps in surrounding tier-3 cities constrain procurement reach.
India Plasma Fractionation Market Competitive Landscape
Capital-heavy fractionators with captive plasma collection networks compete with asset-light specialists outsourcing purification steps to contract manufacturers. The market structures around three tiers: integrated domestic producers with certified facilities, mid-scale regional fractionators serving single-state hospital networks, and import-reliant distributors facing compressed margins under CDSCO's tightened guidelines. Dominant competitive moves include backward integration into plasma collection infrastructure and chromatography technology licensing for viral safety differentiation.
Among integrated domestic producers, PlasmaGen BioSciences Pvt. Ltd. and Reliance Life Sciences occupy positions exemplifying the western India concentration strategy, while Intas Pharmaceuticals Ltd. represents the specialist archetype focused on niche therapeutic formulations. These three anchors demonstrate how geographic clustering around Maharashtra and Gujarat cold-chain corridors, combined with regulatory compliance capabilities, determines competitive access to hospital procurement committees.
| Leading Market Players |
|---|
| PlasmaGen BioSciences Pvt. Ltd. |
| Reliance Life Sciences |
| Intas Pharmaceuticals Ltd. |
| Virchow Biotech Private Limited |
| Bharat Serums and Vaccines Limited |
| Taj Pharmaceuticals Limited |
| Biocon Limited |
| Fusion Healthcare |
| Hemarus Therapeutics Limited |
| Others |
Pricing and Supply Chain Analysis
CDSCO's viral safety certification mandates gate qualified supply and premium-tier pricing access, compressing margins for uncertified imports while rewarding domestic fractionators with documented cold-chain integrity. Hospital procurement committees in Maharashtra and Gujarat now weight supply security above unit cost, reshaping how albumin and immunoglobulin contracts are negotiated.
Pricing Analysis
Yield-based pricing anchors the market, with chromatography-purified products commanding 15-20% premiums over ethanol-precipitated alternatives due to superior viral clearance margins. Price differentiation rests on certification grade and volume scale, with CDSCO GMP-certified manufacturers capturing corporate hospital tenders while commodity-grade imports face margin compression. Pricing pressure stems from centralized procurement consolidation as tier-1 hospital chains unbundle after-sales service. Blood banks and government institutions exhibit highest price sensitivity; specialty neurology centers show lowest sensitivity for CIDP-grade immunoglobulin.
Supply Chain Analysis
PLI scheme domestic-content mandates are reshaping sourcing, redirecting capital toward captive plasma collection networks across western India. Feedstock supply concentrates in the United States, Germany, and Austria as primary source plasma exporters, though CDSCO's tightened import documentation extends approval timelines. Raw material dependencies span cryoprecipitate, chromatography resins, and viral inactivation reagents. Single-source vulnerability runs through US plasma export quota volatility. Distribution runs through manufacturer-direct relationships with corporate hospital networks, compressing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India plasma fractionation market sits in a technology-transition phase as chromatography purification displaces legacy ethanol precipitation across albumin and immunoglobulin production lines.
For Market Incumbents: Anchor market position through backward integration into plasma collection infrastructure across Maharashtra and Gujarat, securing CDSCO-certified donor traceability documentation that import-reliant competitors cannot replicate. Expand chromatography capacity to meet hospital procurement specifications for viral safety margins. Defend against mid-tier fractionators upgrading precipitation lines by locking multi-year supply agreements with corporate hospital chains.
For New Entrants and Emerging Players: Membrane filtration technology offers a technology-first wedge into blood bank channel development under the National Blood Policy, where government collection infrastructure buildout creates direct supply node opportunities. Target tier-2 city hospital networks in Karnataka and Telangana with lower incumbent saturation. Pursue go-to-market partnerships with state-level plasma donor registries to shorten sourcing chains.
For Investors and Strategic Acquirers: CDSCO lot release timeline compression for domestic manufacturers is the leading indicator that certified collection network assets will appreciate disproportionately. Over the medium-term horizon, prioritize acquisition targets with established cold-chain infrastructure and documented viral inactivation protocols. Monitor state-level plasma donor registry expansion rates as the inflection signal for feedstock security.
| Strategic Initiative | Industry Significance |
|---|---|
| Chromatography Capacity Expansion | CDSCO-certified viral clearance margins unlock premium hospital procurement tiers. |
| Plasma Collection Network Buildout | Captive donor traceability documentation satisfies tightened import guideline alternatives. |
| Blood Bank Channel Partnership | National Blood Policy infrastructure converts government nodes into direct supply anchors. |
| Neurological Indication Formulation | CIDP and myasthenia gravis protocols command immunoglobulin price premiums. |
| PLI Scheme Certification Pathway | Domestic biologics incentives offset fractionation plant capital intensity. |
Research Methodology
Multi-period observation of CDSCO regulatory filings, PLI scheme disbursement patterns, and hospital procurement tender awards anchored the trend analysis, supplemented by interviews with fractionation plant managers, regulatory affairs leads at domestic manufacturers, blood bank directors, and corporate hospital procurement committees. Secondary validation drew from CDSCO drug approval databases, BIS quality certification records, National Blood Policy implementation reports, and Maharashtra and Gujarat state health department procurement disclosures. Bottom-up capacity and demand estimates triangulated against top-down market sizing across product type, technology, and end-user dimensions.
Input-output matrices modeled plasma feedstock volumes against fractionation yield rates and product mix assumptions across the projection horizon. Segmentation dimensions spanned product type, purification technology, end-user channel, and application with regional regulatory cluster overlays. CAGRs derived from spline interpolation of capacity expansion announcements, surgical volume growth trajectories, and import substitution elasticity parameters. Forecast inputs incorporated PLI scheme incentive uptake rates and state-level plasma donor registry expansion timelines.
Several conditions sit outside the modeled scope, including unforeseen CDSCO regulatory reversals, US plasma export quota disruptions, and pandemic-scale blood collection interruptions. Forecasts reflect assumptions about sustained PLI scheme funding and continued surgical volume expansion in tier-2 cities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Sildenafil Drug Market