
 Middle East and Africa Anti-Fungal Agents Market | 2026-2036
Middle East and Africa Anti-Fungal Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Anti-Fungal Agents Market Foresight
Combination antifungal therapy protocols is fragmenting traditional single-agent prescribing patterns across hospital formularies. Pfizer, Inc. leverages its established hospital access networks to sustain formulary positioning in systemic infection management. Aspen Pharmacare anchors regional manufacturing capacity, while Hikma Pharmaceuticals competes through localized production and distribution reach.
Anti-fungal agents comprise synthetic and natural compounds engineered to inhibit fungal cell wall synthesis, disrupt membrane ergosterol integrity, or interfere with nucleic acid metabolism, with azoles functioning through lanosterol demethylase inhibition and echinocandins targeting beta-glucan synthase. These agents serve primarily to treat invasive candidiasis, aspergillosis, and dermatophyte infections in immunocompromised and post-surgical patient populations. Azoles retain the largest share of the product type landscape due to their broad spectrum and oral bioavailability, though echinocandins are capturing the fastest expansion in hospital settings where resistant Candida species predominate. Injectable delivery mode commands premium positioning in intensive care applications, while topical formulations occupy the mass retail channel serving superficial infection management.
Saudi Arabia's SFDA and South Africa's SAHPRA enforce divergent registration pathways that shape product launch sequencing and clinical trial investment across the region. Egypt's drug authority applies price ceiling mechanisms that compress margin structures for imported finished formulations. Stakeholders must monitor evolving pharmacovigilance requirements and local content mandates as determinants of sustainable market participation.
Market Dynamics
Hospital formulary consolidation across Saudi Arabia and South Africa is compressing supplier access windows, with centralized procurement mechanisms now filtering which antifungal agents reach immunocompromised patient populations in tertiary care settings.
Growth Catalysts
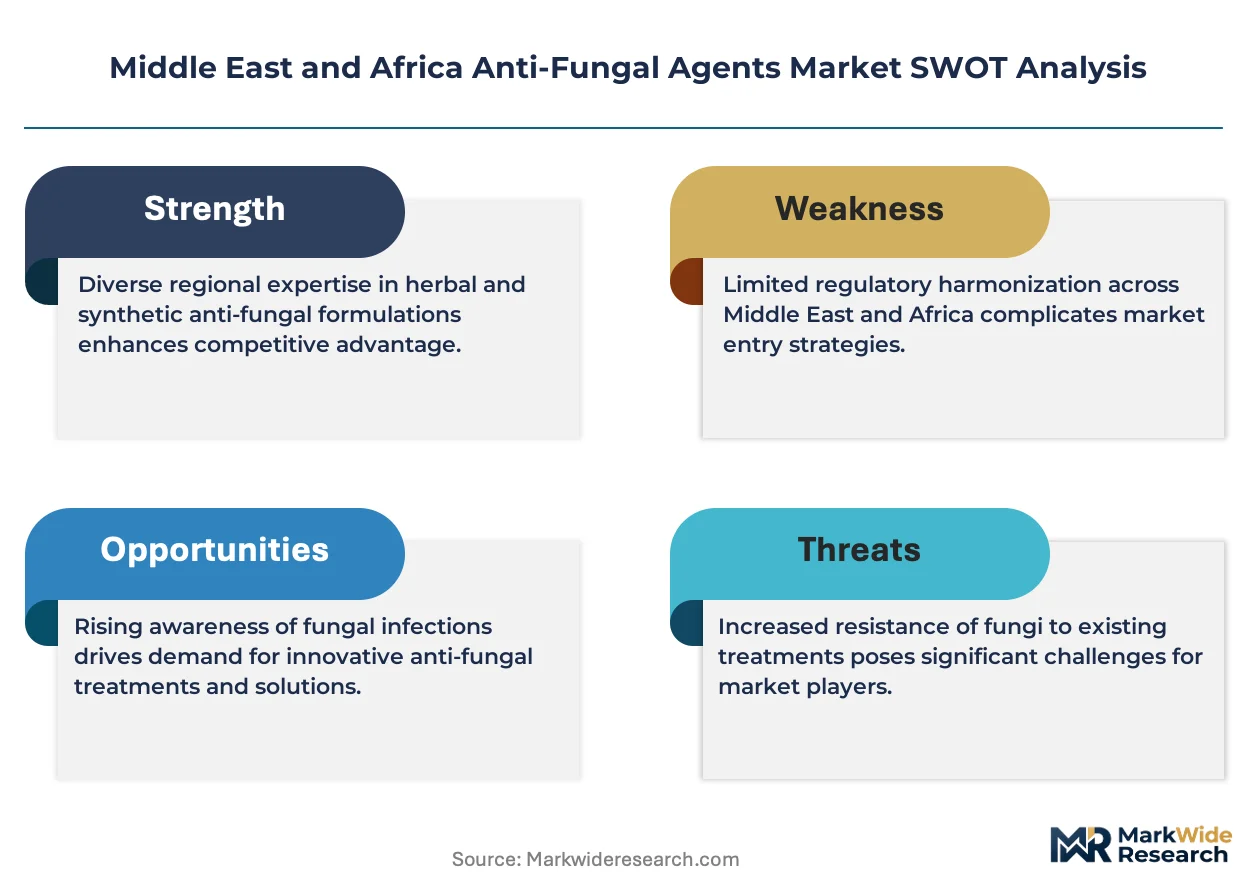
- Medical tourism infrastructure:Saudi Arabia's tertiary care expansion is generating institutional demand for systemic antifungal therapies in transplant and oncology units.
- SAHPRA harmonization:South Africa's health technology assessment framework is standardizing formulary inclusion criteria across public hospital networks.
- Echinocandin adoption:Intensive care protocols are prioritizing beta-glucan synthase inhibitors for resistant Candida species in hematology wards.
Market Restraints
- Active pharmaceutical ingredient concentration:Import dependence on Asian bulk drug manufacturers exposes formulators to supply volatility and currency fluctuation risk.
- Egyptian price ceilings:The country's drug authority applies margin compression mechanisms that limit premium positioning for novel azole formulations.
- Azole resistance surveillance gaps:Limited fungal diagnostic capacity in secondary care facilities restricts appropriate therapy selection and drives empirical overtreatment.
Strategic Opportunities
- Localized manufacturing:Egypt and Nigeria present underpenetrated production bases for regional finished formulation supply.
- Combination therapy protocols:Dual-agent regimens for invasive aspergillosis are creating formulary slots beyond traditional single-agent prescribing.
- SFDA fast-track pathways:Saudi Arabia's abbreviated review for critical care antimicrobials accelerates market entry timelines for hospital-focused portfolios.
Industry Challenges
- Pharmacovigilance infrastructure:Sparse adverse event reporting networks across North African markets complicate post-market surveillance obligations.
- Cold chain distribution:Injectable echinocandin formulations require temperature-controlled logistics that strain last-mile capabilities in Sahel regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Anti-Fungal Agents Market |
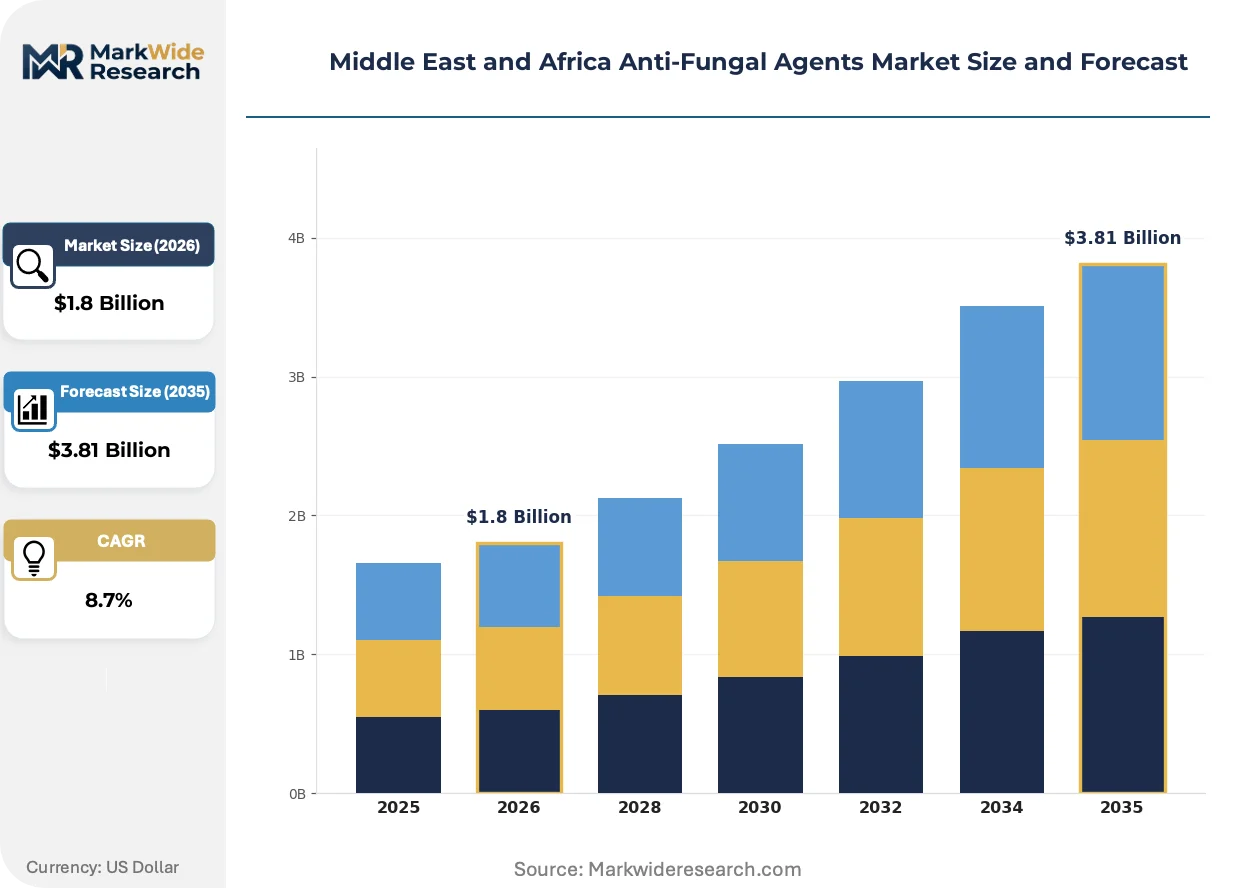
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoles, Echinocandins, Polyenes, Allylamines Delivery Mode: Topical, Oral, Injectable, Inhalation End User: Hospitals, Clinics, Home Care, Pharmacies Application: Superficial Infections, Systemic Infections, Prophylaxis, Oral Candidiasis |
| Companies Covered | Bayer AG, Abbott Laboratories, Pfizer, Inc., Hikma Pharmaceuticals, Aspen Pharmacare, Novartis AG, Merck & Co., Inc., Julphar Gulf Pharmaceutical Industries, Sanofi S.A., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Anti-Fungal Agents Market Shifts & Advancements
Therapeutic protocols across Middle East and Africa hospital systems are pivoting toward precision-guided antifungal selection, with diagnostic integration and resistance surveillance reshaping how formulary committees evaluate agent placement.
Next-generation azole derivatives with enhanced CYP450 safety profiles are rendering obsolete traditional fluconazole-first empirical protocols in hematology-oncology wards. Saudi Arabian tertiary centers are adopting these agents ahead of regional peers. The shift is compressing market share for legacy imidazoles in high-acuity settings.
SFDA's 2023 pharmacovigilance directive mandates real-world safety data submission for antifungal renewals, forcing manufacturers to invest in local observational study infrastructure. The regulation tightens post-approval compliance burdens. Hospital procurement committees now weight pharmacovigilance track records in tender evaluations.
Centralized tendering through Saudi Arabia's NUPCO and South Africa's National Department of Health is consolidating buyer power and squeezing distributor margins. Direct manufacturer-to-hospital contracting is displacing traditional wholesale channels in high-volume institutions. The restructuring is most visible in Johannesburg and Riyadh metropolitan hospital clusters.
Middle East and Africa Anti-Fungal Agents Market Segmentation
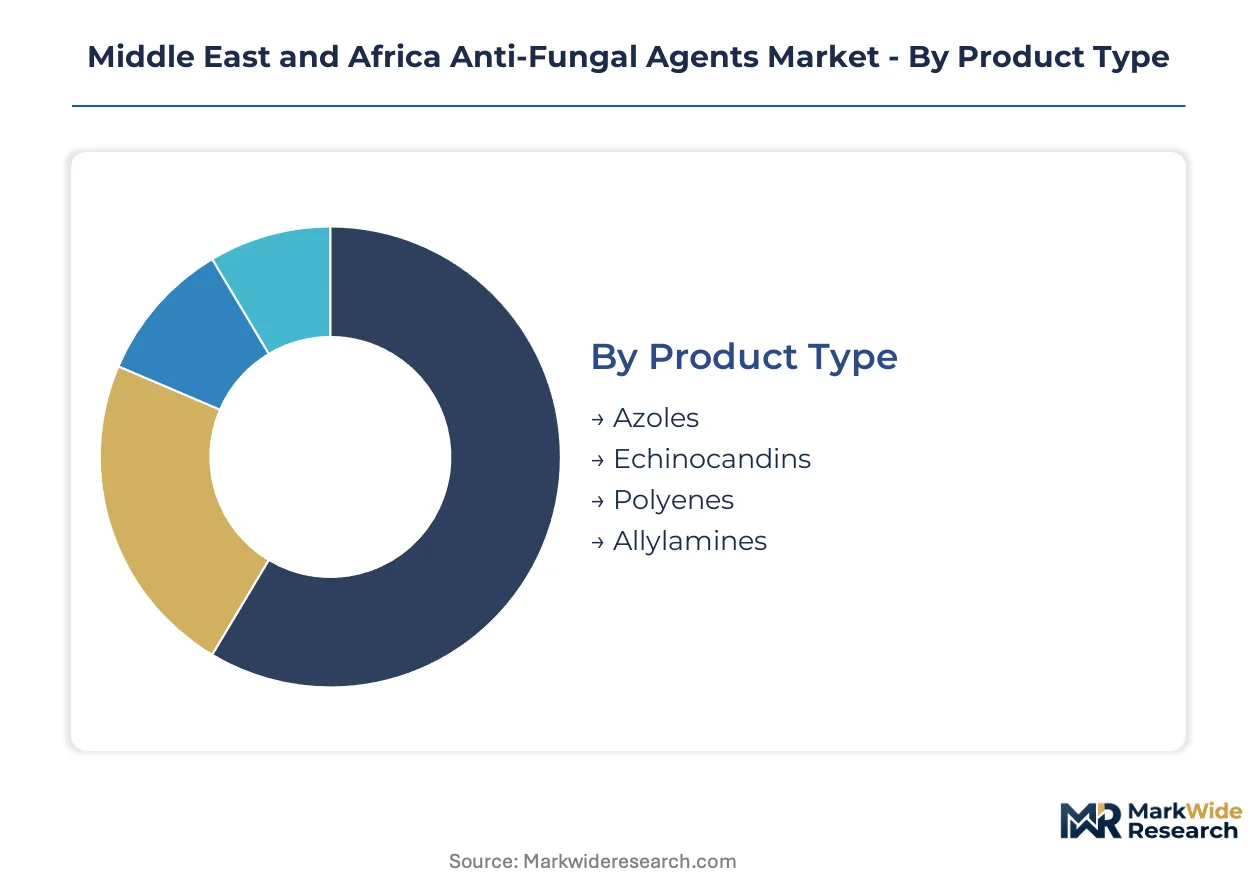
Segmentation in the Middle East and Africa Anti-Fungal Agents Market reveals distinct procurement rhythms across product classes and delivery modes. Hospital formulary committees evaluate segments through divergent lenses of resistance surveillance, cold chain requirements, and outpatient volume potential.
Product Type:
Azoles turn over fastest through retail channels while echinocandins cycle slowly via hospital tender processes with extended qualification periods.
- Azoles:Synthetic compounds inhibiting lanosterol demethylase disrupt fungal membrane ergosterol synthesis. Demand concentrates in Egyptian retail pharmacies where fluconazole dominates empirical therapy for vaginal candidiasis amid diagnostic capacity gaps.
- Echinocandins:Beta-glucan synthase inhibitors target the fungal cell wall with parenteral-only delivery. Saudi Arabian tertiary transplant centers in Riyadh drive institutional uptake as first-line therapy for invasive candidiasis in hematology-oncology wards.
- Polyenes:Amphotericin B formulations retain niche positioning in South African public hospitals for mucormycosis protocols where lipid-complex variants offset nephrotoxicity concerns.
- Allylamines:Terbinafine compounds serve dermatophyte infections through topical and oral routes, with South African retail chains stocking standard formulations for tinea pedis management.
Azoles anchor the volume base while echinocandins gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates premium cold-chain injectables from mass-market topicals with minimal storage overhead.
- Topical:Creams, ointments, and solutions for superficial dermatophyte and yeast infections. Nigerian pharmacy networks distribute clotrimazole and miconazole formulations without prescription requirements.
- Oral:Tablets and capsules enabling outpatient systemic therapy. Egyptian community pharmacies dispense fluconazole and itraconazole for recurrent vaginal candidiasis and onychomycosis.
- Injectable:Intravenous formulations reserved for hospitalized patients with invasive infections. Saudi NUPCO tenders consolidate procurement of liposomal amphotericin B and caspofungin for ICU protocols.
- Inhalation:Nebulized antifungal delivery for pulmonary aspergillosis. South African academic medical centers in Johannesburg deploy inhaled amphotericin B prophylaxis in lung transplant units.
Oral formulations anchor the volume base while injectable delivery climbs the fastest as hospital-based systemic therapy expands.
End User:
Customer type determines regulatory exposure and procurement complexity across institutional versus retail channels.
- Hospitals:Tertiary care institutions with centralized tendering and formulary committees. Saudi Arabia's SFDA mandates pharmacovigilance reporting for antifungal utilization in transplant and oncology wards.
- Clinics:Outpatient facilities managing superficial infections and stable systemic cases. South Africa's primary health care clinics distribute fluconazole through standardized treatment guidelines.
- Home Care:Post-discharge settings for prolonged oral antifungal courses. Egyptian home nursing services coordinate with hospital discharge planners for invasive aspergillosis step-down therapy.
- Pharmacies:Retail outlets serving self-medication and prescription fulfillment. Nigerian patent medicine vendors and community pharmacies drive volume for topical azole sales.
Pharmacies anchor the volume base while hospital procurement expands most quickly through centralized tender consolidation.
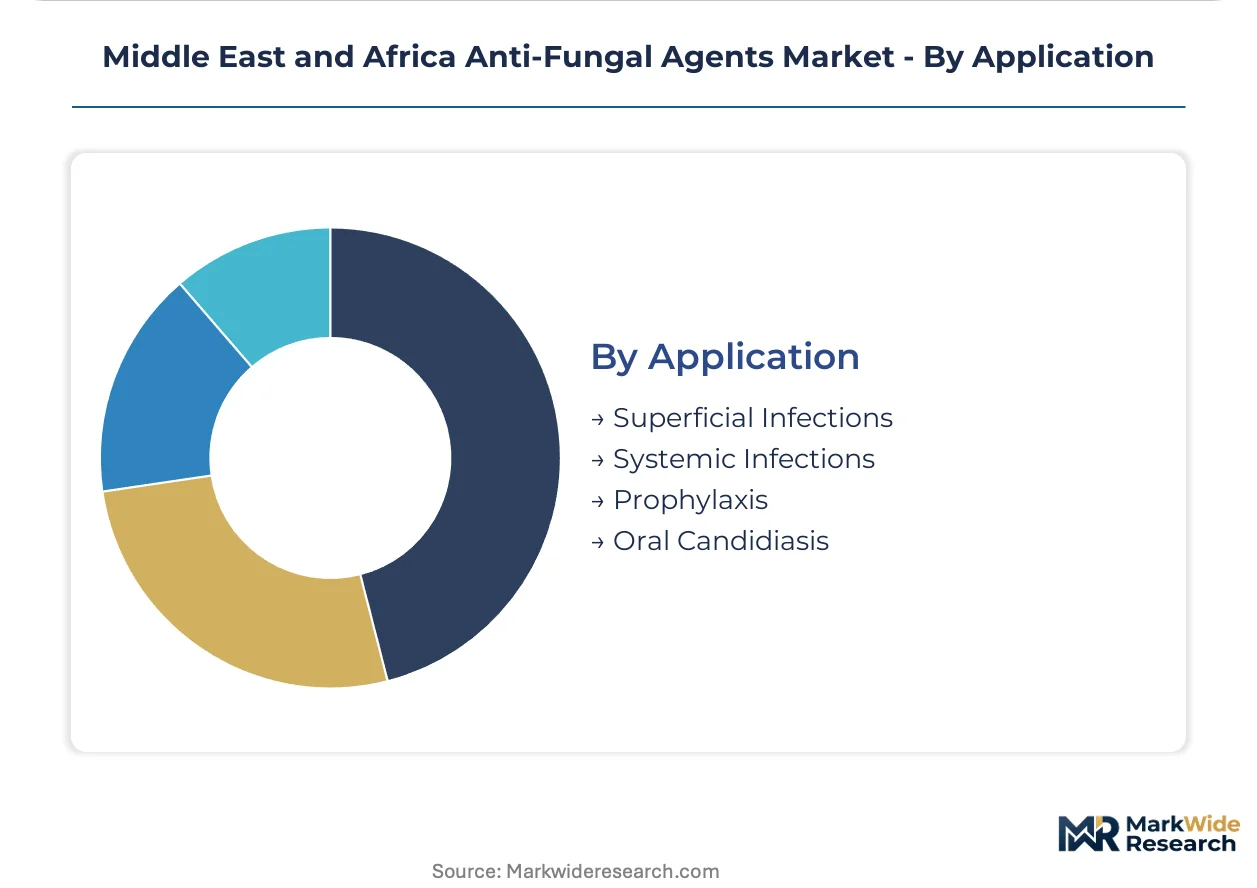
Application:
Maturity gradients separate established superficial infection management from emerging prophylaxis protocols in immunocompromised populations.
- Superficial Infections:Dermatophyte and mucocutaneous candidiasis affecting skin, nails, and mucous membranes. Egyptian and Nigerian retail channels prioritize topical and oral azole access for tinea and vaginal candidiasis.
- Systemic Infections:Invasive candidiasis, aspergillosis, and cryptococcosis in immunocompromised hosts. Saudi tertiary centers deploy combination echinocandin-azole protocols for breakthrough aspergillosis in allogeneic stem cell recipients.
- Prophylaxis:Preventive antifungal regimens in high-risk hematology and transplant populations. South African academic hospitals standardize posaconazole prophylaxis for acute myeloid leukemia induction therapy.
- Oral Candidiasis:Mucosal Candida infections in HIV, oncology, and denture-wearing populations. Kenyan and Ugandan HIV treatment programs distribute fluconazole through integrated chronic care platforms.
Superficial infection management anchors the volume base while prophylaxis applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and centralized drug tendering authorities concentrate buyer power across the Middle East and Africa, with tertiary care expansion in Gulf states and formulary harmonization in Southern Africa reshaping supplier access patterns.
Saudi Arabia
Medical tourism investments and transplant unit expansion at King Faisal Specialist Hospital drive institutional demand for systemic antifungal therapies. The SFDA enforces pharmacovigilance reporting mandates for antifungal utilization in oncology wards. Riyadh's metropolitan hospital cluster leads regional adoption of next-generation azole derivatives.
South Africa
Public hospital networks and academic medical centers generate concentrated demand for echinocandin and liposomal amphotericin B formulations. SAHPRA's health technology assessment framework standardizes formulary inclusion criteria across provincial health systems. Johannesburg's private hospital corridor anchors premium antifungal procurement volumes.
Egypt
Community pharmacy networks and primary care clinics sustain high-volume demand for oral fluconazole and topical azole formulations. The country's drug authority applies price ceiling mechanisms that compress margins for imported finished formulations. Cairo's pharmaceutical distribution hub channels generic antifungal supplies across North African markets.
Nigeria
Patent medicine vendors and retail pharmacy chains drive mass-market consumption of topical antifungal creams and ointments. The national pharmaceutical regulator maintains registration pathways that favor locally manufactured formulations. Lagos and Kano serve as distribution nodes for superficial infection management products across West Africa.
United Arab Emirates
Private hospital groups and specialist dermatology clinics generate demand for premium antifungal formulations in outpatient settings. MOHAP oversees product registration and pricing frameworks that influence Gulf Cooperation Council market access. Dubai's healthcare free zones attract multinational pharmaceutical distributors serving the broader region.
Middle East and Africa Anti-Fungal Agents Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent access pathways, with hospital formulary gatekeepers and retail pharmacy chains exercising distinct procurement logics. Market structure tilts toward consolidated supply at the institutional tier and fragmented distribution at the retail tier. Three archetypes dominate: multinational pharmaceutical conglomerates with hospital access networks, regional manufacturing specialists with localized production capacity, and generic formulators competing on price in high-volume retail channels. Competitive moves center on direct manufacturer-to-hospital contracting and backward integration into active pharmaceutical ingredient sourcing.
Among multinational pharmaceutical conglomerates, Pfizer, Inc. and Bayer AG occupy positions anchored by established hospital formulary relationships and systemic therapy portfolios. Hikma Pharmaceuticals exemplifies the regional manufacturing specialist archetype, with localized production and distribution reach across Middle Eastern markets. These three entities represent distinct competitive vectors: global scale with institutional access, regional manufacturing proximity, and hybrid commercial models spanning hospital and retail channels.
| Leading Market Players |
|---|
| Bayer AG |
| Abbott Laboratories |
| Pfizer, Inc. |
| Hikma Pharmaceuticals |
| Aspen Pharmacare |
| Novartis AG |
| Merck & Co., Inc. |
| Julphar Gulf Pharmaceutical Industries |
| Sanofi S.A. |
| Others |
Supply & Pricing Matrix
Indian and Chinese bulk API manufacturers anchor upstream supply for azole and echinocandin precursors, concentrating margin capture in finished formulation tolling while Gulf hospital procurement committees extract downstream value through NUPCO tender consolidation.
Pricing Analysis
Cost-plus contracts with Asian API suppliers index azole intermediate pricing to petrochemical feedstock benchmarks, creating margin volatility for regional formulators. Three-tier pricing structure across originator brands, licensed generics, and unbranded commodities separates Saudi hospital tenders from Egyptian retail channels and Nigerian patent medicine stalls. Pricing pressure stems from centralized Gulf procurement squeezing distributor markups. Retail pharmacy networks in Cairo and Lagos exhibit highest price sensitivity; Riyadh transplant centers demonstrate lowest sensitivity due to protocol-driven formulary locks.
Supply Chain Analysis
Upstream feedstock concentration in Indian Gujarat and Chinese Zhejiang provinces supplies lanosterol demethylase inhibitors and beta-glucan synthase precursors to regional formulators. Egyptian and Nigerian finished dose manufacturers draw from these API streams while Saudi Arabia imports sterile injectable formulations directly. Single-source vulnerability pervades liposomal amphotericin B production. Distribution runs through Dubai's Jebel Ali pharmaceutical free zone for Gulf markets and Lagos port clusters for West African retail penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital formulary digitization across Saudi Arabia and South Africa is creating platform-economics dynamics where interoperability between procurement systems and clinical decision support tools determines supplier lock-in.
For Market Incumbents: Build pharmacovigilance data moats through real-world evidence partnerships with Saudi tertiary centers and South African academic hospitals. Consolidate backward integration into API sourcing to offset rupee and yuan fluctuation exposure. Anchor formulary positioning by embedding clinical pharmacists within hospital antimicrobial stewardship committees. For New Entrants and Emerging Players: Build out localized finished formulation capacity in Egypt and Nigeria to circumvent import price ceilings and capture retail pharmacy volume. Target superficial infection management segments where diagnostic infrastructure gaps sustain empirical azole prescribing. Deploy direct-to-clinic sampling programs bypassing wholesale markups in Kenyan and Ugandan HIV care platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding exclusive tenders with Saudi NUPCO and South Africa's National Department of Health. Five-to-ten year viability hinges on formulary consolidation durability rather than product innovation cycles. Monitor SFDA fast-track approval velocity as inflection indicator for hospital-focused portfolio entrants.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Fast-Track Registration | Abbreviated review timelines accelerate hospital formulary access for critical care antimicrobials. |
| Backward Integration into API Synthesis | Captive supply of azole intermediates insulates margin structures from Asian currency volatility. |
| Pharmacovigilance Infrastructure Investment | Real-world safety data partnerships satisfy Saudi renewal mandates and differentiate tender bids. |
| Localized Manufacturing Scale-Up | Egyptian and Nigerian production bases circumvent price ceilings and reduce import duty exposure. |
| Combination Therapy Protocol Development | Dual-agent regimens for invasive aspergillosis create formulary slots beyond single-agent commoditization. |
Research Methodology
Initial hypotheses were tested against primary input from hospital formulary directors, pharmaceutical procurement managers, regulatory affairs leads at SFDA and SAHPRA, and clinical pharmacists in hematology-oncology wards, then refined against secondary validation from EMA submission databases, SFDA pharmacovigilance directives, hospital tender documentation, and trade flow records. Bottom-up patient volume modeling and top-down pharmaceutical expenditure analysis were triangulated to constrain estimate ranges.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, delivery mode, end user channel, and application severity. CAGRs were derived from fitted growth curves calibrated to hospital procurement volume trajectories and retail pharmacy audit data. Forecast inputs incorporated resistance surveillance trends and centralized tender consolidation timelines.
Stress conditions across API import cost inflation, Egyptian price ceiling adjustments, and Gulf procurement centralization pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about formulary access continuity and diagnostic capacity expansion. Cross-checking against WHO antifungal consumption databases and national health expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
Levothyroxine Sodium Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Global Vaccine Market