
 Intranasal Corticosteroids Market | 2026-2036
Intranasal Corticosteroids Market Size, Share, and Industry Trends Forecast 2026-2036
Intranasal Corticosteroids Market Foresight
Specialist ENT clinics and pediatric allergy centers are rotating toward higher-efficacy intranasal corticosteroid protocols as first-line therapy. GlaxoSmithKline plc dominates the fluticasone propionate segment through established respiratory franchises. Johnson & Johnson leverages its consumer health distribution network to sustain over-the-counter momentum. Teva Pharmaceutical Industries Ltd. competes on generic mometasone furoate formulations across regulated markets.
Intranasal corticosteroids are synthetic glucocorticoid formulations administered via nasal mucosa absorption, typically dosed at 50-200 micrograms per spray, designed to suppress local inflammatory mediators in allergic and non-allergic rhinitis. Fluticasone and mometasone formulations command the largest prescription volumes due to their favorable systemic bioavailability profiles, while budesonide retains significant pediatric share through established safety databases. The allergic rhinitis treatment focus generates the deepest revenue pools, though nasal polyps represents the fastest-growing indication as biologic-sparing protocols gain traction.
FDA bioequivalence standards for nasal spray products, EMA's MDR requirements for drug-device combinations, and WHO Essential Medicines List inclusion collectively shape product development priorities and market access pathways. Generic sponsors must navigate complex pharmacokinetic bridging studies under FDA guidance, raising barriers to commoditization. Stakeholders should monitor evolving payer policies on step-therapy mandates versus direct specialist access.
Market Dynamics
The FDA's updated bioequivalence guidance for nasal aerosols is compressing generic substitution timelines while concentrating procurement authority within integrated delivery networks. This regulatory inflection is reshaping how formulary committees evaluate therapeutic equivalence across fluticasone and mometasone portfolios.
Growth Catalysts
- Pediatric formulary expansion:Allergy clinics in the United States are elevating intranasal corticosteroids to first-line pediatric protocols. This clinical repositioning is expanding addressable patient populations beyond adult seasonal allergic rhinitis.
- EMA MDR compliance pathways:Drug-device combination requirements in Europe are accelerating investment in next-generation nasal spray delivery systems. Manufacturers with pre-certified quality management systems capture accelerated market access.
- Nasal polyp biologic-sparing protocols:ENT specialists are deploying intranasal corticosteroids as maintenance therapy post-polypectomy. This indication expansion is creating new prescription volume pools independent of allergic rhinitis seasonality.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthetic glucocorticoid production concentrates among three contract manufacturers in India and China. Supply disruptions at any single site create formulation bottlenecks for multiple finished dose sponsors.
- FDA pharmacokinetic bridging study costs:Generic entrants face bioequivalence study expenditures exceeding traditional oral solid dosage requirements. This capital barrier limits the number of viable ANDA filers for mometasone furoate.
- Systemic bioavailability perception:Payer step-therapy protocols prioritize intranasal antihistamines before corticosteroid authorization. This clinical preference hierarchy compresses realized pricing power despite superior efficacy data.
Strategic Opportunities
- Direct-to-specialist distribution:Bypassing wholesale intermediaries to serve ENT and allergy clinics creates margin capture and formulary influence. Teledermatology platforms are emerging as novel prescription initiation channels.
- WHO Essential Medicines List inclusion:Budesonide's pediatric safety profile positions it for expanded procurement in low-income country health systems. National immunization program infrastructure offers distribution leverage.
- Connected delivery device integration:Bluetooth-enabled dose counters paired with smartphone adherence apps are supplanting conventional mechanical actuators. This convergence creates differentiation beyond molecular equivalence.
Industry Challenges
- Device engineering talent scarcity:Nasal spray pump design requires specialized expertise in plume geometry and droplet size distribution. Recruitment competition from pulmonary inhaler manufacturers elevates compensation costs.
- Legacy ERP integration with track-and-trace systems:Serialization requirements under the Drug Supply Chain Security Act demand substantial middleware investment. Smaller generic sponsors face disproportionate compliance burdens relative to revenue scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intranasal Corticosteroids Market |
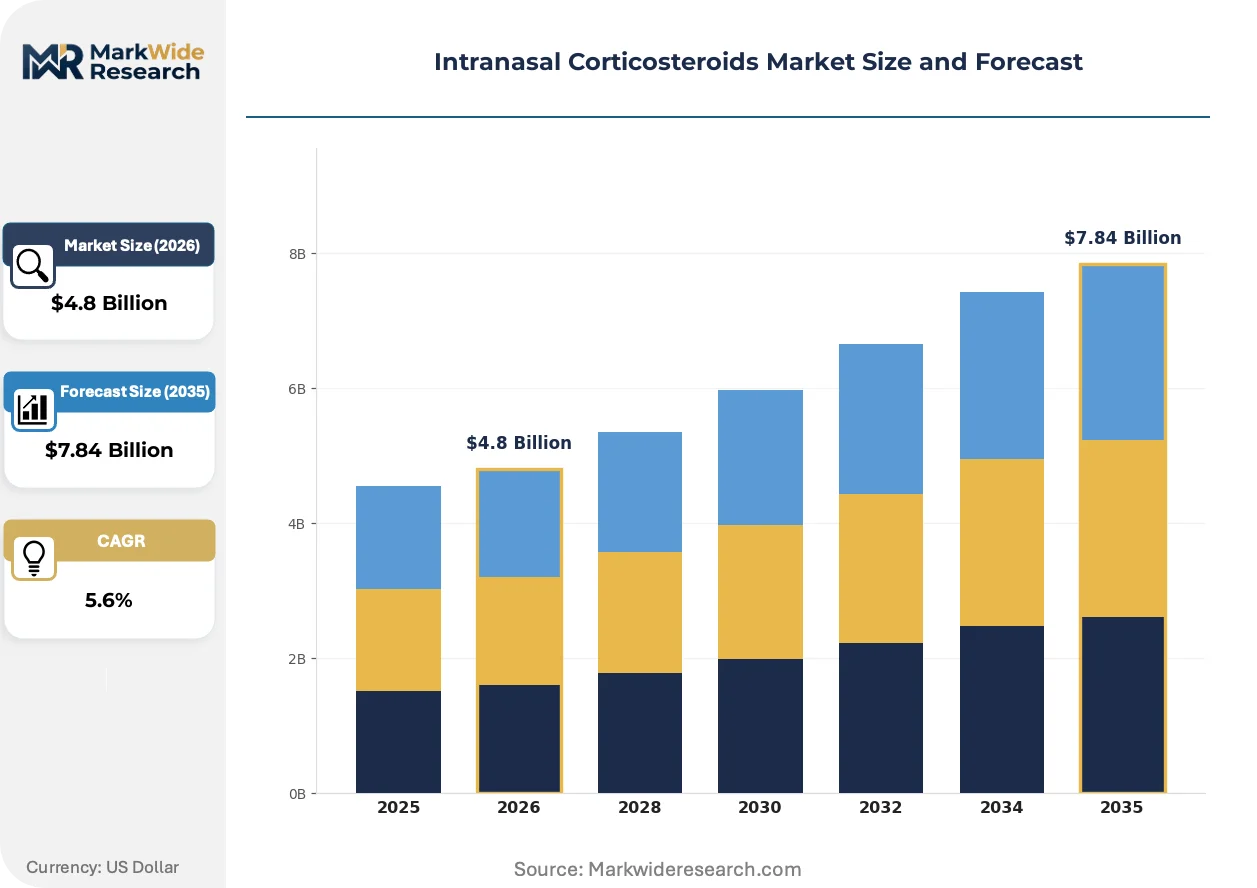
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluticasone, Budesonide, Triamcinolone, Mometasone End User: Pediatric Patients, Adult Patients, Geriatric Patients, Healthcare Providers Delivery Mode: Spray, Nasal Drops, Inhalation Powder, Metered Dose Treatment Focus: Allergic Rhinitis, Sinusitis, Nasal Polyps, Asthma |
| Companies Covered | GlaxoSmithKline plc, Johnson & Johnson, Merck & Co., Inc., AstraZeneca plc, Teva Pharmaceutical Industries Ltd., Sanofi S.A., Bayer AG, Novartis AG, Perrigo Company plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intranasal Corticosteroids Market Shifts & Advancements
Formulation science and delivery mechanism engineering are converging to differentiate products beyond molecular identity. These advances are creating new competitive moats in a market historically commoditized by bioequivalence.
Hydrofluoroalkane-propelled nasal aerosols are supplanting traditional aqueous pump sprays in severe rhinitis segments. Academic medical centers in Germany and the United States are adopting these formulations for patients with compromised mucociliary clearance. The technology is enabling sustained local deposition and reduced systemic exposure, compressing the efficacy gap between intranasal and systemic corticosteroid therapy.
EMA's Medical Device Regulation is forcing reclassification of nasal spray actuators as Class IIa medical devices. This regulatory elevation requires clinical evidence portfolios previously unnecessary for drug-only approvals. Combination product sponsors in the Netherlands and Sweden are responding by vertically integrating device manufacturing to control design history file integrity.
Specialist clinic consolidation is compressing the number of independent formulary decision-makers. Large ENT practice management platforms in Texas and Florida are deploying standardized therapeutic protocols across dozens of sites. This concentration is shifting purchasing leverage from individual prescribers to centralized procurement committees with explicit cost-effectiveness mandates.
Intranasal Corticosteroids Market Segmentation
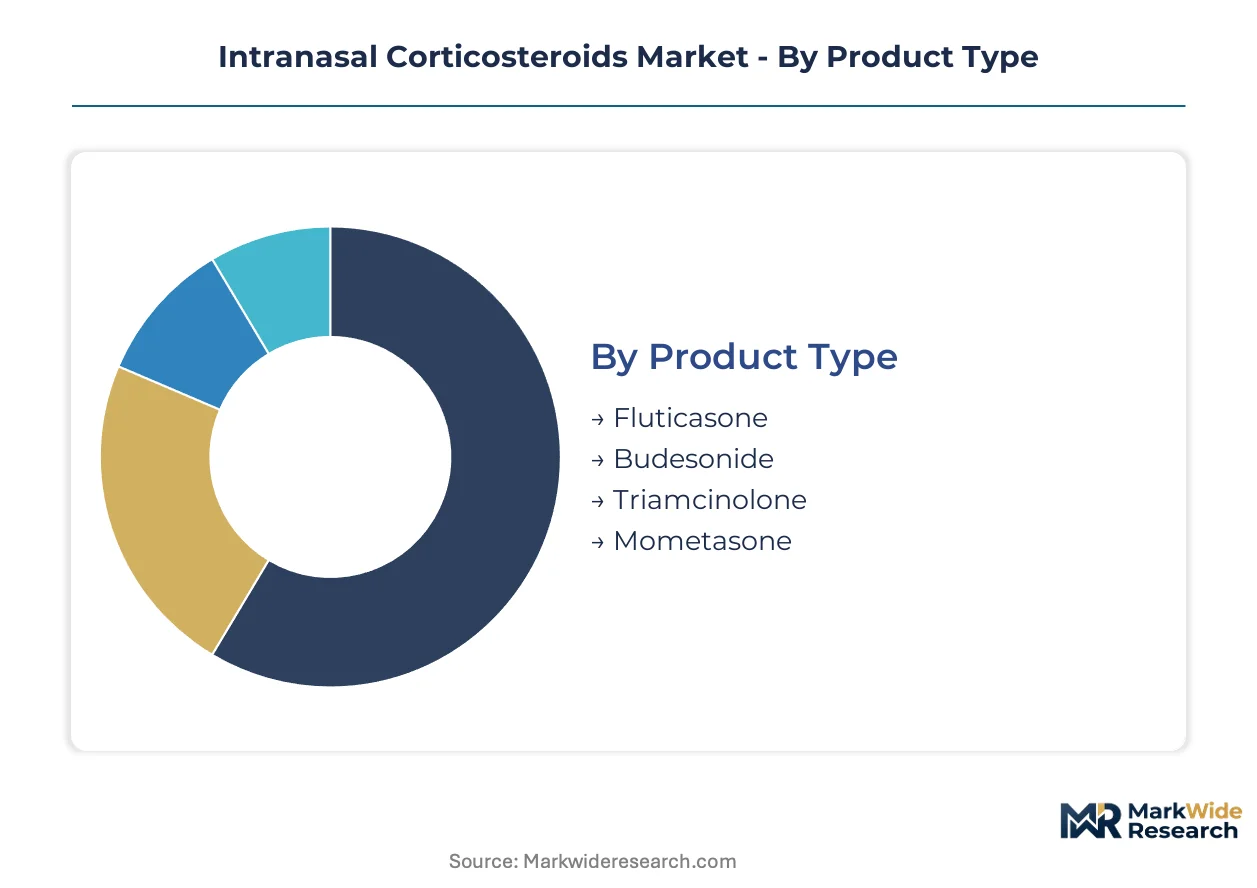
Intranasal corticosteroid portfolios fragment across molecular identity, patient demographics, and device engineering. Each segmentation axis carries distinct margin profiles and regulatory complexity that shape competitive positioning.
Product Type:
Margin pools concentrate in formulations with favorable systemic bioavailability profiles that sustain premium positioning against generic substitution.
- Fluticasone:Synthetic trifluorinated glucocorticoid with high receptor affinity and negligible systemic absorption. ENT specialists in the United States prescribe this molecule most heavily for persistent moderate-to-severe allergic rhinitis, though FDA bioequivalence study costs limit generic filers.
- Mometasone:Second-generation corticosteroid with established efficacy in nasal polyposis. German academic medical centers favor this formulation for post-polypectomy maintenance protocols, creating volume independent of seasonal allergy patterns.
- Budesonide:Non-halogenated corticosteroid with extensive pediatric safety databases. WHO Essential Medicines List inclusion drives procurement in low-income health systems.
- Triamcinolone:Long-acting synthetic glucocorticoid with broader systemic availability. Cost-conscious formularies deploy this option where step-therapy mandates prioritize economy.
The dominant share belongs to Fluticasone, while Mometasone is closing the gap fastest through nasal polyp indication expansion.
End User:
Prescription volume and pricing power diverge sharply between dependent patient populations and autonomous healthcare decision-makers.
- Adult Patients:Self-directed consumers with seasonal symptom recognition drive over-the-counter conversion. Johnson & Johnson's retail distribution network captures this demographic through pharmacy shelf placement.
- Pediatric Patients:Caregiver-mediated demand with stringent safety requirements. Allergy clinics in Texas and Florida are elevating intranasal corticosteroids to first-line protocols for children over two years.
- Geriatric Patients:Polypharmacy considerations and compromised mucociliary clearance necessitate formulation adjustments. Hydrofluoroalkane-propelled aerosols address deposition challenges in this cohort.
- Healthcare Providers:Institutional purchasing through integrated delivery networks concentrates procurement authority. Formulary committees in large ENT practice management platforms standardize protocols across dozens of sites.
Adult Patients command the deepest revenue pools, though Pediatric Patients are expanding most quickly through clinical repositioning.
Delivery Mode:
Device engineering sophistication determines reimbursement tiers and generic substitutability under evolving drug-device combination regulations.
- Spray:Aqueous pump systems with established plume geometry standards. EMA MDR reclassification of actuators as Class IIa medical devices is forcing clinical evidence portfolios for combination products.
- Metered Dose:Hydrofluoroalkane-propelled systems enabling precise dose delivery. German and United States academic centers adopt these for severe rhinitis with compromised clearance.
- Nasal Drops:Gravity-dependent instillation for posterior nasal deposition. Limited commercial presence outside pediatric and post-surgical applications.
- Inhalation Powder:Dry powder devices requiring patient-generated airflow. Niche positioning for patients intolerant of aqueous formulations.
Spray mechanisms retain the dominant installed base, while Metered Dose systems are gaining share fastest through severe rhinitis protocol adoption.
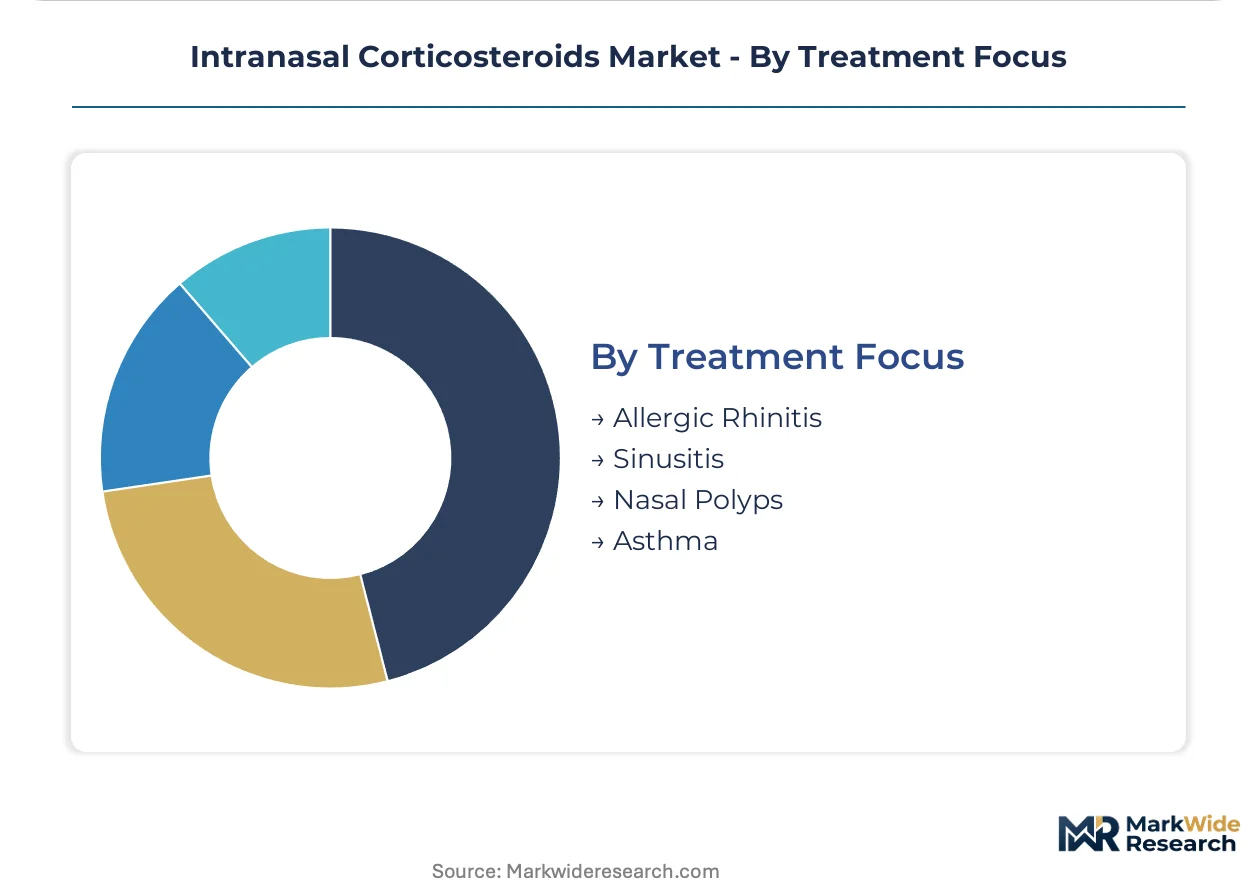
Treatment Focus:
Indication breadth separates seasonal commodity exposure from durable prescription volume anchored in chronic disease management.
- Allergic Rhinitis:Seasonal and perennial IgE-mediated inflammation generating the largest addressable population. United States prevalence sustains volume through year-round perennial and distinct pollen seasons.
- Nasal Polyps:Chronic inflammatory outgrowths requiring maintenance therapy post-surgical resection. ENT specialists deploy intranasal corticosteroids as biologic-sparing protocols, creating indication expansion.
- Sinusitis:Acute and chronic paranasal sinus inflammation with overlapping infectious etiology. Antibiotic co-prescription patterns complicate pure corticosteroid positioning.
- Asthma:Lower airway indication with nasal delivery as adjunctive therapy. Limited standalone commercial focus given pulmonary inhaler dominance.
Allergic Rhinitis commands the dominant share, though Nasal Polyps is climbing the fastest as maintenance protocols displace biologic dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese contract manufacturers export active pharmaceutical ingredients to formulation sponsors across the United States and Europe. Finished dose production concentrates in facilities serving regulated markets with stringent bioequivalence requirements.
United States
Seasonal allergic rhinitis prevalence drives sustained prescription volumes through distinct pollen seasons and year-round perennial demand. FDA bioequivalence guidance for nasal aerosols compresses generic substitution timelines while raising study cost barriers. Texas and Florida host expanding ENT practice management platforms that standardize therapeutic protocols across dozens of clinic sites.
Germany
Academic medical centers favor mometasone formulations for post-polypectomy maintenance protocols independent of seasonal patterns. EMA Medical Device Regulation reclassifies nasal spray actuators as Class IIa devices requiring clinical evidence portfolios. The Netherlands and Sweden host combination product sponsors vertically integrating device manufacturing to control design history file integrity.
India
Contract manufacturers concentrate synthetic glucocorticoid production for multiple finished dose sponsors worldwide. CDSCO oversight of drug-device combinations aligns with evolving international standards for nasal delivery systems. Hyderabad and Mumbai clusters supply active pharmaceutical ingredients to generic formulators across regulated markets.
China
Domestic formulation capacity serves both export markets and expanding local allergic rhinitis patient populations. NMPA standards for nasal spray bioequivalence create parallel regulatory pathways distinct from FDA and EMA requirements. Shanghai and Jiangsu province host facilities engineering next-generation aqueous pump systems with refined plume geometry.
United Kingdom
Pediatric allergy clinics elevate intranasal corticosteroids to first-line protocols for children over two years. MHRA implementation of drug-device combination regulations follows EMA MDR frameworks with national variation. London and Southeast England concentrate specialist ENT referral networks influencing formulary decisions across integrated care systems.
Intranasal Corticosteroids Market Competitive Landscape
Listed leaders compete with private specialists across respiratory franchise breadth and generic manufacturing scale. The market structures around three tiers: research-intensive innovators with established respiratory platforms, diversified consumer health conglomerates with retail distribution networks, and generic specialists competing on bioequivalence execution and cost position. Dominant competitive moves include portfolio diversification into combination drug-device products and geographic expansion through direct-to-specialist distribution channels bypassing wholesale intermediaries.
Within the innovator tier, GlaxoSmithKline plc and AstraZeneca plc represent established respiratory franchise holders with molecular differentiation capabilities. Johnson & Johnson occupies a position exemplifying consumer health conglomerate leverage through pharmacy retail channel dominance. Teva Pharmaceutical Industries Ltd. anchors the generic specialist archetype, competing across regulated markets on mometasone furoate formulation execution.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Merck & Co., Inc. |
| AstraZeneca plc |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| Bayer AG |
| Novartis AG |
| Perrigo Company plc |
| Others |
Supply & Pricing Matrix
Contract manufacturing scale at Indian and Chinese API facilities creates dual pressure on finished dose pricing. Three concentrated production sites supply synthetic glucocorticoid precursors to formulation sponsors across regulated markets, compressing cost floors while FDA bioequivalence study requirements sustain premium tiers for reference-listed drugs.
Pricing Analysis
Aqueous pump spray formulations occupy the economy tier against emerging hydrofluoroalkane-propelled metered dose systems commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates connected-device-enabled products from conventional mechanical actuators from basic generic substitutions. Cost compression in the standard tier intensifies because ANDA sponsors face pharmacokinetic bridging expenditures exceeding oral solid dosage requirements. Pediatric allergy clinics demonstrate lowest price sensitivity due to caregiver-mediated demand and safety prioritization, while cost-conscious formularies deploying step-therapy protocols exhibit highest sensitivity.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for European and North American formulation facilities. Synthetic glucocorticoid production concentrates in India, China, and select European sites, drawing from halogenated steroid precursors, specialized pump actuator components, and hydrofluoroalkane propellant stocks. Single-source vulnerability pervades the contract manufacturer tier where any disruption at Hyderabad or Mumbai clusters propagates across multiple finished dose sponsors. Distribution runs through integrated delivery networks consolidating procurement authority within large ENT practice management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device engineering services and adherence monitoring software represent the fastest-expanding recurring revenue layers, outpacing molecular formulation hardware as clinics seek differentiated patient management protocols.
For Market Incumbents: Fortify respiratory franchise positioning through captive supply of next-generation nasal spray actuators before EMA MDR compliance deadlines accelerate. Secure backward integration into pump device manufacturing to control design history file integrity against emerging generic sponsors with limited device engineering capabilities. Prioritize certification investment for Class IIa medical device status under European regulations. For New Entrants and Emerging Players: FDA bioequivalence fast-track pathways for complex nasal aerosols offer accelerated market entry against entrenched fluticasone portfolios. Target pediatric allergy clinic protocols in Texas and Florida where clinical repositioning elevates intranasal corticosteroids to first-line therapy independent of step-therapy mandates. Deploy direct-to-specialist distribution bypassing wholesale intermediaries to capture margin and formulary influence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors combination product specialists with vertically integrated device manufacturing capabilities over pure molecular generic sponsors. Acquire targets with pre-certified quality management systems capturing accelerated EMA market access. Watch FDA ANDA approval velocity for mometasone furoate formulations as inflection indicator for generic substitution timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Delivery Device Integration | Bluetooth-enabled dose counters paired with smartphone adherence apps differentiate beyond molecular equivalence under FDA guidance. |
| Direct-to-Specialist Distribution | Bypassing wholesale intermediaries to serve ENT and allergy clinics creates margin capture and formulary influence in Texas and Florida. |
| EMA MDR Compliance Pathway | Drug-device combination requirements accelerate investment in next-generation nasal spray delivery systems with clinical evidence portfolios. |
| Pediatric Formulary Expansion | Allergy clinics elevating intranasal corticosteroids to first-line protocols expand addressable populations beyond adult seasonal allergic rhinitis. |
| Biologic-Sparing Protocol Development | ENT specialists deploying maintenance therapy post-polypectomy create prescription volume pools independent of allergic rhinitis seasonality. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration against evolving FDA bioequivalence guidance and EMA Medical Device Regulation requirements. Primary interviews with ENT specialists and allergy clinic administrators combined with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling and top-down revenue reconciliation ensured analytical consistency.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare Part D claims patterns and European hospital procurement database trends. Segmentation dimensions spanned molecular identity, patient demographic cohort, delivery mechanism engineering, and treatment indication across the analysis window. CAGRs derived from year-over-year prescription volume trajectories adjusted for seasonal pollen pattern variation and polypectomy procedure frequency in academic medical centers.
The analysis sits within stated boundaries; outcomes outside sustained FDA bioequivalence study cost structures or stable API contract manufacturing capacity would require recalibration. Forecasts reflect assumptions regarding EMA MDR implementation timelines and pediatric protocol adoption rates. Regulatory revision to nasal spray classification standards or supply disruption at concentrated API manufacturing sites could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Global Low Molecular Weight Heparin Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market