
 Telmisartan Market | 2026-2036
Telmisartan Market Size, Share, and Industry Trends Forecast 2026-2036
Telmisartan Market Intelligence
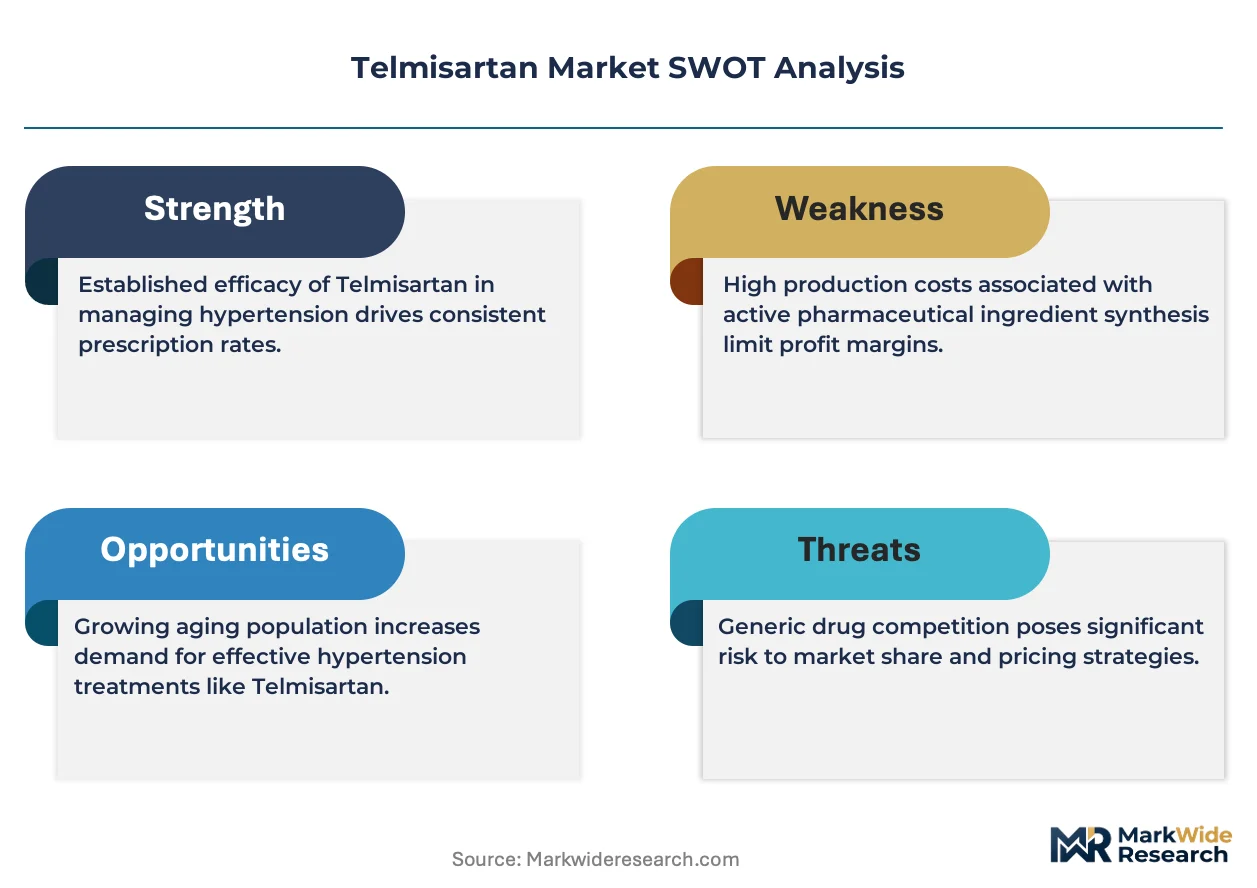
Multi-source API procurement is realigning how generic manufacturers secure telmisartan active pharmaceutical ingredient supply. Boehringer Ingelheim International GmbH leverages its original formulation heritage to sustain brand loyalty in European markets. Cipla Limited anchors its competitive stance through backward integration into API production. Aurobindo Pharma Limited specializes in high-volume oral solid dosage exports to regulated markets.
Telmisartan is a non-peptide angiotensin II receptor blocker with high lipophilicity and selective AT1 receptor antagonism, formulated primarily as 20 mg, 40 mg, and 80 mg oral tablets for hypertension and cardiovascular risk reduction. Tablet formulations dominate volume consumption due to manufacturing scalability and patient compliance advantages. Extended release formulations capture premium positioning within the formulation segment as patent cliffs erode immediate-release margins. Retail pharmacies channel the majority of dispensed volume, though homecare settings represent the fastest-growing end-user segment driven by chronic disease management decentralization.
The FDA oversees bioequivalence standards for generic telmisartan submissions, while the EMA enforces stringent impurity profiling under ICH Q3D guidelines for European market access. India's CDSCO mandates local clinical bridging studies that shape the timing of domestic generic launches. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional bioequivalence study waivers as determinants of competitive entry velocity.
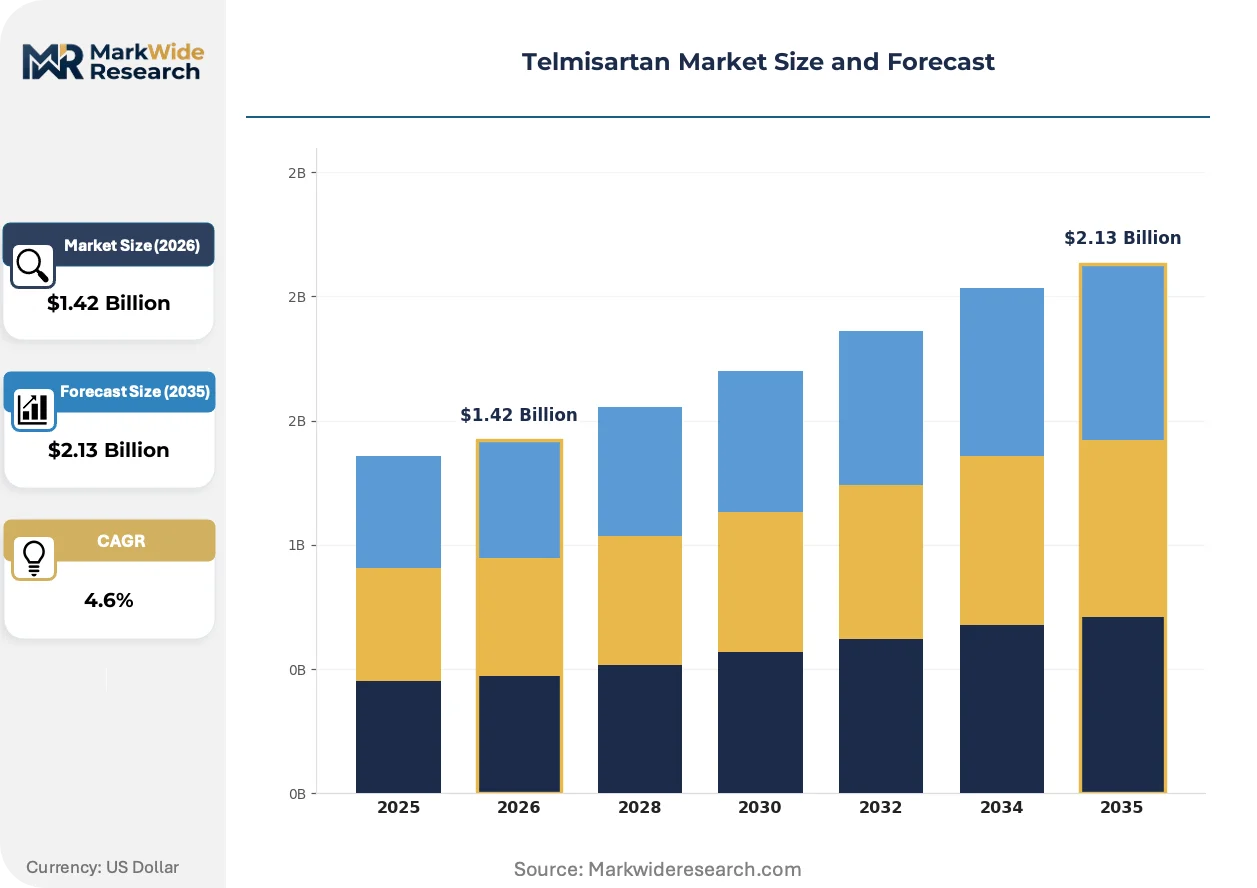
Market Dynamics
The FDA's abbreviated new drug application pathway for generic angiotensin II receptor blockers has compressed competitive entry timelines, forcing originators to defend market position through formulation differentiation rather than exclusivity alone.
Growth Catalysts
- Cardiovascular disease management programs:Hospital systems in the United States, Germany, and Japan are integrating telmisartan into standardized hypertension protocols, expanding institutional procurement volumes.
- REACH compliance:European manufacturers are reformulating to meet ECHA impurity thresholds, creating upgrade cycles for existing product lines.
- CDSCO bridging study requirements:India's mandate for local clinical data has delayed generic saturation, preserving margin structures for early movers.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in India and China expose formulators to geopolitical disruption and freight volatility.
- ICH Q3D compliance costs:EMA enforcement of elemental impurity profiling raises quality control expenditures for European market entry.
- Sartan class substitution:Olmesartan and azilsartan alternatives compete on dosing frequency, pressuring telmisartan's once-daily positioning.
Strategic Opportunities
- Homecare settings:Chronic disease management decentralization in Japan and Germany is diverting dispensing volume from retail pharmacies to direct-to-patient channels.
- Extended-release formulations:Patent cliff erosion of immediate-release margins creates premium positioning for modified-release dosage development.
- PLI scheme alignment:India's production-linked incentive framework for pharmaceuticals rewards backward-integrated API-to-tablet manufacturers with tax benefits.
Industry Challenges
- Bioequivalence study execution:FDA statistical power requirements for generic submissions demand larger patient cohorts, extending development timelines.
- Pharmacopeial monograph synchronization:Divergent United States Pharmacopeia, European Pharmacopoeia, and Indian Pharmacopoeia standards force multi-jurisdiction filing complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telmisartan Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Oral Solutions Therapy Area: Hypertension, Heart Failure, Cardiovascular Diseases, Renal Protection End User: Hospitals, Clinics, Retail Pharmacies, Homecare Settings Formulation: Immediate Release, Extended Release, Combination Therapy, Mono Therapy |
| Companies Covered | Cipla Limited, Mylan N.V., Boehringer Ingelheim International GmbH, Sanofi S.A., Abbott Laboratories, Aurobindo Pharma Limited, Sun Pharmaceutical Industries Ltd., GlaxoSmithKline PLC, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telmisartan Market Strategic Shifts & Innovations
Formulation science and regulatory science are advancing in parallel, with modified-release technologies and impurity control methods reshaping how manufacturers compete beyond basic bioequivalence.
Continuous manufacturing technology for oral solid dosage forms is converging with real-time release testing protocols. Contract development and manufacturing organizations serving regulated markets are adopting these integrated production-quality systems to reduce batch rejection rates. This convergence is compressing the cost gap between high-volume generic producers and mid-tier regional suppliers.
EMA's ICH Q3D guideline implementation for elemental impurities is forcing reformulation of legacy telmisartan products. Manufacturers must resubmit stability data and revalidate analytical methods to maintain European market authorization. The tablet segment bears the heaviest compliance burden due to mineral excipient sourcing complexity.
Hospital procurement consortia in Germany and Japan are consolidating purchasing authority into fewer decision-making entities. This concentration shifts negotiating leverage toward volume-commitment contracts with price indexing clauses. The United States remains fragmented by health system scale, though integrated delivery networks in California and Texas are replicating European consolidation patterns.
Telmisartan Market Segmentation
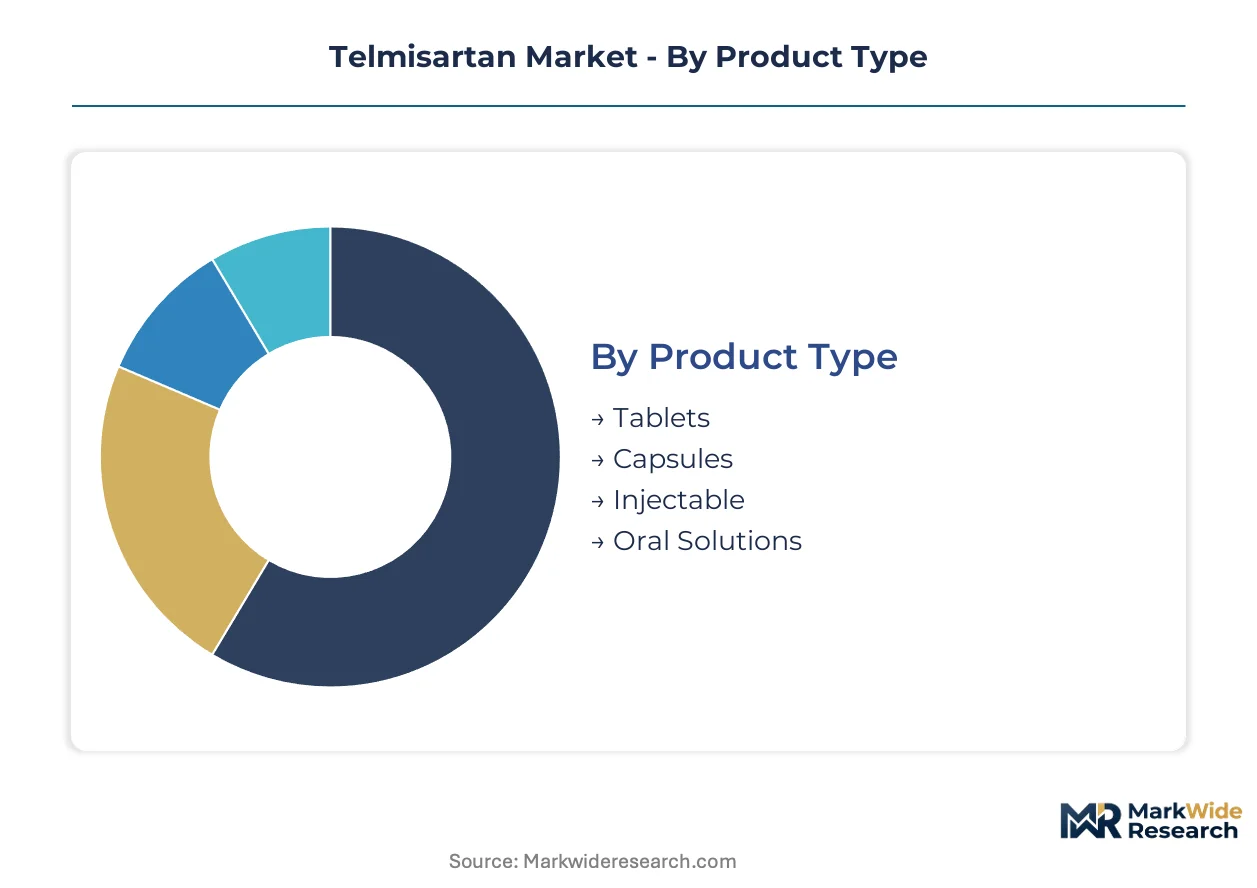
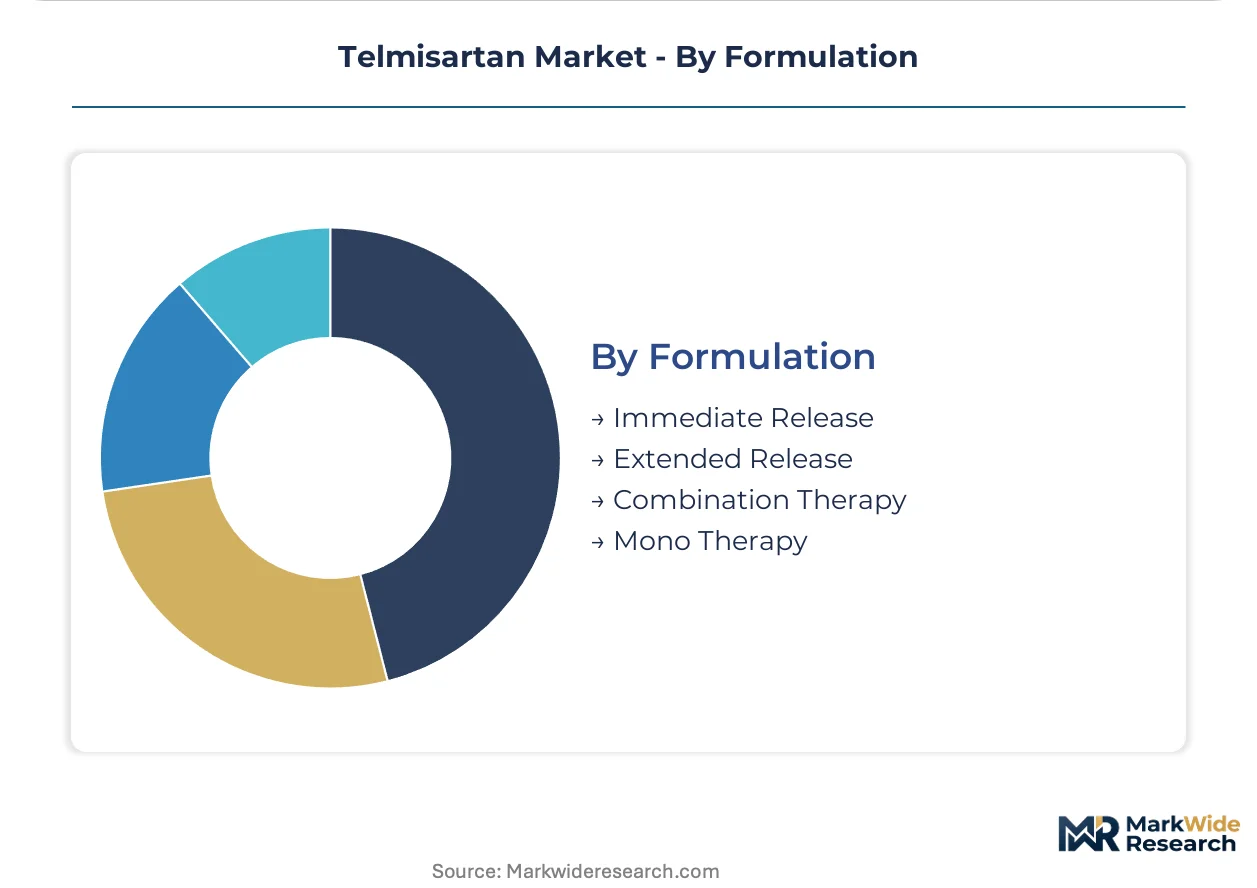
Telmisartan's therapeutic positioning across cardiovascular and renal indications creates distinct demand profiles by formulation and delivery setting. Supply chain configuration varies sharply across these boundaries, with hospital procurement favoring immediate-release tablets while homecare channels drive extended-release adoption.
Product Type:
API supply concentration in Indian and Chinese manufacturing clusters shapes competitive dynamics across dosage forms.
- Tablets:Oral solid dosage forms containing 20 mg, 40 mg, and 80 mg telmisartan dominate commercial volumes due to manufacturing scalability at Indian API-to-tablet integrated facilities. Hospital systems in the United States, Germany, and Japan standardize procurement around tablet presentations for hypertension protocol compliance.
- Capsules:Gelatin and HPMC capsule formulations serve patients with tablet swallowing difficulties, capturing niche positioning in geriatric-focused homecare channels. Demand concentrates in Japan's aging demographic segments where dosing flexibility commands premium positioning.
- Injectable:Parenteral formulations for acute hypertensive crisis management in emergency departments.
- Oral Solutions:Liquid presentations for pediatric and dysphagia populations in specialized hospital settings.
Today's leader: Tablets. Tomorrow's challenger: Injectable.
Therapy Area:
Clinical evidence differentiation determines reimbursement tier placement and prescribing authority across cardiovascular indications.
- Hypertension:First-line angiotensin II receptor blocker indication with established J-curve mortality benefit data driving protocol inclusion. German and Japanese hypertension management programs mandate ARB-first prescribing for stage 1 and 2 patients, institutionalizing volume commitment contracts.
- Cardiovascular Diseases:ONTARGET trial evidence supports telmisartan's cardiovascular risk reduction positioning in high-risk diabetic populations. Payers in the United States require prior authorization documentation for this expanded indication, creating administrative friction.
- Heart Failure:Adjunctive therapy in ACE inhibitor-intolerant patients with reduced ejection fraction.
- Renal Protection:Diabetic nephropathy indication with albuminuria reduction endpoints in type 2 diabetes populations.
Hypertension anchors current volume. Cardiovascular Diseases claims the steepest expansion trajectory as risk-based contracting proliferates.
End User:
Channel consolidation patterns in Germany and Japan are compressing price realization for manufacturers dependent on fragmented retail pharmacy networks.
- Hospitals:Integrated delivery networks and procurement consortia consolidate purchasing authority through standardized hypertension protocols. German hospital federations negotiate multi-year volume commitments with price indexing clauses, shifting leverage toward buyers.
- Homecare Settings:Chronic disease management decentralization in Japan and Germany diverts dispensing from retail pharmacies to direct-to-patient channels. Telemedicine integration enables remote blood pressure monitoring with automated prescription renewal.
- Retail Pharmacies:Community dispensing remains volume-dominant in the United States due to pharmacy benefit manager formulary structures.
- Clinics:Outpatient cardiology and nephrology practices with sample-driven prescribing initiation.
Homecare Settings are climbing the fastest as reimbursement shifts toward outcome-based chronic care models.
Formulation:
Patent cliff erosion of immediate-release margins creates R&D allocation pressure toward modified-release development programs.
- Immediate Release:Standard tablet formulations with rapid absorption profiles and established bioequivalence reference standards. FDA abbreviated new drug application pathway enables rapid generic entry, compressing originator pricing power.
- Extended Release:Modified-release technologies utilizing matrix or osmotic pump systems achieve sustained plasma concentration with reduced dosing frequency. Premium positioning persists in Japanese and German markets where patient compliance economics justify higher acquisition costs.
- Combination Therapy:Fixed-dose combinations with hydrochlorothiazide or amlodipine for multidrug hypertension regimens.
- Mono Therapy:Single-agent telmisartan for initial treatment or substitution in intolerance scenarios.
Immediate Release commands present volume. Extended Release holds margin defense potential as bioequivalence competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting API production toward jurisdictions with lower elemental impurity compliance costs, while hospital procurement consolidation in high-price markets squeezes formulation margins. Manufacturers are relocating finishing operations to capture tax incentives and avoid REACH-mandated reformulation expenses.
United States
Integrated delivery networks in California and Texas are consolidating hypertension protocol standardization, driving volume-commitment contracting with price indexing clauses. FDA bioequivalence requirements for abbreviated new drug applications demand larger patient cohorts, extending generic development timelines. API supply chains run through Indian manufacturing clusters in Hyderabad and Ahmedabad, exposing formulators to freight volatility.
Germany
Hospital procurement consortia are consolidating purchasing authority through multi-year volume agreements with manufacturers. EMA enforcement of ICH Q3D elemental impurity guidelines forces reformulation of legacy telmisartan products and resubmission of stability data. The Rhine-Ruhr pharmaceutical corridor hosts formulation facilities upgrading analytical methods to maintain European market authorization.
Japan
Chronic disease management decentralization is diverting dispensing volume from retail pharmacies to homecare channels with telemedicine integration. PMDA standards for modified-release formulations create premium positioning opportunities as immediate-release margins erode. The Kansai region around Osaka contains aging-demographic patient concentrations where dosing flexibility commands price premiums.
India
CDSCO bridging study requirements for local clinical data delay generic saturation, preserving margin structures for early movers. The production-linked incentive scheme rewards backward-integrated API-to-tablet manufacturers with tax benefits. Gujarat and Maharashtra industrial corridors concentrate integrated manufacturing facilities serving regulated export markets.
China
NMPA bioequivalence standards for generic ARBs are converging with international norms, accelerating domestic competitive entry. Dual carbon goals are reshaping energy-intensive API production economics in coastal manufacturing zones. The Yangtze River Delta pharmaceutical cluster is upgrading impurity control capabilities to meet EMA and FDA export requirements.
Telmisartan Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue extended-release differentiation and homecare channel penetration. The market structure fragments across originator heritage brands, integrated Indian generic manufacturers, and contract development organizations serving regulated markets. Three archetypes dominate: backward-integrated API producers, formulation specialists with regulatory filing expertise, and hospital procurement consortia partners. Competitive moves concentrate on portfolio diversification into fixed-dose combinations and geographic expansion through European market authorization acquisitions.
Among India-based integrated manufacturers, Cipla Limited and Aurobindo Pharma Limited exemplify the backward-integrated archetype with captive API supply chains. Boehringer Ingelheim International GmbH occupies the originator heritage position in European markets. These three entities represent distinct competitive vectors: cost leadership through vertical control, regulatory filing scale, and brand loyalty defense respectively.
| Leading Market Players |
|---|
| Cipla Limited |
| Mylan N.V. |
| Boehringer Ingelheim International GmbH |
| Sanofi S.A. |
| Abbott Laboratories |
| Aurobindo Pharma Limited |
| Sun Pharmaceutical Industries Ltd. |
| GlaxoSmithKline PLC |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Backward integration into API production anchors competitive positioning for Indian manufacturers while insulating them from raw material price volatility that compresses margins for pure-play formulators in regulated markets.
Pricing Analysis
Retailer markup compression in German hospital procurement consortia is forcing manufacturers toward direct contracting models. Three-tier pricing structure across originator brands, authorized generics, and commodity generics reflects bioequivalence certification tiers and volume commitment scales. Price erosion runs through immediate-release tablets as FDA abbreviated new drug application approvals accelerate. Retail pharmacy networks in the United States exhibit highest price sensitivity due to pharmacy benefit manager formulary exclusion leverage.
Supply Chain Analysis
India's production-linked incentive scheme for active pharmaceutical ingredients is reshoring synthesis capacity from Chinese coastal zones to Gujarat and Maharashtra industrial corridors. Telmisartan API production draws from 4-amino-3-methylbenzoic acid and biphenyl-2-carboxylic acid feedstocks sourced through petrochemical intermediates. Single-source vulnerability concentrates in Hyderabad manufacturing clusters exposed to monsoon logistics disruption. Distribution runs through hospital procurement consortia in Germany and Japan alongside fragmented retail pharmacy networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's CDSCO bridging study requirements and the FDA's abbreviated new drug application pathway creates margin preservation opportunities for manufacturers with dual-filing capabilities.
For Market Incumbents: Lock in multi-year volume commitment contracts with German hospital federations before procurement consolidation completes. Secure captive API supply through Maharashtra facility investments to offset ICH Q3D compliance cost inflation in European markets. Defend against azilsartan and olmesartan substitution through fixed-dose combination portfolio expansion. For New Entrants and Emerging Players: The premium-to-economy price gap in Japanese homecare channels offers white-space entry for extended-release formulation specialists. Target India's delayed generic saturation window created by CDSCO clinical bridging mandates. Pursue contract development and manufacturing organization partnerships with European regulatory filing expertise as go-to-market accelerant. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier Indian API-to-tablet integrators because CDSCO requirements preserve domestic margin structures against Chinese export competition. Long-term viability hinges on backward integration depth and EMA filing scale. Monitor FDA abbreviated new drug application approval velocity as inflection indicator for immediate-release margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | PMDA standards enable premium positioning in Japan's aging demographic segments. |
| Backward Integration into API Production | PLI scheme tax benefits in India offset REACH compliance costs for European exports. |
| Hospital Procurement Consortium Partnership | German federation contracts lock in volume commitments with price indexing clauses. |
| CDSCO Bridging Study Investment | Local clinical data requirements delay generic saturation for early movers. |
| Homecare Channel Direct Distribution | Telemedicine integration in Japan diverts volume from retail pharmacy networks. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at generic manufacturers, formulary directors at German hospital federations, and procurement managers at United States integrated delivery networks were cross-validated against FDA abbreviated new drug application filings, EMA marketing authorization databases, CDSCO clinical trial registries, and Indian pharmaceutical export customs records.
Input-output matrices mapping telmisartan API synthesis through formulation finishing to end-user dispensing generated volume and value estimates across the projection horizon. Segmentation dimensions encompassed dosage form, therapy line, end-user channel, and regional regulatory cluster. Compound annual growth rates were derived from elasticity-adjusted demand curves incorporating hypertension protocol adoption rates and patent cliff erosion timelines.
Caveats apply where FDA bioequivalence guideline revisions, EMA impurity threshold adjustments, or API supply disruptions could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Soft Capsules Drugs CMO Market