
 Europe Over-The-Counter (OTC) Drugs Market | 2026-2036
Europe Over-The-Counter (OTC) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Over-The-Counter (OTC) Drugs Market Foresight
Younger self-medicating consumers is unwinding the traditional elderly-heavy buyer base that long dominated OTC purchasing patterns. Bayer AG leverages its analgesics heritage and pharmacy channel control to sustain shelf presence across German and French retail networks. Sanofi anchors its position through gastrointestinal specialization, while Haleon differentiates via brand strength in oral health and respiratory segments.
Europe Over-The-Counter drugs comprise non-prescription medicinal products containing active pharmaceutical ingredients at fixed dosages, formulated for self-diagnosed conditions without clinician supervision; these products undergo stability testing, bioequivalence validation, and patient-friendly packaging design to ensure safe unsupervised use. Analgesics and cold & cough categories occupy mature volume positions with concentrated margin pools tied to brand loyalty, whereas dermatological and gastrointestinal segments lead growth trajectory due to rising self-treatment awareness and expanded indication switches from prescription status. Online retail channels are capturing incremental share from pharmacies, though regulatory dispensing requirements in several member states constrain pure digital penetration.
EMA coordinates centralized marketing authorization pathways for OTC switches, while national regulators such as Germany's BfArM and France's ANSM enforce pharmacovigilance and advertising standards that directly shape product labeling and promotional boundaries. The EU Green Deal packaging requirements and CSRD sustainability disclosures are forcing reformulation and supply chain documentation investments that favor larger manufacturers with compliance infrastructure. Stakeholders must monitor the evolving switch pipeline and digital pharmacy regulatory harmonization to anticipate which therapeutic categories unlock next-wave volume expansion.
Market Dynamics
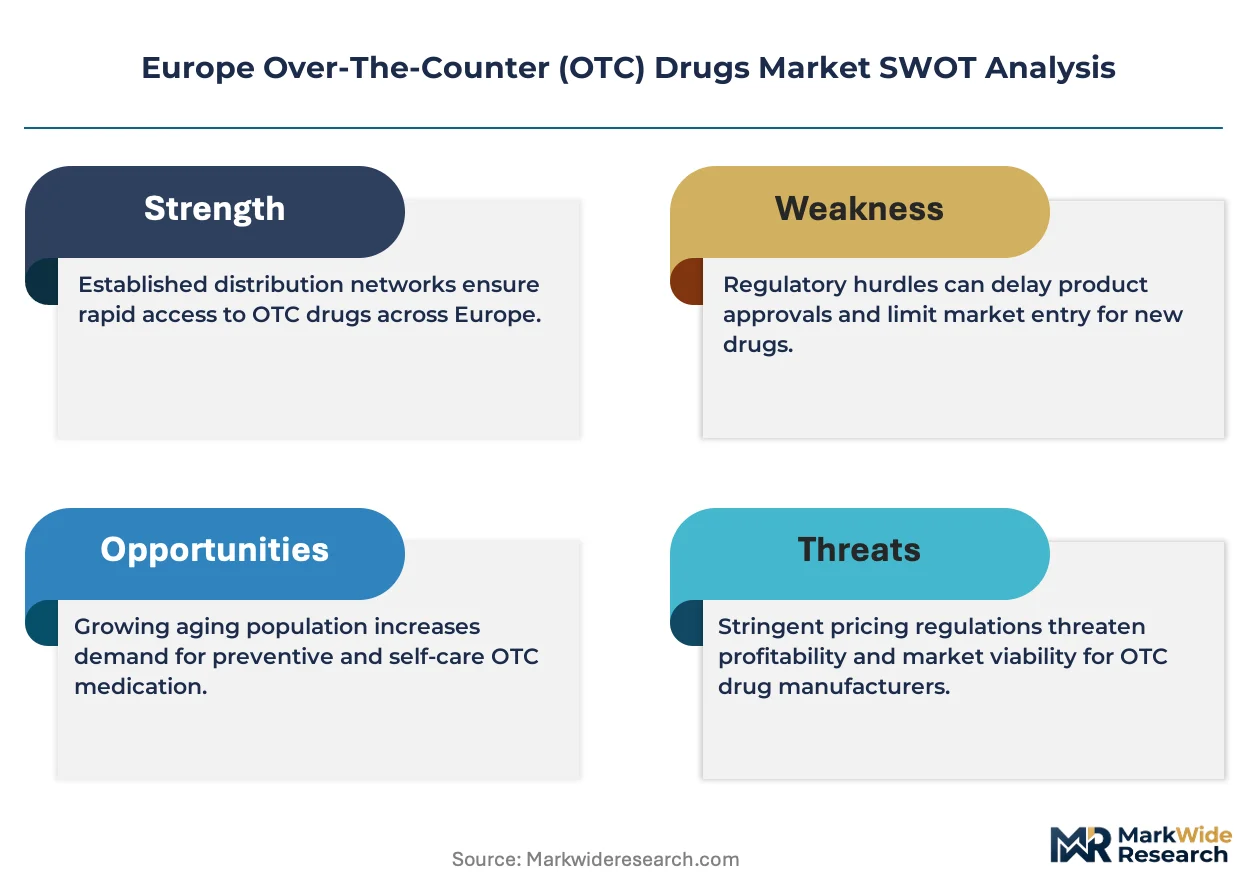
The EU's Pharmaceutical Strategy and national switch programs are redrawing competitive boundaries by accelerating prescription-to-OTC reclassifications, forcing incumbents to rebuild portfolio architectures around self-medication eligibility rather than traditional prescription dominance.
Growth Catalysts
- Aging demographics:Germany's expanding elderly population intensifies demand for digestive health and pain management solutions that bypass clinician visits.
- REACH and CSRD compliance investments:Sustainability disclosure mandates favor large manufacturers with established documentation infrastructure, consolidating shelf access.
- Digital pharmacy platforms:E-commerce integration is decomposing traditional pharmacy gatekeeper control in markets where regulatory dispensing requirements permit remote fulfillment.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing clusters in Asian manufacturing hubs expose European formulators to geopolitical freight disruptions and customs bottlenecks.
- BfArM and ANSM advertising constraints:German and French pharmacovigilance standards restrict comparative efficacy claims, compressing marketing differentiation space.
- Generic substitution pressure:Off-patent analgesic molecules face price erosion from private-label pharmacy chains capturing margin-conscious switchers.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania exhibit lower OTC per-capita consumption than Western benchmarks, presenting volume expansion terrain for gastrointestinal and respiratory entrants.
- EU Green Deal packaging mandates:Recyclable blister and bottle requirements create first-mover advantage for manufacturers with validated biodegradable polymer supply chains.
- Telehealth-OTC convergence:Symptom-checker algorithms and remote pharmacist consultations are unlocking prescription-free access pathways for chronic condition management categories.
Industry Challenges
- Pharmacovigilance talent scarcity:Post-market surveillance and adverse event reporting functions face recruitment gaps as regulatory complexity outpaces university program outputs.
- Legacy ERP integration:Batch record digitization and serialized packaging track-and-trace requirements strain IT infrastructure at mid-sized manufacturers.
- Cross-border labeling harmonization:EMA centralized approvals still require national language adaptations that fragment production runs and inflate inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Over-The-Counter (OTC) Drugs Market |
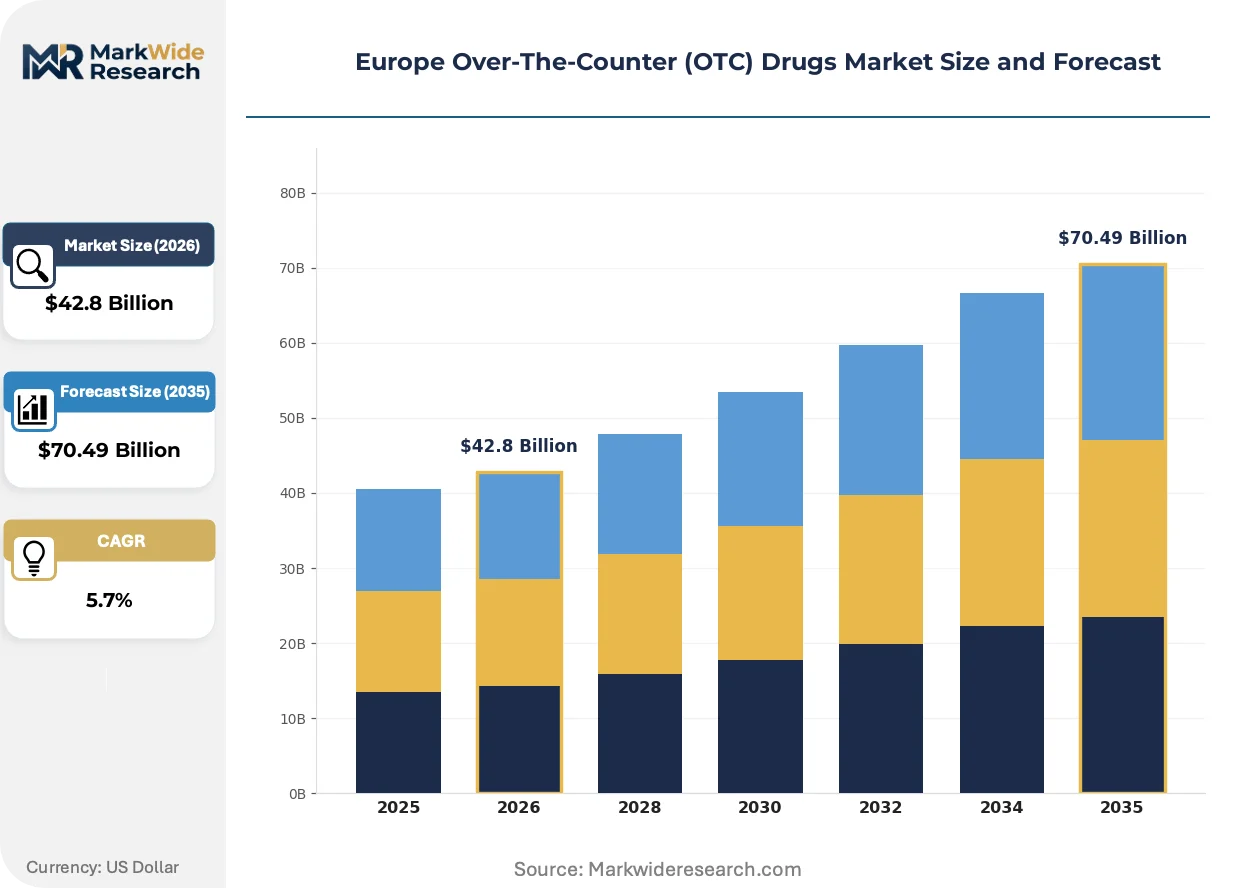
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Cold & Cough, Gastrointestinal, Dermatological Use Case: Pain Relief, Allergy Treatment, Digestive Health, Skin Care End User: Adults, Pediatrics, Elderly, Pregnant Women Distribution Channel: Pharmacies, Supermarkets, Online Retail, Convenience Stores |
| Companies Covered | Bayer AG, Sanofi, GSK plc, Reckitt Benckiser Group plc, Haleon, Kenvue, Procter & Gamble Company, Stada Arzneimittel, Boehringer Ingelheim, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Over-The-Counter (OTC) Drugs Market Shifts & Advancements
Self-diagnosis tools and sustainability mandates are forcing simultaneous reinvention of product format, packaging substrate, and patient communication channels across European OTC portfolios.
Connected health devices and smartphone-integrated symptom trackers are decomposing the traditional pharmacist-patient consultation model. Younger cohorts in France and the Netherlands now initiate treatment journeys via algorithmic self-triage before entering physical retail channels. This behavior is compressing brand loyalty windows and elevating digital shelf visibility above pharmacy counter placement.
EMA's streamlined switch assessment pathways and the EU's consolidated marketing authorization procedures are accelerating prescription-to-OTC transitions. Germany's BfArM has reduced review timelines for well-established molecules, enabling faster competitive entry in mature analgesic categories. French regulators at ANSM are aligning national advertising standards with centralized EMA labeling, reducing compliance fragmentation for pan-European launches.
Subscription-based replenishment models are displacing episodic pharmacy purchases for chronic condition management. German consumers with recurring digestive health needs now favor automated delivery services over monthly retail trips. This pattern concentrates purchasing data with platform operators and erodes traditional wholesaler-distributor relationships in urban catchment areas.
Europe Over-The-Counter (OTC) Drugs Market Segmentation
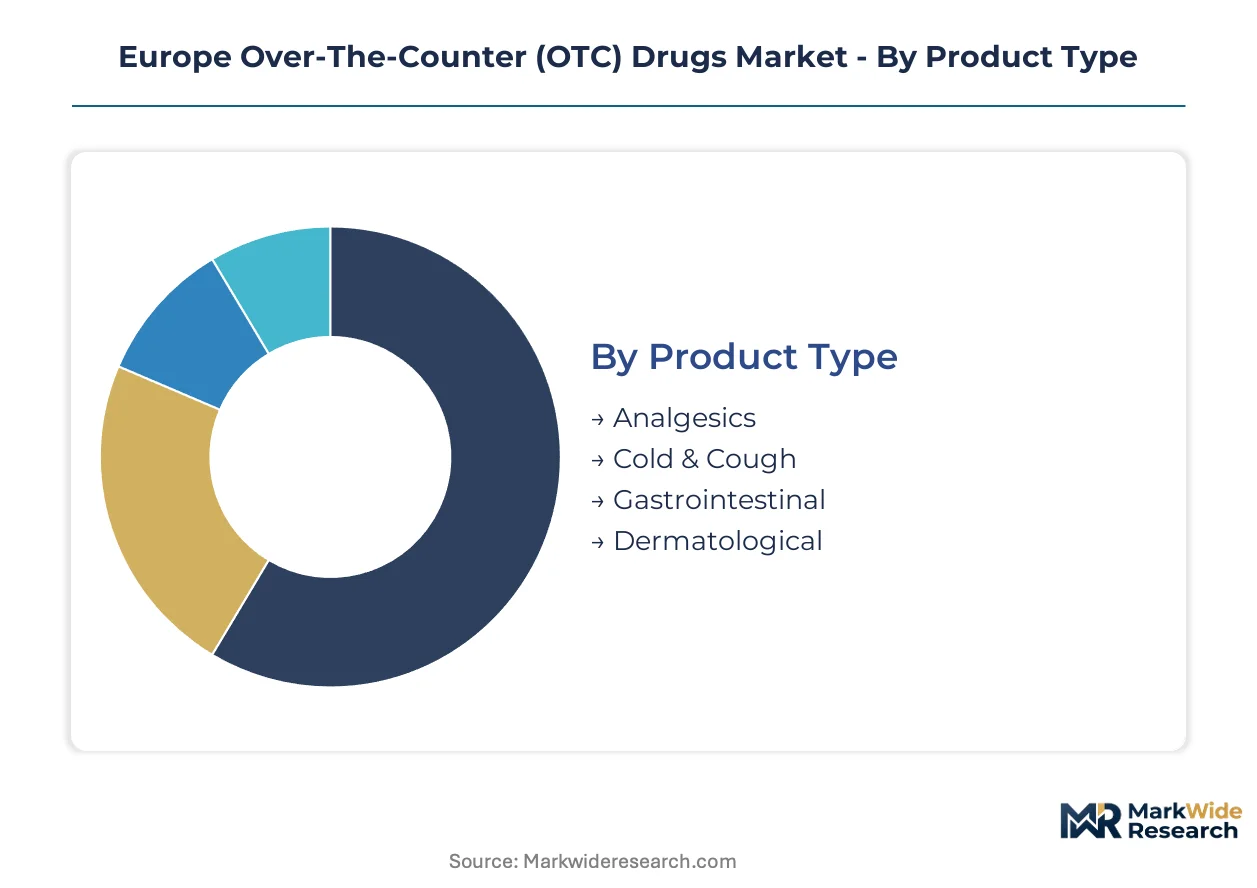
Segmentation in the European OTC drugs market determines which therapeutic categories flow through pharmacy-controlled channels versus open retail networks. Channel eligibility rules vary by member state, creating patchwork distribution strategies that manufacturers must navigate. Understanding these segment-channel linkages reveals where regulatory barriers protect margin pools and where price competition intensifies.
Product Type:
Pharmacy-led distribution dominates higher-potency analgesics and prescription-switched gastrointestinal products, while supermarkets and convenience stores capture standard-strength cold remedies and basic dermatological formats.
- Analgesics:Formulations containing ibuprofen, paracetamol, and acetylsalicylic acid at fixed dosages up to prescription thresholds. German pharmacy chains BfArM-classify higher-strength tablets for behind-counter dispensing, concentrating value capture in professional channels despite supermarket penetration of standard doses. By volume, Analgesics leads. By growth pace, Gastrointestinal is ahead.
- Cold & Cough:Decongestant, antitussive, and expectorant combinations for upper respiratory symptom relief. French and UK supermarkets capture substantial volume through self-selection aisles, though pseudoephedrine-containing variants remain pharmacy-restricted under national precursor regulations.
- Gastrointestinal:Antacids, proton pump inhibitors at OTC doses, and anti-diarrheal agents. ANSM in France and BfArM in Germany have accelerated prescription-to-OTC switches for well-established molecules, expanding self-treatment eligibility for chronic digestive conditions.
- Dermatological:Topical antifungals, corticosteroids at low potency, and acne treatments. Expanded indication approvals through EMA centralized procedures are widening pharmacy shelf placement for previously prescription-only skin therapies.
Margin concentration follows regulatory classification tiering rather than absolute sales volume, with switched prescription molecules commanding premium positioning in professional channels.
Use Case:
Application-driven demand patterns reveal distinct customer journey starting points, from acute symptom response to chronic condition maintenance protocols.
- Pain Relief:Acute musculoskeletal, headache, and menstrual pain management. German elderly populations drive recurring purchases through pharmacy loyalty programs, while younger French consumers increasingly initiate via digital symptom-checkers before channel selection.
- Allergy Treatment:Antihistamine and intranasal corticosteroid formats for seasonal and perennial rhinitis. Northern European markets exhibit extended purchase seasons due to longer pollen calendars, stretching inventory planning cycles for retailers.
- Digestive Health:Functional dyspepsia, reflux, and irritable bowel symptom management. Subscription replenishment models in urban Germany are displacing episodic pharmacy visits for this recurring-need category.
- Skin Care:Cosmetic-therapeutic hybrids addressing acne, eczema maintenance, and sun damage. Pharmacy beauty positioning in France and Italy supports premium pricing versus mass-market cosmetic alternatives.
Pain Relief generates the highest absolute transaction frequency. Digestive Health demonstrates the steepest expansion trajectory as switch programs broaden self-treatment eligibility.
End User:
Patient population targeting determines formulation specifications, dosing convenience features, and communication channel selection across European markets.
- Adults:Standard tablet, capsule, and liquid formats for the core self-medicating population aged 18-64. Marketing investments concentrate on digital channels and pharmacy point-of-sale materials in France and the Netherlands.
- Pediatrics:Weight-calibrated dosing systems, palatable liquid suspensions, and child-resistant packaging. BfArM and ANSM enforce stricter advertising limitations for this segment, constraining promotional latitude.
- Elderly:Large-print labeling, blister packs with adherence aids, and drug-interaction screening protocols. Germany's aging demographic intensifies demand for digestive and pain management solutions with pharmacist consultation support.
- Pregnant Women:Teratogenicity-tested formulations with explicit gestational safety labeling. Pharmacy channel control remains mandatory across most member states due to liability considerations and contraindication complexity.
The Elderly segment anchors current volume. Pediatric formats are climbing the fastest as formulation innovation expands age-appropriate options.
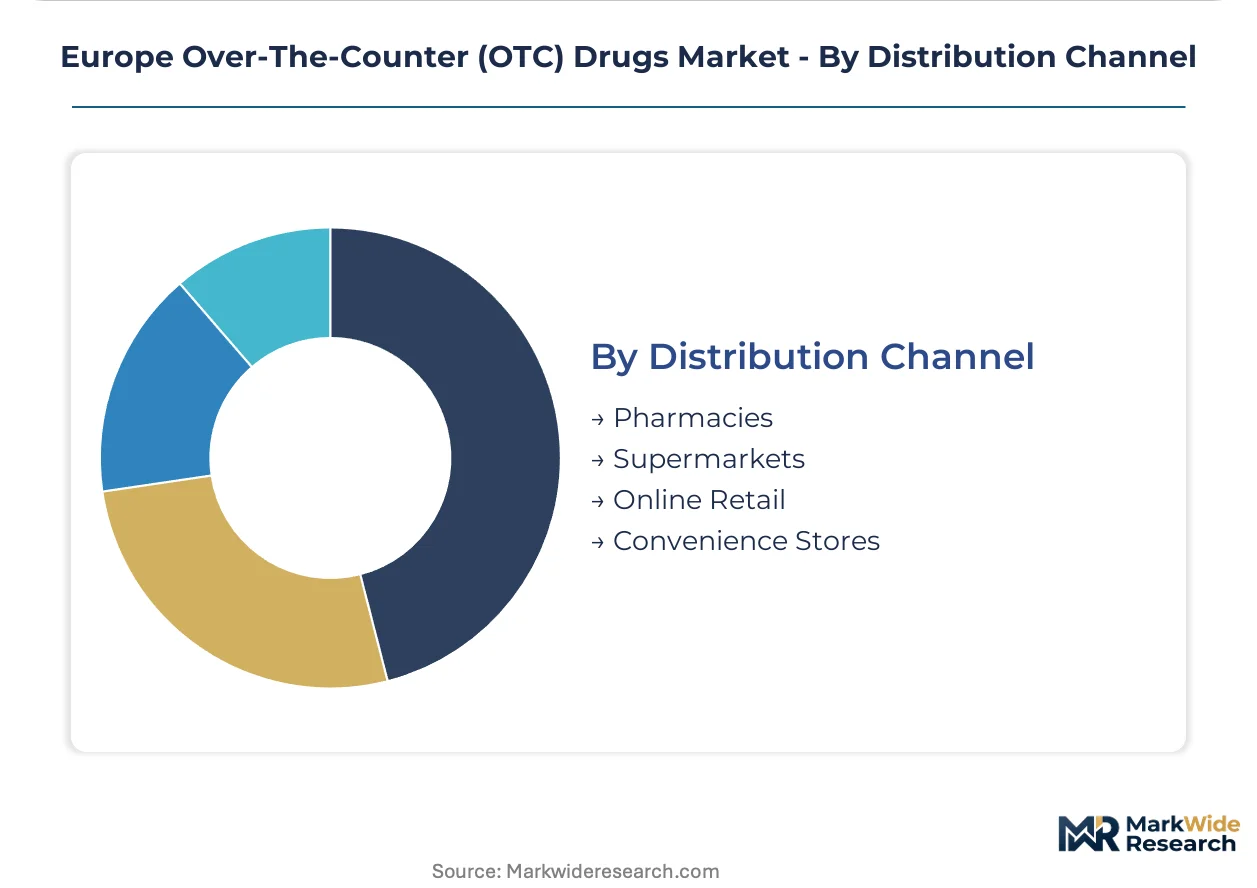
Distribution Channel:
Channel structure reflects national regulatory dispensing requirements, with pharmacy control varying by therapeutic potency and switch history.
- Pharmacies:Professional-controlled access for higher-potency analgesics, switched prescription molecules, and all pediatric and pregnancy-targeted formats. German and French pharmacy networks retain dominant share through regulatory dispensing mandates and insurance reimbursement integration.
- Supermarkets:Self-service distribution for standard-strength cold remedies, basic analgesics, and dermatological cosmetics. UK and Nordic markets exhibit highest supermarket penetration due to liberalized retail pharmacy regulations.
- Online Retail:Remote fulfillment where national regulations permit, concentrated in markets with harmonized distance-selling frameworks. Platform operators capture purchasing data that erodes traditional wholesaler relationships.
- Convenience Stores:Emergency and impulse purchase occasions for travel-sized formats and single-dose pain relief. Limited to lowest-potency classifications under national pharmacy practice acts.
Pharmacies dominate value capture. Online Retail is gaining share fastest where regulatory harmonization enables cross-border fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation and packaging operations cluster in Germany's industrial corridor, with distribution networks radiating through Rhine-Ruhr logistics hubs toward French and Benelux markets. National pharmacy regulations fragment last-mile access, creating divergent channel strategies across member states.
Germany
Aging demographics in North Rhine-Westphalia and Bavaria intensify demand for digestive health and pain management self-treatment. BfArM's streamlined switch assessment pathways accelerate prescription-to-OTC transitions for established molecules. Frankfurt's pharmaceutical logistics cluster anchors pan-European distribution for German-manufactured analgesics and gastrointestinal formats.
France
ANSM's evolving advertising standards reshape promotional boundaries for pharmacy-restricted products, compressing marketing differentiation space. Paris and Lyon concentrate formulation R&D facilities serving both domestic and export markets. Subscription replenishment models in urban Île-de-France are displacing episodic pharmacy visits for chronic digestive condition management.
United Kingdom
Liberalized retail pharmacy regulations permit broader supermarket penetration of standard-strength cold remedies and basic analgesics than continental counterparts. London's health technology cluster incubates symptom-checker algorithms that initiate treatment journeys before channel selection. Manchester and Birmingham distribution hubs handle cross-border fulfillment into Ireland where regulatory harmonization permits.
Italy
Lombardy's pharmaceutical manufacturing base supplies Mediterranean markets with dermatological and gastrointestinal OTC formats. Pharmacy-led distribution remains mandatory for higher-potency classifications under national practice acts. Milan's logistics infrastructure supports seasonal inventory surges for allergy treatment products across northern European pollen calendars.
Poland
Lower per-capita OTC consumption than Western benchmarks presents volume expansion terrain for gastrointestinal and respiratory entrants. Warsaw and Krakow pharmacy networks retain dominant share through regulatory dispensing mandates. EU structural funds accelerate cold-chain infrastructure investments for temperature-sensitive pediatric and pregnancy-targeted formulations.
Europe Over-The-Counter (OTC) Drugs Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates that leverage prescription heritage and pharmacy channel control. The vendor base spans three tiers: legacy drug manufacturers with switch program expertise, consumer health spin-offs optimizing brand portfolios, and private-label pharmacy chains capturing price-sensitive switchers. Strategic moves center on portfolio restructuring around self-medication eligibility and sustainability-compliant packaging investments that satisfy EU Green Deal mandates.
Within the diversified pharmaceutical tier, Bayer AG and Sanofi anchor positions through analgesics heritage and gastrointestinal specialization respectively. Haleon occupies a distinct position as a consumer health pure-play with brand strength in oral health and respiratory segments. GSK plc represents the prescription-to-OTC transition archetype through its legacy switch program participation.
| Leading Market Players |
|---|
| Bayer AG |
| Sanofi |
| GSK plc |
| Reckitt Benckiser Group plc |
| Haleon |
| Kenvue |
| Procter & Gamble Company |
| Stada Arzneimittel |
| Boehringer Ingelheim |
| Others |
Supply & Pricing Matrix
Ninety-day API inventory buffers at European formulators now separate agile responders from margin-squeezed competitors, concentrating pricing power with manufacturers who secured strategic stockpiles ahead of REACH compliance deadlines and freight disruption cycles.
Pricing Analysis
EMA centralized authorization pathways dictate the pricing tier structure across European OTC markets, with switched prescription molecules commanding premium positioning in pharmacy-controlled channels while standard-strength analgesics face commodity pressure in supermarket aisles. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, bioequivalence certification status, and pharmacist recommendation intensity. Cost compression in off-patent analgesic categories is intensifying because private-label pharmacy chains capture switchers through direct-to-consumer digital platforms. Price-sensitive buyers cluster in supermarket and convenience channels seeking single-dose travel formats, whereas chronic condition patients in pharmacy loyalty programs exhibit lower elasticity for subscription-based digestive health replenishment.
Supply Chain Analysis
Strategic stockpiling of active pharmaceutical ingredients now dominates inventory strategy across European OTC manufacturers, displacing just-in-time preferences that proved vulnerable during pandemic-era freight bottlenecks and customs delays. API sourcing draws from India, China, and Switzerland, with ibuprofen and paracetamol precursors particularly concentrated in Asian manufacturing hubs. Single-source vulnerability for specialized excipients and child-resistant packaging polymers exposes formulators to regulatory restriction cascades when environmental compliance deadlines shift. Distribution runs through Rhine-Ruhr logistics clusters for German-manufactured analgesics, with radiating networks serving French and Benelux pharmacy chains under national dispensing mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized pharmacovigilance talent pools have thinned below replacement rates across European OTC operations, constraining expansion velocity for manufacturers lacking established adverse-event reporting infrastructure and EMA relationship networks.
For Market Incumbents: Fortify pharmacy channel control through exclusive distribution agreements for switched prescription molecules in Germany and France, while accelerating backward integration into sustainable blister packaging polymers to preempt EU Green Deal compliance gaps. Digital pharmacy platform operators threaten traditional wholesaler relationships by capturing chronic-condition subscription data; defend against disintermediation by embedding pharmacist consultation services into direct-to-patient replenishment apps. For New Entrants and Emerging Players: EMA streamlined switch assessment fast-tracks offer the most penetrable entry vector for gastrointestinal and respiratory categories with well-established molecule histories. Target Poland and Romania where per-capita OTC consumption lags Western benchmarks and pharmacy networks remain fragmented. Launch through telehealth-integrated symptom-checker partnerships that initiate treatment journeys before channel selection, bypassing incumbent shelf dominance. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates spinning non-core consumer health divisions to focus on prescription pipeline investments. Long-term viability hinges on switch program expertise and sustainability-compliant packaging capabilities rather than brand equity alone. Monitor BfArM and ANSM advertising standard harmonization as the inflection indicator for pan-European launch scalability; divergence in national promotional restrictions would compress marketing differentiation space and favor regionally focused operators over centralized players.| Strategic Initiative | Industry Significance |
|---|---|
| Prescription-to-OTC Switch Program Expansion | EMA centralized pathways accelerate competitive entry in mature therapeutic categories with established safety profiles. |
| Sustainable Packaging Transition | EU Green Deal mandates force reformulation investments that favor manufacturers with validated biodegradable polymer supply chains. |
| Digital Pharmacy Platform Integration | Symptom-checker algorithms and remote pharmacist consultations unlock prescription-free access for chronic condition management. |
| Eastern European Market Development | Poland and Romania present volume expansion terrain where per-capita consumption remains below Western benchmarks. |
| Subscription-Based Replenishment Models | Automated delivery services for digestive health needs concentrate purchasing data and erode traditional wholesaler relationships. |
Research Methodology
A spread of perspectives from regulatory affairs leads at EMA and national agencies, pharmacy chain procurement directors, gastrointestinal brand managers, and pharmacovigilance specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through EMA centralized authorization databases, BfArM switch assessment filings, ANSM advertising standard rulings, and EU structural fund disbursement records for cold-chain infrastructure. Bottom-up volume modeling across product type, use case, end user, and distribution channel dimensions triangulated against top-down pharmaceutical expenditure forecasts from national health accounts.
Segmentation dimensions modeled include therapeutic category, application-driven demand pattern, patient population targeting, and channel structure across the analysis window. CAGRs were derived from growth driver elasticity estimates applied to base-year consumption data, with cross-validation against historical switch program velocity and demographic aging trajectories. Forecast inputs incorporated EMA pipeline assessment timelines, REACH compliance cost pass-through assumptions, and digital pharmacy regulatory harmonization progress indicators.
Decision-makers should treat outputs as directional under stable regulatory dispensing requirements and continued API supply access; material deviation would warrant model refresh. Forecasts reflect assumptions of sustained switch program momentum and gradual digital channel penetration without abrupt national pharmacy practice act liberalization. Revision becomes warranted when API supply concentration crosses disruption thresholds or when BfArM and ANSM advertising standard divergence exceeds historical variance bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Seasonal Influenza Vaccines Therapeutics Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Asia-Pacific Cancer Vaccines Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Global Caspofungin Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market