
 Late Stage Chronic Kidney Disease Therapeutics Market | 2026-2036
Late Stage Chronic Kidney Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Late Stage Chronic Kidney Disease Therapeutics Market Foresight
The capability gap between integrated dialysis service providers and standalone pharmaceutical developers is collapsing as treatment protocols merge drug and device workflows. Fresenius leverages its captive clinic network to bundle biologic administration with dialysis sessions. Baxter anchors its position through peritoneal dialysis solutions that integrate phosphate binder delivery. AstraZeneca competes via SGLT2 inhibitor portfolios that delay disease progression before dialysis dependency.
Late stage chronic kidney disease therapeutics encompass pharmacologic agents designed to manage complications of glomerular filtration rates below 15 mL/min, including synthetic erythropoietin analogs with specific glycosylation patterns that extend half-life to 24–72 hours and non-calcium phosphate binders with lanthanum or sevelamer backbones. These agents primarily sustain hemoglobin targets, control mineral bone disorder, and reduce cardiovascular mortality in pre-dialysis and dialysis populations. Erythropoiesis-Stimulating Agents dominate current revenue pools due to chronic administration requirements, while Vitamin D Analogs represent concentrated margin opportunities in home care settings where oral calcitriol analogs displace intravenous formulations. The Dialysis application segment leads volume consumption, though Disease Progression Delay commands premium pricing as nephrologists prioritize SGLT2 and finerenone protocols.
FDA REMS requirements for erythropoiesis-stimulating agents mandate prescriber certification and patient counseling documentation, elevating compliance costs for manufacturers while restricting market entry. EMA's MDR classification for combination drug-device dialysis systems imposes clinical evidence thresholds that favor established players with trial infrastructure. Stakeholders must monitor how CMS reimbursement shifts for oral phosphate binders versus intravenous alternatives reshape site-of-care economics and manufacturer channel strategy.
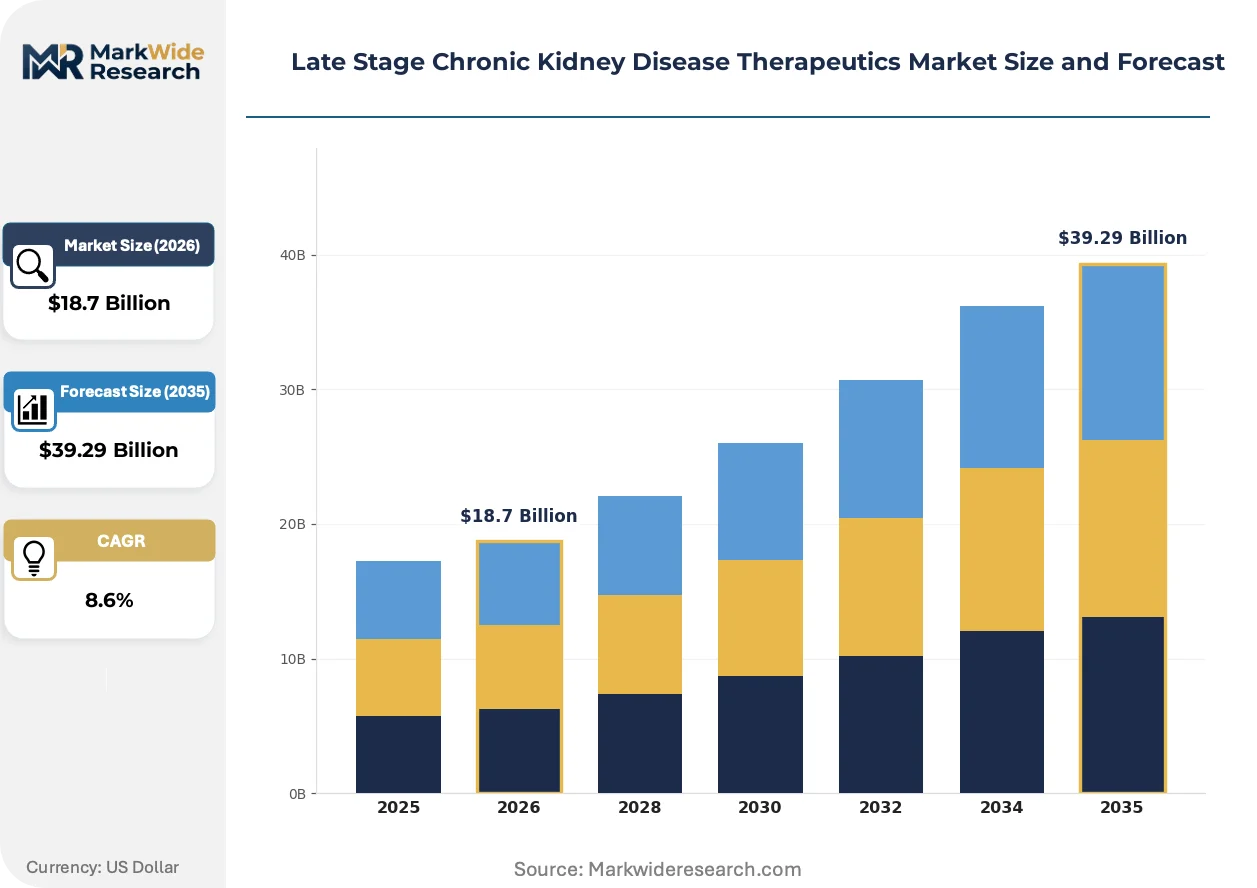
Market Dynamics
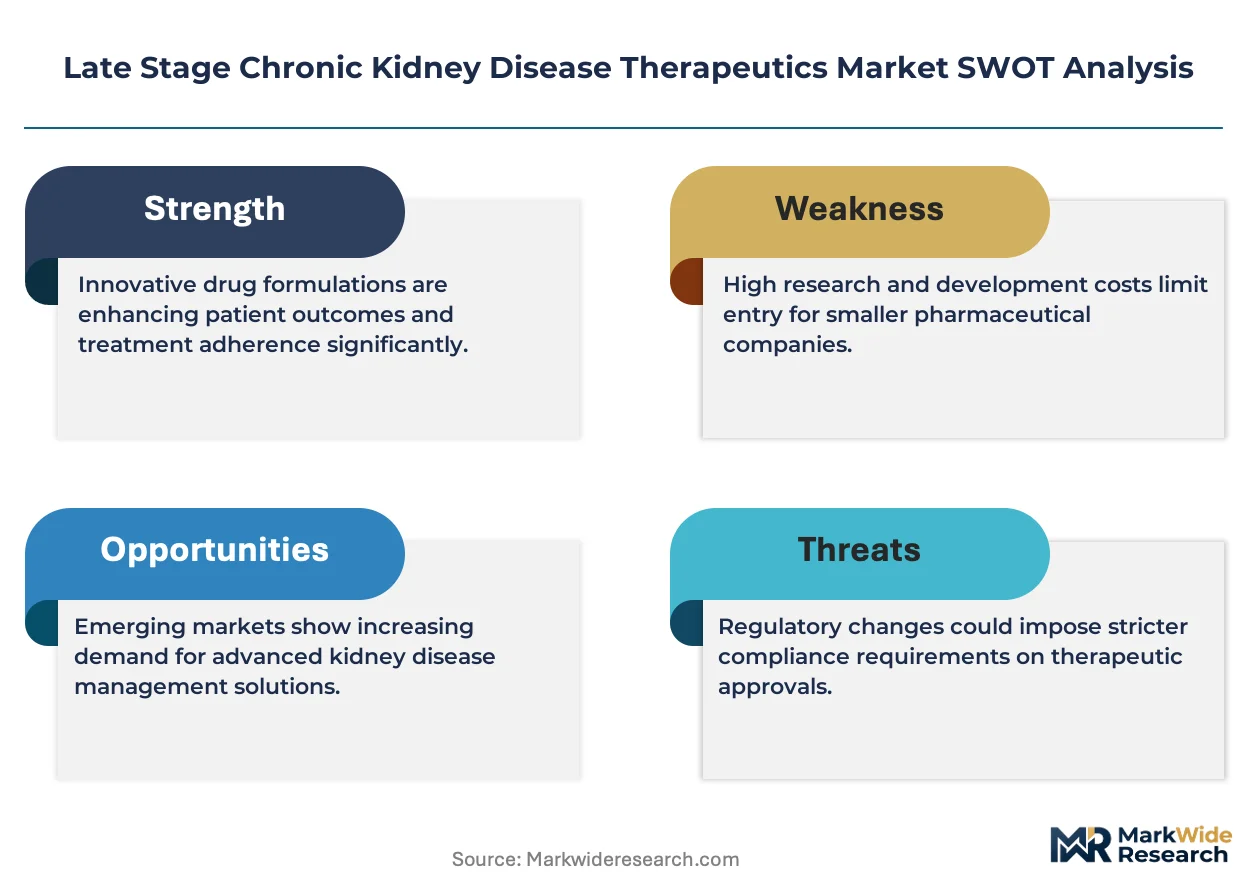
FDA REMS mandates for erythropoiesis-stimulating agents have restructured prescriber certification workflows, elevating compliance burdens that favor integrated dialysis providers over standalone pharmaceutical developers. This regulatory density is compressing the capability gap between drug and device workflows.
Growth Catalysts
- Diabetes-related nephropathy prevalence:The United States sustains concentrated demand for renal replacement therapies as metabolic syndrome drives dialysis dependency rates in Medicare populations.
- CMS reimbursement structures:Favorable payment policies for home-based peritoneal dialysis accelerate site-of-care migration away from in-center hemodialysis.
- SGLT2 inhibitor protocols:Nephrology guidelines now prioritize sodium-glucose cotransporter-2 inhibitors for disease progression delay before dialysis dependency.
Market Restraints
- REMS documentation burden:FDA prescriber certification and patient counseling requirements elevate fixed compliance costs for erythropoiesis-stimulating agent manufacturers.
- Active pharmaceutical ingredient concentration:Synthetic erythropoietin analog production clusters with contract manufacturers in India and China, exposing supply chains to geopolitical friction.
- Intravenous vitamin D displacement:Oral calcitriol analogs in home care settings compress margins for hospital-based intravenous formulation providers.
Strategic Opportunities
- Pre-dialysis population:Disease progression delay protocols remain underpenetrated among Medicare Advantage plans seeking to defer renal replacement therapy costs.
- Combination drug-device systems:EMA MDR classification creates clinical evidence thresholds that reward established trial infrastructure for integrated phosphate binder delivery.
- Telehealth-enabled anemia management:Remote hemoglobin monitoring protocols open channel innovation for biologic administration outside traditional dialysis center footprints.
Industry Challenges
- Nephrologist workforce scarcity:Fellowship training pipeline constraints limit prescriber capacity for complex mineral bone disorder management in rural service areas.
- Legacy EHR integration:Dialysis center data systems require costly reconfiguration to capture REMS-compliant patient counseling documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Late Stage Chronic Kidney Disease Therapeutics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erythropoiesis-Stimulating Agents, Phosphate Binders, Vitamin D Analogs, Antihypertensive Agents Application: Dialysis, Transplantation, Symptomatic Management, Disease Progression Delay End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Delivery Mode: Oral, Intravenous, Subcutaneous, Inhalation |
| Companies Covered | Fresenius, Baxter, Nikkiso, B. Braun, Asahi Kasei, Nipro, Toray, Medtronic, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Late Stage Chronic Kidney Disease Therapeutics Market Shifts & Advancements
Treatment protocols are converging across pharmaceutical and device boundaries as integrated care models reshape how anemia, mineral bone disorder, and cardiovascular complications are managed in late-stage populations.
Extended-half-life erythropoiesis-stimulating agents with engineered glycosylation patterns are fragmenting administration schedules from thrice-weekly to biweekly or monthly intervals. Dialysis chains with captive pharmacy operations adopt these formulations to reduce chair-time utilization and improve patient throughput. The technology is fragmenting revenue concentration among traditional short-acting product manufacturers.
EMA MDR classification for combination drug-device dialysis systems imposes clinical evidence thresholds that extend regulatory timelines. Manufacturers must generate prospective trial data for phosphate binder delivery integration. Peritoneal dialysis solution providers face the steepest compliance burden as they retrofit legacy formulations for combined labeling.
Home-based care preferences among Medicare beneficiaries are redirecting site-of-care economics toward oral phosphate binders and subcutaneous erythropoiesis-stimulating agents. Dialysis providers unbundle traditional in-center service packages to capture patients earlier in disease progression. The United States exhibits the most pronounced shift as Medicare reimbursement differentials favor home modalities.
Late Stage Chronic Kidney Disease Therapeutics Market Segmentation
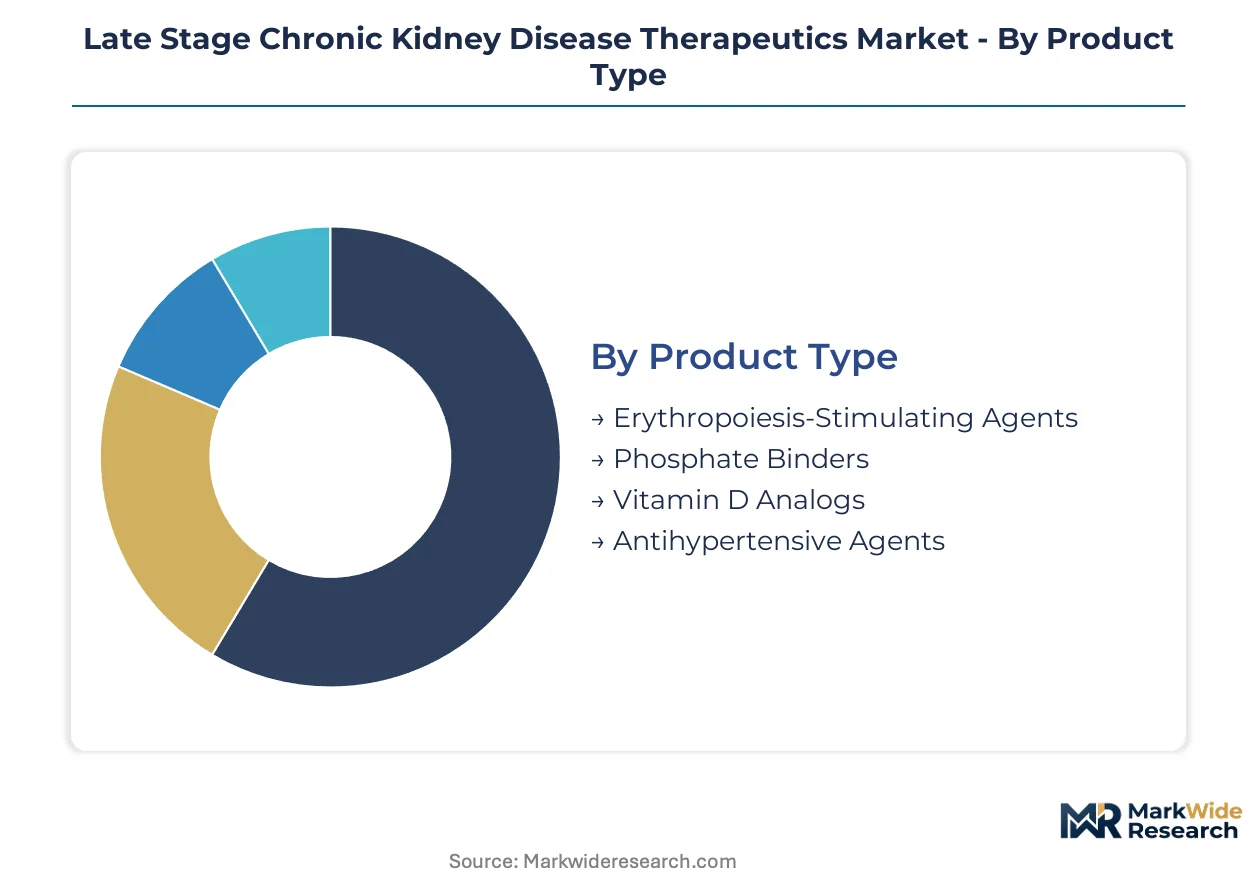
Segmentation in late-stage chronic kidney disease therapeutics reveals how treatment protocols fragment across care settings and patient acuity levels. Product portfolios, application contexts, and delivery infrastructure each demand distinct commercial strategies.
Product Type:
Domestic demand concentrates on biologics with established reimbursement pathways, while export-led growth tracks phosphate binder formulations with lanthanum or sevelamer backbones.
- Erythropoiesis-Stimulating Agents:Synthetic erythropoietin analogs with engineered glycosylation patterns extend half-life to 24–72 hours, enabling reduced dosing frequency. Dialysis centers in the United States favor extended-half-life formulations to maximize chair-time throughput and patient compliance.
- Phosphate Binders:Non-calcium binders with lanthanum carbonate or sevelamer hydrochloride backbones control mineral bone disorder without vascular calcification risk. Medicare reimbursement differentials between oral and intravenous formulations reshape prescribing patterns across nephrology practices.
- Vitamin D Analogs:Oral calcitriol analogs displace intravenous formulations in home care settings where patient self-administration reduces facility dependency.
- Antihypertensive Agents:Renin-angiotensin system inhibitors and mineralocorticoid receptor antagonists manage cardiovascular comorbidity in pre-dialysis populations.
Erythropoiesis-Stimulating Agents command the established base. The steepest expansion runs through Phosphate Binders.
Application:
Cost tier stratification separates high-frequency dialysis maintenance from premium-priced disease modification protocols that defer renal replacement therapy.
- Dialysis:Anemia management and mineral bone disorder control dominate volume consumption in both hemodialysis and peritoneal modalities. United States dialysis chains bundle biologic administration with treatment sessions to capture pharmacy margin.
- Disease Progression Delay:SGLT2 inhibitors and non-steroidal mineralocorticoid receptor antagonists command premium pricing as nephrologists prioritize protocols that slow glomerular filtration rate decline before dialysis dependency.
- Transplantation:Immunosuppressive regimens and post-transplant complication management sustain niche demand within specialized transplant centers.
- Symptomatic Management:Uremic symptom control and cardiovascular risk modification address quality-of-life endpoints in palliative care contexts.
Dialysis absorbs the highest volume. Disease Progression Delay climbs the fastest as payers seek to defer renal replacement costs.
End User:
Site-of-care migration from institutional settings to home environments restructures channel economics and product formulation requirements.
- Home Care:Subcutaneous erythropoiesis-stimulating agents and oral phosphate binders enable patient self-management outside dialysis center footprints. Medicare Advantage plans in the United States accelerate this shift through reimbursement differentials favoring home-based modalities.
- Hospitals:Intravenous vitamin D analogs and acute complication management sustain inpatient pharmacy demand for severe mineral bone disorder cases.
- Clinics:Pre-dialysis nephrology practices concentrate disease progression delay protocols and patient education for emerging renal replacement candidates.
- Long-term Care Facilities:Skilled nursing settings manage stable dialysis patients with reduced transportation capacity.
Hospitals retain the acute case base. Home Care gains share fastest as beneficiary preferences and payer incentives align.
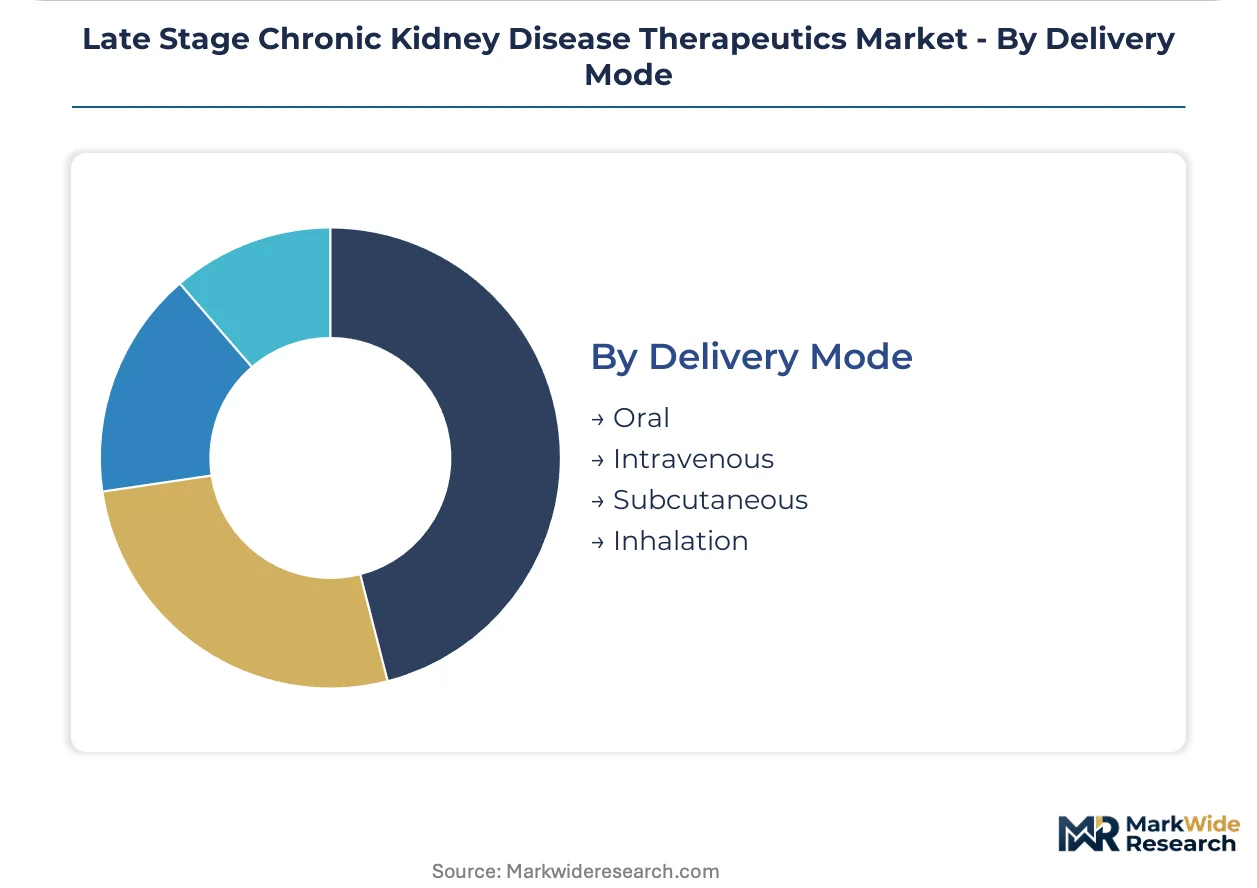
Delivery Mode:
Supply concentration in parenteral manufacturing creates capability gaps that oral formulation developers exploit for channel access.
- Intravenous:Direct bloodstream delivery of erythropoiesis-stimulating agents and vitamin D analogs ensures bioavailability in dialysis center settings where patient compliance is supervised.
- Oral:Phosphate binders and calcitriol analogs in tablet or capsule form enable home administration without clinical infrastructure.
- Subcutaneous:Extended-half-life erythropoiesis-stimulating agents reduce injection frequency for home-based anemia management.
- Inhalation:Investigational dry powder formulations target uremic toxin clearance with limited current commercial penetration.
Intravenous delivery anchors the established base. Oral administration expands most quickly as site-of-care economics favor home modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dialysis chains exhibit the lowest price elasticity as bundled reimbursement insulates patients from direct drug costs, while emerging markets in Asia face acute sensitivity to phosphate binder out-of-pocket expenses. European markets sit mid-range, with reference pricing systems compressing margins on established erythropoiesis-stimulating agents.
United States
Medicare Advantage plans drive concentrated demand for home-based peritoneal dialysis and oral phosphate binders as they seek to defer renal replacement therapy costs. FDA REMS mandates for erythropoiesis-stimulating agents require prescriber certification and patient counseling documentation, elevating compliance burdens. The Southeast dialysis corridor spanning Florida and Georgia anchors expansion of integrated clinic-pharmacy operations.
Germany
Nephrology practices prioritize disease progression delay protocols using SGLT2 inhibitors and finerenone to slow glomerular filtration rate decline. EMA MDR classification for combination drug-device dialysis systems imposes clinical evidence thresholds that extend regulatory timelines. The Rhine-Ruhr metropolitan cluster concentrates contract research organizations supporting phosphate binder delivery integration trials.
Japan
Aging demographics sustain demand for extended-half-life erythropoiesis-stimulating agents that reduce injection frequency for elderly home care patients. PMDA review pathways for biologics with novel glycosylation patterns require extensive pharmacokinetic bridging studies. The Kansai region around Osaka anchors domestic manufacturing of synthetic erythropoietin analogs.
China
Rapid urbanization drives diabetes-related nephropathy prevalence in coastal provinces, expanding the pre-dialysis population eligible for disease modification therapies. NMPA priority review vouchers accelerate approval timelines for mineralocorticoid receptor antagonists with cardiovascular outcome data. The Yangtze River Delta cluster concentrates active pharmaceutical ingredient production for erythropoietin analog contract manufacturers.
India
Price-sensitive patients in tier-2 cities favor oral phosphate binders over intravenous alternatives as out-of-pocket costs dominate purchasing decisions. CDSCO tightened bioequivalence requirements for generic sevelamer formulations, extending approval timelines for domestic manufacturers. The Hyderabad-Visakhapatnam corridor anchors contract manufacturing organization capacity for lanthanum carbonate API synthesis.
Late Stage Chronic Kidney Disease Therapeutics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated dialysis service providers commanding workflow integration advantages while pharmaceutical developers retain molecular innovation capabilities. The market structure exhibits tiered consolidation: a narrow premium band of vertically integrated clinic operators, a broad mid-tier of specialty pharmaceutical manufacturers, and fragmented generic producers competing on phosphate binder price. Three archetypes dominate—captive clinic networks bundling drug delivery with treatment sessions, pure-play biologic developers with extended-half-life platforms, and diversified medtech firms retrofitting dialysis solutions for combination labeling. Competitive moves concentrate on strategic partnerships between device manufacturers and phosphate binder developers, plus geographic expansion of home care service footprints.
Among integrated dialysis service providers, Fresenius and Baxter exemplify the captive clinic network archetype, leveraging direct patient access to bundle biologic administration with treatment sessions. AstraZeneca occupies a position within the pharmaceutical tier focused on disease progression delay, representing pure-play molecular innovation without vertical integration into service delivery. These three anchors illustrate how competitive positioning fragments across workflow control versus molecular differentiation.
| Leading Market Players |
|---|
| Fresenius |
| Baxter |
| Nikkiso |
| B. Braun |
| Asahi Kasei |
| Nipro |
| Toray |
| Medtronic |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Take-or-pay contracts for synthetic erythropoietin analog active pharmaceutical ingredients lock in multi-year supply access for integrated dialysis providers while capping price volatility exposure. These arrangements concentrate procurement leverage among Fresenius and Baxter, whose captive clinic networks absorb volume commitments that standalone pharmaceutical developers cannot match.
Pricing Analysis
After-sales revenue from anemia management protocols drives lifetime value for dialysis chains bundling biologic administration with treatment sessions. Three-tier pricing structure across premium extended-half-life formulations, standard synthetic erythropoietin analogs, and economy-tier biosimilars stratifies by glycosylation engineering sophistication and FDA REMS certification burden. Cost compression in economy-tier phosphate binders intensifies as Indian contract manufacturers expand generic sevelamer capacity. Medicare Advantage plans exhibit lowest price sensitivity due to bundled reimbursement, while tier-2 Indian cities face acute out-of-pocket pressure.
Supply Chain Analysis
Strategic stockpiling of lanthanum carbonate and sevelamer hydrochloride raw materials dominates over just-in-time preferences given API concentration risks. Active pharmaceutical ingredient synthesis concentrates in India, China, and the United States, with the Yangtze River Delta and Hyderabad-Visakhapatnam corridor anchoring contract manufacturing organization capacity. Synthetic erythropoietin production draws from genetically engineered cell line dependencies and specialized glycosylation equipment. Single-source vulnerability for novel glycosylation enzyme suppliers threatens extended-half-life formulation timelines. Distribution runs through integrated dialysis service networks and specialty pharmaceutical wholesalers to hospital and home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power concentrates among Medicare Advantage plans and integrated dialysis chains, compressing margin capture for standalone pharmaceutical developers unable to secure captive clinic access.
For Market Incumbents: Secure backward integration into phosphate binder API synthesis to defend against Indian contract manufacturer price erosion. Lock in exclusive formulary placement with Medicare Advantage plans seeking to defer renal replacement therapy costs through disease progression delay protocols. FDA REMS certification infrastructure represents a defendable moat against emerging biosimilar entrants lacking prescriber education networks. For New Entrants and Emerging Players: Anchor in telehealth-enabled anemia management platforms that bypass traditional dialysis center footprints for home care patient capture. The pre-dialysis population within Medicare Advantage plans offers the most penetrable white space, as nephrologist workforce scarcity limits incumbent reach into rural service areas. Partner with peritoneal dialysis solution providers seeking phosphate binder delivery integration to accelerate regulatory pathway access. For Investors and Strategic Acquirers: Extended-half-life biologic developers with novel glycosylation platforms and established FDA REMS infrastructure offer the strongest acquisition target archetype for portfolio diversification. Long-term viability hinges on demonstrating cardiovascular outcome differentiation against standard-of-care erythropoiesis-stimulating agents. Watch CMS reimbursement shifts for oral versus intravenous phosphate binders as the inflection indicator for site-of-care economics reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Investment | Prescriber certification networks create regulatory moats against biosimilar entrants lacking compliance systems. |
| Phosphate Binder API Backward Integration | Captive lanthanum carbonate synthesis insulates margin from Indian generic sevelamer price compression. |
| Telehealth Anemia Management Platform | Remote hemoglobin monitoring opens channel access outside traditional dialysis center footprints. |
| Peritoneal Dialysis Combination Labeling | EMA MDR clinical evidence thresholds reward established trial infrastructure for integrated delivery systems. |
| Medicare Advantage Formulary Exclusivity | Exclusive disease progression delay protocols lock in premium pricing for SGLT2 inhibitor portfolios. |
Research Methodology
Desk research of FDA REMS documentation, CMS Medicare reimbursement filings, and EMA MDR guidance preceded structured interviews with nephrology practice administrators, dialysis center pharmacy directors, and payer formulary managers. Secondary validation drew from ClinicalTrials.gov records, hospital procurement databases, and GPO contract disclosures. Bottom-up patient population modeling triangulated against top-down pharmaceutical manufacturer revenue attribution across the analysis window.
Variance decomposition across product type, application context, delivery mode, and regional regulatory cluster shaped the analytical framework. Modeled segmentation captured erythropoiesis-stimulating agent half-life tier, phosphate binder backbone chemistry, and site-of-care economics. CAGRs derived from patient population growth trajectories and reimbursement rate evolution throughout the forecast period. Forecast inputs incorporated diabetes-related nephropathy prevalence curves and nephrologist workforce pipeline constraints.
Decision-makers should treat outputs as directional under assumptions of stable CMS reimbursement differentials and continued FDA REMS enforcement; material deviation would warrant model refresh. Specific risk factors include geopolitical friction affecting API supply from India and China, plus nephrologist workforce shortages limiting prescriber capacity expansion. Revision becomes warranted when Medicare Advantage penetration of home-based peritoneal dialysis crosses thresholds that restructure site-of-care economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Blood Dialyzer Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Nephrotic Syndrome Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Dialysis Service Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Kidney Transplant Medicine Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Plasmapheresis Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Radiation Nephropathy Treatment and Management Market