
 Global Exocrine Pancreatic Insufficiency (EPI) Market | 2026-2036
Global Exocrine Pancreatic Insufficiency (EPI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exocrine Pancreatic Insufficiency (EPI) Market Foresight
Patient adherence monitoring and dose-optimization software is realigning how enzyme replacement therapies get prescribed and reimbursed. AbbVie leverages its gastroenterology specialty infrastructure to sustain high prescriber engagement for its established pancreatic enzyme portfolio. Nestlé Health Science competes through nutritional support integration, bundling medical foods with enzyme therapy protocols in metabolic clinics.
Exocrine pancreatic insufficiency denotes the inability of the pancreas to synthesize adequate digestive enzymes—primarily lipase, protease, and amylase—resulting in maldigestion and malabsorption; formulations typically specify lipase units per capsule, with enteric-coated microspheres protecting enzymes from gastric acid degradation until duodenal release. Pancreatic enzyme supplements dominate prescription volumes due to chronic replacement requirements in cystic fibrosis and chronic pancreatitis patients. Diagnostic kits represent the fastest-expanding segment as non-invasive fecal elastase testing displaces invasive secretin-stimulated endoscopy in initial workups.
FDA bioequivalence requirements for pancreatic enzyme products under the NDA pathway shape formulation stability standards, while EMA orphan designation incentives accelerate pediatric indication expansions across European markets. The EU F-Gas Regulation indirectly pressures manufacturers to reformulate propellants in diagnostic device delivery systems. Stakeholders must monitor how decentralized diagnostic testing and home infusion protocols reshape channel economics between specialty pharmacies and traditional hospital purchasing.
Market Dynamics
Home healthcare expansion and decentralized diagnostic testing are compressing the traditional hospital-centric care model for EPI management, forcing reimbursement frameworks to adapt to remote patient monitoring and direct-to-consumer enzyme delivery channels.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate pediatric indication expansions for enzyme replacement therapies, shortening development timelines for cystic fibrosis populations.
- Fecal Elastase Testing:Non-invasive diagnostic kits displace secretin-stimulated endoscopy in initial workups, expanding addressable patient pools through primary care accessibility.
- Germany:Universal cystic fibrosis newborn screening programs sustain chronic replacement therapy demand through early diagnosis and lifetime patient capture.
Market Restraints
- Porcine-Derived Enzyme Supply:Concentration of pharmaceutical-grade pancreatin sourcing creates vulnerability to African swine fever outbreaks and agricultural commodity cycles.
- EMA Bioequivalence Pathways:Complex pediatric investigation plan requirements delay generic enzyme product approvals, maintaining incumbent pricing power.
- Recombinant Lipase Alternatives:Microbial fermentation-derived enzymes threaten to displace traditional porcine extracts if manufacturing scale achieves cost parity.
Strategic Opportunities
- Japan:Aging chronic pancreatitis demographics and diagnostic underpenetration create expansion potential for screening program investment.
- Dose-Optimization Software:AI-enabled adherence monitoring platforms integrate with specialty pharmacy dispensing to capture outcomes-based reimbursement contracts.
- EU F-Gas Regulation:Propellant reformulation mandates for diagnostic device delivery systems create first-mover advantage for compliant inhaler-integrated enzyme formulations.
Industry Challenges
- Enteric Coating Expertise:Shortage of pharmaceutical engineers skilled in acid-resistant microsphere formulation limits manufacturing capacity expansion.
- Cold Chain Integrity:Temperature-sensitive enzyme stability requirements complicate direct-to-patient shipping logistics and last-mile delivery economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exocrine Pancreatic Insufficiency (EPI) Market |
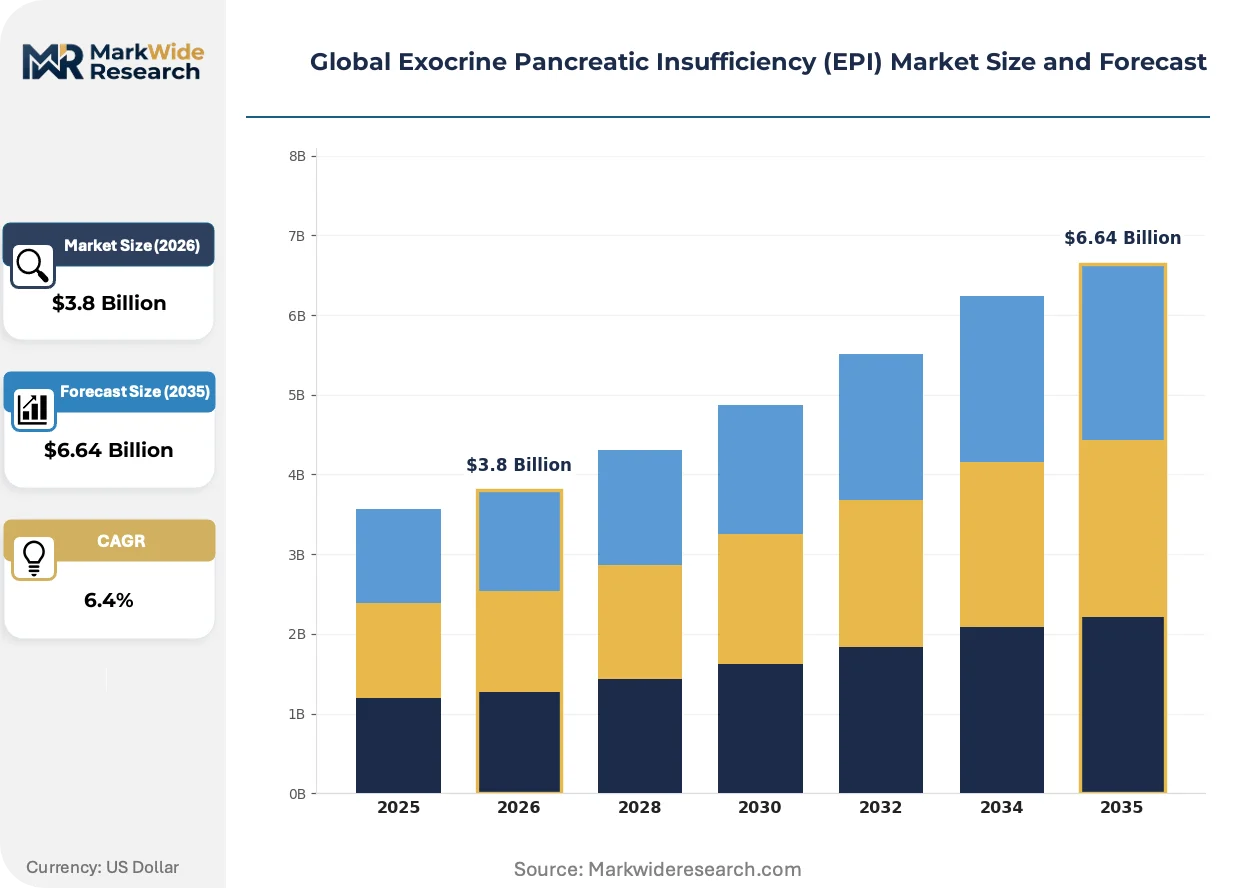
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pancreatic Enzyme Supplements, Acid Suppressants, Nutritional Support, Diagnostic Kits Therapy Area: Cystic Fibrosis, Chronic Pancreatitis, Pancreatic Cancer, Post-Gastrointestinal Surgery End User: Specialty Clinics, Diagnostic Laboratories, Home Healthcare Services, Rehabilitation Centers Delivery Mode: Oral Capsules, Tablets, Powders, Enteric-Coated Microspheres |
| Companies Covered | AbbVie, Viatris, Nestlé Health Science, Digestive Care, Chiesi Farmaceutici, Nordmark Arzneimittel, First Wave BioPharma, Abbott Laboratories, Vivus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exocrine Pancreatic Insufficiency (EPI) Market Shifts & Advancements
Digital health integration and formulation science advances are converging to transform how pancreatic enzyme therapies are dosed, monitored, and reimbursed across outpatient settings.
Microsphere enteric coating technology is consolidating manufacturing standards across the enzyme replacement category. Specialty pharmaceutical contractors in Germany and the United States are adopting pH-dependent release systems at accelerating rates. This consolidation is compressing differentiation among originator and generic products, shifting competitive focus toward adherence services.
REACH chemical safety protocols in Europe are tightening excipient purity requirements for pharmaceutical coatings. Manufacturers must reformulate phthalate-based enteric polymers ahead of sunset dates. Pediatric formulations face the steepest compliance costs, driving regional production consolidation toward integrated chemical-pharmaceutical facilities.
Specialty pharmacy dispensing now dominates maintenance therapy fulfillment for cystic fibrosis patients. Hospital outpatient departments cede volume to home infusion services that bundle enzyme delivery with nutritional counseling. This channel migration is most advanced in United States metropolitan markets where integrated care networks control formulary placement.
Global Exocrine Pancreatic Insufficiency (EPI) Market Segmentation
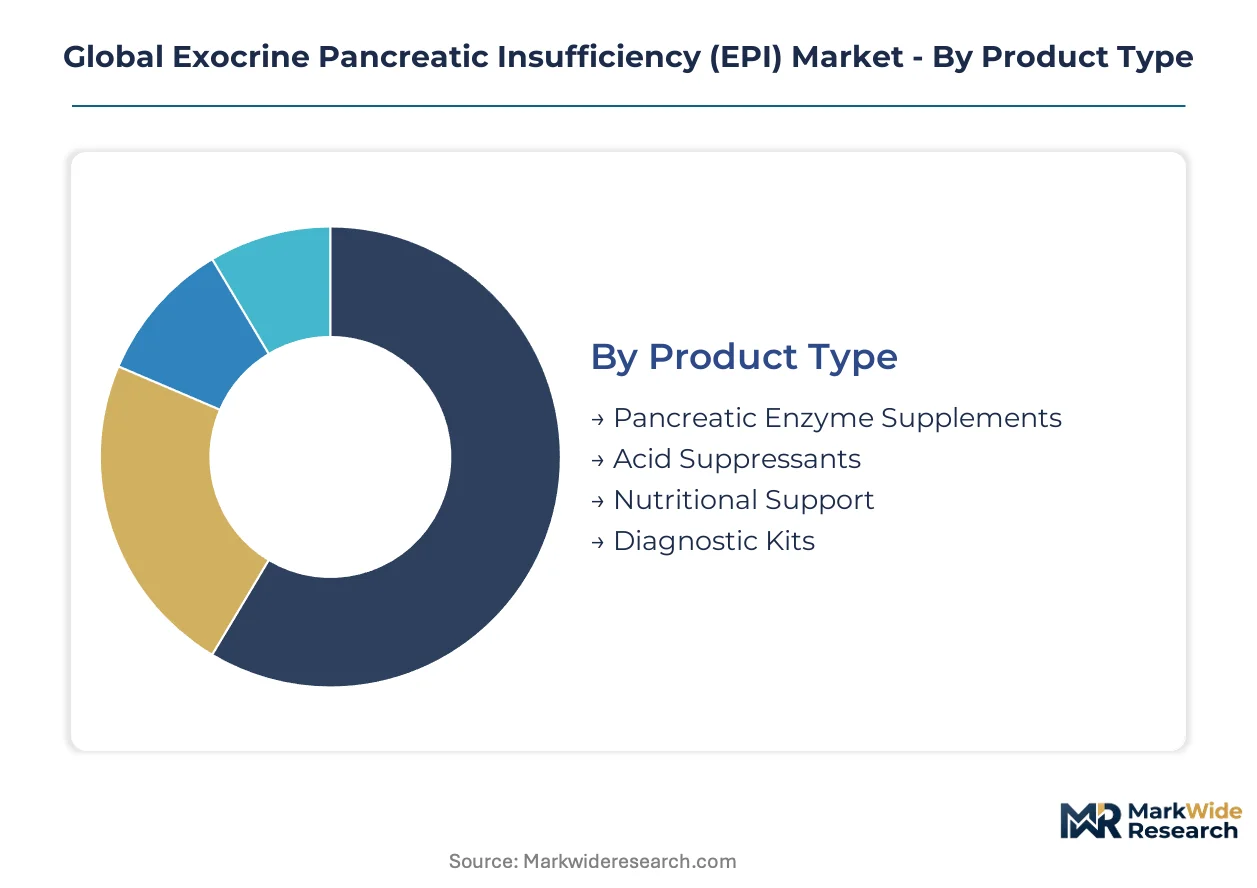
Product differentiation in the EPI market hinges on formulation stability, delivery precision, and diagnostic accessibility. Supply-side capabilities in enteric coating technology and cold chain logistics determine competitive positioning across each segment tier.
Product Type:
Manufacturing capacity concentrates among contractors with pharmaceutical-grade pancreatin extraction and acid-resistant microsphere expertise.
- Pancreatic Enzyme Supplements:Porcine-derived lipase-protease-amylase combinations dominate prescription volumes, with enteric-coated formulations protecting enzymatic activity through gastric transit. Demand concentrates in cystic fibrosis treatment centers across the United States and Germany, where lifetime replacement therapy requirements sustain chronic dispensing volumes. FDA bioequivalence standards under the NDA pathway enforce formulation stability benchmarks that limit supplier entry.
- Diagnostic Kits:Fecal elastase immunoassays displace invasive secretin-stimulated endoscopy in initial workups, expanding primary care accessibility. Germany and Japan show the steepest adoption curves as screening programs penetrate outpatient settings; EMA IVDR compliance costs favor established IVD manufacturers with integrated European distribution.
- Acid Suppressants:Proton pump inhibitors and H2 antagonists serve as adjunctive therapy to reduce gastric acid load on supplemental enzymes.
- Nutritional Support:Medical foods and specialized enteral formulations address malabsorption sequelae in metabolic clinics.
Pancreatic enzyme supplements absorb the bulk of installed capacity; diagnostic kits are expanding most quickly.
Therapy Area:
Patient volume distribution reflects epidemiology of underlying conditions and diagnostic penetration rates in high-income markets.
- Cystic Fibrosis:Transmembrane conductance regulator mutations create permanent exocrine dysfunction requiring lifelong enzyme replacement. Universal newborn screening in the United States and Germany captures patients at birth, locking in decades of continuous therapy demand. Orphan drug incentives accelerate pediatric indication expansions.
- Chronic Pancreatitis:Alcohol-induced and idiopathic forms drive adult-onset EPI with progressive enzyme decline. Japan's aging population and rising alcohol-related pancreatitis incidence create expansion potential where diagnostic underpenetration currently limits treatment rates.
- Pancreatic Cancer:Tumor obstruction and surgical resection precipitate iatrogenic exocrine failure requiring temporary or permanent supplementation.
- Post-Gastrointestinal Surgery:Gastric bypass and pancreaticoduodenectomy procedures disrupt normal digestive enzyme delivery, creating procedure-dependent replacement needs.
Cystic fibrosis commands the deepest therapy penetration; chronic pancreatitis shows the steepest expansion trajectory as screening improves.
End User:
Channel economics shift as reimbursement frameworks adapt to decentralized care models and remote monitoring capabilities.
- Home Healthcare Services:Specialty pharmacy dispensing now dominates maintenance therapy fulfillment, bundling enzyme delivery with nutritional counseling and adherence monitoring. United States metropolitan markets lead this migration as integrated care networks control formulary placement and capture outcomes-based contracts.
- Specialty Clinics:Gastroenterology and cystic fibrosis centers manage complex dosing optimization and comorbidity coordination. Germany's dense network of university-affiliated metabolic clinics sustains high prescriber engagement for established enzyme portfolios.
- Diagnostic Laboratories:Centralized and hospital-based labs process fecal elastase testing volumes as primary care adoption accelerates.
- Rehabilitation Centers:Post-surgical and oncology recovery facilities manage short-term enzyme supplementation during nutritional rehabilitation.
Home healthcare services capture the fastest-growing share of prescription fulfillment; specialty clinics retain the highest-margin complex cases.
Delivery Mode:
Formulation technology barriers concentrate manufacturing among specialists with pH-dependent release system expertise.
- Enteric-Coated Microspheres:Acid-resistant polymers protect enzymes from gastric degradation until duodenal pH triggers release. REACH chemical safety protocols in Europe are phasing out phthalate-based coatings, forcing reformulation investments that favor integrated chemical-pharmaceutical facilities with polymer synthesis capabilities.
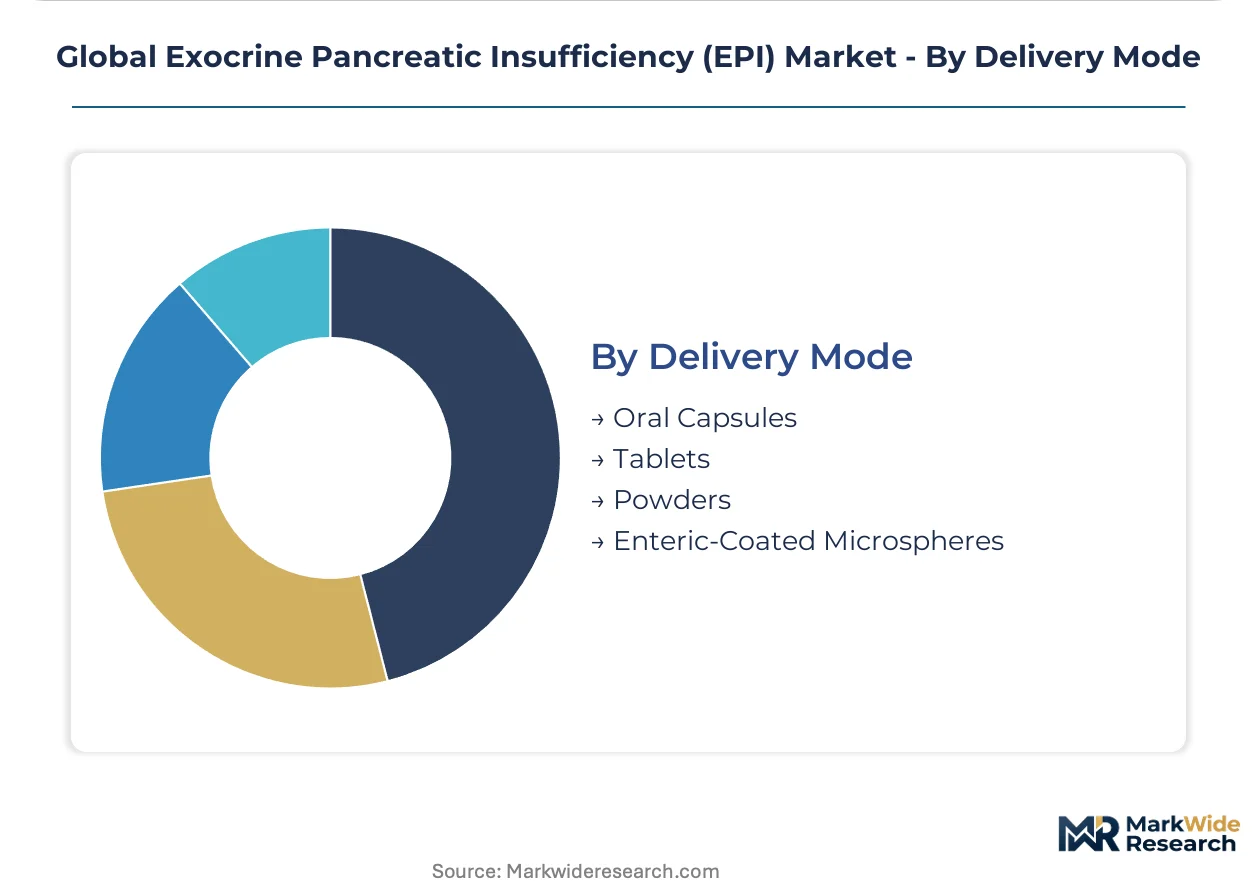
- Oral Capsules:Hard gelatin and HPMC shells contain enzyme granules or powders for adult dosing flexibility. United States and German contract manufacturers dominate capacity for high-volume capsule filling with validated dissolution profiles.
- Tablets:Compressed formulations offer dose standardization but challenge gastric acid protection without advanced coating technology.
- Powders:Bulk formulations enable pediatric and enteral tube administration with dose titration flexibility.
Enteric-coated microspheres command premium pricing through technical differentiation; oral capsules maintain the highest production volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for pancreatic enzyme products concentrates in Germany and the United States, while diagnostic kit production clusters in Japan and Switzerland. Consumption patterns diverge sharply: cystic fibrosis screening programs drive chronic therapy demand in North America and Western Europe, whereas aging pancreatitis populations in East Asia represent underpenetrated expansion terrain.
United States
Universal newborn screening for cystic fibrosis captures patients at birth, locking in decades of continuous enzyme replacement demand. FDA orphan drug incentives accelerate pediatric indication expansions, compressing development timelines for manufacturers. Specialty pharmacy dispensing dominates in metropolitan markets where integrated care networks control formulary placement and bundle adherence monitoring with drug delivery.
Germany
Dense networks of university-affiliated metabolic clinics sustain high prescriber engagement for established enzyme portfolios. EMA pediatric investigation plan requirements delay generic approvals, maintaining incumbent pricing power. REACH chemical safety protocols are phasing out phthalate-based enteric coatings, forcing reformulation investments toward integrated chemical-pharmaceutical facilities in Bavaria and North Rhine-Westphalia.
Japan
Aging demographics and rising alcohol-related chronic pancreatitis incidence create expansion potential where diagnostic underpenetration currently limits treatment rates. PMDA streamlined pathways for orphan indications attract multinational sponsors seeking faster market entry. Tokyo and Osaka medical centers pioneer fecal elastase testing adoption in outpatient gastroenterology clinics.
Switzerland
Swissmedic's alignment with EMA standards facilitates seamless cross-border supply into EU markets while maintaining distinct pediatric labeling requirements. Precision diagnostics manufacturing clusters in Basel and Zurich leverage pharmaceutical heritage to develop next-generation immunoassay platforms. Cold chain logistics infrastructure supports temperature-sensitive enzyme stability requirements for alpine distribution networks.
United Kingdom
NHS cystic fibrosis specialist centers coordinate enzyme prescribing through centralized procurement frameworks that favor high-volume contract manufacturers. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for reformulated enteric coatings compliant with evolving chemical safety standards. London and Manchester host diagnostic laboratory networks processing rising fecal elastase testing volumes from primary care referrals.
Global Exocrine Pancreatic Insufficiency (EPI) Market Competitive Landscape
Top-tier vendors anchor originator enzyme portfolios, while mid-tier generic manufacturers compete on formulation stability and contract manufacturing scale. Market structure reflects dual consolidation: a handful of multinational pharmaceutic
AbbVie, Viatris, and Nestlé Health Science occupy distinct competitive positions within this landscape. AbbVie exemplifies the gastroenterology-focused multinational with established specialty infrastructure. Viatris represents the generics-heavy consolidator leveraging manufacturing scale across multiple therapeutic categories. Nestlé Health Science anchors the nutritional-therapeutic convergence archetype, bundling medical foods with enzyme protocols in metabolic care settings. Chiesi Farmaceutici and Nordmark Arzneimittel sit within the European mid-tier, while Digestive Care and First Wave BioPharma occupy development-stage positions. Abbott Laboratories bridges diagnostic and therapeutic domains through integrated testing-to-treatment platforms.
| Leading Market Players |
|---|
| AbbVie |
| Viatris |
| Nestlé Health Science |
| Digestive Care |
| Chiesi Farmaceutici |
| Nordmark Arzneimittel |
| First Wave BioPharma |
| Abbott Laboratories |
| Vivus |
| Others |
Supply & Pricing Matrix
Backward integration into pharmaceutical-grade pancreatin extraction anchors supply positions for established enzyme manufacturers while insulating them from African swine fever commodity cycles. This captive sourcing strategy preserves formulation stability premiums against generic competitors dependent on spot-market porcine extracts.
Pricing Analysis
Margin tightening in originator enzyme tiers reflects REACH-mandated phthalate coating reformulation costs and cold chain logistics investments. Three-tier pricing structure across originator, authorized generic, and commodity pancreatin segments stratifies by bioequivalence certification tier and enteric coating sophistication. Cost-down pressure on mid-tier products accelerates because EMA pediatric investigation plans delay generic approvals. Hospital purchasing committees exhibit lowest price sensitivity for cystic fibrosis maintenance therapy; primary care diagnostic kit procurement shows highest elasticity.
Supply Chain Analysis
Direct-to-specialty-pharmacy channels handle chronic enzyme replacement fulfillment while hospital outpatient departments manage acute diagnostic workups. Manufacturing gravity centers on Germany, the United States, and Denmark for enteric-coated microsphere production; diagnostic kit assembly clusters in Japan and Switzerland. Raw material flows draw from Danish and Dutch pharmaceutical-grade pancreatin processors, German polymer coating suppliers, and Japanese immunoassay reagent manufacturers. Single-source vulnerability concentrates in porcine-derived lipase extracts given African swine fever eradication protocols. Distribution runs through integrated care networks in United States metropolitan markets and university-affiliated metabolic clinics in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as FDA bioequivalence standards and EMA pediatric investigation requirements raise capital barriers, forcing subscale generic manufacturers toward contract manufacturing exits.
For Market Incumbents: Deploy adherence monitoring platform integration to capture outcomes-based reimbursement contracts before diagnostic kit manufacturers bundle software with testing hardware. Defensive moves center on acquiring specialty pharmacy dispensing networks in United States metropolitan markets and securing Bavarian chemical-pharmaceutical facilities for REACH-compliant coating synthesis. The recombinant lipase threat from microbial fermentation specialists demands accelerated pediatric formulation patent estate reinforcement. For New Entrants and Emerging Players: Begin with fecal elastase diagnostic kit distribution partnerships in Japanese outpatient gastroenterology clinics where PMDA orphan pathways accelerate market entry. White-space targets include aging chronic pancreatitis populations in Osaka and Nagoya medical centers, plus home healthcare enzyme delivery bundling in United States integrated care networks. Go-to-market positioning emphasizes AI-enabled dose-optimization software integration with existing specialty pharmacy infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty pharmaceutical platform acquisitions by diversified nutrition-therapeutic conglomerates seeking metabolic clinic channel control. Long-term viability favors contractors with integrated enteric coating polymer synthesis and validated cold chain logistics across alpine distribution networks. The inflection signal to monitor is PMDA approval velocity for recombinant lipase alternatives achieving manufacturing scale parity with porcine extracts.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | Phthalate-free enteric polymer investments secure EMA market access ahead of sunset deadlines. |
| Specialty Pharmacy Network Acquisition | Integrated care network formulary control captures cystic fibrosis maintenance therapy volumes. |
| Fecal Elastase Diagnostic Expansion | Primary care testing adoption in Japan and Germany displaces invasive endoscopy workups. |
| Recombinant Lipase Scale-Up | Microbial fermentation manufacturing threatens porcine extract cost structures. |
| Adherence Software Platform Integration | AI-enabled dosing optimization captures outcomes-based reimbursement contracts. |
Research Methodology
Independent corroboration across gastroenterology prescribing data, FDA bioequivalence filing records, and EMA pediatric investigation plan documentation underwrites the qualitative findings. Primary interviews engaged drug development executives at enzyme replacement therapy manufacturers, regulatory affairs leads navigating REACH coating compliance, formulary directors at United States integrated care networks, and procurement managers at German university-affiliated metabolic clinics. Secondary validation drew from FDA Orange Book listings, EMA EPAR assessments, ClinicalTrials.gov pediatric indication expansions, and hospital procurement database pricing benchmarks. Bottom-up patient volume modeling and top-down pharmaceutical spending allocation triangulate segment sizing.
Rate-of-change decomposition across the projection horizon segments volume and value by product type, therapy area, end user channel, and delivery mode formulation technology. Cystic fibrosis newborn screening penetration rates, chronic pancreatitis diagnostic yield improvements, and specialty pharmacy dispensing migration patterns inform patient capture assumptions. CAGRs derive from epidemiological trend extrapolation, reimbursement framework evolution, and channel economics shift modeling.
Underlying measurement precision varies by segment; pancreatic enzyme supplement volume estimates carry tighter precision than emerging recombinant lipase development-stage forecasts. Projections reflect assumptions regarding regulatory approval timelines, porcine supply stability, and diagnostic testing adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Pharmaceuticals Preservative Market