
 Listeria Monocytogenes Treatment Market | 2026-2036
Listeria Monocytogenes Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Listeria Monocytogenes Treatment Market Foresight
Project finance for late-stage infectious disease assets is fragmenting competitive dynamics in Listeria therapeutics. Pfizer Inc. leverages its established hospital anti-infective franchise to secure formulary placement across acute care networks. Cipla Ltd. anchors emerging market access through differential oral solid manufacturing economics. F. Hoffmann-La Roche AG sustains diagnostic-therapeutic bundling capabilities that reinforce institutional purchasing loyalty.
Listeria monocytogenes treatment encompasses antimicrobial and adjunctive therapeutic interventions targeting facultative intracellular gram-positive bacterial infection, with ampicillin-gentamicin combination therapy representing the standard-of-care pharmacological specification for invasive listeriosis management. The primary commercial purpose centers on reducing mortality in immunocompromised, pregnant, and elderly patient populations where bloodstream and central nervous system invasion drive clinical urgency. Antibiotics dominate current revenue pools given established hospital protocols, while intravenous delivery mode commands premium positioning due to severity-appropriate administration requirements in critical care settings. Vaccines represent the fastest-growing structural category as maternal immunization and high-risk population prophylaxis programs advance through clinical validation.
FDA pharmacovigilance requirements and EMA infectious disease therapeutic guidelines shape product development priorities and market access pathways for Listeria treatment developers. The EU Green Deal's antimicrobial resistance containment framework and WHO essential medicines list revisions further constrain formulary composition and manufacturing sustainability standards. Stakeholders must monitor regulatory convergence on intracellular pathogen drug development incentives to anticipate portfolio prioritization shifts among active developers.
Market Dynamics
Hospital formulary consolidation under FDA and EMA pharmacovigilance mandates is compressing vendor access and forcing therapeutic developers to demonstrate mortality outcome differentials against ampicillin-gentamicin standards. This structural pressure favors developers with integrated diagnostic capabilities and established acute care networks.
Growth Catalysts
- Maternal Immunization Programs:Clinical validation of prophylactic vaccines for high-risk pregnancy populations is expanding addressable patient pools beyond acute infection management. Regulatory pathways for maternal indications are clarifying under EMA infectious disease guidelines.
- EMA Post-Market Surveillance Mandates:Intensified foodborne illness tracking is accelerating outbreak response protocols and driving institutional procurement of rapid diagnostic-therapeutic bundles. Reference laboratories in Germany and France are upgrading therapeutic protocol automation.
- Intravenous Delivery Infrastructure:Critical care network expansion in Japan and the United States is reinforcing premium positioning for hospital-administered antibiotic therapies. Severe listeriosis cases require continuous infusion monitoring that oral formulations cannot satisfy.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Gentamicin and ampicillin raw material supply concentrates in Chinese and Indian bulk manufacturing clusters, exposing formulators to geopolitical trade friction and quality enforcement variability.
- EU Green Deal Manufacturing Standards:Antimicrobial production sustainability mandates are raising compliance costs for solvent-intensive synthesis processes. ECHA framework revisions threaten capacity utilization at legacy European facilities.
- Generic Substitution Pressure:Patent-expired first-line antibiotics face aggressive tender-based procurement in emerging markets, compressing margin structures for branded intravenous formulations.
Strategic Opportunities
- Oral Bioavailability Innovation:Lipid nanoparticle encapsulation technologies enabling gastrointestinal absorption of macrolide alternatives are migrating from oncology to infectious disease applications. Japan's PMDA has granted exploratory IND facilitation for intracellular pathogen programs.
- Diagnostic-Therapeutic Bundling:Syndromic panel adoption in US hospital networks creates entry points for developers with rapid Listeria species identification. FDA-cleared molecular assays can anchor formulary placement for companion therapeutic protocols.
- Antimicrobial Stewardship Incentives:US hospital reimbursement adjustments under CMS quality metrics reward narrow-spectrum pathogen-specific therapy selection. Developers demonstrating spectrum specificity against standard broad-spectrum empiric regimens capture premium positioning.
Industry Challenges
- Intracellular Pharmacokinetic Modeling:Predicting cerebrospinal fluid penetration and macrophage uptake requires specialized preclinical capabilities scarce among mid-scale infectious disease developers. Regulatory agencies demand standardized tissue distribution data that extends development timelines.
- Reference Laboratory Fragmentation:Decentralized outbreak response coordination across US state health departments complicates post-market surveillance data collection. Therapeutic protocol updates propagate unevenly, creating regional variation in standard-of-care adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Listeria Monocytogenes Treatment Market |
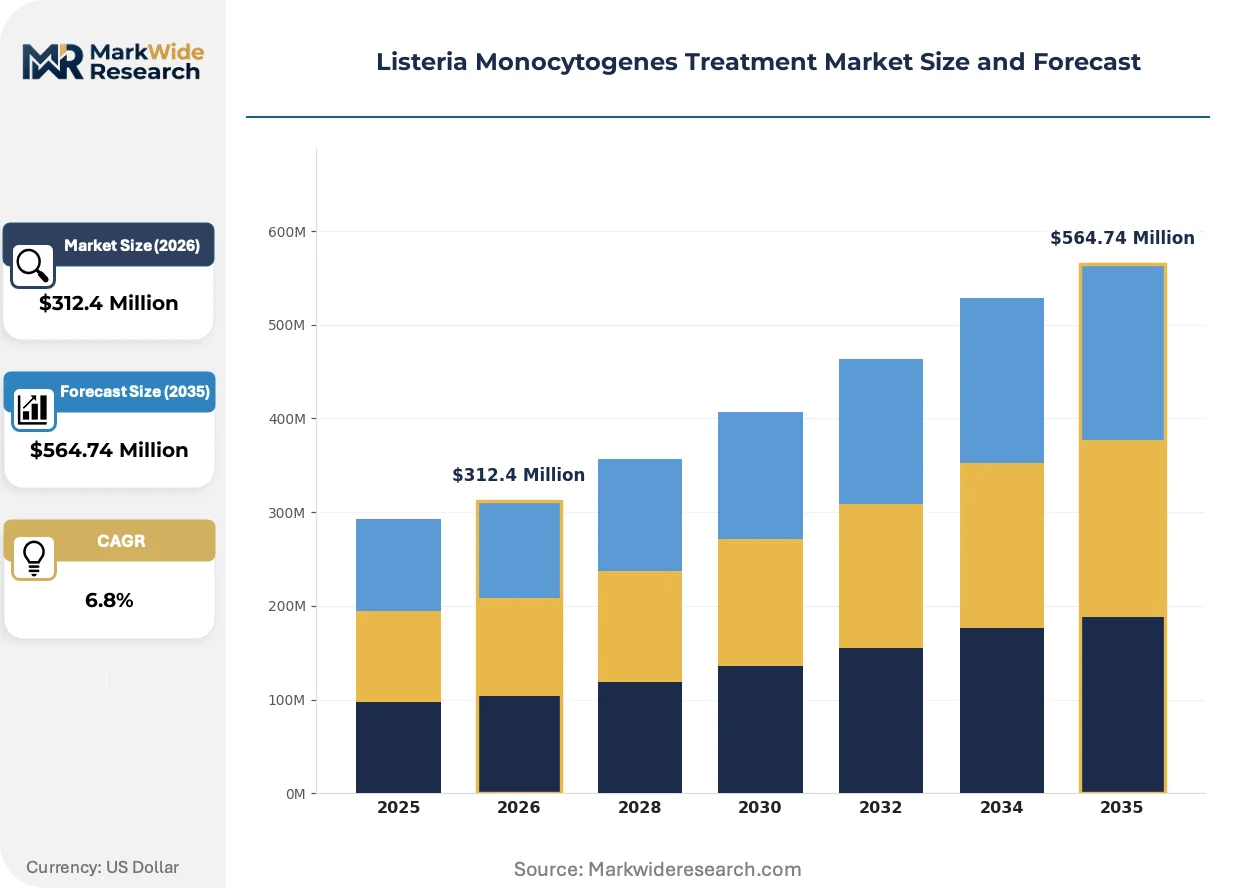
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Antiseptics, Probiotics Therapy Area: Infectious Diseases, Gastroenterology, Neurology, Critical Care Delivery Mode: Oral, Intravenous, Intra-muscular, Topical End User: Hospitals, Clinics, Healthcare Organizations, Research Institutions |
| Companies Covered | AstraZeneca PLC, AbbVie Inc., Pfizer Inc., GlaxoSmithKline PLC, Teva Pharmaceutical Industries Ltd., Novartis AG, Sanofi S.A., Cipla Ltd., F. Hoffmann-La Roche AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Listeria Monocytogenes Treatment Market Shifts & Advancements
Pharmaceutical developers are engineering next-generation intracellular penetration mechanisms while regulatory agencies tighten manufacturing sustainability requirements. Three developments are restructuring competitive positioning in Listeria therapeutics.
Macrolide-liposome conjugation technology is migrating from experimental tuberculosis programs into gram-positive intracellular pathogen applications. Academic medical centers in Boston and Heidelberg are piloting compassionate-use protocols for refractory neuro-listeriosis cases. This delivery platform is compressing the effective dose requirements for blood-brain barrier penetration compared to conventional aminoglycoside regimens.
REACH antimicrobial manufacturing amendments are forcing API producers to substitute green solvents in gentamicin fermentation and purification stages. ECHA authorization timelines for novel process chemistry are extending by eight to fourteen months for facilities supplying European hospital networks. Formulators with captive fermentation capacity in Germany and Switzerland are absorbing compliance costs faster than contract manufacturers dependent on Asian bulk supply.
Hospital procurement committees are unbundling diagnostic and therapeutic vendor relationships that previously favored single-source bundled contracts. US acute care networks now separate molecular assay selection from antibiotic formulary decisions, enabling standalone therapeutic developers to compete against integrated diagnostics giants. This pattern is most visible in tertiary referral centers with dedicated infectious disease stewardship programs.
Listeria Monocytogenes Treatment Market Segmentation
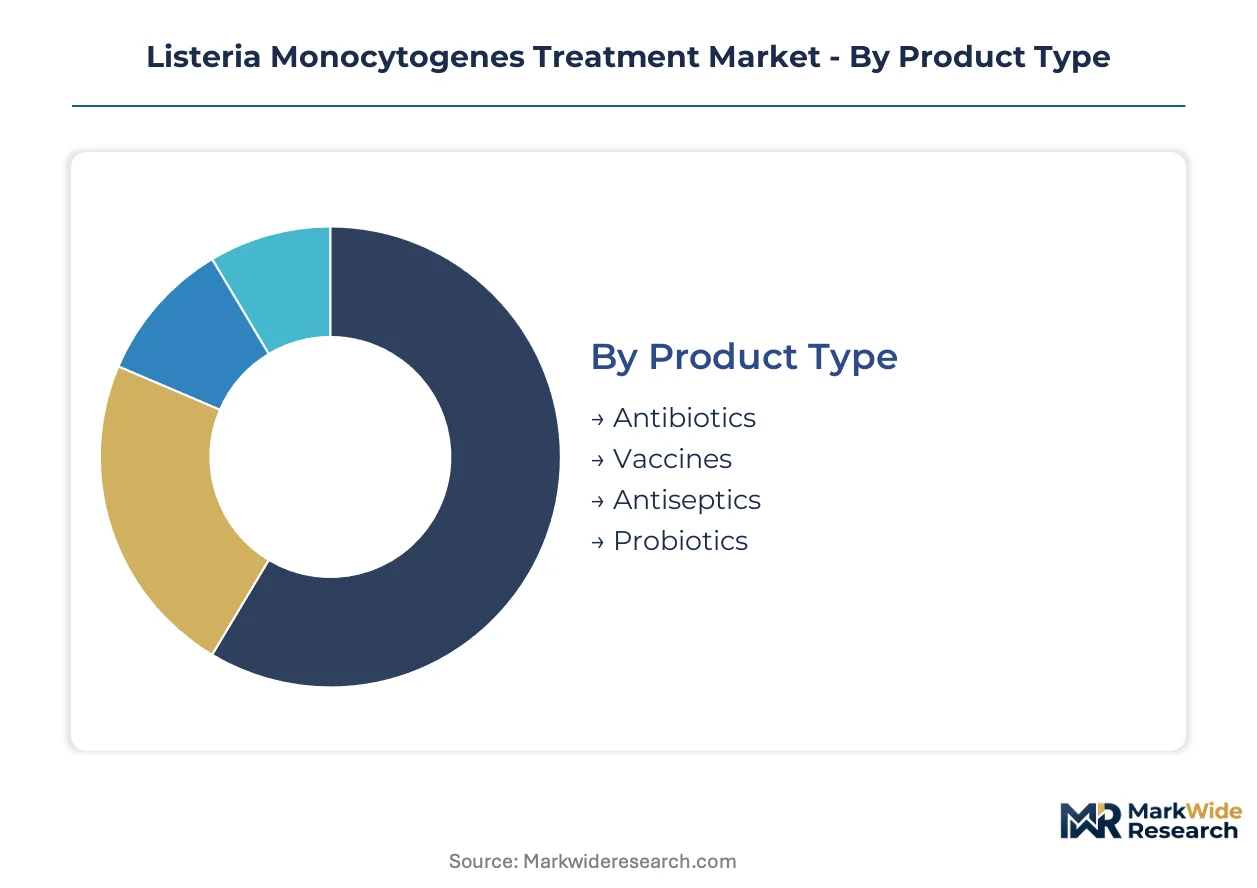
Treatment modality selection in listeriosis management hinges on infection severity, patient immunocompetence, and institutional protocol standardization. Segmentation reveals how pharmaceutical developers align R&D investments with distinct clinical workflows and reimbursement pathways across acute care networks.
Product Type:
After-sales service intensity varies sharply across product categories, with intravenous antibiotics demanding continuous infusion monitoring and vaccine programs requiring cold chain maintenance and immunization record systems.
- Antibiotics:Ampicillin-gentamicin combination therapy constitutes the pharmacological backbone for invasive listeriosis, with hospital pharmacies in the United States and Germany maintaining 72-hour stockpiles for sepsis protocol activation. Demand concentrates in tertiary referral centers managing bloodstream and central nervous system infections, where mortality outcome differentials against standard-of-care drive formulary retention.
- Vaccines:Prophylactic maternal immunization candidates target high-risk pregnancy populations, with clinical validation programs advancing under EMA infectious disease guidelines. Japanese and French reference laboratories coordinate cohort studies examining transplacental antibody transfer efficiency, positioning this category for pipeline expansion as regulatory pathways clarify.
- Antiseptics:Surface decontamination formulations for food processing environments complement therapeutic interventions.
- Probiotics:Competitive exclusion cultures for agricultural applications remain investigational for human listeriosis prevention.
By volume, Antibiotics leads. By growth pace, Vaccines is ahead.
Therapy Area:
Cost tier stratification separates acute intervention from chronic management, with critical care commanding premium pricing and infectious disease stewardship programs narrowing spectrum selection.
- Infectious Diseases:Hospital-based antimicrobial stewardship teams direct empiric therapy initiation and pathogen-directed de-escalation, with CMS quality metrics in the United States rewarding narrow-spectrum selection. Academic medical centers in Boston and Heidelberg pilot rapid diagnostic integration to compress time-to-appropriate therapy.
- Critical Care:Continuous renal replacement therapy and vasopressor support accompany severe listeriosis management in intensive care units, with intravenous delivery infrastructure in Japan and Germany reinforcing premium therapeutic positioning. Outcome data from these settings inform regulatory submissions for novel intracellular penetration mechanisms.
- Gastroenterology:Mild febrile gastroenteritis cases in immunocompetent adults rarely require antimicrobial intervention.
- Neurology:Meningoencephalitis presentations drive cerebrospinal fluid penetration studies for macrolide-liposome conjugates.
Critical Care captures highest per-patient revenue. Infectious Diseases shows broadest institutional penetration.
Delivery Mode:
Patient acuity determines administration route, with severity-appropriate requirements creating impermeable boundaries between hospital and ambulatory settings.
- Intravenous:Continuous infusion monitoring for aminoglycoside therapy in bacteremia and meningitis cases requires dedicated nursing infrastructure unavailable outside acute care networks. Japanese hospital expansion and US critical care network consolidation reinforce this mode's premium positioning.
- Oral:Step-down therapy following clinical stabilization permits discharge planning, though bioavailability limitations constrain macrolide alternatives. Lipid nanoparticle encapsulation technologies under PMDA exploratory IND facilitation may reshape gastrointestinal absorption profiles.
- Intra-muscular:Limited applicability for listeriosis given need for sustained therapeutic levels in severe infection.
- Topical:Irrelevant for systemic listeriosis management; confined to wound contamination scenarios.
Intravenous dominates hospital procurement value. Oral formulations face generic substitution pressure in step-down settings.
End User:
Procurement authority concentration varies by setting, with integrated delivery networks in the United States consolidating vendor selection while European reference laboratories coordinate multi-site therapeutic protocols.
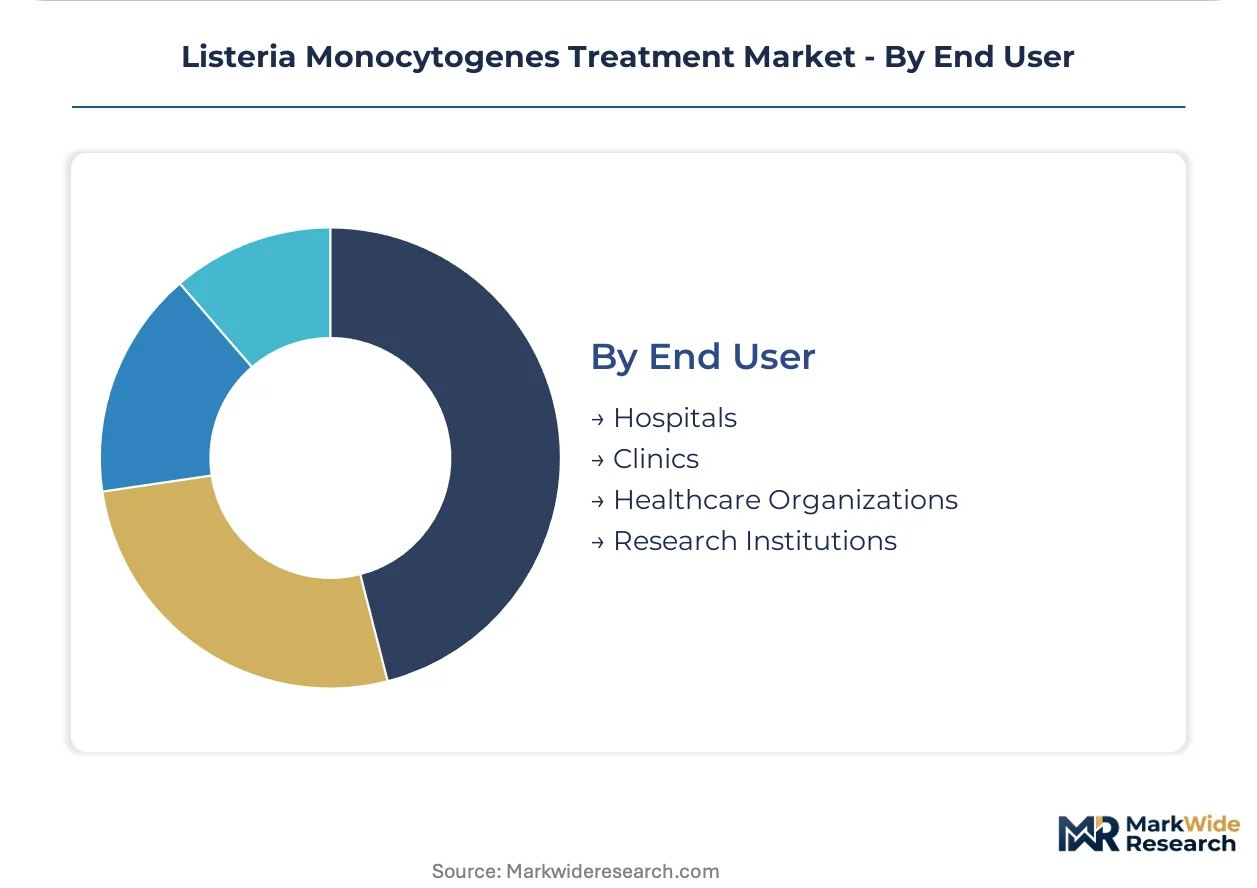
- Hospitals:Formulary committees in US acute care networks unbundle diagnostic and therapeutic vendor relationships, enabling standalone antibiotic developers to compete against integrated diagnostics giants. EMA post-market surveillance mandates in Germany and France accelerate outbreak response protocol automation and therapeutic bundle procurement.
- Healthcare Organizations:Accountable care organizations and managed care entities in the United States negotiate population-level contracts, with antimicrobial stewardship incentives embedded in quality metric frameworks. These structures reward developers demonstrating spectrum specificity against empiric broad-spectrum regimens.
- Clinics:Outpatient settings manage rare mild cases; limited therapeutic decision authority.
- Research Institutions:Academic medical centers pilot compassionate-use protocols for refractory neuro-listeriosis and intracellular pharmacokinetic modeling studies.
Hospitals command procurement volume concentration. Healthcare Organizations are gaining contracting leverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pharmacovigilance mandates and EMA infectious disease surveillance frameworks are redirecting procurement budgets toward rapid diagnostic-therapeutic bundles. Hospital networks in high-income markets consolidate formulary decisions under antimicrobial stewardship programs.
United States
CMS quality metrics reward narrow-spectrum pathogen-specific therapy selection in acute care networks. FDA post-market surveillance requirements accelerate outbreak response protocol automation across state health departments. Academic medical centers in Boston pilot compassionate-use protocols for refractory neuro-listeriosis cases.
Germany
EMA infectious disease guidelines clarify regulatory pathways for maternal immunization candidates. The EU Green Deal's antimicrobial resistance containment framework raises compliance costs for solvent-intensive synthesis processes. Reference laboratories in Heidelberg coordinate multi-site therapeutic protocol updates and cohort studies.
Japan
Critical care network expansion reinforces premium positioning for hospital-administered antibiotic therapies. PMDA exploratory IND facilitation supports intracellular pathogen programs utilizing lipid nanoparticle encapsulation. The Kanto region concentrates pharmaceutical manufacturing capacity serving domestic hospital procurement.
France
ANSM coordinates with EMA on post-market surveillance mandates intensifying foodborne illness tracking. Hospital procurement committees unbundle diagnostic and therapeutic vendor relationships in tertiary referral centers. The Paris region anchors infectious disease reference laboratory infrastructure for outbreak response coordination.
India
CDSCO regulatory pathways for generic intravenous antibiotics support emerging market access strategies. Differential oral solid manufacturing economics attract formulators seeking cost-competitive production. Bulk API manufacturing clusters in Gujarat and Maharashtra supply gentamicin and ampicillin raw materials to global formulators.
Listeria Monocytogenes Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around developers with integrated diagnostic capabilities and established acute care network relationships. Hospital formulary committees increasingly unbundle vendor selection, enabling standalone therapeutic developers to compete against integrated diagnostics giants. Three archetypes dominate: multinational anti-infective franchises, emerging market cost-optimized formulators, and diagnostic-therapeutic bundling specialists. Competitive moves center on M&A for diagnostic assets and capacity expansion in regulatory-compliant manufacturing jurisdictions.
Among multinational pharmaceutical developers, Pfizer Inc. and AstraZeneca PLC occupy positions within the hospital anti-infective franchise tier, exemplifying established acute care network access. Cipla Ltd. represents the emerging market cost-optimized formulator archetype, anchoring differential manufacturing economics for oral solid production. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors in institutional procurement markets.
| Leading Market Players |
|---|
| AstraZeneca PLC |
| AbbVie Inc. |
| Pfizer Inc. |
| GlaxoSmithKline PLC |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Sanofi S.A. |
| Cipla Ltd. |
| F. Hoffmann-La Roche AG |
| Others |
Supply & Pricing Matrix
Shanghai-Rotterdam container freight corridors transmit cost volatility from Chinese API manufacturing clusters into European hospital procurement budgets, compressing margin structures for gentamicin-ampicillin formulators while amplifying price spreads between regulatory-grade and commodity-tier supply. This logistics-cost transmission mechanism concentrates pricing power among developers with captive fermentation capacity in Switzerland and Germany.
Pricing Analysis
Certification level (FDA-grade versus CE-marked versus non-certified bulk) creates the primary spread in intravenous antibiotic procurement, with US hospital networks paying substantial premiums for FDA-validated manufacturing documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by pharmacovigilance compliance depth and cold-chain assurance. Cost compression in the economy tier is intensifying because Indian and Chinese bulk suppliers face ECHA solvent-substitution mandates. Emerging market tender-based procurement shows highest price sensitivity; Japanese critical care networks demonstrate lowest sensitivity due to severity-appropriate administration requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for aminoglycoside API sourcing, forcing formulators to qualify secondary supply from Indian bulk manufacturers. Active pharmaceutical ingredient production concentrates in China, India, and Switzerland, with gentamicin fermentation and ampicillin synthesis drawing from fermentation-derived starting materials. Single-source vulnerability persists for liposome-encapsulation excipients used in experimental neuro-listeriosis programs. Distribution runs through hospital procurement committees in integrated US delivery networks and reference laboratory-coordinated tenders in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Listeria therapeutics sector is recovering from a cyclical trough in infectious disease R&D investment, with hospital formulary consolidation under FDA and EMA pharmacovigilance mandates creating replacement demand for mortality-differentiated products.
For Market Incumbents: Harden formulary retention through diagnostic-therapeutic bundling capabilities that withstand unbundling pressures in US acute care networks. Invest in backward integration into liposome-encapsulation manufacturing to secure supply of cerebrospinal fluid-penetrating delivery platforms. Prioritize EMA certification for maternal immunization candidates ahead of regulatory pathway clarification.
For New Entrants and Emerging Players: Pursue white-space positioning in oral bioavailability innovation for step-down therapy settings, where lipid nanoparticle encapsulation technologies face limited incumbent competition. Target Japanese PMDA exploratory IND facilitation for intracellular pathogen programs as the most penetrable regulatory entry point. Anchor go-to-market strategy through academic medical center compassionate-use protocols for refractory neuro-listeriosis.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents divesting legacy anti-infective franchises under portfolio prioritization shifts toward oncology and immunology. Long-term viability in this market hinges on intracellular pharmacokinetic modeling capabilities and reference laboratory relationships. Watch for inflection signals in maternal immunization regulatory pathway clarity from EMA infectious disease guideline revisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Maternal immunization cohort studies in French and Japanese reference laboratories validate transplacental antibody transfer. |
| Regulatory Approval Pathway | EMA infectious disease guidelines clarify prophylactic vaccine indications ahead of standard-of-care expansion. |
| Manufacturing Scale-Up | Green solvent substitution in gentamicin fermentation responds to EU Green Deal antimicrobial production mandates. |
| Pipeline Diversification | Macrolide-liposome conjugation technology migrates from tuberculosis programs into gram-positive intracellular applications. |
| Hospital System Partnership | Integrated US delivery networks unbundle vendor selection, enabling standalone therapeutic developers to secure formulary placement. |
Research Methodology
Desk research of FDA pharmacovigilance filings, EMA regulatory submissions, and hospital formulary databases preceded structured interviews with infectious disease stewardship directors, hospital procurement managers, regulatory affairs leads, and reference laboratory coordinators. Secondary validation drew from ClinicalTrials.gov entries, CMS quality metric disclosures, and EU Green Deal implementation documents. Bottom-up therapeutic protocol adoption modeling and top-down hospital procurement expenditure analysis were triangulated to constrain forecast variance.
Assumptions held fixed across the projection horizon include EMA and FDA pharmacovigilance mandate intensity, EU Green Deal solvent-substitution timelines, and Japanese critical care network expansion rates. Variables included maternal immunization regulatory pathway clarity, liposome-encapsulation manufacturing cost curves, and reference laboratory coordination centralization. Segmentation dimensions encompassed treatment modality, delivery mode, therapy area, and regional regulatory cluster. CAGRs were derived from therapeutic protocol update velocity and outbreak response automation investment patterns.
Sensitivities concentrate around ECHA authorization timeline extensions for novel process chemistry, geopolitical trade friction affecting Chinese API supply, and maternal immunization clinical validation outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Latin America Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Pharma PLM Market