
 Vacuum Blood Collection Tube Market | 2026-2036
Vacuum Blood Collection Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Blood Collection Tube Market Intelligence
The integration of high-throughput automated analyzers in diagnostic laboratories is reshaping vacuum blood collection tube specifications for compatibility and precision. Becton, Dickinson and Company leverages its extensive patent portfolio and global distribution network to maintain a dominant market position. Greiner Bio-One GmbH differentiates through its focus on specialized tubes for sensitive assays and pre-analytical systems. SARSTEDT AG & Co. KG competes on manufacturing excellence and integrated phlebotomy solutions for hospitals.
A vacuum blood collection tube is a sterile glass or plastic test tube with a pre-set vacuum designed for drawing a predetermined volume of blood. Its interior is treated with additives like clot activators or anticoagulants, such as EDTA or heparin, to stabilize the sample for specific analytical procedures. Plastic tubes have largely displaced glass tubes due to superior safety and durability, now commanding the majority of market volume. Diagnostic labs and pathology centers represent the largest end-user segments, driven by high-volume routine testing requirements.
Product quality and market access are governed by stringent medical device regulations, including FDA 510(k) clearance in the United States and CE marking under the MDR in Europe. Furthermore, ISO 6710 standards dictate the requirements for single-use containers for venous blood specimen collection, ensuring global interoperability. Navigating the divergent regulatory requirements for novel additives and tube materials remains a critical challenge for manufacturers seeking to expand their geographic footprint.
Market Dynamics
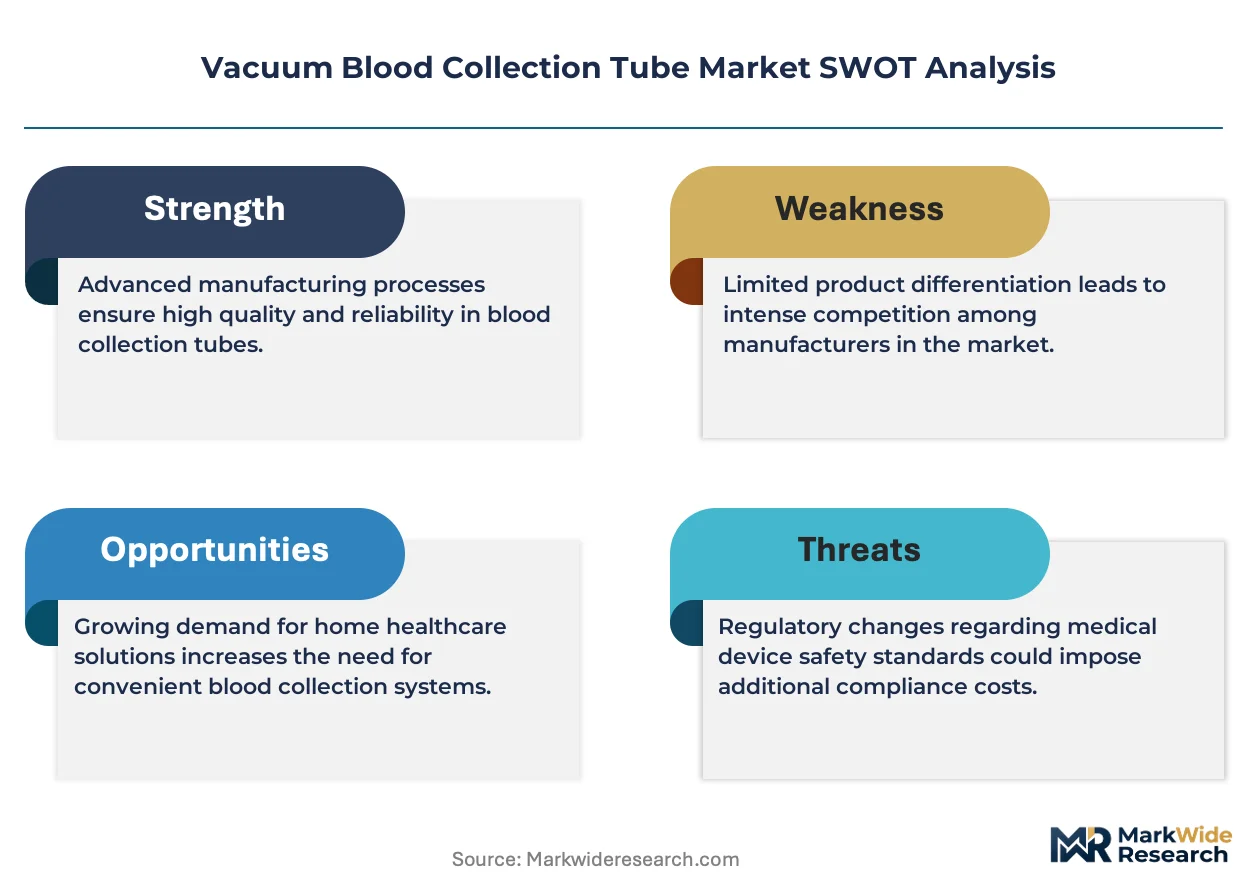
The convergence of material science and laboratory automation serves as the central force shaping the market. A decisive shift towards shatter-resistant PET plastic, driven by safety regulations, is occurring simultaneously with the deployment of high-throughput analyzers that demand precise tube specifications.
Growth Catalysts
- Public Health Initiatives:Large-scale government screening programs for chronic and infectious diseases, particularly in China, are creating immense volume demand for standardized vacuum blood collection tubes.
- Material Advancement:The transition from glass to PET plastic tubes enhances user safety by reducing breakage risk, a factor mandated by occupational safety bodies like OSHA, and improves sample integrity during transport.
- Diagnostic Volume:A rising global prevalence of conditions like diabetes and cardiovascular disease necessitates more frequent diagnostic testing, directly increasing tube consumption in hospitals and pathology centers.
Market Restraints
- Regulatory Divergence:Conflicting requirements for novel additives and materials between the US FDA and the European Union's MDR create significant hurdles and costs for manufacturers seeking simultaneous market access.
- Input Cost Volatility:The price of medical-grade PET resin and specialized anticoagulants like heparin is subject to fluctuations in petrochemical and biopharmaceutical supply chains, impacting manufacturer margins.
- Substitution by Specialized Tests:The growth of point-of-care testing and alternative sample types like saliva for certain diagnostics can reduce the need for venous blood draws in specific clinical settings.
Strategic Opportunities
- Specialized Tube Development:There is an opportunity to design tubes with proprietary additives optimized for emerging applications like liquid biopsy, cell-free DNA preservation, and proteomics, commanding premium pricing.
- Integrated Sample Management:Developing tubes with pre-applied, machine-readable 2D barcodes or integrated RFID chips can enable seamless sample tracking from patient to analyzer, reducing pre-analytical errors. *Geographic Expansion: Diagnostic infrastructure development in Southeast Asia and Latin America presents new growth markets for manufacturers able to navigate local registration requirements and distribution channels.
Industry Challenges
- Sterilization Process Management:Transitioning from glass to plastic requires manufacturers to manage and validate different sterilization methods, such as gamma or E-beam irradiation, which can affect polymer properties and additive stability.
- Automated System Compatibility:Ensuring tube dimensions, cap design, and label placement are compatible with a diverse and fragmented installed base of automated analyzers from various equipment vendors remains a constant engineering challenge.
- Compliance Documentation Burden:Obtaining and maintaining ISO 6710 compliance, FDA 510(k) clearance, and CE marking under MDR requires extensive technical documentation, clinical data, and quality management system audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Blood Collection Tube Market |
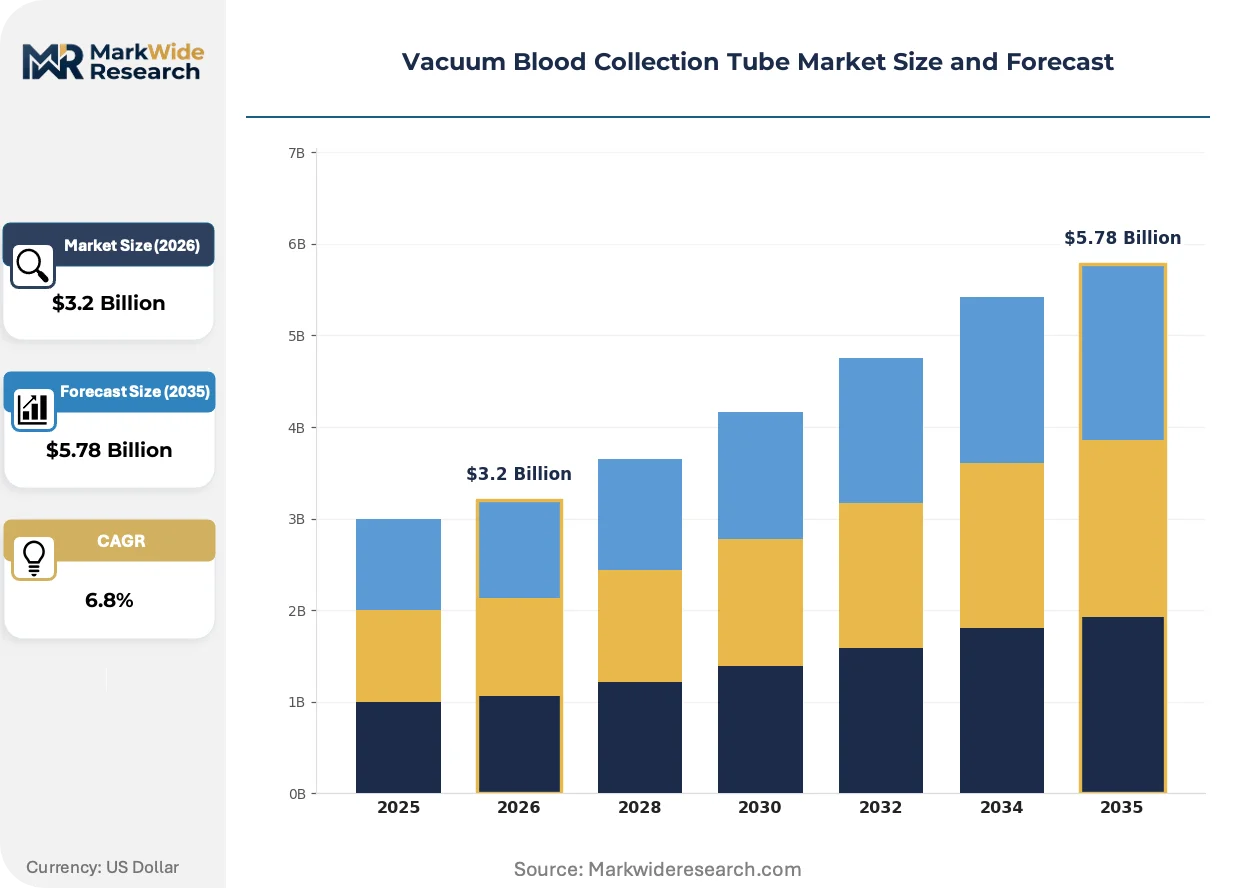
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Tubes, Glass Tubes, Mixed Material Tubes, Specialty Tubes Technology: Gel Separator, Clot Activator, EDTA, Citrate, Fluoride, Heparin Application: Diagnostic Testing, Clinical Trials, Biobanking, Blood Typing, Therapeutic Monitoring End User: Diagnostic Labs, Blood Banks, Research Institutions, Pathology Centers |
| Companies Covered | SARSTEDT AG & Co. KG, Sekisui Medical Co., Ltd., Becton, Dickinson and Company, FL Medical, Nipro Corporation, Greiner Bio-One GmbH, Cardinal Health, Improve Medical Instruments Co., Ltd., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Blood Collection Tube Market Strategic Shifts & Innovations
The market's evolution is defined by the drive for pre-analytical accuracy and workflow efficiency. Innovations are focused on enhancing sample integrity from the point of collection through to analysis, minimizing human error and integrating the physical tube into digital laboratory information systems.
Smart tubes incorporating unique digital identifiers represent a significant product evolution. Large hospital networks and high-volume diagnostic labs are adopting these products to reduce sample misidentification and automate accessioning. This technology is digitizing the phlebotomy process, creating an unbroken digital chain of custody from the patient's bedside to the final analytical result within the laboratory information system.
Global standardization under ISO 6710 provides a critical framework for market interoperability. This standard's stringent requirements for tube dimensions, vacuum retention, and additive volume ensure that products from different manufacturers can function reliably in automated laboratory environments worldwide. Compliance is especially critical for manufacturers in developing regions seeking to export to the regulated markets of North America and Europe.
A shift toward consolidated procurement for entire phlebotomy systems is altering purchasing behaviors. Instead of buying tubes as standalone commodities, large integrated delivery networks are signing contracts for bundled solutions that include tubes, needles, holders, and even collection workflow software. This trend is most prominent in the United States and Western Europe, where healthcare systems prioritize process standardization and supply chain simplification.
Vacuum Blood Collection Tube Market Segmentation
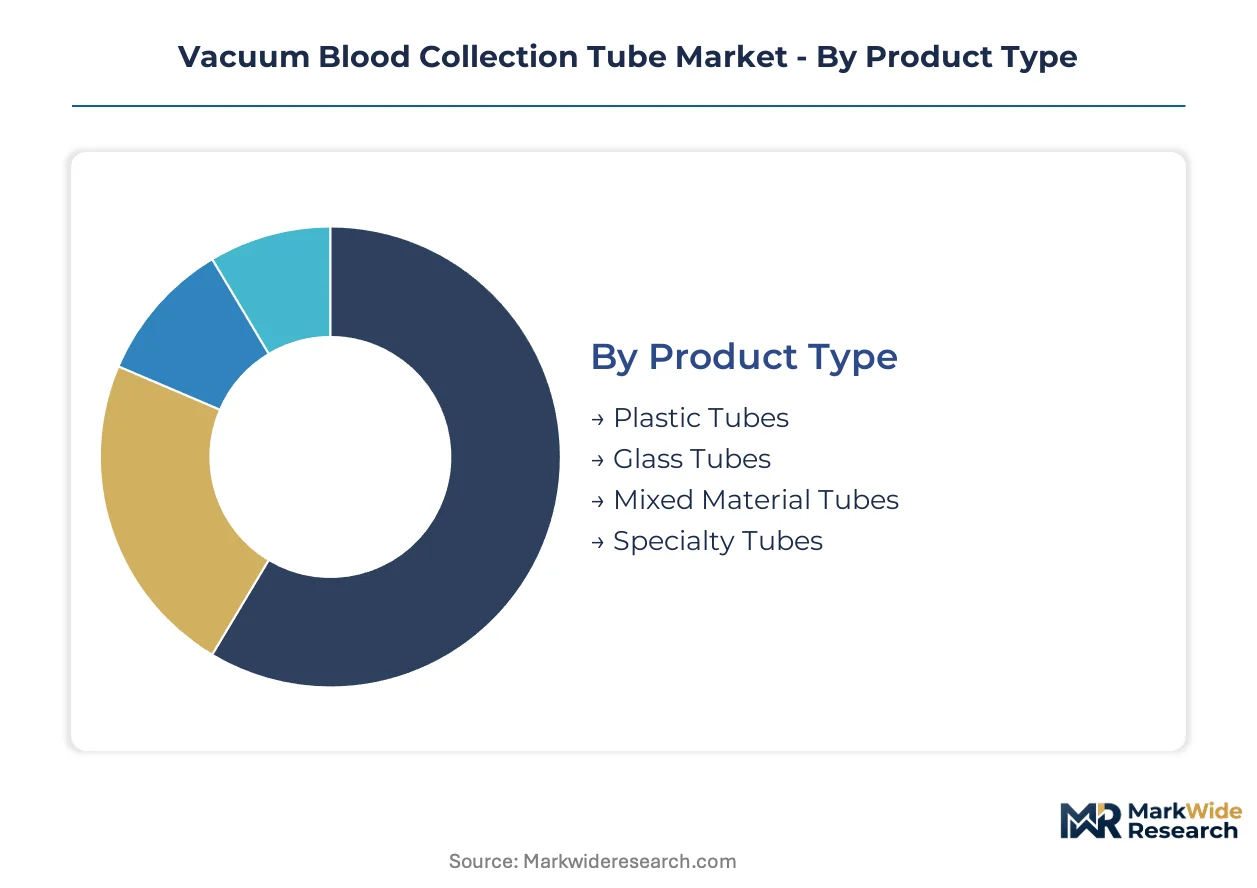
Segmentation within the vacuum blood collection tube market reveals distinct product lifecycles, technological dependencies, and end-user requirements. Understanding these segments is crucial for manufacturers to align product development with evolving clinical needs and regulatory landscapes.
Product Type:
Segments within product type exhibit varying life cycles, from high-volume, rapid-turnover plastic tubes to specialized, lower-volume mixed material options.
- Plastic Tubes:These tubes are primarily made from shatter-resistant polyethylene terephthalate (PET), offering superior safety and durability compared to glass. Demand concentrates in large diagnostic laboratories in China, driven by extensive public health screening programs.
- Specialty Tubes:Designed for specific, sensitive assays, these tubes often contain proprietary additives for preserving emerging biomarkers like cell-free DNA. Demand concentrates in research institutions for liquid biopsy and proteomics applications.
- Glass Tubes:Historically dominant, these tubes are now largely displaced due to safety concerns and material advancements in plastic alternatives across most clinical settings.
- Mixed Material Tubes:These combine plastic bodies with specific internal coatings or components, balancing durability with specialized surface properties for niche applications.
Plastic Tubes dominate the installed base. Specialty Tubes are where expansion concentrates.
Technology:
The diverse array of internal tube technologies directly supports the specificity and precision required for various diagnostic tests.
- EDTA:This technology utilizes Ethylenediaminetetraacetic acid as an anticoagulant to preserve cellular components and prevent clotting. Demand concentrates in hematology and molecular diagnostics for complete blood counts and DNA analysis.
- Clot Activator:Tubes with clot activators feature silica particles or thrombin to accelerate blood clotting, facilitating serum separation for analysis. Demand concentrates in clinical chemistry and serology for general biochemistry panels.
- Heparin:This technology employs lithium, sodium, or ammonium heparin as an anticoagulant to prevent clotting, primarily used for plasma analysis.
- Gel Separator:Tubes with a gel separator contain an inert thixotropic gel that forms a stable barrier between serum/plasma and blood cells after centrifugation, improving sample stability.
- Citrate:Sodium citrate acts as an anticoagulant by binding calcium ions, primarily used for coagulation studies and erythrocyte sedimentation rate tests.
- Fluoride:Sodium fluoride functions as an antiglycolytic agent and an anticoagulant, essential for accurate glucose and lactate measurements.
Precision requirements drive demand for specific anticoagulant and activator technologies, with automation compatibility becoming a critical differentiator.
Application:
Application segments reflect the varied purposes of blood collection, from high-volume routine screening to specialized research endeavors.
- Diagnostic Testing:This application encompasses routine blood tests for disease detection, monitoring, and general health assessment across various medical specialties. Demand concentrates in pathology centers and hospitals globally for a vast array of common conditions like diabetes and cardiovascular disease.
- Clinical Trials:This involves collecting blood samples for drug development, efficacy assessment, and safety monitoring in controlled research studies. Demand concentrates in pharmaceutical companies and contract research organizations globally for new therapeutic evaluations.
- Biobanking:This application focuses on the long-term storage of biological samples for future research, requiring tubes that preserve sample integrity over extended periods.
- Blood Typing:This application utilizes specific tubes for ABO/Rh determination and cross-matching, crucial for transfusion medicine in blood banks.
- Therapeutic Monitoring:This involves regular blood draws to assess drug levels or disease markers, ensuring optimal patient treatment and safety.
Routine diagnostic testing accounts for the largest volume consumption, while clinical trials and biobanking applications present opportunities for specialized product innovation.
End User:
End-user segments highlight distinct procurement behaviors and infrastructure requirements across healthcare facilities.
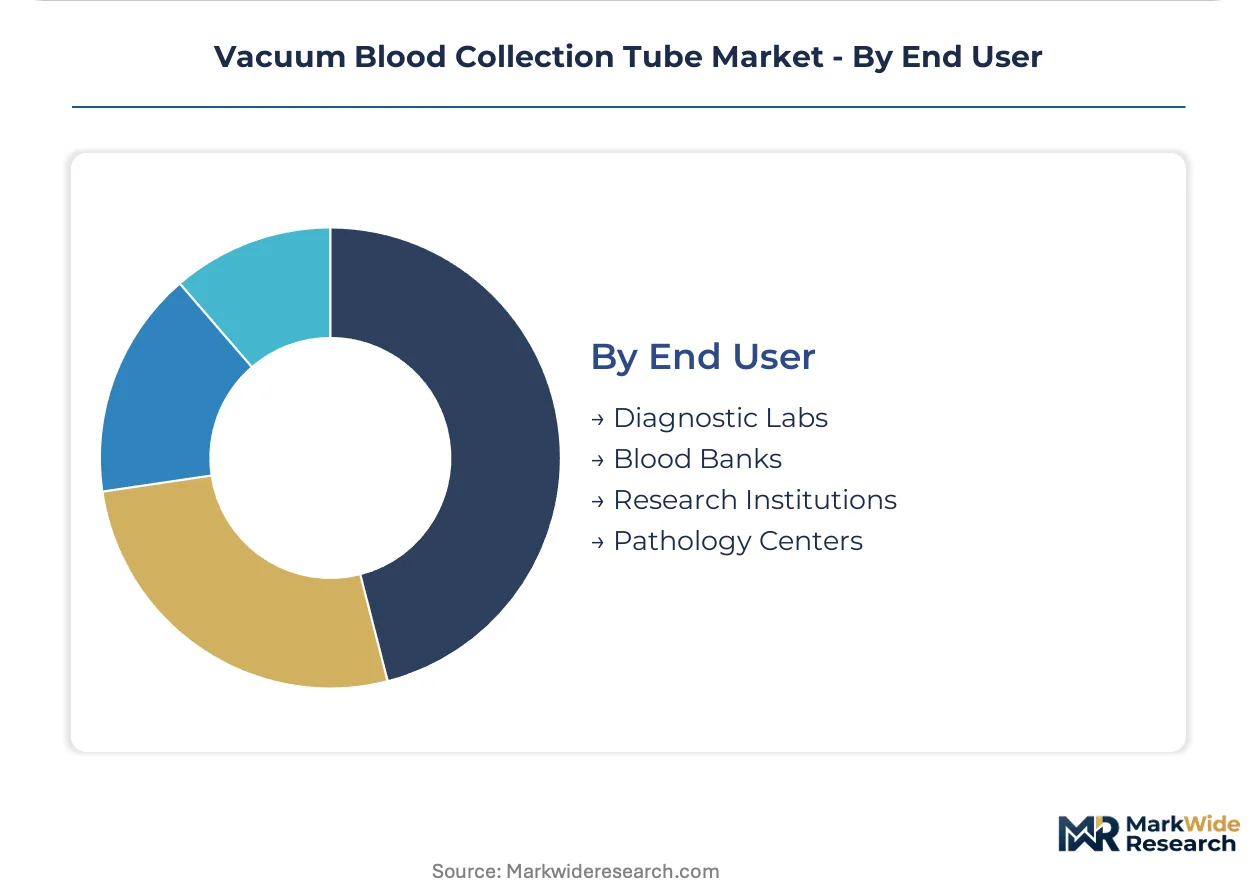
- Diagnostic Labs:These are high-throughput facilities performing a wide range of analytical tests on patient samples for various healthcare providers. Demand concentrates in urban centers and large reference laboratories that prioritize automation compatibility and cost-efficiency.
- Pathology Centers:These specialized laboratories focus on disease diagnosis through tissue and fluid analysis, including high-volume blood work for hospitals and clinics. Demand concentrates in integrated delivery networks in the United States and Germany for process standardization.
- Blood Banks:These specialized centers focus on collecting, processing, and storing blood products for transfusions, demanding stringent quality control and specific tube types.
- Research Institutions:These academic and private entities engage in basic and translational research, often requiring specialized tubes for novel assays and biobanking.
Diagnostic Labs and Pathology Centers represent the primary volume drivers, with research institutions seeking tubes optimized for emerging scientific applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration heavily influences regional market dynamics for vacuum blood collection tubes. High-volume diagnostic laboratories and pathology centers drive demand, particularly in regions undergoing significant healthcare infrastructure expansion. These end-users prioritize automation compatibility and cost-efficiency in their procurement strategies.
China
China's extensive public health screening programs create immense volume demand for standardized vacuum blood collection tubes. The country's national health policies, including large-scale disease prevention initiatives, mandate widespread diagnostic testing. Major urban centers like Beijing and Shanghai are witnessing rapid hospital infrastructure expansion, fueling local market growth.
United States
The United States market is characterized by stringent regulatory oversight and a strong emphasis on safety. FDA 510(k) clearance is critical for market entry, ensuring product quality and efficacy. Integrated Delivery Networks (IDNs) across major metropolitan areas like New York and Los Angeles are consolidating procurement, seeking bundled phlebotomy solutions.
Germany
Germany exhibits a mature market with a focus on manufacturing excellence and advanced pre-analytical systems. CE marking under the MDR dictates product compliance, impacting market access for novel materials. Pathology centers in regions like North Rhine-Westphalia and Bavaria are key end-users, demanding integrated phlebotomy solutions.
India
India's rapidly expanding healthcare sector and increasing prevalence of chronic diseases are driving diagnostic testing volumes. Government initiatives aimed at improving primary healthcare access are expanding the network of diagnostic laboratories. Major cities such as Mumbai and Delhi are experiencing significant investment in modern pathology infrastructure.
Japan
Japan's advanced diagnostic infrastructure and aging population contribute to a steady demand for high-quality blood collection tubes. PMDA regulations ensure strict adherence to medical device standards, emphasizing precision and reliability. Research institutions in areas like Tokyo and Kyoto are also crucial, focusing on specialized tubes for emerging biomarker analysis.
Vacuum Blood Collection Tube Market Key Industry Players
Channel-controlling players compete with product-specialist players to secure market share in vacuum blood collection tubes. The market structure exhibits consolidation around a few global integrators alongside a fragmented base of regional manufacturers and niche innovators. Strategic archetypes include large-scale distributors, specialized technology providers, and integrated solution developers. Dominant competitive moves involve leveraging extensive patent portfolios and forming strategic partnerships for product differentiation.
Within the global integrator archetype, Becton, Dickinson and Company exemplifies market leadership through its broad product portfolio and extensive distribution network. This company leverages its significant patent portfolio to maintain a dominant market presence across various geographies. Greiner Bio-One GmbH, a GmbH company, occupies a strong position as a specialized innovator, focusing on advanced pre-analytical systems and tubes for sensitive assays. SARSTEDT AG & Co. KG, an AG & Co. KG, anchors the segment for manufacturing excellence and integrated phlebotomy solutions for hospital systems. These players continually adapt their offerings to meet evolving regulatory standards and automation compatibility requirements, addressing both high-volume routine testing and niche research applications.
| Leading Market Players |
|---|
| SARSTEDT AG & Co. KG |
| Sekisui Medical Co., Ltd. |
| Becton, Dickinson and Company |
| FL Medical |
| Nipro Corporation |
| Greiner Bio-One GmbH |
| Cardinal Health |
| Improve Medical Instruments Co., Ltd. |
| Terumo Corporation |
| Others |
Cost & Logistics Intelligence
China's significant PET tube manufacturing overcapacity influences global pricing dynamics, prompting suppliers to optimize production efficiencies and adjust pricing strategies.
Pricing Analysis
Cost-plus contract patterns with raw material indexation govern many long-term procurement agreements for vacuum blood collection tubes. Price differentiation emerges from certification levels, such as FDA 510(k) clearance, and significant volume scale. Pricing softness stems from intense competition among manufacturers and regional overcapacity. Diagnostic labs exhibit high price sensitivity, while research institutions prioritize specialized tube performance over cost.
Supply Chain Analysis
Contract manufacturing concentration in China, Germany, and Japan dominates the supply of vacuum blood collection tubes. The production relies heavily on medical-grade PET resin and specialized anticoagulants like EDTA and heparin. Commodity price volatility for these inputs presents a structural supply chain risk. Distribution typically runs through established medical distributors and direct sales channels to large hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vacuum blood collection tube market is experiencing a buyer-power shift, driven by integrated delivery networks (IDNs) consolidating procurement for bundled phlebotomy solutions.
For Market Incumbents:Pre-empt emerging competitive threats from alternative sample types by investing in specialized tube development for advanced diagnostics. Expand patent portfolios to protect novel additive formulations for liquid biopsy applications. Consolidate market share through strategic acquisitions of regional manufacturers with strong distribution networks in Southeast Asia. This approach mitigates margin pressure from high-volume commodity tube sales.
For New Entrants and Emerging Players:Underserved diagnostic infrastructure in Southeast Asia and Latin America represents a penetrable entry point for standardized plastic tubes. Focus on developing tubes compatible with high-throughput automated analyzers, a critical go-to-market angle. Partner with local distributors to navigate regional registration requirements and establish market access. Specialized tubes for cell-free DNA preservation also offer a niche opportunity.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across specialized tube manufacturing due to complex additive development and stringent validation requirements. Long-term viability remains strong, supported by sustained diagnostic testing volumes for chronic disease management. Target niche innovators with unique intellectual property in pre-analytical systems or smart tube technologies. Monitor adoption rates of integrated sample management solutions as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Patent Portfolio | Becton, Dickinson and Company leverages intellectual property to maintain market dominance against new entrants. |
| Develop Specialized Tubes | Greiner Bio-One GmbH differentiates its offerings for sensitive assays like liquid biopsy, commanding premium pricing. |
| Pursue Geographic Expansion | Manufacturers can navigate local registration requirements to access new growth markets in Southeast Asia. |
| Enhance Automation Compatibility | SARSTEDT AG & Co. KG ensures its tube dimensions and cap designs integrate with diverse laboratory systems. |
| Secure Regulatory Clearances | FDA 510(k) clearance and CE marking are critical for market access in the United States and Europe. |
Research Approach
Operator-level perspectives from pathologists, lab managers, procurement officers, and regulatory affairs specialists anchored the qualitative base of this analysis. Primary interviews were triangulated with secondary validation from FDA 510(k) filings, CE marking documentation, ISO 6710 standards, and national health ministry reports. This approach facilitated a robust bottom-up and top-down data synthesis.
Scenario-bracketing informed the quantitative analytical framework across the analysis window, evaluating potential market trajectories. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, projected demand drivers, and industry-specific forecast inputs like chronic disease prevalence data and public health screening program budgets.
Practitioners should monitor regulatory divergence and medical-grade PET resin input cost volatility for early signals of market shifts. Forecasts reflect assumptions regarding technological advancements and healthcare infrastructure expansion. Quarterly review of regulatory updates and raw material pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Laboratory Temperature Control Units Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Human Milk Analyzers Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Micropipette Puller Market