
 Bulbospinal Muscular Atrophy Drugs Market | 2026-2036
Bulbospinal Muscular Atrophy Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Bulbospinal Muscular Atrophy Drugs Market Analysis
Rare-disease venture philanthropy and milestone-based partnership structures is rewriting capital access for developers of bulbospinal muscular atrophy therapies. GlaxoSmithKline plc leverages its established rare-disease infrastructure to sustain clinical programs in neuromuscular indications. Takeda Pharmaceutical Company Limited anchors its position through deep expertise in plasma-derived and gene-targeted platforms for orphan conditions. Pfizer Inc competes via strategic positioning in antisense oligonucleotide research partnerships.
Bulbospinal muscular atrophy drugs comprise therapeutic agents targeting the androgen receptor polyglutamine expansion that causes progressive lower motor neuron degeneration, with formulations requiring blood-brain barrier penetration or direct central nervous system delivery. These therapeutics aim to halt or reverse skeletal muscle atrophy, bulbar dysfunction, and endocrine disruption characteristic of Kennedy disease. Antisense oligonucleotides command concentrated R&D investment due to their sequence-specific knockdown potential against mutant androgen receptor transcripts. Intrathecal delivery routes attract technical attention as manufacturers address the pharmacokinetic challenge of achieving therapeutic concentrations in spinal cord motor neurons. Gene therapy approaches occupy the frontier segment, with viral vector manufacturing scale and durable expression timelines determining competitive viability.
FDA orphan drug designation and EMA priority medicines pathways shape clinical trial design and market exclusivity timelines for bulbospinal muscular atrophy developers. The national pharmaceutical regulator in Japan and Health Canada each maintain accelerated review frameworks for serious rare diseases, creating parallel approval tracks that influence global development sequencing. Stakeholders must monitor biomarker qualification progress and payer evidence requirements for one-time gene therapies versus chronic small-molecule administration.
Market Dynamics
Antisense oligonucleotide platforms are compressing development timelines for Kennedy disease therapeutics while intrathecal delivery systems reshape clinical trial infrastructure requirements.
Growth Catalysts
- EMA Priority Medicines Pathway:Accelerated assessment timelines for serious rare diseases reduce regulatory lag between Phase II data and conditional marketing authorization in European markets.
- Expanded Newborn Screening:State-level mandates in the United States identify presymptomatic patients earlier, expanding addressable populations for intervention protocols.
- Gene Therapy Manufacturing Scale:Viral vector production capacity at dedicated CDMO facilities is removing bottlenecks that previously stalled rare disease program advancement.
Market Restraints
- Intrathecal Delivery Complexity:Specialized catheter systems and neurosurgical coordination requirements limit site activation for pivotal trials.
- Plasma-Derived Input Volatility:Immunoglobulin and albumin supply fluctuations from fractionation facility concentration in North America and Europe create raw material uncertainty.
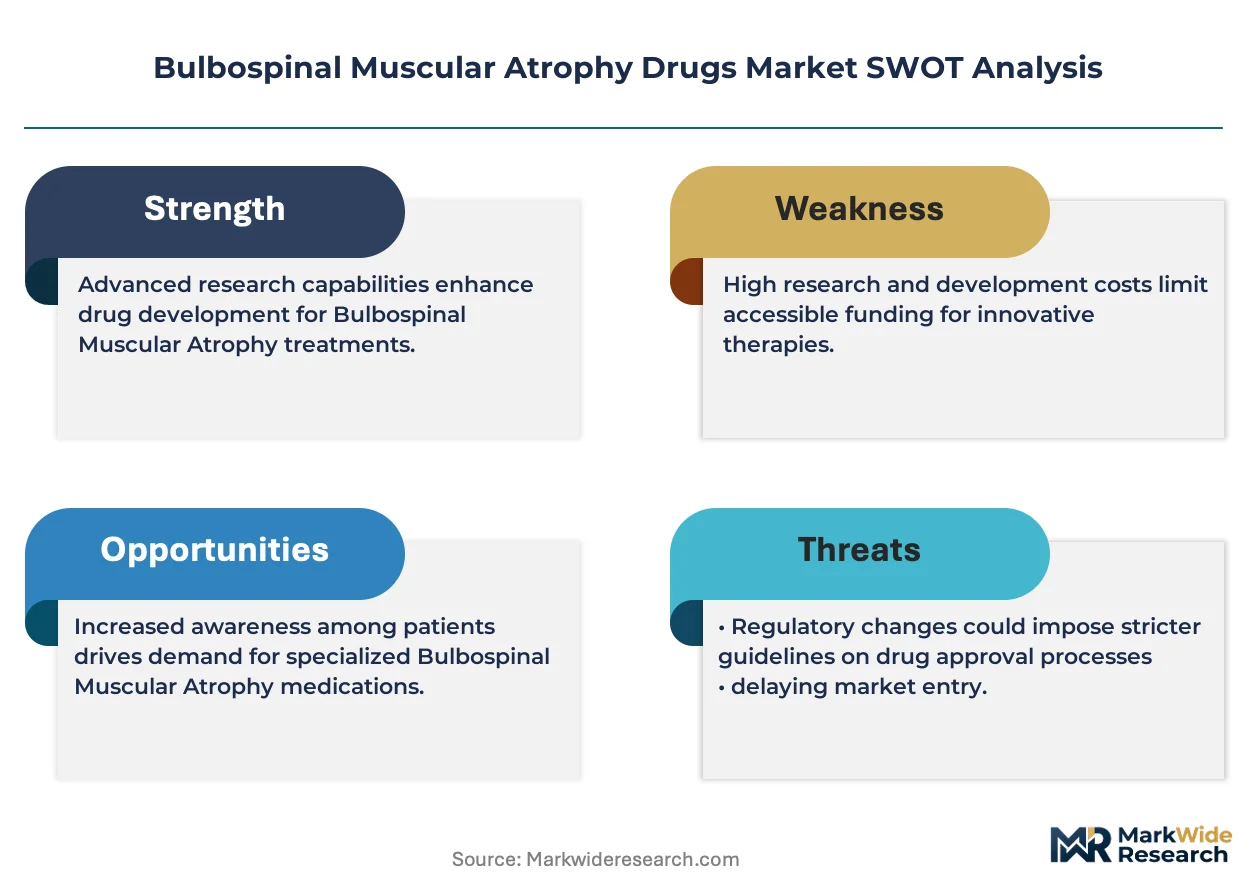
- Biomarker Qualification Delays:FDA and EMA have not validated surrogate endpoints for Kennedy disease progression, extending pivotal study duration requirements.
Strategic Opportunities
- Japan's Sakigake Designation:PMDA's fast-track framework offers priority review and extended market exclusivity for first-in-class neuromuscular therapies.
- Direct-to-Patient Distribution:Specialty pharmacy networks bypass hospital procurement committees for chronic antisense administration.
- CRISPR-ASO Convergence:Combination platforms integrating transient transcript knockdown with permanent gene editing address durability limitations of single-modality approaches.
Industry Challenges
- Neurosurgeon Training Bottlenecks:Intrathecal catheter placement expertise concentrates at academic medical centers, constraining patient enrollment velocity.
- Reimbursement Evidence Standards:Payers demand functional outcome data exceeding 24 months for one-time gene therapies, compressing pricing negotiation leverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulbospinal Muscular Atrophy Drugs Market |
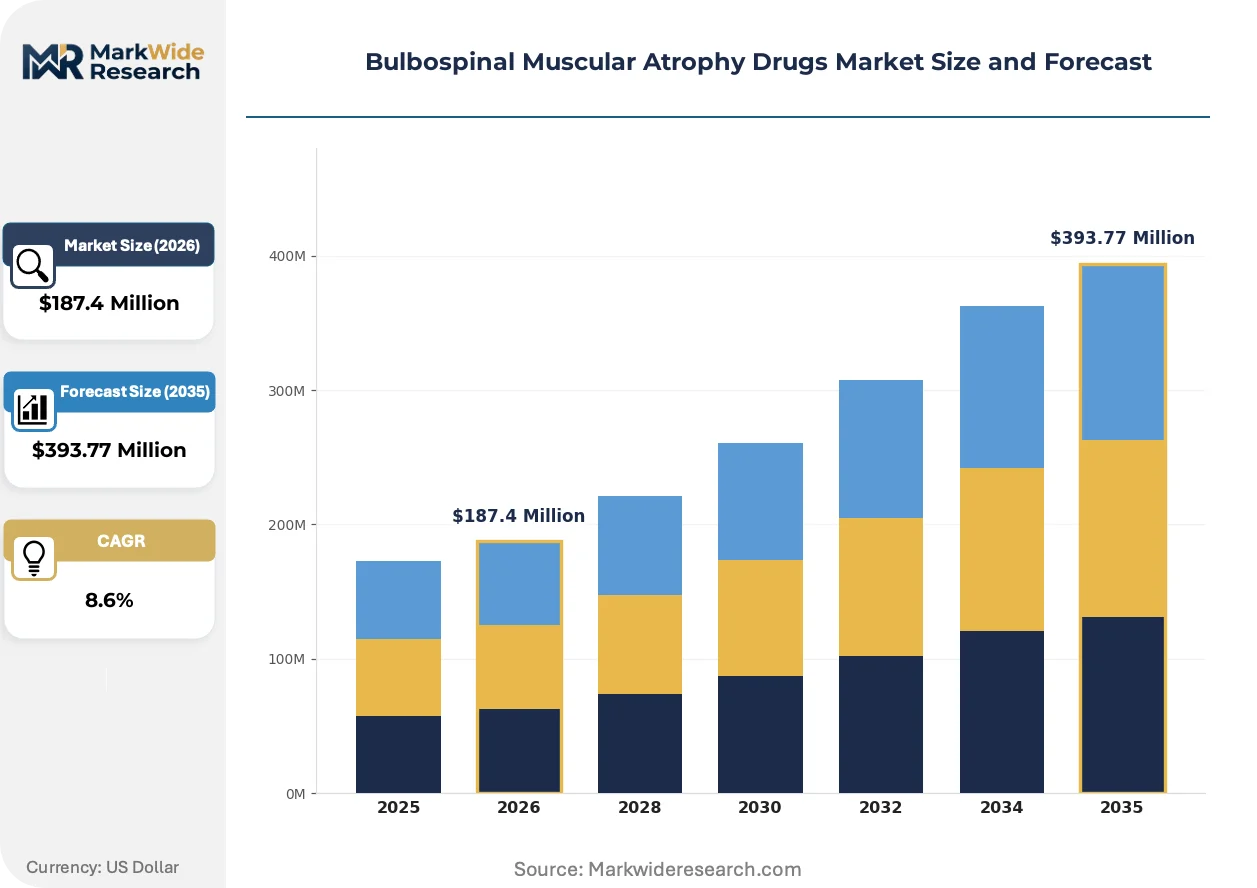
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Small Molecule, Antisense Oligonucleotides, Protein Replacement Delivery Mode: Intravenous, Subcutaneous, Oral, Intrathecal End User: Hospitals, Clinics, Homecare, Research Institutions Treatment Stage: Preclinical, Clinical Trials, Post-Marketing, Approved |
| Companies Covered | GlaxoSmithKline plc, AbbVie Inc, Takeda Pharmaceutical Company Limited, Astellas Pharma, Pfizer Inc, Sanofi, Novartis, Boehringer Ingelheim International GmbH, Johnson and Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulbospinal Muscular Atrophy Drugs Market Emerging Trajectories
Delivery modality diversification and biomarker-driven trial design are restructuring how bulbospinal muscular atrophy programs advance from preclinical stages to regulatory submission.
Antisense oligonucleotide chemistry is migrating from first-generation phosphorothioate backbones to constrained ethyl modifications that improve spinal cord tissue penetration. Neuromuscular centers in the United States and Germany are adopting these next-generation chemistries for investigator-sponsored trials. The shift is compressing dose frequency requirements from monthly to quarterly intrathecal administration, reducing site burden and patient travel constraints.
REACH regulation in Europe is tightening impurity thresholds for oligonucleotide manufacturing intermediates, forcing CDMOs to revalidate synthetic routes. The industrial consequence is extended tech transfer timelines and higher qualification costs for European supply chains. Developers with captive manufacturing or pre-qualified Asian suppliers are gaining six-to-nine month regulatory submission advantages.
Patient advocacy organizations are consolidating procurement influence through centralized registries that direct trial-ready cohorts toward specific sponsors. This behavior shift is displacing traditional site-by-site recruitment with pre-qualified patient pools managed by the Kennedy's Disease Association and analogous bodies in Germany and Japan. The phenomenon is most visible in the United States, where advocacy-funded natural history studies have created de facto screening infrastructure that sponsors now access through partnership structures rather than de novo investment.
Bulbospinal Muscular Atrophy Drugs Market Segmentation
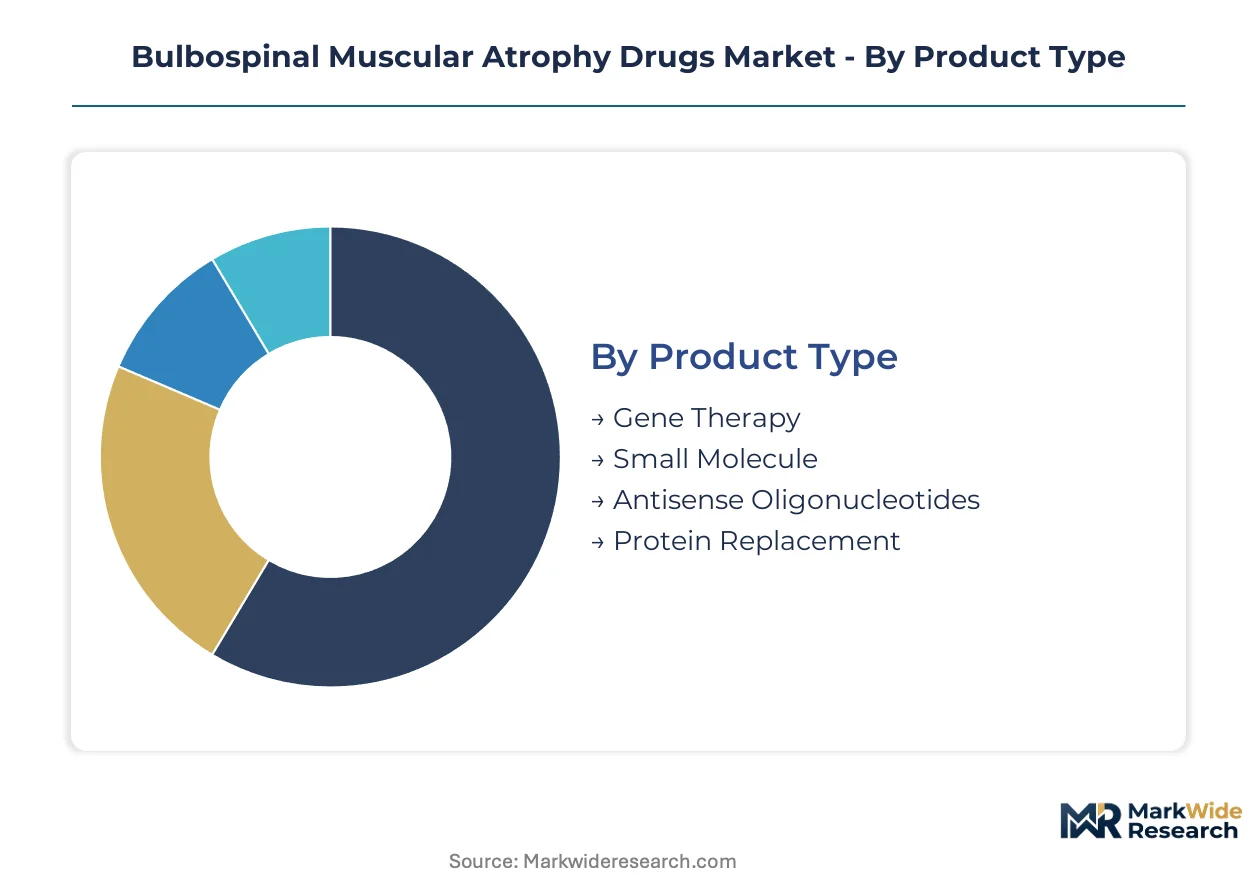
Segmentation in the bulbospinal muscular atrophy drugs market reveals how therapeutic modality, delivery complexity, and care setting interact to determine patient access and commercial viability. Developers must align platform selection with infrastructure requirements at specialized neuromuscular centers and evolving homecare protocols.
Product Type:
Use-case spectrum spans curative intent through chronic disease management, with each modality demanding distinct manufacturing scale and regulatory evidence packages.
- Antisense Oligonucleotides:Sequence-specific knockdown agents targeting mutant androgen receptor transcripts with constrained ethyl backbone modifications improving spinal cord penetration. United States neuromuscular centers concentrate demand for quarterly intrathecal administration protocols as site burden reduction becomes a patient retention priority.
- Gene Therapy:Viral vector-delivered genetic constructs aiming for durable expression with single-dose administration. Manufacturing scale at dedicated CDMO facilities is removing prior capacity bottlenecks, though payer evidence requirements exceeding 24 months of functional outcome data compress pricing negotiation leverage for developers.
- Small Molecule:Blood-brain barrier penetrant compounds addressing androgen receptor polyglutamine expansion through alternative mechanistic pathways.
- Protein Replacement:Exogenous protein administration compensating for deficiency states secondary to motor neuron degeneration.
Established volume favors antisense oligonucleotides; emerging adoption favors gene therapy.
Delivery Mode:
Route selection determines site activation requirements, pharmacokinetic profiles, and patient compliance architecture across the treatment journey.
- Intrathecal:Direct cerebrospinal fluid delivery via specialized catheter systems achieving therapeutic concentrations in spinal cord motor neurons. Germany and United States academic medical centers concentrate enrollment capacity, though neurosurgeon training bottlenecks constrain patient velocity for pivotal trials.
- Oral:Systemic administration with blood-brain barrier penetration requirements driving formulation complexity for Kennedy disease indications.
- Intravenous:Peripheral vascular access enabling systemic distribution with CNS penetration limitations necessitating higher dosing regimens.
- Subcutaneous:Depot formulations or continuous infusion systems for chronic administration protocols in outpatient settings.
Site infrastructure constraints concentrate development in intrathecal; patient convenience preferences are expanding oral formulation investment.
End User:
Care setting fragmentation reflects the intersection of therapy complexity, reimbursement architecture, and patient mobility limitations characteristic of progressive neuromuscular disease.
- Hospitals:Inpatient and infusion center administration for complex delivery modalities requiring surgical coordination or intensive monitoring. United States hospital procurement committees remain gatekeepers for one-time gene therapy access, while specialty pharmacy networks increasingly bypass these structures for chronic antisense administration.
- Homecare:Nurse-administered or patient self-administration protocols for subcutaneous and selected oral therapies. Expanded newborn screening programs in United States state-level mandates are expanding addressable populations requiring longitudinal care coordination across settings.
- Clinics:Outpatient neuromuscular specialty centers managing intrathecal administration schedules and monitoring protocols.
- Research Institutions:Academic medical center sites conducting natural history studies and interventional trials with de facto screening infrastructure.
Institutional concentration favors hospitals; care model evolution favors homecare.
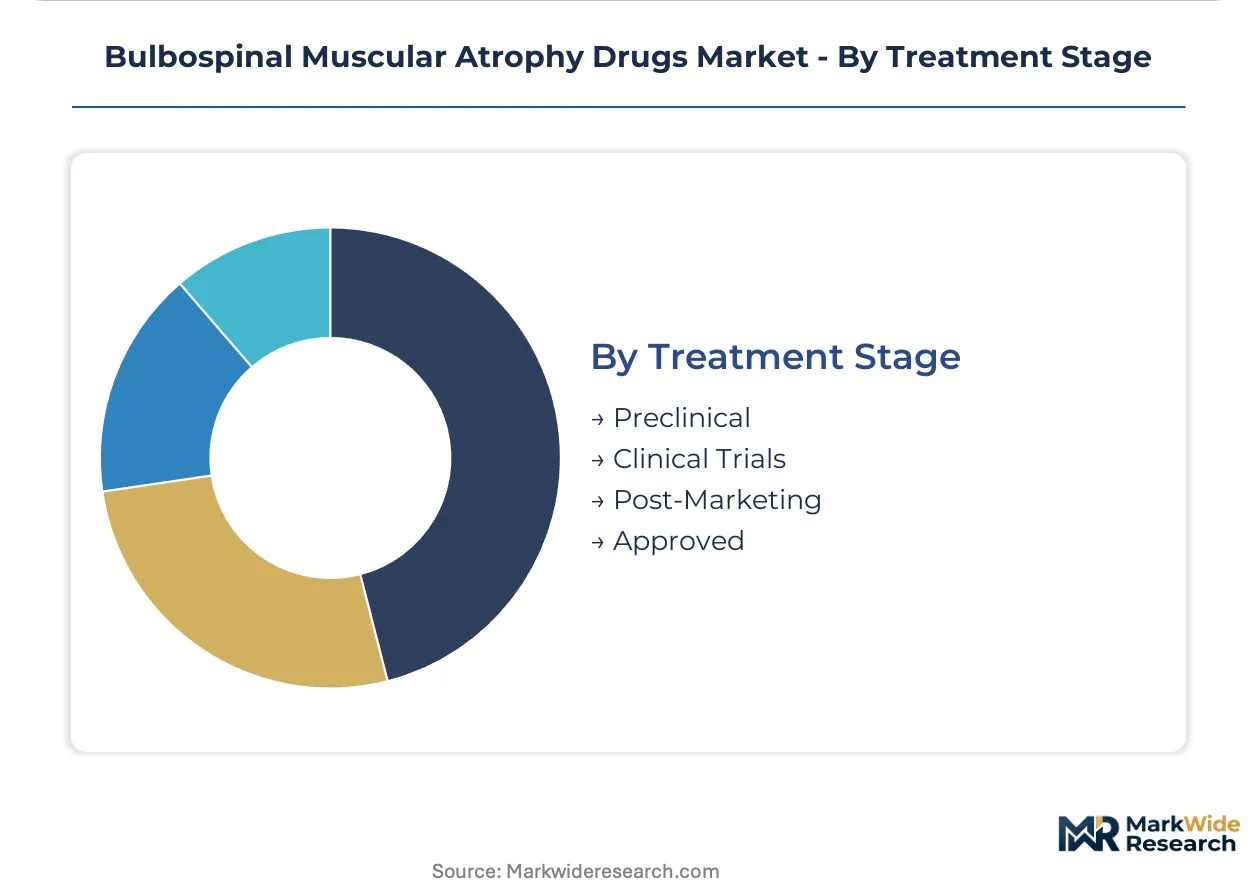
Treatment Stage:
Development phase distribution indicates pipeline maturity and the timeline for competitive entry reshaping market dynamics.
- Clinical Trials:Active interventional studies spanning Phase I through pivotal Phase III designs. FDA orphan drug designation and EMA priority medicines pathways are compressing regulatory lag between Phase II data and conditional marketing authorization in European markets.
- Approved:Marketed therapies with established reimbursement and distribution infrastructure. Japan's PMDA Sakigake designation offers priority review and extended market exclusivity for first-in-class neuromuscular therapies entering this category.
- Preclinical:Early-stage programs including CRISPR-ASO convergence platforms addressing durability limitations of single-modality approaches.
- Post-Marketing:Real-world evidence generation and label expansion activities for approved agents.
Pipeline concentration favors clinical trials; commercial maturity favors approved.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for specialized neuromuscular therapies runs highest in markets lacking domestic antisense manufacturing infrastructure. The United States, Germany, and Japan collectively absorb the majority of intrathecal delivery systems and viral vector production capacity, while emerging markets rely on parallel import channels and expanded access programs.
United States
Specialized neuromuscular centers in Boston, Durham, and San Francisco anchor clinical trial enrollment for intrathecal antisense programs. The FDA's orphan drug designation framework compresses regulatory timelines while providing seven-year market exclusivity incentives. Massachusetts and North Carolina academic medical centers coordinate directly with advocacy-funded registries to channel presymptomatic patients identified through expanded newborn screening into intervention protocols.
Germany
Heidelberg and Munich university hospitals concentrate European intrathecal administration expertise, though neurosurgeon training bottlenecks constrain patient velocity for pivotal trials. The EMA's priority medicines pathway accelerates assessment timelines for serious rare diseases, reducing lag between Phase II data and conditional marketing authorization. REACH regulation tightening impurity thresholds for oligonucleotide manufacturing intermediates forces CDMOs to revalidate synthetic routes, extending tech transfer timelines.
Japan
Tokyo and Osaka metropolitan areas host the majority of Asia-Pacific Kennedy disease patient advocacy infrastructure and natural history study coordination. The PMDA's Sakigake designation offers priority review and extended market exclusivity for first-in-class neuromuscular therapies. Domestic plasma fractionation capacity remains limited, creating import dependency for immunoglobulin-based supportive care products.
United Kingdom
London and Cambridge clusters concentrate antisense oligonucleotide research partnerships, though post-Brexit regulatory divergence from EMA frameworks complicates parallel submission strategies. The MHRA's innovative licensing and access pathway provides early patient access while formal marketing authorization proceeds. NHS England's specialized commissioning arrangements create centralized procurement gatekeeping for high-cost gene therapies.
Switzerland
Basel and Zurich anchor European headquarters functions for multinational neuromuscular drug developers, leveraging Swissmedic's accelerated review frameworks for serious rare diseases. Domestic manufacturing of viral vectors remains minimal, requiring cross-border supply arrangements with German and French CDMO facilities. The country's pharmaceutical pricing authority applies outcome-based reimbursement criteria that demand extended functional outcome data for one-time therapies.
Bulbospinal Muscular Atrophy Drugs Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in chemistry and delivery device supply. The market structure consolidates around multinational pharmaceutical conglomerates with established rare-disease infrastructure, while emerging entrants cluster in gene therapy and CRISPR-ASO convergence platforms. Three archetypes dominate: antisense oligonucleotide developers with intrathecal delivery expertise, viral vector manufacturers scaling production capacity, and small-molecule specialists pursuing blood-brain barrier penetrant alternatives. Competitive moves center on milestone-based partnership structures for early-stage assets and captive manufacturing investments to secure supply chain control.
Among UK-based pharmaceutical conglomerates, GlaxoSmithKline plc occupies a position exemplifying rare-disease platform integration, while Takeda Pharmaceutical Company Limited represents Japanese multinational anchoring through plasma-derived and gene-targeted expertise. Pfizer Inc exemplifies antisense oligonucleotide research positioning via strategic partnership structures. These three entities collectively represent the dominant competitive archetypes: integrated rare-disease infrastructure, Asian-market anchoring with platform diversification, and nucleic acid therapeutic partnership models.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AbbVie Inc |
| Takeda Pharmaceutical Company Limited |
| Astellas Pharma |
| Pfizer Inc |
| Sanofi |
| Novartis |
| Boehringer Ingelheim International GmbH |
| Johnson and Johnson |
| Others |
Supply Flow & Price Mechanics
Undercapacity at dedicated viral vector CDMO facilities in the United States and Germany is compressing availability timelines for gene therapy candidates while simultaneously elevating pricing leverage for qualified manufacturers of antisense oligonucleotide backbones. This utilization asymmetry between modalities is forcing developers to commit to multi-year offtake contracts at premium rates to secure manufacturing slots, embedding cost rigidities that propagate through clinical trial budgets and eventual therapy pricing.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing structures for intrathecal delivery systems, with cost stratification across FDA breakthrough-designated, EMA priority-medicine-tagged, and standard development-tier assets. Price differentiation hinges on biomarker qualification status and manufacturing exclusivity arrangements, with unqualified surrogate endpoints compressing negotiation leverage. Pricing pressure stems from payer demands for functional outcome data exceeding twenty-four months, intensifying cost scrutiny for one-time gene therapies. Hospital procurement committees exhibit highest price sensitivity for chronic antisense administration protocols, while specialty pharmacy networks demonstrate greater flexibility on upfront costs when bundled with patient adherence programs.
Supply Chain Analysis
Contract manufacturing concentration at CDMO facilities in the United States, Germany, and Switzerland dominates viral vector and oligonucleotide production capacity for Kennedy disease therapeutics. Raw material dependencies center on phosphoramidite chemistries, recombinant albumin, and specialized catheter polymers subject to REACH-mandated impurity threshold tightening. Supply chain risk concentrates in single-source vulnerability for neurosurgical delivery device components, with academic medical center procurement committees facing extended lead times for trial activation. Distribution runs through specialty pharmacy networks for chronic administration, bypassing traditional hospital procurement structures for antisense oligonucleotide protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across delivery modality specialization, as expanded newborn screening programs fragment patient populations into presymptomatic intervention cohorts requiring distinct manufacturing scale and clinical infrastructure.
For Market Incumbents: Entrench rare-disease infrastructure advantages through captive manufacturing investments in constrained ethyl backbone chemistry and dedicated intrathecal delivery device production. Secure neurosurgeon training partnerships at academic medical centers to preempt enrollment bottlenecks for pivotal trials. Counter emerging CRISPR-ASO convergence platforms by accelerating biomarker qualification timelines to compress payer evidence requirements. For New Entrants and Emerging Players: Build out gene therapy manufacturing partnerships with Asian CDMO facilities to circumvent REACH-driven tech transfer delays affecting European supply chains. Target Japan's Sakigake-designated fast-track pathway as the most penetrable regulatory geography for first-in-class neuromuscular therapies. Establish direct-to-patient distribution capabilities to bypass hospital procurement committee gatekeeping for chronic administration protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across viral vector manufacturing sub-segments as dedicated facility construction outpaces near-term program demand. Long-term viability favors platform-integrated developers with antisense oligonucleotide chemistry expertise and established intrathecal delivery partnerships. Acquisition target archetypes include CRISPR-ASO convergence specialists with preclinical proof-of-concept and qualified CDMO relationships. Monitor biomarker qualification progress at FDA and EMA as the critical inflection signal for compressed regulatory timelines and expanded addressable populations.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Pathway | FDA and EMA validation of surrogate endpoints would compress pivotal study duration requirements for developers. |
| Captive Manufacturing Scale-Up | In-house viral vector production at dedicated facilities removes CDMO bottlenecks constraining gene therapy advancement. |
| Neurosurgeon Training Partnership | Academic medical center alliances expand site activation capacity for intrathecal delivery pivotal trials. |
| Direct-to-Patient Distribution | Specialty pharmacy networks bypass hospital procurement committees for chronic antisense administration protocols. |
| Regulatory Fast-Track Positioning | Sakigake and Priority Medicines designations accelerate assessment timelines and extend market exclusivity periods. |
Methodological Framework
Cross-validation between regulatory submission databases and clinical trial registries anchors the qualitative findings on development pipeline positioning and competitive entry timelines. Primary interviews with drug development executives, regulatory affairs leads, formulary directors at major payers, and hospital procurement managers were combined with secondary validation from FDA orphan drug designations, EMA priority medicines submissions, ClinicalTrials.gov protocols, and national newborn screening mandate databases. Bottom-up patient population estimates and top-down therapy revenue projections were triangulated to constrain forecast variance.
Calibration against historical approval timelines for neuromuscular orphan indications informs the projection framework across the analysis window. Segmentation dimensions modeled include therapeutic modality, delivery route complexity, treatment stage, and regional regulatory cluster. CAGRs were derived from patient prevalence projections, therapy penetration assumptions, and pricing evolution scenarios. Forecast inputs incorporate biomarker qualification probability assessments and intrathecal site activation velocity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive manufacturing capacity expansion by emerging CDMO entrants or accelerated FDA biomarker validation would shift outcomes beyond modeled ranges. Regulatory divergence between EMA and post-Brexit MHRA frameworks, plasma-derived input supply disruptions, and gene therapy durability failures represent specific revision risks. Quarterly review of regulatory submission cadence and site activation metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Trenbolone Enanthate Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market