
 Middle East and Africa Gastrointestinal Drugs Market | 2026-2036
Middle East and Africa Gastrointestinal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Gastrointestinal Drugs Market Foresight
Specialty-grade biologic formulations is bifurcating the competitive landscape between mass-market antacid producers and targeted therapy developers. Takeda Pharmaceutical leverages its inflammatory bowel disease portfolio to anchor premium positioning across Gulf Cooperation Council hospital networks. Pfizer sustains broad-channel penetration through pharmacy-distributed proton pump inhibitor lines that compete on brand recognition rather than price.
Gastrointestinal drugs comprise pharmaceutical agents formulated to modulate acid secretion, motility, or mucosal integrity, typically administered via oral tablets with enteric coatings designed to withstand gastric pH before duodenal release. These compounds serve to manage chronic conditions including gastroesophageal reflux disease and peptic ulcer disorders across outpatient and inpatient settings. Proton pump inhibitors command the largest revenue pool within the product type dimension due to chronic prescribing patterns and patent-protected formulations. The therapy area segmentation shows inflammatory bowel disease generating the fastest growth trajectory as biologic penetration expands beyond South Africa into North African markets. Oral delivery mode dominates volume, though injectable biologics capture disproportionate margin in hospital settings.
South Africa's SAHPRA, Egypt's EDA, and Saudi Arabia's SFDA collectively shape market access through divergent bioequivalence requirements and import licensing protocols that extend registration timelines. The EU MDR convergence pressure on Gulf regulatory frameworks is elevating documentation standards for European-originated products. Stakeholders must monitor harmonization timelines between national medicine agencies and the African Medicines Regulatory Harmonization initiative to anticipate priority market entry sequencing.
Market Dynamics
Biologic penetration into inflammatory bowel disease treatment is compressing prescribing patterns for traditional small-molecule therapies across Gulf hospital networks and North African tertiary centers.
Growth Catalysts
- SFDA Accelerated Pathways:Saudi Arabia's streamlined biosimilar registration is reducing time-to-market for infliximab and adalimumab alternatives, expanding patient access to biologic IBD therapies.
- Chronic Gastritis Prevalence:Egypt's Cairo-Alexandria corridor sustains volume demand for proton pump inhibitors through high Helicobacter pylori infection rates and dietary risk factors.
- Enteric Coating Advances:pH-responsive polymer technologies are improving drug stability and bioavailability for acid-labile compounds targeting duodenal release.
Market Restraints
- Cold Chain Infrastructure Gaps:Temperature-controlled distribution networks remain underdeveloped in Sub-Saharan African markets outside South Africa, limiting biologics reach.
- Import Licensing Fragmentation:Divergent documentation requirements across SAHPRA, EDA, and SFDA extend registration timelines and duplicate compliance costs for multinational filings.
- Reference Product Pricing:Originator biologics maintain premium positioning through Gulf hospital tender structures, constraining biosimilar volume uptake despite regulatory approvals.
Strategic Opportunities
- Morocco Manufacturing Localization:Royal initiative incentives for pharmaceutical production are attracting fill-finish investments to serve Maghreb markets with reduced import dependency.
- Telemedicine Integration:Remote gastroenterology consultations are expanding diagnostic reach into Nigeria's secondary cities, creating new prescription channels for maintenance therapies.
- African Medicines Regulatory Harmonization:AMRH mutual recognition procedures promise consolidated registration pathways across participating East and West African states.
Industry Challenges
- Specialized Infusion Nursing:Biologic administration requirements outpace trained clinician availability in Jordan and Lebanon hospital systems.
- Legacy ERP Integration:Hospital procurement platforms across Gulf Cooperation Council networks require costly adaptation to track serialized biologic cold chain data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Gastrointestinal Drugs Market |
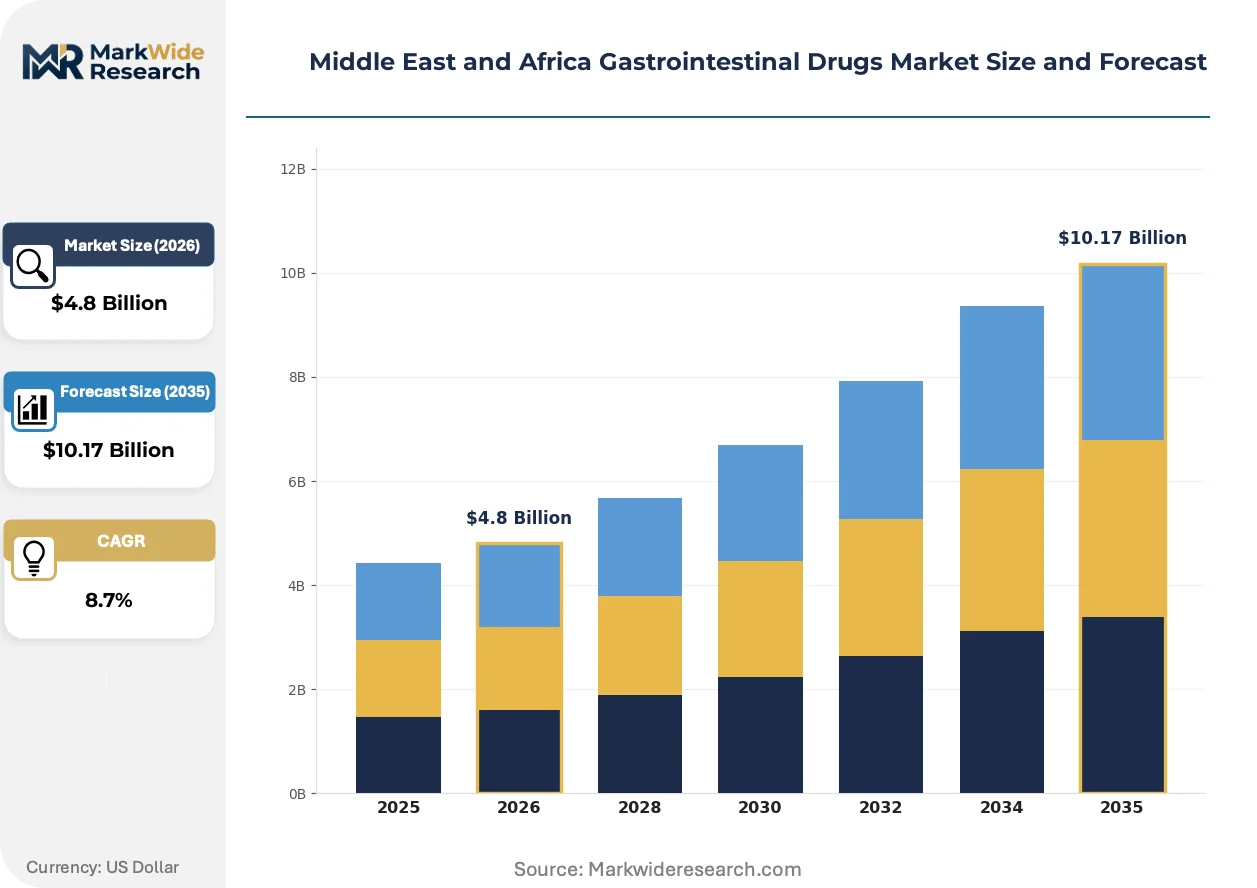
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antacids, Laxatives, Antidiarrheal, Proton Pump Inhibitors End User: Hospitals, Clinics, Pharmacies, Homecare Therapy Area: Gastroesophageal Reflux Disease, Irritable Bowel Syndrome, Inflammatory Bowel Disease, Peptic Ulcers Delivery Mode: Oral, Injectable, Topical, Rectal |
| Companies Covered | Sanofi, GlaxoSmithKline, Pfizer, Johnson & Johnson, AstraZeneca, Takeda Pharmaceutical, Abbott Laboratories, Novartis, Hikma Pharmaceuticals, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Gastrointestinal Drugs Market Shifts & Advancements
Oral biologic delivery platforms and regulatory convergence pressures are restructuring competitive advantage around formulation science rather than manufacturing scale alone.
Targeted nanoparticle carriers engineered for ileal release are miniaturizing biologic payloads to survive gastric transit without injection requirements. Egyptian and South African research hospitals are piloting these formulations for Crohn's disease patients with needle aversion. This technology is miniaturizing the administration barrier that has historically restricted biologics to infusion centers, enabling outpatient oral regimens that compress site-of-care costs.
EU MDR documentation standards are elevating Gulf regulatory expectations through SFDA and MOHAP alignment initiatives, requiring enhanced clinical evidence packages for European-originated products. Manufacturers now face parallel conformity assessment burdens that extend pre-market timelines. High-complexity biologics and combination devices encounter the steepest compliance gradients, with several sponsors withdrawing lower-priority indications from regional filings.
Hospital pharmacy committees are consolidating therapeutic interchange authority, displacing individual prescriber discretion with protocol-driven formulary compliance across Dubai Health Authority and Abu Dhabi Health Services networks. This concentration of procurement decision-making compresses vendor negotiation cycles and elevates total-cost-of-evidence requirements. The shift is most visible in Saudi Arabia's National Unified Procurement Company consolidated tenders for proton pump inhibitor classes.
Middle East and Africa Gastrointestinal Drugs Market Segmentation
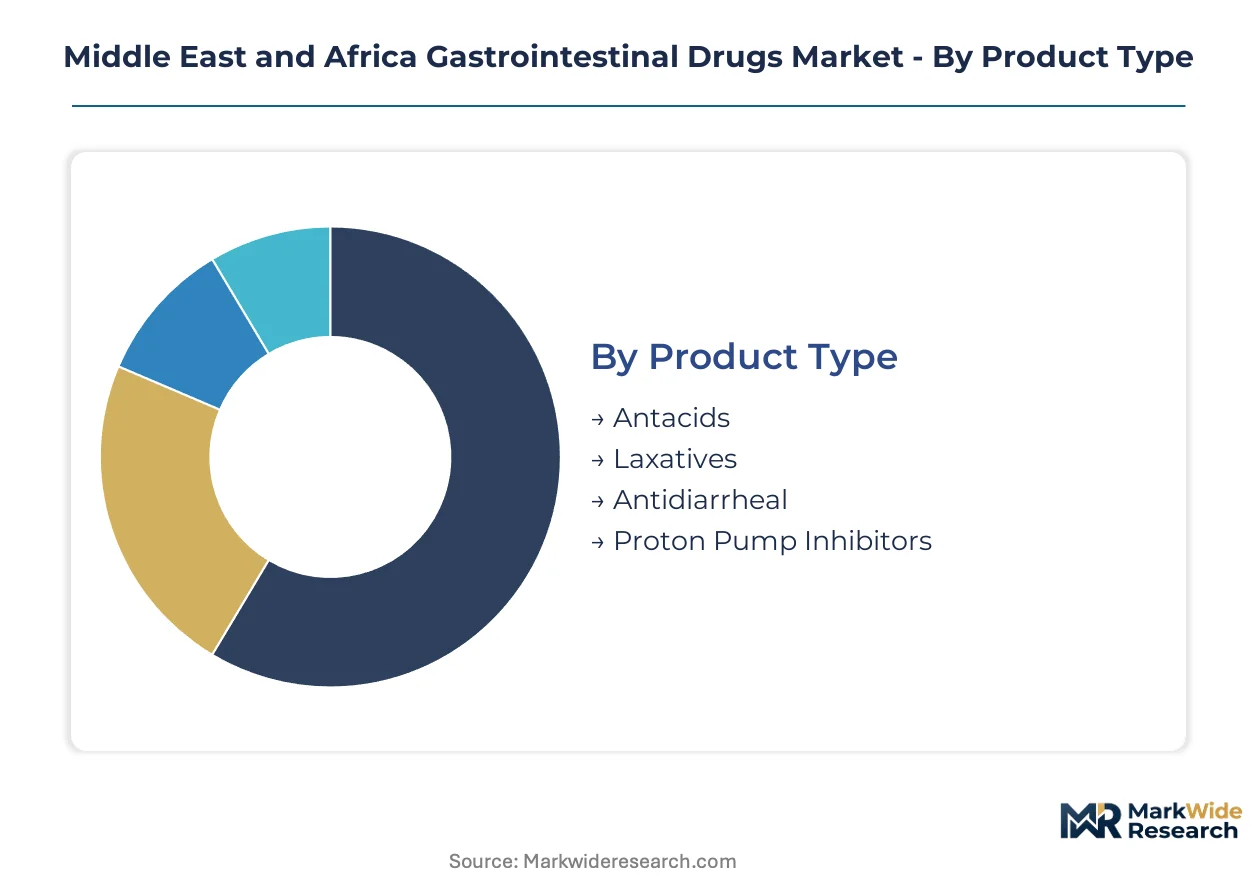
Segmentation reveals where biologic substitution is compressing traditional small-molecule volumes and which delivery modes face infrastructure constraints across Middle East and African markets. Understanding these fault lines guides resource allocation between mass-market and specialty portfolios.
Product Type:
Proton pump inhibitors face intensifying pressure from generic substitution and biosimilar encroachment, while antacids confront OTC channel displacement by private-label alternatives.
- Proton Pump Inhibitors:These agents irreversibly inhibit gastric H+/K+ ATPase enzymes, suppressing acid secretion for 24-hour intervals through enteric-coated formulations. Hospital procurement across Saudi Arabia's National Unified Procurement Company tenders concentrates demand for esomeprazole and pantoprazole, though originator brands retain formulary slots through bundled tender structures.
- Antacids:Rapid-acting neutralization compounds containing aluminum hydroxide, magnesium hydroxide, or calcium carbonate provide symptomatic relief without prescription requirements. Egypt's pharmacy-distributed volumes dominate regional consumption, driven by Cairo-Alexandria corridor self-medication patterns and limited primary care access.
- Laxatives:Osmotic and stimulant formulations address constipation predominant irritable bowel syndrome across outpatient settings.
- Antidiarrheal:Opioid agonists and adsorbent agents serve acute infectious diarrhea management where clean water access remains inconsistent.
Proton pump inhibitors retain volume leadership; inflammatory bowel disease biologics are displacing traditional acid suppression in premium hospital segments.
End User:
Cost tier stratification separates capital-intensive hospital infusion centers from distributed pharmacy networks, with procurement authority concentrating at divergent organizational levels.
- Hospitals:Tertiary care networks across Gulf Cooperation Council states anchor biologic administration through specialized gastroenterology units. Dubai Health Authority and Abu Dhabi Health Services therapeutic interchange protocols now override individual prescriber discretion, compressing vendor negotiation cycles and elevating total-cost-of-evidence requirements for formulary inclusion.
- Pharmacies:Community and hospital outpatient dispensaries handle maintenance therapy refills for chronic conditions across North African markets. Egypt's EDA registration pathways favor locally manufactured proton pump inhibitors, reducing import dependency while maintaining bioequivalence standards.
- Clinics:Primary care and specialist outpatient facilities manage diagnostic workup and initial prescribing decisions.
- Homecare:Self-administered oral regimens and visiting nurse services support treatment adherence outside institutional settings.
Hospitals command biologic margin concentration; pharmacies sustain volume throughput for maintenance therapies.
Therapy Area:
Application severity determines whether patients route through hospital biologic protocols or pharmacy-managed symptomatic care.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis require immunomodulatory biologics that disrupt inflammatory cytokine signaling. South Africa's SAHPRA streamlined biosimilar approvals are expanding infliximab and adalimumab access beyond tertiary centers into North African markets, though cold chain gaps in Sub-Saharan Africa outside South Africa constrain geographic penetration.
- Gastroesophageal Reflux Disease:Chronic acid exposure of esophageal mucosa drives long-term proton pump inhibitor prescribing. Saudi Arabia's SFDA maintains reference pricing alignment with European markets, preserving originator premium positioning despite biosimilar regulatory pathways.
- Irritable Bowel Syndrome:Functional motility and sensitivity disorders respond to antispasmodic and neuromodulatory agents.
- Peptic Ulcers:Helicobacter pylori eradication protocols combine acid suppression with antimicrobial therapy.
Gastroesophageal reflux disease retains prescription volume leadership; inflammatory bowel disease holds the steepest expansion curve as biologic penetration accelerates.
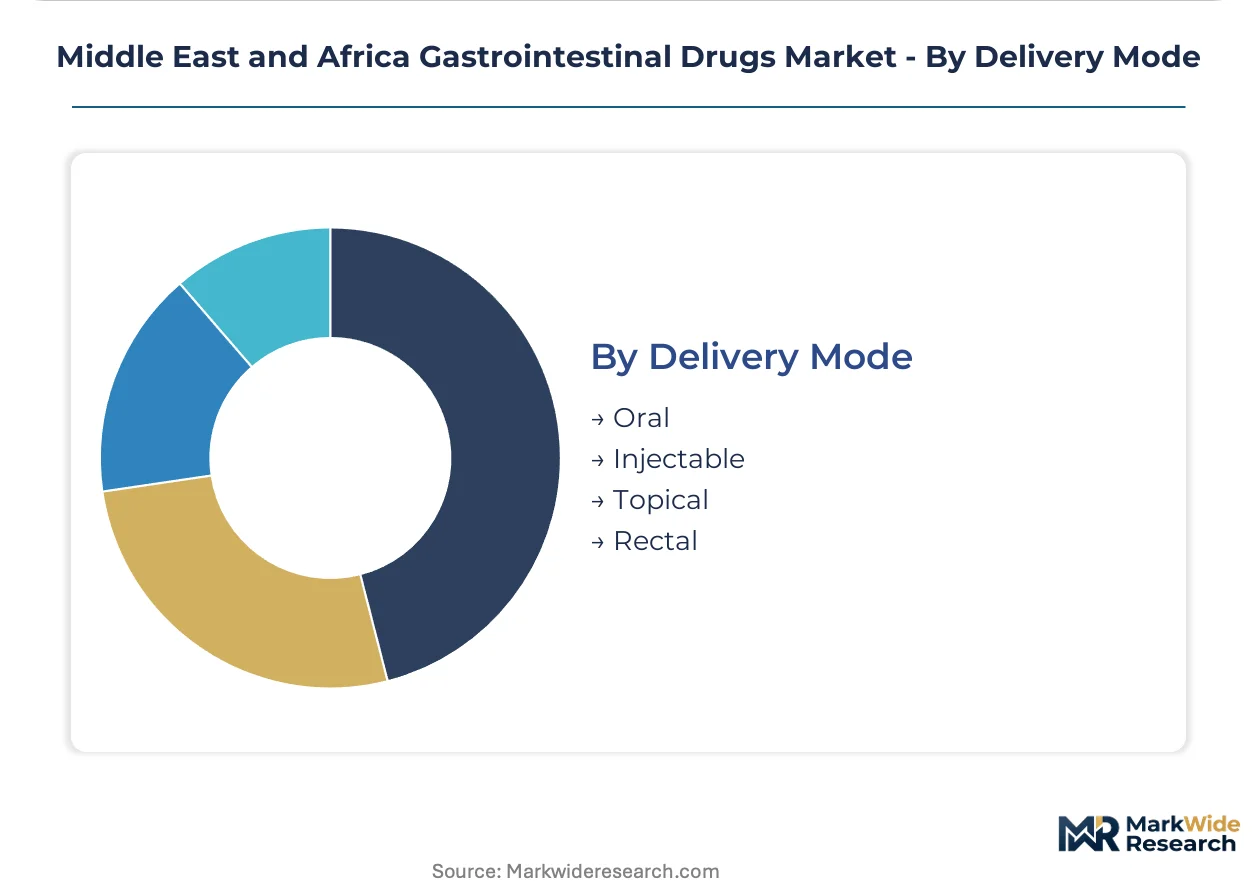
Delivery Mode:
Supply concentration in oral manufacturing contrasts with infrastructure-dependent biologic distribution, creating divergent margin and access profiles.
- Oral:Enteric-coated tablets and capsules dominate chronic maintenance prescribing through pharmacy channels. pH-responsive polymer advances from Egyptian and South African research hospitals are piloting nanoparticle carriers for ileal biologic release, potentially miniaturizing administration barriers that have restricted injectable therapies to infusion centers.
- Injectable:Subcutaneous and intravenous biologics require temperature-controlled distribution and specialized nursing capacity. Cold chain infrastructure gaps across Jordan and Lebanon hospital systems limit biologic reach, with trained infusion nursing availability lagging prescription growth.
- Topical:Rectal and perianal formulations serve localized inflammatory conditions.
- Rectal:Suppository and enema delivery provides direct mucosal contact for distal colonic disease.
Oral delivery retains volume leadership; injectable biologics capture disproportionate margin concentration in hospital settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fractures across the Middle East and Africa gastrointestinal drugs market, with Gulf Cooperation Council hospital networks absorbing premium biologic pricing while North African pharmacy channels drive aggressive generic substitution for proton pump inhibitors.
Saudi Arabia
Hospital procurement consolidation through the National Unified Procurement Company concentrates demand for originator proton pump inhibitors and biologic therapies. SFDA accelerated biosimilar pathways reduce infliximab registration timelines, expanding inflammatory bowel disease treatment access. Riyadh and Jeddah tertiary networks anchor biologic infusion capacity, with specialized gastroenterology units driving premium therapy adoption.
United Arab Emirates
Dubai Health Authority and Abu Dhabi Health Services therapeutic interchange protocols override individual prescriber discretion, compressing vendor negotiation cycles. MOHAP alignment with EU MDR documentation standards elevates clinical evidence requirements for European-originated products. Dubai's hospital pharmacy committees consolidate formulary authority, displacing fragmented procurement decision-making.
South Africa
SAHPRA streamlined biosimilar approvals expand infliximab and adalimumab access beyond tertiary centers into managed care networks. Chronic gastritis prevalence in urban corridors sustains volume demand for pharmacy-distributed acid suppression therapies. Johannesburg and Cape Town research hospitals pilot oral nanoparticle carriers for ileal biologic release, miniaturizing administration barriers.
Egypt
EDA registration pathways favor locally manufactured proton pump inhibitors, reducing import dependency while maintaining bioequivalence standards. The Cairo-Alexandria corridor sustains regional volume leadership through high Helicobacter pylori infection rates and dietary risk factors. EDA's streamlined pathways for generic substitution accelerate price compression in pharmacy channels.
Nigeria
Telemedicine-integrated gastroenterology consultations expand diagnostic reach into Lagos and secondary cities, creating prescription channels for maintenance therapies. Cold chain infrastructure gaps outside major urban centers limit biologic distribution to oral formulations. The country's national pharmaceutical regulator maintains fragmented import licensing protocols that extend registration timelines for multinational filings.
Middle East and Africa Gastrointestinal Drugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa gastrointestinal drugs market. The competitive structure stratifies between originator biologic developers commanding hospital formulary slots through bundled tender structures and generic manufacturers competing on price in pharmacy-distributed proton pump inhibitor segments. Three strategic archetypes dominate: multinational pharmaceutical conglomerates with inflammatory bowel disease biologic portfolios, regional generic specialists leveraging local manufacturing incentives, and diversified healthcare companies with broad-channel distribution capabilities. M&A activity concentrates on biosimilar portfolio expansion and geographic fill-finish investments, while strategic partnerships target cold chain infrastructure development in underserved markets.
Among multinational pharmaceutical conglomerates, Takeda Pharmaceutical and Pfizer occupy distinct positioning vectors. Takeda exemplifies the premium biologic archetype through its inflammatory bowel disease portfolio anchoring Gulf Cooperation Council hospital networks. Pfizer represents broad-channel penetration capabilities, competing on brand recognition across pharmacy-distributed proton pump inhibitor lines rather than price alone. Sanofi and GlaxoSmithKline sit within the diversified healthcare archetype, leveraging established distribution infrastructure across North African markets.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline |
| Pfizer |
| Johnson & Johnson |
| AstraZeneca |
| Takeda Pharmaceutical |
| Abbott Laboratories |
| Novartis |
| Hikma Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Long-term tender contracts through Saudi Arabia's National Unified Procurement Company lock in proton pump inhibitor supply access while anchoring price visibility across Gulf hospital networks. Egypt's EDA bioequivalence pathways for locally manufactured generics simultaneously compress pharmacy-channel pricing floors in North African markets.
Pricing Analysis
SFDA reference pricing alignment dictates the pricing tier structure across Saudi hospital procurement, separating originator biologics from biosimilar alternatives and locally manufactured small molecules. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, clinical evidence depth, and bundled tender participation. Cost compression in the economy tier is intensifying because Egyptian and Moroccan manufacturing incentives expand generic proton pump inhibitor capacity. Pharmacy-distributed maintenance therapies in North Africa exhibit highest price sensitivity; Gulf hospital biologic tenders show lowest sensitivity due to bundled originator contracts.
Supply Chain Analysis
Port congestion at Jeddah Islamic Port and container availability constraints on Asia-Middle East trade lanes elevate inbound logistics costs for European-originated active pharmaceutical ingredients. API manufacturing concentrates in India, China, and Switzerland for proton pump inhibitor precursors; biologic fill-finish capacity clusters in Ireland, Singapore, and South Africa. Raw material dependencies span enteric coating polymers, pH-responsive nanoparticle carriers, and temperature-stable excipients. Single-source vulnerability persists for specialized cold chain logistics providers serving Gulf biologic distribution. Distribution runs through hospital pharmacy committees in tertiary networks and community pharmacy chains in North African urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic penetration into inflammatory bowel disease treatment represents early-cycle expansion, with infliximab and adalimumab biosimilars capturing formulary slots faster than historical small-molecule substitution patterns anticipated.
For Market Incumbents: Fortify hospital formulary positioning through bundled tender structures that combine originator biologics with proton pump inhibitor volume commitments. Deepen backward integration into Moroccan fill-finish capacity to reduce import dependency exposure. Prioritize SAHPRA and SFDA regulatory relationship investment as biosimilar approval velocity accelerates substitution timelines. For New Entrants and Emerging Players: Differentiate on oral biologic delivery platforms targeting Egypt's Cairo-Alexandria corridor patient populations with needle aversion. Target Nigeria's telemedicine-integrated secondary cities as the most penetrable geography for maintenance therapy prescription channels. Pursue AMRH mutual recognition pathway pre-positioning to capture consolidated East and West African registration advantages. For Investors and Strategic Acquirers: Regional generic specialists with EDA-approved manufacturing facilities and established North African distribution infrastructure represent priority acquisition targets. Long-term viability hinges on biosimilar portfolio breadth and cold chain logistics control. Watch SFDA-EU MDR convergence timelines as the signal indicating accelerated documentation burden for European-originated products.| Strategic Initiative | Industry Significance |
|---|---|
| Biologic Biosimilar Registration | SFDA accelerated pathways compress infliximab time-to-market across Gulf hospital networks. |
| Manufacturing Localization | Morocco fill-finish investments reduce Maghreb import dependency and tender pricing exposure. |
| Oral Biologic Formulation | Nanoparticle ileal release pilots in South African research hospitals miniaturize administration barriers. |
| Cold Chain Infrastructure | Temperature-controlled distribution partnerships expand biologic reach beyond South African urban centers. |
| Telemedicine Integration | Remote gastroenterology consultations in Nigeria create prescription channels for maintenance therapies. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA registration databases, EDA approval records, SAHPRA biosimilar guidance documents, and Gulf hospital procurement tender archives. Primary interviews engaged regulatory affairs leads at multinational pharmaceutical firms, formulary directors within Dubai Health Authority and Abu Dhabi Health Services, hospital procurement managers across Saudi National Unified Procurement Company networks, and pharmacy chain category buyers in Egypt's Cairo-Alexandria corridor. Bottom-up patient volume modeling and top-down pharmaceutical spending allocation triangulate market sizing across the analysis window.
Segmentation dimensions modeled include product type, therapy area, delivery mode, end user, and regional regulatory cluster. Volume and value outputs reflect reconciliation between prescription volume data from pharmacy audit services and hospital procurement expenditure records. CAGRs were derived from trend extrapolation of biologic penetration rates and generic substitution velocity. Industry-specific forecast inputs incorporate SFDA biosimilar approval timelines and AMRH mutual recognition implementation progress.
The analysis sits within stated boundaries; outcomes outside sustained SFDA regulatory streamlining, stable cold chain infrastructure investment, and continued Gulf hospital procurement consolidation would require recalibration. Forecasts reflect documented assumptions regarding biosimilar uptake curves and telemedicine diagnostic expansion. Specific risk factors include AMRH harmonization delays, EU MDR documentation burden escalation, and Sub-Saharan African cold chain capacity shortfalls. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
B7-H3 Antibody Market