
 Lactated Ringers Injection Market | 2026-2036
Lactated Ringers Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Lactated Ringers Injection Market Insights
Aftermarket service revenue for infusion pump maintenance and calibration is reshaping margin distribution across the Lactated Ringers value chain. Baxter International leverages its installed base of automated compounding devices to sustain recurring service contracts. Fresenius Kabi anchors European hospital supply through centralized manufacturing scale. B. Braun Melsungen competes on integrated delivery systems that bundle fluid bags with proprietary infusion hardware.
Lactated Ringers injection is a sterile, nonpyrogenic solution containing sodium chloride, sodium lactate, potassium chloride, and calcium chloride in water for injection, with an osmolarity of approximately 273 mOsm per liter and a pH of 6.0 to 7.5, manufactured via aseptic processing in flexible plastic containers or glass bottles for intravenous administration to restore electrolyte balance and expand plasma volume during hypovolemia or metabolic acidosis. The fluid resuscitation product type dominates hospital purchasing due to perioperative protocol standardization, while home healthcare end users represent the fastest-expanding delivery channel as ambulatory infusion gains reimbursement traction. Burn care applications command premium pricing relative to dehydration treatment owing to higher electrolyte monitoring intensity and specialized compounding requirements.
FDA current Good Manufacturing Practice enforcement and USP <797> sterile compounding revisions govern US production standards, while EMA's GMP guidelines and the EU Medical Device Regulation shape European market access for combination infusion products. China's NMPA implements GB standards for large-volume parenterals that foreign manufacturers must navigate through local partnership or direct registration pathways. Stakeholders should monitor how evolving pharmacopeial harmonization between FDA, EMA, and NMPA affects multi-territory registration strategies and manufacturing site qualification costs.
Market Dynamics
Hospital procurement departments are consolidating IV fluid purchasing through long-term supply agreements that favor manufacturers with automated compounding capabilities and redundant sterile production sites.
Growth Catalysts
- Surgical volume rebound:Elective procedure backlogs in the United States, China, and Germany are expanding perioperative fluid resuscitation requirements. Health systems are rebuilding buffer inventories to prevent the shortages experienced during recent supply disruptions.
- USP <797> compounding standards:Updated sterile compounding requirements are accelerating outsourcing of IV solution preparation to FDA-registered manufacturers with validated aseptic processing lines.
- Home infusion infrastructure:Medicare reimbursement expansion for ambulatory infusion services is extending Lactated Ringers administration beyond acute care settings into skilled nursing and home healthcare channels.
Market Restraints
- API supply concentration:Sodium lactate and electrolyte raw material production clusters in China create single-source dependency risks for multinational manufacturers.
- Energy-intensive sterilization:Terminal steam sterilization of large-volume parenterals requires substantial natural gas input, exposing margins to European and North American energy price volatility.
- Glass-to-plastic conversion limits:Certain high-temperature sterilization protocols remain incompatible with current flexible polymer films, constraining container format innovation.
Strategic Opportunities
- Indian hospital network expansion:CDSCO streamlined registration pathways for large-volume parenterals are opening access to tertiary care construction in Maharashtra and Karnataka states.
- Burn care specialization:Custom electrolyte formulations with enhanced calcium buffering command premium positioning in specialized wound centers and trauma networks.
- Closed-system transfer devices:Integration of needle-free IV access ports with Lactated Ringers bags addresses USP <800> hazardous drug handling requirements in oncology-adjacent infusion protocols.
Industry Challenges
- Aseptic processing technician shortage:FDA and EMA qualified personnel requirements for sterile manufacturing outpace vocational training program output in multiple production regions.
- Multi-site validation complexity:Establishing equivalent manufacturing processes across FDA, EMA, and NMPA inspected facilities demands extended timeline and documentation burden.
- Legacy ERP integration:Hospital procurement systems require custom EDI mapping to receive automated compounding device telemetry and inventory signals from fluid management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactated Ringers Injection Market |
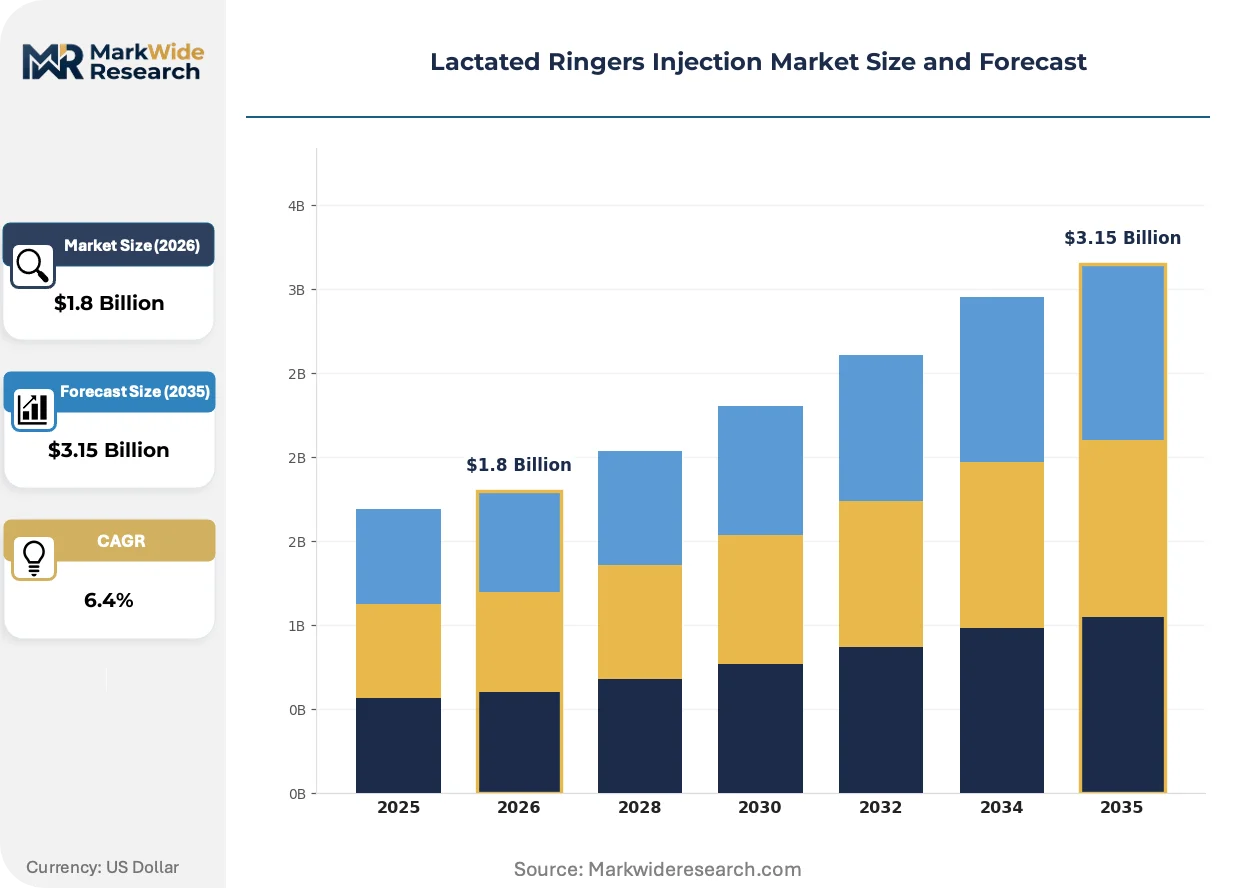
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Solution, Electolyte Replacement, Acid-Base Balancer, Fluid Resuscitation Delivery Mode: Intravenous, Injectable, Infusion Pump, Gravity End User: Hospitals, Clinics, Emergency Services, Home Healthcare Application: Surgery, Dehydration Treatment, Electrolyte Imbalance, Burn Care |
| Companies Covered | Baxter International, B. Braun Melsungen, Fresenius Kabi, ICU Medical, Becton Dickinson & Company, Otsuka Pharmaceutical, Pfizer, Hospira, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactated Ringers Injection Market Trends and Innovations
Digital integration across the IV fluid value chain is compressing order-to-delivery cycles while regulatory harmonization efforts are reshaping multi-territory manufacturing strategies.
Smart infusion pumps with embedded RFID authentication are digitizing medication safety workflows in perioperative and emergency departments. Academic medical centers in the United States are deploying these systems at scale to eliminate manual programming errors. The technology is digitizing adverse event reporting and enabling real-time utilization analytics that reshape contract negotiations.
EMA's Medical Device Regulation and FDA's evolving software-as-a-medical-device guidance are converging on cybersecurity validation requirements for connected infusion systems. Manufacturers must now submit threat modeling documentation alongside traditional 510(k) sterility data. European notified bodies are applying enhanced scrutiny to wireless communication protocols in hospital networks.
Consolidated service line agreements are bundling Lactated Ringers procurement with pump maintenance and clinical education under single-source contracts. Integrated delivery networks in Texas and Florida are displacing fragmented purchasing through centralized pharmacy governance. This concentration is most visible in US health systems pursuing Medicare ACO performance incentives.
Lactated Ringers Injection Market Segmentation
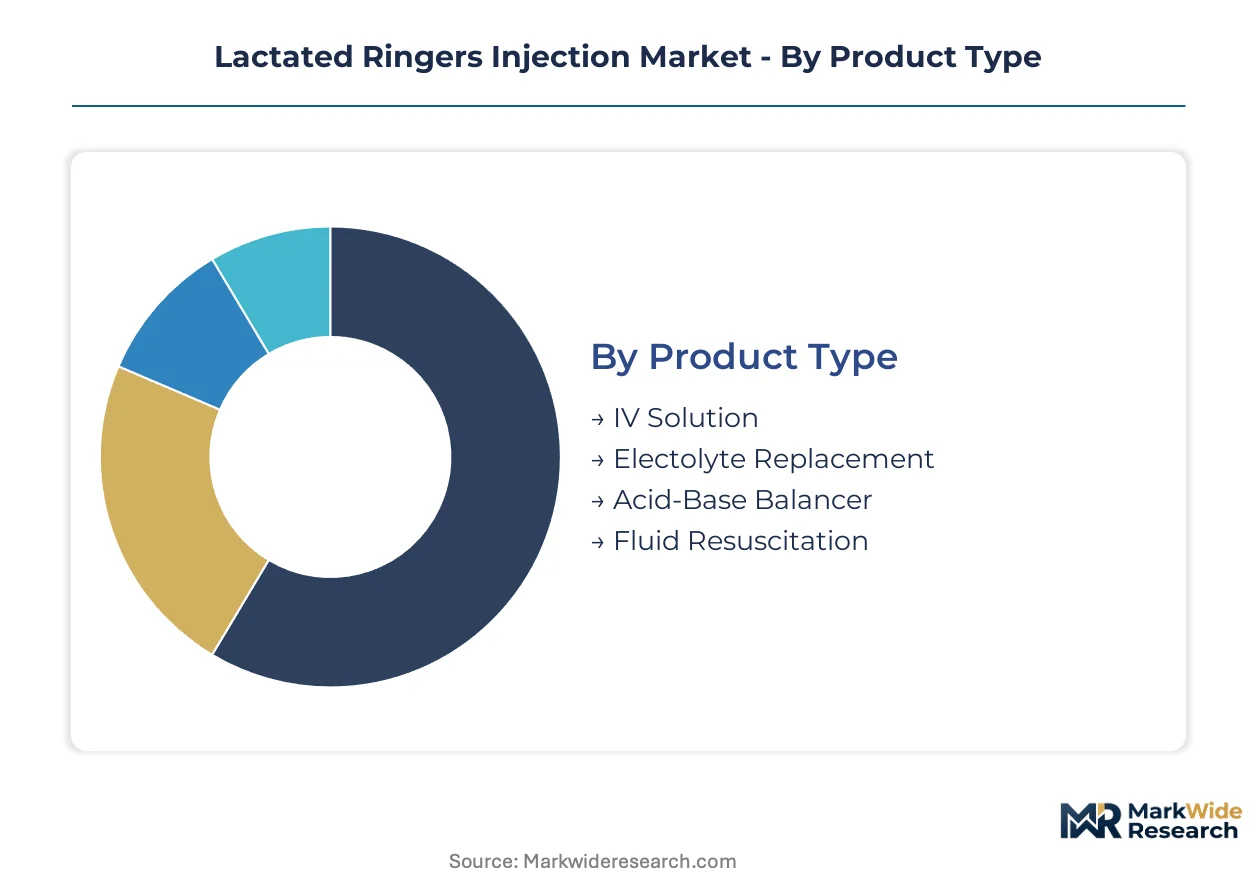
Segmentation in the Lactated Ringers Injection Market reveals how clinical use cases, delivery infrastructure, and care settings fragment purchasing power across distinct technical and commercial requirements. Manufacturers must align sterile production capacity and container formats against these diverging demand profiles.
Product Type:
Cost tier differentiation separates commodity formulations from specialized electrolyte blends, with pricing power concentrated in products requiring custom compounding validation.
- Fluid Resuscitation:Large-volume parenterals in 500ml to 1000ml flexible containers dominate perioperative protocols. Hospital systems in the United States and Germany standardize procurement around this format for surgical volume resuscitation, with USP <797> compliance driving outsourcing to FDA-registered manufacturers.
- IV Solution:Standard isotonic preparations serve general hydration and electrolyte maintenance across emergency departments and medical floors. Demand concentrates in China and India where tertiary care expansion requires scalable, low-cost supply.
- Electrolyte Replacement:Modified calcium and potassium ratios target specific metabolic disturbances in critical care settings.
- Acid-Base Balancer:Sodium lactate-buffered formulations address metabolic acidosis in trauma and sepsis protocols.
Fluid Resuscitation commands the established base. The steepest expansion runs through Acid-Base Balancer applications in specialized trauma networks.
Delivery Mode:
Application intensity determines hardware integration depth, with automated systems capturing premium positioning in high-acuity environments.
- Infusion Pump:Programmable volumetric delivery with embedded safety software dominates perioperative and ICU settings. Academic medical centers in Texas and Florida deploy smart pumps with RFID authentication to eliminate manual programming errors, with EMA MDR and FDA SaMD guidance tightening cybersecurity validation requirements.
- Gravity:Passive drip administration persists in resource-constrained settings and emergency field medicine. Rural hospitals in India and Southeast Asia rely on this format where electrical infrastructure and technical support remain limited.
- Intravenous:Direct venous access via peripheral or central lines remains the standard administration route.
- Injectable:Push-dose delivery in emergency and anesthesia protocols requires precise bolus control.
Gravity administration retains volume leadership in emerging markets. Infusion Pump integration is climbing the fastest in Medicare ACO-aligned US health systems.
End User:
Customer type segmentation maps reimbursement structure against care intensity, with ambulatory channels disrupting traditional hospital-centric supply relationships.
- Hospitals:Integrated delivery networks consolidate purchasing through pharmacy governance and long-term supply agreements. Centralized procurement in the United States favors manufacturers with redundant sterile production sites and automated compounding capabilities.
- Home Healthcare:Skilled nursing and patient-directed infusion represents the most dynamic channel expansion. Medicare reimbursement expansion for ambulatory services extends Lactated Ringers administration beyond acute care, with Texas and Florida IDNs pioneering consolidated service line contracts.
- Clinics:Outpatient surgical centers and infusion suites require flexible volume commitments.
- Emergency Services:Pre-hospital and mobile intensive care units demand ruggedized packaging and rapid deployment formats.
Hospitals anchor procurement volume concentration. Home Healthcare is gaining share fastest as reimbursement policy reshapes site-of-care economics.
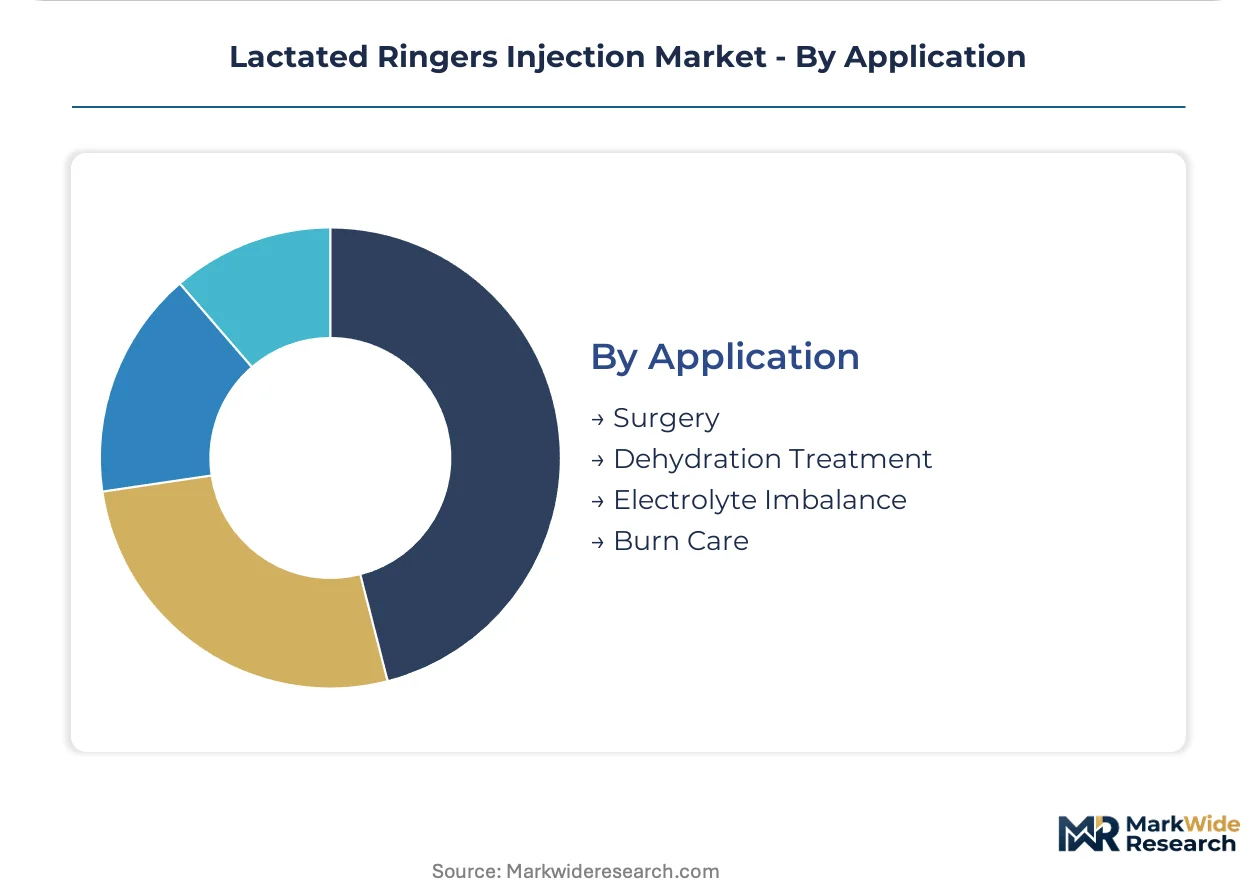
Application:
Volume scale and clinical specialization diverge sharply across use cases, with trauma and burn protocols commanding formulation premiums over routine rehydration.
- Burn Care:Custom electrolyte formulations with enhanced calcium buffering and intensive monitoring requirements support specialized wound centers. Parkland formula resuscitation protocols in US trauma networks and European burn centers sustain premium positioning relative to standard dehydration treatment.
- Surgery:Perioperative fluid management protocols standardize around Lactated Ringers for hypovolemia correction. Elective procedure backlogs in Germany and China are expanding buffer inventory requirements as health systems rebuild supply resilience.
- Dehydration Treatment:Routine rehydration in emergency departments and general medicine represents high-volume, price-sensitive demand.
- Electrolyte Imbalance:Targeted metabolic correction in renal and endocrine populations requires precise laboratory monitoring.
Surgery maintains the largest installed demand base. Burn Care is expanding most quickly as specialized trauma network construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement in India and Southeast Asia operates on razor-thin margins where gravity-fed administration dominates, while US and German health systems absorb premium pricing for smart pump integration and USP <797> compliance without volume elasticity.
United States
Elective surgical backlogs at Texas and Florida integrated delivery networks are rebuilding buffer inventories for perioperative fluid resuscitation. FDA enforcement of updated USP <797> sterile compounding standards accelerates outsourcing to manufacturers with validated aseptic processing lines. Academic medical centers in Houston and Miami deploy smart infusion pumps with RFID authentication to eliminate manual programming errors.
Germany
Hospital construction in Bavaria and North Rhine-Westphalia expands centralized pharmacy governance for large-volume parenteral procurement. EMA Medical Device Regulation and EU GMP guidelines shape manufacturing site qualification for combination infusion products. The Frankfurt-Rhine-Main medical technology cluster anchors European supply chain coordination for automated compounding devices.
China
Tertiary care expansion in Sichuan-Chongqing and Yangtze River Delta provinces drives scalable demand for standard IV solutions. NMPA implements GB standards for large-volume parenterals that foreign manufacturers navigate through local partnership or direct registration pathways. Shanghai-based production facilities serve as qualification hubs for multi-territory pharmacopeial harmonization.
India
CDSCO streamlined registration pathways open access to Maharashtra and Karnataka state hospital networks where gravity administration persists in rural infrastructure. Centralized procurement at Mumbai and Bangalore tertiary centers favors low-cost supply with flexible volume commitments. The country's national pharmaceutical regulator tightens sterile manufacturing inspections alongside capacity expansion.
Japan
Aging demographics at Tokyo and Osaka metropolitan hospitals sustain demand for home healthcare infusion channels. PMDA guidelines for large-volume parenterals align with international pharmacopeial standards to reduce multi-site validation burden. The Kanto region's medical device cluster integrates closed-system transfer devices with fluid management platforms.
Lactated Ringers Injection Market Competitive Landscape
Capability concentration sits with specialized aseptic processors; scale advantage sits with diversified hospital supply conglomerates. The market structure tiers across three segments: integrated delivery system bundlers, standalone sterile manufacturers, and regional infusion specialists. Dominant competitive moves include strategic partnerships for automated compounding technology licensing and capacity expansion into redundant FDA-EMA-NMPA inspected production sites.
Within the integrated systems tier, Baxter International and B. Braun Melsungen exemplify manufacturers leveraging installed bases of infusion hardware to sustain recurring service contracts and long-term supply agreements. Fresenius Kabi occupies a position anchoring European hospital procurement through centralized manufacturing scale. These three companies represent distinct archetypes: the device-fluid bundler, the continental supply anchor, and the integrated delivery network partner.
| Leading Market Players |
|---|
| Baxter International |
| B. Braun Melsungen |
| Fresenius Kabi |
| ICU Medical |
| Becton Dickinson & Company |
| Otsuka Pharmaceutical |
| Pfizer |
| Hospira |
| Grifols |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European sterile manufacturing facilities is driving contract renegotiations and selective price premiums for USP <797> validated production slots. Manufacturers with redundant FDA-EMA inspected sites command pricing leverage as hospital procurement teams prioritize supply security over unit cost minimization.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement, with three-year supply contracts locking in volume commitments against indexed electrolyte raw material costs. Price differentiation separates premium formulations with enhanced calcium buffering from standard resuscitation fluids, while Medicare ACO-aligned health systems in Texas and Florida show lowest price sensitivity due to bundled reimbursement structures. Cost compression in standard IV solutions intensifies as Indian and Chinese manufacturers expand export capacity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as hospital procurement departments conserve working capital. Supply concentrates in the United States, Germany, and China where FDA, EMA, and NMPA inspected facilities anchor multi-territory qualification strategies. Sodium lactate and electrolyte APIs draw from concentrated Chinese chemical manufacturing clusters, creating single-source vulnerability exposure. Distribution runs through hospital GPO contracts and direct IDN agreements rather than wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA 510(k) sterility validation and USP <797> compliance create formidable switching costs for hospital procurement teams.
For Market Incumbents: Build certification moats through simultaneous FDA, EMA, and NMPA site qualification to capture multi-territory contract bundling. Incumbents should expand automated compounding device fleets in Texas and Florida IDNs to lock in recurring service revenue. Capacity addition in Bavaria and North Rhine-Westphalia addresses European supply security demand while insulating margins from energy price volatility exposure. For New Entrants and Emerging Players: Mid-market hospital networks in Maharashtra and Karnataka states represent the most penetrable entry point given CDSCO streamlined registration and gravity-fed infrastructure requirements. Burn care specialization with custom electrolyte formulations offers premium positioning away from commoditized resuscitation fluids. Partnership with established infusion pump OEMs accelerates hospital system access without proprietary hardware development. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated compounding technology segments as cybersecurity validation requirements expand under FDA SaMD guidance. Targets with redundant sterile production sites and validated aseptic processing lines offer defensive positioning against supply disruption premiums. Watch for USP <797> enforcement acceleration as the signal indicating outsourcing demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Redundant Multi-Regulator Site Qualification | Simultaneous FDA, EMA, and NMPA inspection enables single-source contracting across hospital networks. |
| Automated Compounding Device Fleet Expansion | Installed base of smart pumps with RFID authentication generates recurring service revenue and supply lock-in. |
| Burn Care Formulation Specialization | Custom calcium-buffered electrolyte blends command premium positioning in Parkland protocol trauma centers. |
| Closed-System Transfer Device Integration | Needle-free IV access ports address USP <800> requirements in oncology-adjacent infusion protocols. |
| Home Healthcare Channel Development | Medicare reimbursement expansion for ambulatory infusion extends addressable market beyond acute care settings. |
Research Methodology
Operator-level perspectives from hospital pharmacy directors, GPO contracts managers, aseptic processing technicians, and biomedical engineers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EMA GMP inspection records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up facility capacity modeling and top-down health system expenditure analysis provided cross-verification.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation modeling across fluid resuscitation product types, infusion pump versus gravity delivery modes, and hospital versus home healthcare end users. CAGRs derived from surgical volume trajectories, inventory rebuild patterns, and reimbursement policy evolution. Energy cost pass-through assumptions and raw material indexation clauses informed margin compression sensitivity.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, electrolyte commodity costs, or hospital capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and pharmacopeial harmonization progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market