
 Pipeline Pigging Equipment Market | 2026-2036
Pipeline Pigging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Pigging Equipment Market Analytics
The US Gulf Coast is rewriting capital allocation patterns across the pipeline services sector. Baker Hughes Company leverages its turbomachinery heritage to anchor intelligent pigging R&D in Houston. T.D. Williamson, Inc. sustains manufacturing scale through dedicated fabrication facilities in Oklahoma and Norway. NDT Global FZE competes on ultrasonic technology leadership for crack detection in liquid pipelines.
Pipeline pigging equipment comprises self-propelled or flow-driven devices inserted into pipelines to clean debris, inspect wall integrity, or separate product batches, typically constructed from polyurethane bodies with steel mandrels and instrumented sensor arrays rated for pressures exceeding 100 bar. Intelligent pigs embed magnetic flux leakage or ultrasonic transducers to detect metal loss and geometric deformation without pipeline shutdown. Cleaning pigs and foam pigs occupy the highest unit-volume tier, while intelligent pigs command the dominant margin pool due to embedded electronics and data analytics requirements. Magnetic and ultrasonic technologies lead the inspection segment, with ultrasonic methods gaining share in crack-sensitive environments.
The US PHMSA and Canada's National Energy Board enforce mandatory inline inspection intervals for pipelines in high-consequence areas, directly shaping replacement demand for certified equipment. The EU F-Gas Regulation and REACH compliance standards govern seal and coating materials used in European pigging systems, raising material qualification barriers for non-European suppliers. Stakeholders must monitor evolving integrity management rules and sensor miniaturization roadmaps to align product portfolios with operator procurement criteria.
Market Dynamics
Regulatory mandates for inline inspection are compressing replacement cycles for intelligent pigging systems across hazardous liquid corridors. Midstream operators face simultaneous pressure from aging infrastructure integrity requirements and sensor miniaturization roadmaps that obsolete equipment faster than historical depreciation schedules.
Growth Catalysts
- PHMSA Inspection Mandates:The US Pipeline and Hazardous Materials Safety Administration enforces mandatory inline inspection intervals for pipelines in high-consequence areas, creating sustained equipment replacement demand.
- Shale Corridor Expansion:North American midstream operators are extending smart pigging programs across Permian and Bakken production basins to monitor corrosion in high-throughput lines.
- Ultrasonic Crack Detection:Advanced ultrasonic transducer arrays now enable geometric deformation sensing in liquid pipelines previously requiring magnetic flux leakage methods alone.
Market Restraints
- Specialized Polyurethane Supply:Seal and body material formulations face qualification barriers under EU REACH and F-Gas Regulation compliance standards, limiting qualified European suppliers.
- Embedded Electronics Cost Concentration:Intelligent pig sensor arrays and data analytics modules concentrate manufacturing in Germany and Japan, exposing buyers to currency and logistics volatility.
- Pressure Rating Limitations:Conventional polyurethane-steel mandrel construction faces technical ceilings above 100 bar in sour gas service, restricting addressable pipeline segments.
Strategic Opportunities
- Alberta Oil Sands Infrastructure:Canadian thermal extraction corridors require specialized high-temperature pigging solutions for bitumen transport lines with elevated viscosity challenges.
- EU Green Deal Alignment:The European Green Deal's methane reduction targets create inspection equipment demand for previously unmonitored gathering lines and distribution networks.
- AI-Enabled Predictive Analytics:Convergence of inline sensor data with machine learning platforms is digitizing maintenance scheduling from calendar-based to condition-based protocols.
Industry Challenges
- NDE Technician Scarcity:Magnetic flux leakage and ultrasonic data interpretation requires certified non-destructive examination specialists, with training pipelines failing to match retirement rates.
- Multi-Standard Certification Timelines:Equipment must simultaneously satisfy API, ASME, and ISO integrity management standards, extending product qualification cycles by 18-24 months.
- Legacy Pipeline Compatibility:Pre-1980s pipeline geometries and valve configurations obstruct intelligent pig passage, requiring costly line modification or alternative inspection methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Pigging Equipment Market |
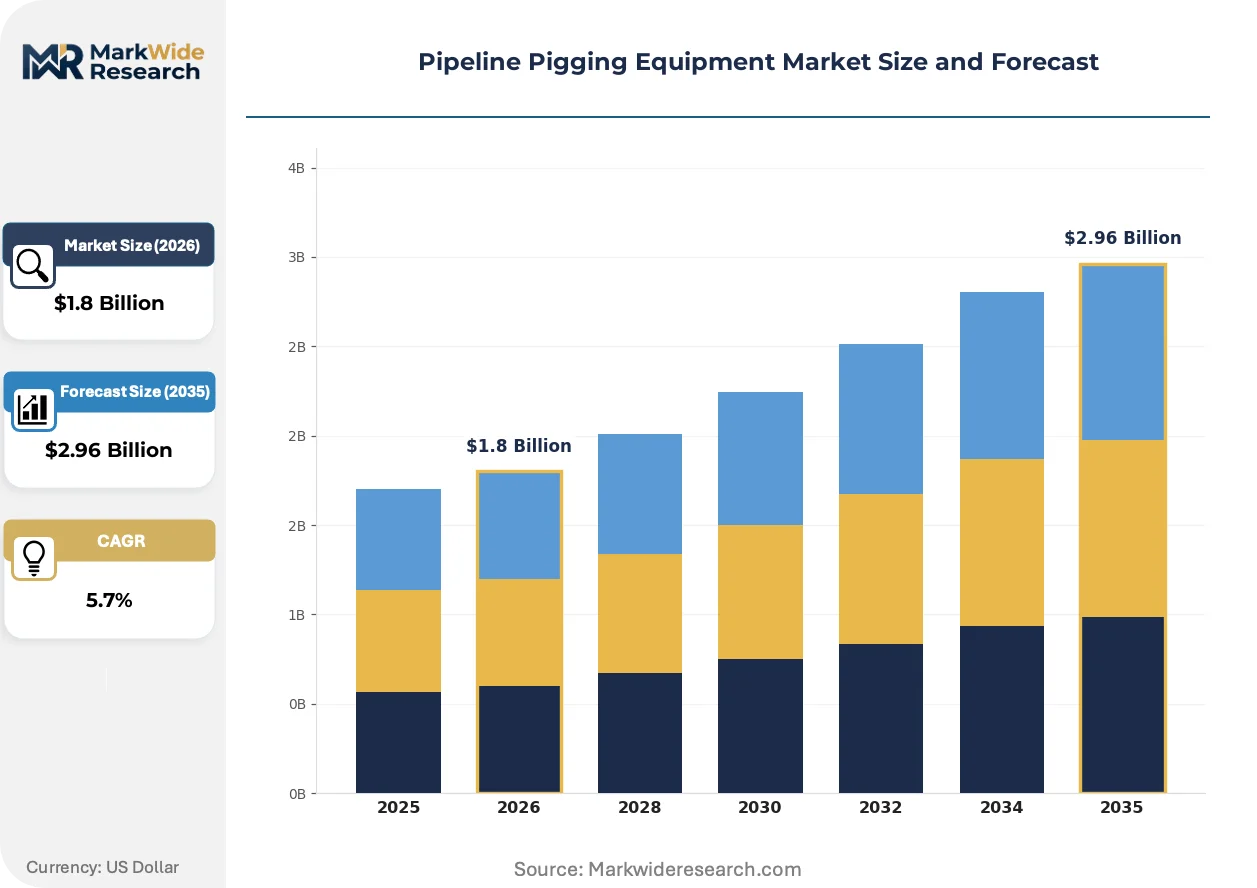
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intelligent Pigs, Cleaning Pigs, Foam Pigs, Coprod Pigs End User: Oil & Gas, Chemical, Water Treatment, Food & Beverage Application: Maintenance, Inspection, Cleaning, Monitoring Technology: Magnetic, Ultrasonic, Mechanical, Hydraulic |
| Companies Covered | 3P Services GmbH & Co. KG, Russell NDE Systems Inc., Baker Hughes Company, NDT Global FZE, Pigs Unlimited International, T.D. Williamson, Inc., Dacon Inspection Services Co. Ltd., Quest Integrity Group, Inc., LIN SCAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Pigging Equipment Market Evolving Landscape
Sensor fusion architectures and edge computing capabilities are transforming pigging equipment from passive inspection tools into real-time pipeline monitoring platforms. Equipment manufacturers now compete on data throughput and analytics integration rather than mechanical reliability alone.
Magnetic flux leakage technology is digitizing wall-thickness mapping through high-density sensor arrays that transmit sub-millimeter resolution data to surface acquisition systems. Offshore pipeline operators in the US Gulf of Mexico are deploying these systems at twice historical frequencies to satisfy insurer requirements. The technology is digitizing corrosion assessment from episodic campaigns to continuous integrity monitoring.
REACH and F-Gas Regulation compliance is reshaping European procurement specifications for seal elastomers and coating chemistries. Equipment vendors must now qualify alternative formulations that maintain pressure ratings while eliminating restricted fluorinated compounds. German and Norwegian pipeline operators are advancing the strictest material certification requirements, forcing suppliers to maintain parallel European and North American product lines.
Midstream buyers are consolidating vendor relationships around integrated service contracts that bundle equipment supply, run execution, and data interpretation. Texas-based operators now prefer single-source accountability over discrete equipment purchases. This consolidation is most visible in the Permian Basin, where independent producers have merged procurement functions to match supermajor scale.
Pipeline Pigging Equipment Market Segmentation
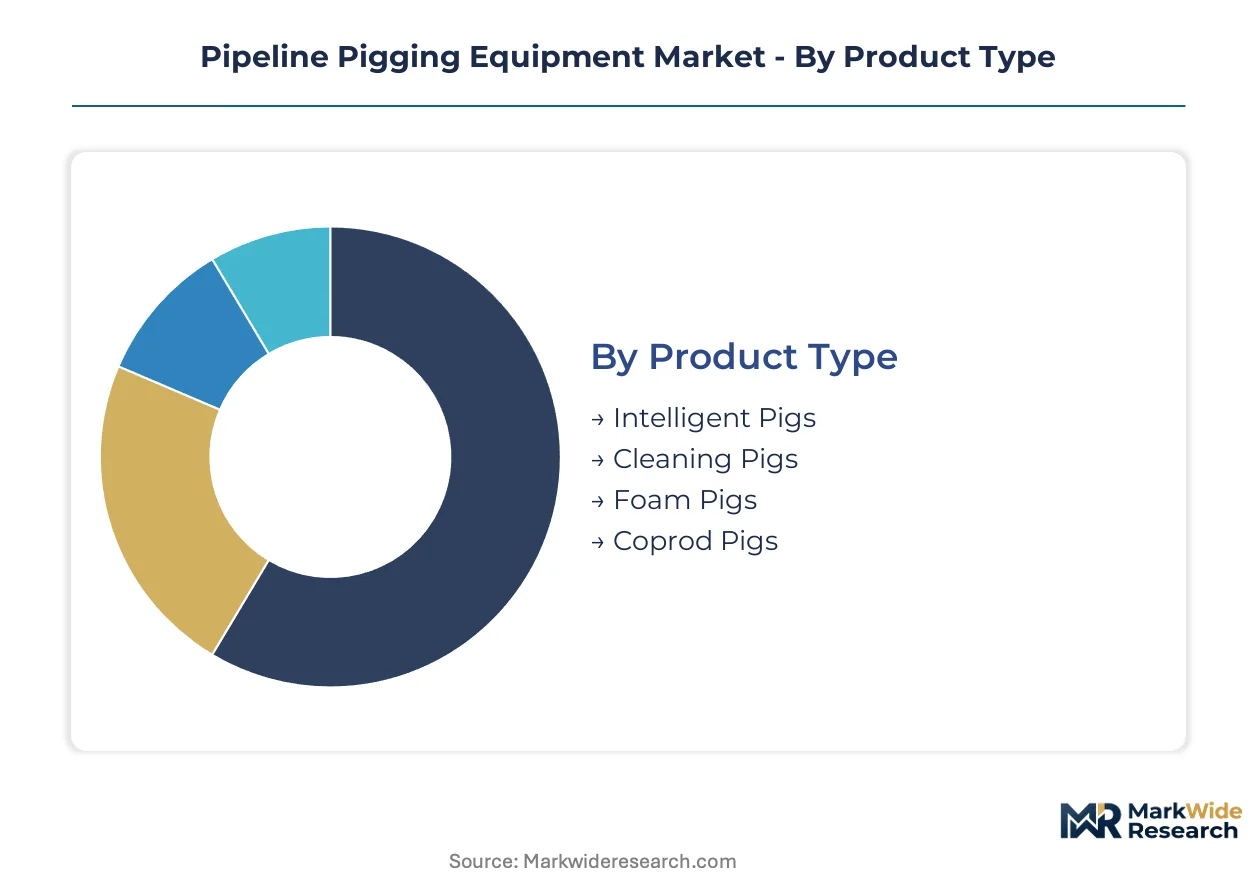
Equipment segmentation in pipeline pigging reveals divergent margin architectures across product tiers. Intelligent pigs command premium pricing through embedded sensor arrays and data analytics, while cleaning pigs generate volume through consumable replacement cycles. Understanding these segment economics shapes procurement strategy and vendor selection for midstream operators.
Product Type:
After-sales service intensity varies dramatically across pig categories, with intelligent pigs requiring continuous calibration support and cleaning pigs demanding rapid field replacement logistics.
- Intelligent Pigs:Self-propelled devices integrate magnetic flux leakage or ultrasonic transducer arrays for wall-thickness mapping without pipeline shutdown. Demand concentrates in Texas and Alberta shale corridors where PHMSA mandates compress replacement cycles for hazardous liquid lines.
- Cleaning Pigs:Polyurethane-bodied flow-driven devices remove debris and wax deposits through mechanical scraping action. Water treatment utilities in the US Midwest drive steady demand for scheduled maintenance programs.
- Foam Pigs:Lightweight cylindrical foam bodies navigate irregular pipeline geometries for batch separation and light debris removal.
- Coprod Pigs:Composite-bodied designs combine scraping durability with reduced weight for extended offshore pipeline runs.
Intelligent pigs hold the largest share; momentum sits with cleaning pigs as water infrastructure investment accelerates.
End User:
Cost tier differentiation separates capital-intensive inspection programs from routine maintenance budgets across verticals.
- Oil & Gas:Midstream operators deploy the full equipment spectrum from foam pigs for batching to intelligent pigs for corrosion monitoring. The US Gulf Coast and Alberta oil sands anchor procurement volume through pipeline density and regulatory pressure.
- Chemical:Process manufacturers prioritize cleaning pigs for product purity compliance between batch transitions.
- Water Treatment:Municipal utilities in the US Southwest drive demand for inspection pigs as aging distribution networks face replacement timelines.
- Food & Beverage:Hygienic pipeline standards in dairy and beverage processing require specialized elastomer formulations.
Oil & gas dominates procurement value; water treatment is expanding most quickly as infrastructure legislation funds distribution system upgrades.
Application:
Volume concentration favors cleaning operations while margin pools concentrate in inspection services requiring certified data interpretation.
- Maintenance:Scheduled pigging programs prevent wax buildup and corrosion initiation in crude oil trunk lines. Canadian thermal extraction corridors require specialized high-temperature protocols for bitumen viscosity management.
- Inspection:Inline assessment generates the dominant service revenue through magnetic flux leakage and ultrasonic data analytics.
- Cleaning:Debris removal and wall conditioning represent the highest unit-volume deployment across all pipeline classes.
- Monitoring:Continuous sensor fusion architectures are digitizing episodic campaigns into real-time integrity platforms.
Cleaning commands the highest unit volume; inspection generates the steepest margin expansion.
Technology:
Technology maturity curves separate established mechanical methods from emerging sensor fusion architectures.
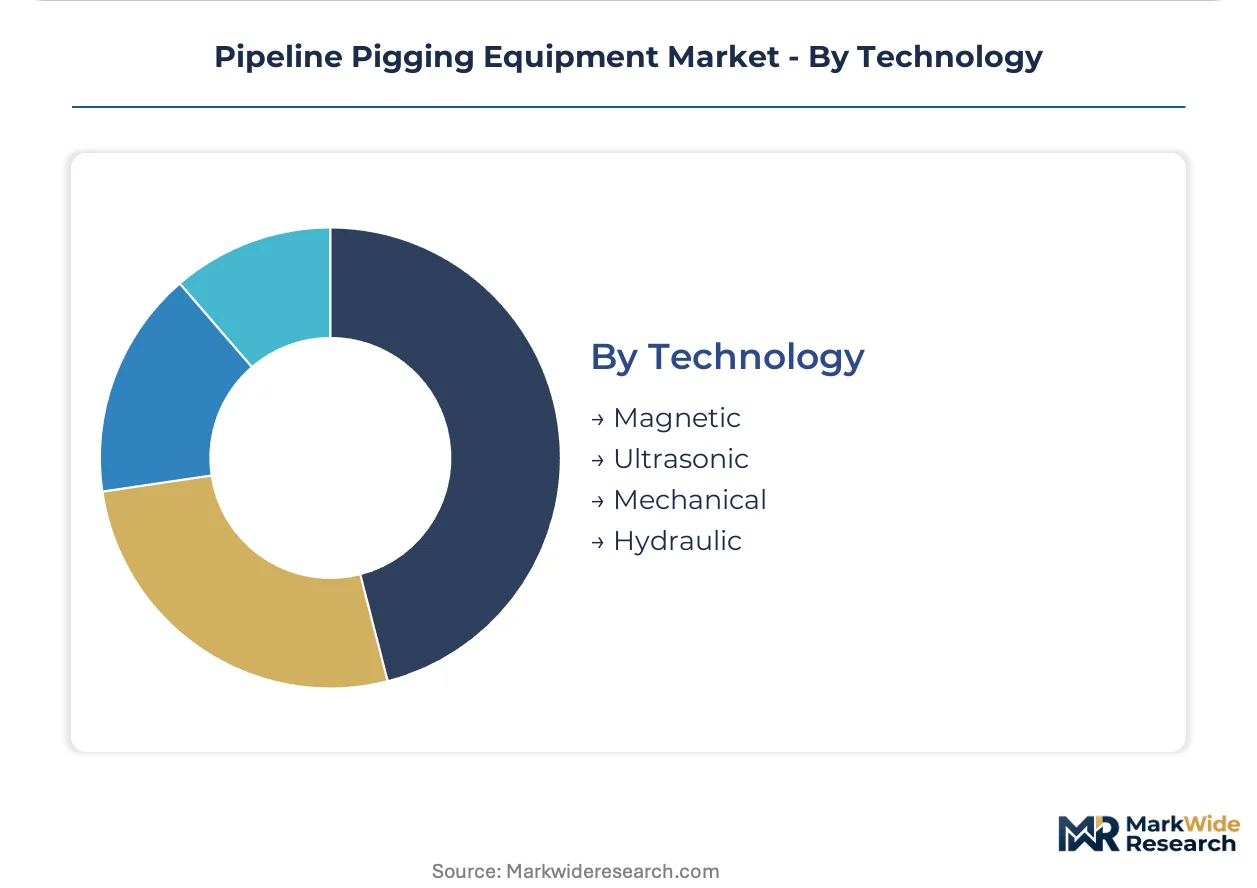
- Magnetic:Magnetic flux leakage systems digitize wall-thickness mapping through high-density sensor arrays transmitting sub-millimeter resolution data. Offshore operators in the US Gulf of Mexico deploy at elevated frequencies to satisfy insurer requirements.
- Ultrasonic:Advanced transducer arrays now enable crack detection in liquid pipelines previously requiring magnetic methods alone.
- Mechanical:Spring-loaded disc and cup designs provide reliable scraping action without electronic complexity.
- Hydraulic:Pressure-driven propulsion suits short-run applications in food processing and chemical batching.
Magnetic technology anchors current deployment; ultrasonic methods are gaining share fastest in crack-sensitive environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network anchors United States demand for intelligent pigging systems, with trunk line density creating sustained equipment replacement cycles across Texas and New Mexico corridors.
United States
The PHMSA mandates inline inspection intervals for hazardous liquid pipelines in high-consequence areas, compressing replacement cycles for certified intelligent pigs. Midstream operators in Texas deploy smart pigging programs across Permian and Bakken production basins to monitor corrosion in high-throughput lines. Houston anchors intelligent pigging R&D through turbomachinery heritage and fabrication scale.
Canada
The National Energy Board enforces integrity management standards for oil sands transport infrastructure, driving specialized high-temperature pigging demand. Alberta thermal extraction corridors require bitumen-specific solutions for elevated viscosity challenges. Calgary and Edmonton clusters concentrate procurement for Canadian midstream operators managing aging pipeline networks.
Germany
The EU F-Gas Regulation and REACH compliance standards govern seal and coating materials, raising qualification barriers for pigging system suppliers. German pipeline operators advance strictest material certification requirements for alternative elastomer formulations. The Ruhr industrial region maintains inspection equipment demand through chemical processing and refined product distribution networks.
Norway
Offshore pipeline operators in the North Sea deploy magnetic flux leakage systems at elevated frequencies to satisfy insurer requirements for subsea integrity. Norwegian material standards influence European procurement specifications for pressure-rated polyurethane-steel mandrel construction. Stavanger anchors fabrication facilities serving North Sea midstream infrastructure.
Saudi Arabia
The Master Gas System expansion drives demand for inspection equipment across high-pressure sour gas service corridors. Saudi Aramco procurement standards emphasize API and ASME certification for intelligent pigging systems in hydrocarbon transport networks. The Eastern Province concentrates pipeline density and maintenance program investment.
Pipeline Pigging Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor arrays, polyurethane bodies, and calibration services. The vendor base separates into consolidated equipment manufacturers with integrated service capabilities and fragmented regional fabricators focused on cleaning pig production. Three archetypes dominate: turbomachinery heritage conglomerates with R&D scale, specialized inspection technology developers with ultrasonic or magnetic sensor expertise, and regional fabrication houses with rapid field replacement logistics. Competitive moves concentrate on strategic partnerships bundling equipment supply with run execution and data interpretation, plus portfolio diversification into AI-enabled predictive analytics platforms.
Among Germany-based platform integrators, 3P Services GmbH & Co. KG exemplifies the European system-tier archetype with integrated service bundling. T.D. Williamson, Inc. and Baker Hughes Company anchor the North American intelligent pigging segment, representing turbomachinery heritage and fabrication scale respectively. NDT Global FZE occupies a position within the specialized inspection technology tier, with ultrasonic transducer expertise for crack-sensitive pipeline environments.
| Leading Market Players |
|---|
| 3P Services GmbH & Co. KG |
| Russell NDE Systems Inc. |
| Baker Hughes Company |
| NDT Global FZE |
| Pigs Unlimited International |
| T.D. Williamson, Inc. |
| Dacon Inspection Services Co. Ltd. |
| Quest Integrity Group, Inc. |
| LIN SCAN |
| Others |
Value Network & Pricing Analysis
Tariff exposure between Germany and Japan for embedded sensor arrays determines both pricing tier spreads and supply chain shape in the intelligent pigging segment. Buyers face currency volatility alongside REACH compliance costs that stratify equipment procurement across premium certified and standard unbundled tiers.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts for midstream operators consolidating vendor relationships. Three-tier pricing structure across premium, standard, and economy levels separates API-certified intelligent pigs with full data analytics from basic cleaning pigs and uncalibrated mechanical units. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because embedded electronics manufacturing concentrates in Germany and Japan. Municipal water utilities exhibit highest price sensitivity; offshore operators in the US Gulf of Mexico demonstrate lowest sensitivity due to insurer-mandated inspection frequencies.
Supply Chain Analysis
Tariff exposure between Germany and Japan dominates supply chain risk for sensor array procurement. Manufacturing draws from Germany for ultrasonic transducer arrays, Japan for data analytics modules, and the United States for polyurethane-steel mandrel fabrication. Raw material dependencies include specialized polyurethane formulations, high-grade steel for pressure-rated mandrels, and semiconductor components for edge computing architectures. Single-source vulnerability persists for ultrasonic crack detection sensors qualified under EU REACH standards. Distribution runs through integrated service contracts bundling equipment supply, run execution, and data interpretation rather than discrete product sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a platform-economics inflection where sensor data interoperability between operator SCADA systems and vendor analytics platforms determines competitive positioning. Equipment manufacturers must pivot from mechanical reliability competition to real-time data integration ecosystems.
For Market Incumbents: Pre-empt margin erosion in the intelligent pigging segment by deepening backward integration into sensor array manufacturing rather than sourcing from German and Japanese suppliers. Anchor fabrication scale in Houston or Calgary to reduce logistics exposure for North American shale corridor operators. Invest in API and ASME certification maintenance as regulatory timelines compress replacement cycles.
For New Entrants and Emerging Players: Build out AI-enabled predictive analytics capabilities targeting water treatment utilities in the US Southwest as the most penetrable segment. Municipal infrastructure legislation funds distribution system upgrades with less stringent certification requirements than oil and gas applications. Pursue partnership-based go-to-market models with established inspection service providers rather than direct equipment sales.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized inspection technology developers with ultrasonic or magnetic sensor expertise over pure-play fabricators. Long-term viability rests on data platform ownership rather than mechanical manufacturing scale. Watch for PHMSA mandate expansion into previously unregulated gathering lines as the inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Transforms passive inspection tools into real-time monitoring platforms for Permian Basin operators. |
| Backward Integration into Ultrasonic Transducers | Reduces currency exposure from German and Japanese sensor array suppliers for midstream vendors. |
| REACH-Compliant Elastomer Qualification | Enables European market access by eliminating restricted fluorinated compounds from seal formulations. |
| Integrated Service Contract Bundling | Matches Texas-based operator preference for single-source accountability over discrete equipment purchases. |
| AI-Enabled Predictive Analytics Platform | Digitizes maintenance scheduling from calendar-based to condition-based protocols for Alberta oil sands corridors. |
Research Methodology
Cross-validation between regulatory filing analysis and equipment procurement databases anchors the qualitative findings in this study. Primary interviews with pipeline integrity managers, PHMSA compliance officers, midstream procurement directors, and NDE technician training program administrators combined with secondary validation from PHMSA incident reports, EPA pipeline safety databases, API standards documentation, and Canadian National Energy Board filings. Bottom-up equipment shipment analysis and top-down midstream capital expenditure triangulation established market sizing boundaries.
Calibration against historical replacement cycle data and regulatory mandate implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use vertical, application purpose, and technology platform. CAGRs derived from equipment replacement frequency analysis and pipeline mileage expansion in shale corridors. Industry-specific forecast inputs incorporated PHMSA inspection interval mandates and sensor miniaturization roadmaps from turbomachinery R&D programs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native analytics entrants or consolidated supermajor procurement functions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Europe Valves Market
Valves
Leak Detection Market
Valves
GCC and MENA Valves Market
Valves
North America Valves Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Cryogenic Valve Market
Valves
Mechanical Shaft Seal Market
Valves
Compressor Valves Market
Valves
Backflow Preventers Market
Valves
Mobile Hydraulic Valves Market
Valves
Stainless Steel Valve Tag Market
Valves
Three Way Ball Valve Market
Valves
Refrigeration Valves Market
Valves
Fluid Transfer Solutions Market
Valves
Thermal Power Valve Market
Valves
Electronic Expansion Valves Market