
 Middle East and Africa Electro Hydraulic Servo Valve Market | 2026-2036
Middle East and Africa Electro Hydraulic Servo Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Electro Hydraulic Servo Valve Market Foresight
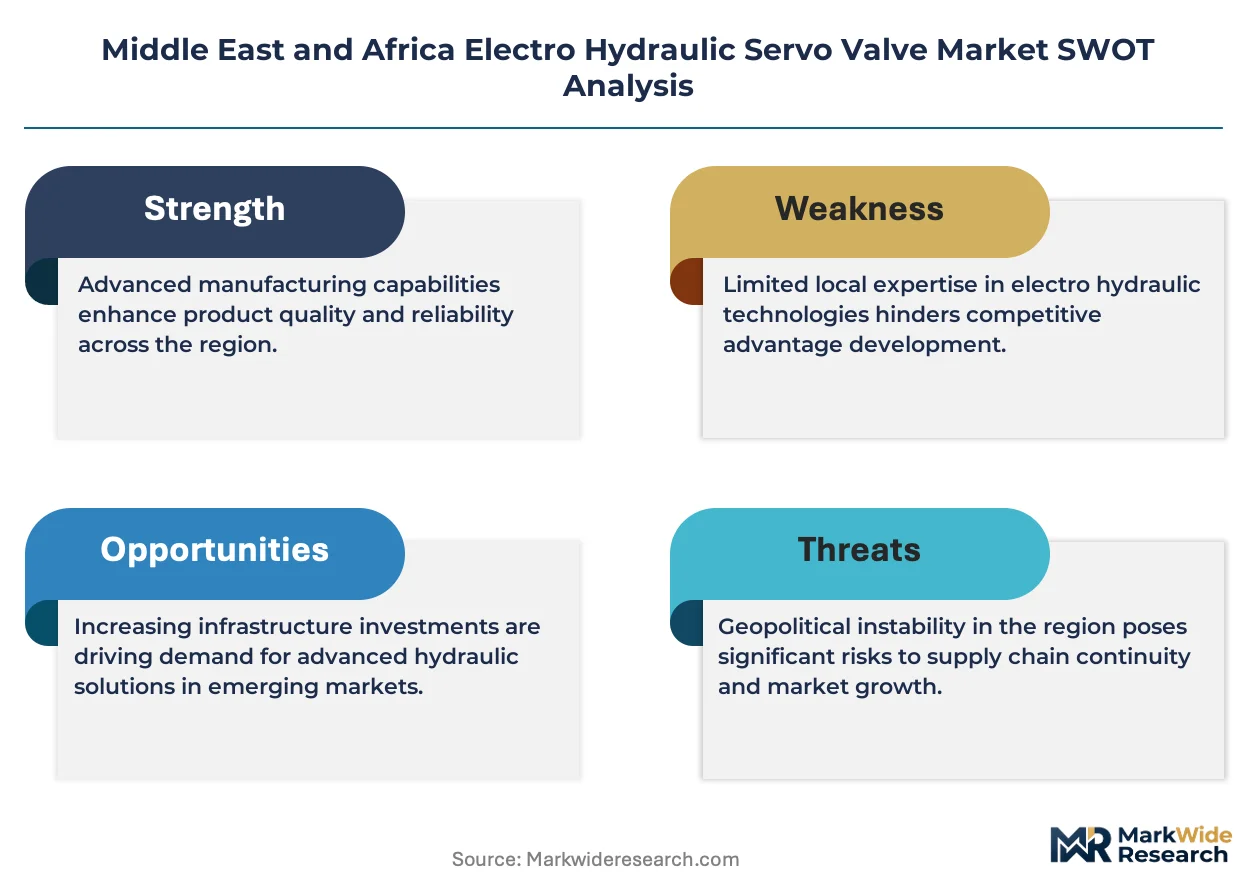
Defense and aerospace contractors are redrawing procurement patterns for electro hydraulic servo valves across the Middle East and Africa. Moog Inc. leverages its legacy in flight control actuation to anchor premium positioning in regional aerospace programs. Parker Hannifin Corporation sustains manufacturing scale advantages through localized distribution hubs serving Gulf industrial clusters. Bosch Rexroth AG competes on digital control integration, embedding smart diagnostics into valve architectures for predictive maintenance workflows.
An electro hydraulic servo valve converts low-power electrical signals into precise hydraulic flow and pressure modulation, typically operating with response times below five milliseconds and hysteresis under 0.5 percent for closed-loop positioning. These devices govern actuator motion in heavy machinery where mechanical accuracy determines output quality and operational safety. Servo-controlled variants command the dominant revenue share due to their saturation in flight control and turbine governing applications across the region's aviation and energy infrastructure. Proportional technology represents the fastest-expanding category as mid-tier industrial automation buyers in South Africa and Nigeria prioritize cost-calibrated precision over full servo performance. End-user concentration tilts heavily toward oil and gas, where subsea manifold control and wellhead intervention systems consume high-specification valves with corrosion-resistant coatings.
SFDA equipment certification protocols in Saudi Arabia and South Africa's national standards authority impose mandatory pressure-testing and material-traceability requirements on imported hydraulic components. The UAE's MOHAP-aligned industrial safety directives for offshore installations further narrow the supplier base to manufacturers with documented quality management systems. Stakeholders must monitor evolving carbon-intensity disclosures tied to EU Green Deal extraterritorial compliance, as European-headquartered oil majors operating in the region extend their Scope 3 reporting requirements down through valve procurement chains.
Market Dynamics
SFDA certification mandates and UAE offshore safety directives are compressing the supplier base for electro hydraulic servo valves, forcing manufacturers to document quality management systems and material traceability before entering procurement chains for Saudi petrochemical and Emirati subsea projects.
Growth Catalysts
- Subsea manifold automation:Deepwater exploration off the UAE coast demands corrosion-resistant servo valves for wellhead intervention systems, pulling high-specification orders from European oil majors operating in the Gulf.
- South Africa mining automation:Platinum and gold extraction operations are retrofitting hydraulic control systems to meet occupational safety thresholds, generating replacement demand for proportional valve technology.
- EU Green Deal extraterritoriality:Scope 3 carbon disclosure requirements imposed on European-headquartered energy companies are cascading down through valve procurement specifications, favoring suppliers with documented low-carbon manufacturing processes.
Market Restraints
- Specialized alloy input volatility:Nickel and cobalt price swings for corrosion-resistant valve coatings compress margins on long-delivery subsea contracts priced twelve months ahead of material procurement.
- European supplier concentration:Flight control actuation expertise for regional aerospace programs resides with a limited set of Western European manufacturers, creating single-source vulnerability for Saudi and Emirati defense procurement.
- Proportional valve performance ceiling:Mid-tier industrial buyers in Nigeria and Kenya accept hysteresis levels above one percent, capping upgrade pathways to full servo precision in cost-constrained automation budgets.
Strategic Opportunities
- Nigerian downstream refining:Dangote Refinery complex automation creates first-mover positioning for valve suppliers offering localized technical service and spare parts warehousing in Lagos.
- Digital twin convergence:Integration of servo valve telemetry with predictive maintenance platforms enables aftermarket service contracts tied to uptime guarantees rather than component sales.
- Saudi industrial cluster localization:Vision 2030 manufacturing incentives encourage joint ventures for domestic valve assembly and testing facilities, reducing import duty exposure and certification lead times.
Industry Challenges
- Pressure-testing certification backlog:SFDA and South African national standards authority queue times extend project commissioning schedules, forcing operators to hold contingency inventory and compress working capital cycles.
- Legacy hydraulic-pneumatic integration:Mining and petrochemical sites operate mixed actuator fleets, requiring servo valve suppliers to engineer backward-compatible control interfaces without degrading closed-loop response specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Electro Hydraulic Servo Valve Market |
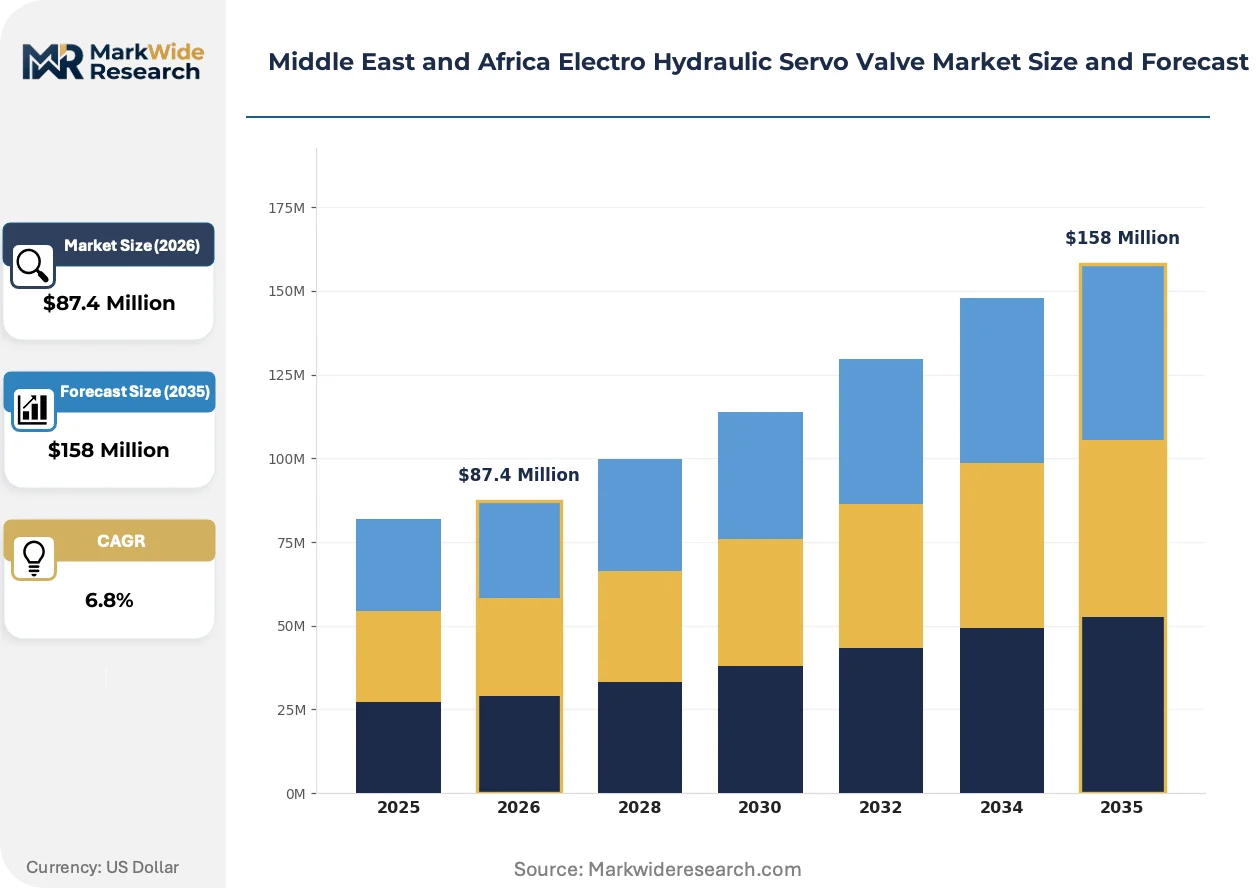
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct-Acting, Servo-Controlled, Proportional, On/Off End User: Aerospace, Automotive Manufacturing, Oil & Gas, Industrial Automation Technology: Electro-Hydraulic, Pneumatic, Mechanical, Digital Control Application: Robotics, Hydraulic Presses, Flight Control Systems, CNC Machines |
| Companies Covered | Moog Inc., Parker Hannifin Corporation, Eaton Corporation, Bosch Rexroth AG, Honeywell International Inc., Woodward Inc., Voith GmbH & Co. KGaA, Emerson Electric Co., Danfoss A/S, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Electro Hydraulic Servo Valve Market Shifts & Advancements
Smart diagnostics and edge-computing architectures are redefining valve value propositions across Middle Eastern oil infrastructure and African mining operations. Three developments are compressing traditional hardware-centric business models.
Additive manufacturing of titanium valve bodies is decomposing conventional foundry-to-machining supply chains for subsea applications. Norwegian and Emirati offshore contractors are piloting topology-optimized geometries that reduce weight by thirty percent while maintaining pressure ratings. This distributed production model is collapsing minimum order quantities and enabling rapid spare part replication at portside service hubs.
EU Green Deal carbon border adjustment mechanisms are tightening material provenance documentation for hydraulic components entering European-operated energy assets in the Gulf. SFDA has aligned its industrial equipment certification protocols with these extraterritorial requirements, mandating lifecycle emissions disclosures for imported valves. Suppliers without ISO 14001-extended certification are losing eligibility for Saudi Aramco and ADNOC framework agreements.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts in South Africa's platinum belt. Mining operators are separating valve hardware procurement from predictive analytics subscriptions, sourcing diagnostics from third-party industrial IoT platforms. This disaggregation pressures incumbent suppliers to modularize software offerings and compete on data integration rather than sole-source hardware lock-in.
Middle East and Africa Electro Hydraulic Servo Valve Market Segmentation
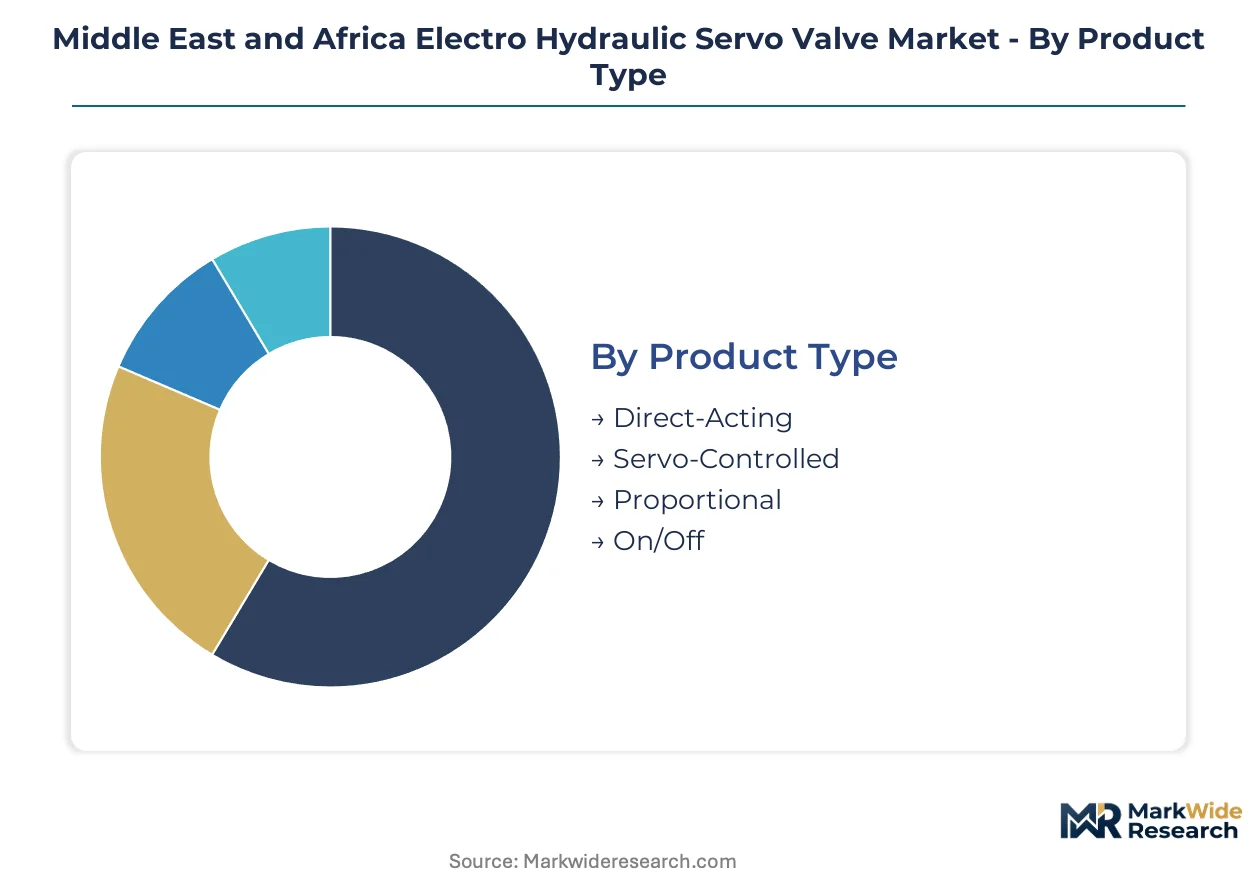
Segmentation in the Middle East and Africa electro hydraulic servo valve market exposes divergent procurement patterns between Gulf petrochemical operators and African mining houses. Technology tiers and end-use specifications vary sharply across Saudi Aramco framework agreements and South African platinum belt automation retrofits.
Product Type:
Domestic assembly concentrates in Saudi industrial clusters under Vision 2030 localization mandates, while high-specification subsea variants remain import-dependent through European supply chains.
- Servo-Controlled:These valves deliver sub-five-millisecond response times with hysteresis below 0.5 percent for closed-loop positioning. Saudi aerospace programs and UAE flight control systems anchor demand, with SFDA certification protocols filtering supplier eligibility.
- Proportional:Cost-calibrated precision with hysteresis tolerance above one percent suits mid-tier budgets. South African and Nigerian mining operators favor these for hydraulic retrofit programs where full servo performance exceeds operational requirements.
- Direct-Acting:Simplified architectures without pilot stages serve basic industrial automation in Kenya and Ghana manufacturing corridors.
- On/Off:Binary flow control for safety-critical isolation functions in pipeline infrastructure across the Gulf Cooperation Council states.
Servo-Controlled commands the established base. The steepest expansion runs through Proportional.
End User:
Cost tiers stratify sharply between defense-grade aerospace procurement and commodity-driven industrial automation budgets.
- Oil & Gas:Subsea manifold control and wellhead intervention systems consume corrosion-resistant coatings with nickel-alloy specifications. Deepwater exploration off the UAE coast pulls high-specification orders from European majors operating under EU Green Deal Scope 3 disclosure requirements.
- Industrial Automation:Platinum and gold extraction operations in South Africa's Bushveld Complex retrofit hydraulic controls to meet occupational safety thresholds. Replacement cycles favor proportional technology over full servo upgrades.
- Aerospace:Flight control actuation for Saudi and Emirati defense programs relies on limited Western European supplier bases.
- Automotive Manufacturing:Assembly line robotics in Morocco's Tangier-Med industrial zone drives precision valve demand for stamping press automation.
Oil & Gas anchors revenue concentration. Industrial Automation is climbing the fastest as mining safety mandates accelerate replacement schedules.
Technology:
Supply concentration favors electro-hydraulic architectures, with pneumatic and mechanical alternatives serving legacy infrastructure.
- Electro-Hydraulic:Dominant architecture converting low-power electrical signals into precise hydraulic flow modulation. Bosch Rexroth and Parker Hannifin embed smart diagnostics for predictive maintenance workflows in Gulf petrochemical installations.
- Digital Control:Edge-computing integration enabling telemetry feeds to third-party industrial IoT platforms. South African mining operators unbundle hardware from analytics subscriptions, pressuring modular software offerings.
- Pneumatic:Legacy compatibility requirements for mixed actuator fleets in Nigerian downstream refining.
- Mechanical:Backup systems for fail-safe positioning in subsea applications where electrical isolation is mandatory.
Electro-Hydraulic retains the volume base. Digital Control is gaining share fastest through aftermarket service contract unbundling.
Application:
Customer type differentiation separates defense procurement with extended certification timelines from commercial industrial buyers with compressed commissioning schedules.
- Flight Control Systems:Moog Inc. leverages legacy actuation expertise for Saudi and Emirati aerospace programs. Response time specifications below five milliseconds and material traceability mandates constrain the supplier base.
- Hydraulic Presses:Dangote Refinery complex automation in Nigeria creates first-mover positioning for suppliers offering localized technical service and Lagos-based spare parts warehousing.
- CNC Machines:Precision positioning for toolpath control in UAE metal fabrication clusters serving petrochemical maintenance operations.
- Robotics:Articulated arm actuation for material handling in South African automotive component plants.
Flight Control Systems commands the premium tier. Hydraulic Presses shows the steepest expansion trajectory through Nigerian downstream infrastructure commissioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Italian valve manufacturers dominate export flows into Gulf petrochemical installations, while South African distributors channel European-sourced components into platinum belt mining operations.
Saudi Arabia
SFDA certification mandates filter supplier eligibility for Aramco framework agreements, with domestic assembly incentives under Vision 2030 accelerating joint ventures in Jubail Industrial City. Eastern Province clusters now host pressure-testing facilities that reduce import lead times for subsea manifold projects.
United Arab Emirates
MOHAP-aligned offshore safety directives constrain procurement to documented quality management systems, pulling high-specification orders into Abu Dhabi National Oil Company supply chains. Dubai's Jebel Ali portside service hubs enable rapid spare part replication for deepwater exploration contractors.
South Africa
National standards authority queue times extend project commissioning for Bushveld Complex platinum operations, forcing contingency inventory holdings. Johannesburg-based distributors unbundle hardware procurement from predictive analytics subscriptions, pressuring modular software offerings.
Nigeria
Dangote Refinery complex automation creates concentrated demand for localized technical service capabilities in Lagos. Downstream refining retrofit programs favor proportional valve technology where full servo precision exceeds operational requirements.
Israel
Defense procurement for flight control actuation maintains reliance on limited Western European supplier bases, with extended certification timelines constraining commissioning schedules. Tel Aviv aerospace clusters coordinate specification alignment with Saudi and Emirati regional programs.
Middle East and Africa Electro Hydraulic Servo Valve Market Competitive Landscape
Listed leaders compete with private specialists across certification documentation and aftermarket service bundling. The supplier base compresses around quality management system credentials, with tiered positioning separating full-servo precision providers from proportional technology fabricators. Three archetypes dominate: European incumbents with flight control heritage, diversified industrial conglomerates with Gulf distribution scale, and regional assemblers leveraging Vision 2030 localization incentives. Competitive moves concentrate on strategic partnerships for domestic testing facilities and portfolio diversification into predictive maintenance platforms.
Within the European incumbent tier, Moog Inc. and Bosch Rexroth AG exemplify archetypes anchored in aerospace actuation expertise and digital control integration respectively. Parker Hannifin Corporation occupies a position among diversified industrial conglomerates with localized distribution infrastructure. These three entities represent the certification-heavy, specification-driven competitive vector that dominates Saudi and Emirati defense and energy procurement.
| Leading Market Players |
|---|
| Moog Inc. |
| Parker Hannifin Corporation |
| Eaton Corporation |
| Bosch Rexroth AG |
| Honeywell International Inc. |
| Woodward Inc. |
| Voith GmbH & Co. KGaA |
| Emerson Electric Co. |
| Danfoss A/S |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for subsea manifold projects lock in both nickel-alloy supply access and price visibility for European oil majors operating under EU Green Deal Scope 3 mandates, compressing margin flexibility for valve manufacturers facing twelve-month procurement lags. SFDA certification requirements and UAE offshore safety directives further constrain supplier eligibility, amplifying pricing power for documented quality management systems.
Pricing Analysis
Full servo-controlled technology commands a generation-gap premium over proportional and direct-acting alternatives, with hysteresis specifications below 0.5 percent justifying three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on SFDA certification grade and after-sales service bundling, with corrosion-resistant coating tiers separating Aramco framework suppliers from spot-market entrants. Cost compression in mid-tier proportional valves is intensifying because Nigerian and Kenyan mining buyers accept performance ceilings above one percent hysteresis. Industrial automation retrofit budgets in South Africa's platinum belt show the highest price sensitivity, while Saudi aerospace procurement demonstrates the lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate subsea project planning, with European contractors holding nickel and cobalt alloy inventory against twelve-month delivery schedules. Manufacturing concentrates in Germany, Italy, and the United Kingdom for flight control actuation expertise, while Saudi Vision 2030 incentives are anchoring domestic assembly in Jubail Industrial City. Raw material dependencies draw from South African platinum-group metals, Indonesian nickel processing, and German precision machining capabilities. Single-source vulnerability runs through limited Western European flight control specialists serving Saudi and Emirati defense programs. Distribution runs through Dubai's Jebel Ali portside hubs and Johannesburg-based mining distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa electro hydraulic servo valve market is accelerating through smart diagnostics convergence and EU Green Deal carbon disclosure cascading into procurement specifications. SFDA alignment with extraterritorial compliance requirements is compressing supplier eligibility, creating first-mover advantages for certified quality management systems.
For Market Incumbents: Compound certification documentation advantages by embedding predictive maintenance platforms into valve architectures, converting hardware sales into uptime-guarantee subscriptions. Deepen backward integration into titanium additive manufacturing for subsea valve bodies, securing topology-optimized geometries against Norwegian and Emirati offshore contractor pilot programs. Lock in Aramco and ADNOC framework extensions through ISO 14001-extended lifecycle emissions disclosures before carbon border adjustments tighten.
For New Entrants and Emerging Players: Differentiate on localized technical service capabilities, establishing Lagos-based spare parts warehousing to capture Dangote Refinery complex automation demand. Target Nigerian downstream refining and Kenyan manufacturing corridors where proportional valve performance ceilings match operational requirements and full servo precision exceeds budgets. Pursue joint venture structures with Saudi industrial cluster developers to bypass import duty exposure and certification lead times under Vision 2030 localization mandates.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier proportional valve fabricators with established South African mining relationships and modular software offerings compatible with third-party industrial IoT platforms. Long-term viability over the projection horizon favors suppliers capable of unbundling hardware from predictive analytics subscriptions as mining operators fragment traditional bundled maintenance contracts. Watch for SFDA queue time reductions as domestic pressure-testing facilities commission in Jubail Industrial City, signaling localization inflection and import substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Testing Facility Joint Venture | Vision 2030 incentives reduce SFDA certification lead times for Saudi Aramco framework eligibility. |
| Predictive Maintenance Platform Integration | Bosch Rexroth and Parker Hannifin embed smart diagnostics for Gulf petrochemical uptime contracts. |
| Additive Manufacturing Capability Buildout | Topology-optimized titanium valve bodies cut weight thirty percent for Norwegian subsea contractors. |
| Localized Spare Parts Warehousing | Lagos-based inventory captures Dangote Refinery automation commissioning and aftermarket service. |
| ISO 14001-Extended Certification Investment | EU Green Deal Scope 3 disclosures filter ADNOC procurement toward documented low-carbon processes. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at Saudi petrochemical installations, OEM procurement teams serving UAE offshore contractors, aftermarket service heads in South African platinum operations, and plant engineers at Nigerian downstream refineries, then refined through customs and trade data, SEC filings from listed valve manufacturers, SFDA equipment certification registries, and EU ETS carbon border adjustment documentation. Bottom-up demand aggregation across technology tiers and end-use segments was cross-validated against top-down industrial automation capex trends.
Variance decomposition across the projection horizon isolates technology substitution effects, regulatory compliance cost pass-through, and raw material price volatility as primary forecast drivers. The analytical framework models electro-hydraulic and digital control technology segments, servo-controlled and proportional product tiers, oil and gas versus industrial automation end-use splits, and Gulf versus African regional production clusters. CAGRs were derived from segment-level growth rate reconciliation against macro industrial output projections, with subsea manifold automation intensity and mining safety mandate replacement cycles serving as industry-specific volume anchors.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal extraterritorial enforcement and stable nickel-cobalt alloy supply; material deviation in either would warrant model refresh. Forecasts incorporate SFDA certification queue time stability and Vision 2030 localization incentive continuity. Revision becomes warranted when carbon border adjustment scope expansion crosses thresholds affecting valve component tariff classifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Christmas Tree Valves Market
Valves
Diaphragm Valve Market
Valves
Global Gate Valve Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
HVAC Valves Market
Valves
Hot Blast Valves Market
Valves
Global Compression Packing Market
Valves
Subsea Control System Market
Valves
Air Heated Vaporizer Market
Valves
Mobile Hydraulic Valves Market
Valves
Instrumentation Valves and Fittings Market
Valves
North America Butterfly Valve Market
Valves
Leak Detection Market
Valves
Insulation Flanges Market
Valves
Hydraulic Valves Market
Valves
Choke and Kill Manifold Market