
 Global Thermostatic Radiator Valve Market | 2026-2036
Global Thermostatic Radiator Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermostatic Radiator Valve Market Analysis
Brass is realigning thermostatic radiator valve economics as manufacturers substitute engineered polymers and stainless steel to reduce lead content and raw material volatility. Danfoss A/S leverages its Nordic manufacturing footprint to sustain cost advantages across electronic valve lines. Honeywell International Inc. anchors its position through channel control in North American commercial retrofits. IMI plc differentiates via hydronic system integration expertise spanning valve-to-actuator portfolios.
A thermostatic radiator valve is a temperature-sensitive flow control device, typically incorporating a wax-filled thermostatic element or liquid sensor with a spring-loaded valve seat, designed to maintain individual room temperature setpoints by modulating hot water flow through radiators. Smart valves with Zigbee or LoRaWAN connectivity now dominate R&D investment, while brass-bodied manual valves remain the mature margin pool in replacement cycles. Wireless valves represent the fastest-growing installation type as residential end users prioritize non-invasive upgrades over wall-mounted alternatives requiring pipework disruption.
The EU Green Deal and F-Gas Regulation shape product efficiency mandates across European member states, while the EPA's lead-free plumbing standards influence material composition for valves entering US distribution channels. REACH compliance and CE marking requirements determine market access for brass and bronze alloy suppliers serving valve manufacturers. Stakeholders must monitor evolving interoperability standards between smart valves and utility demand-response platforms before committing to proprietary communication protocols.
Market Dynamics
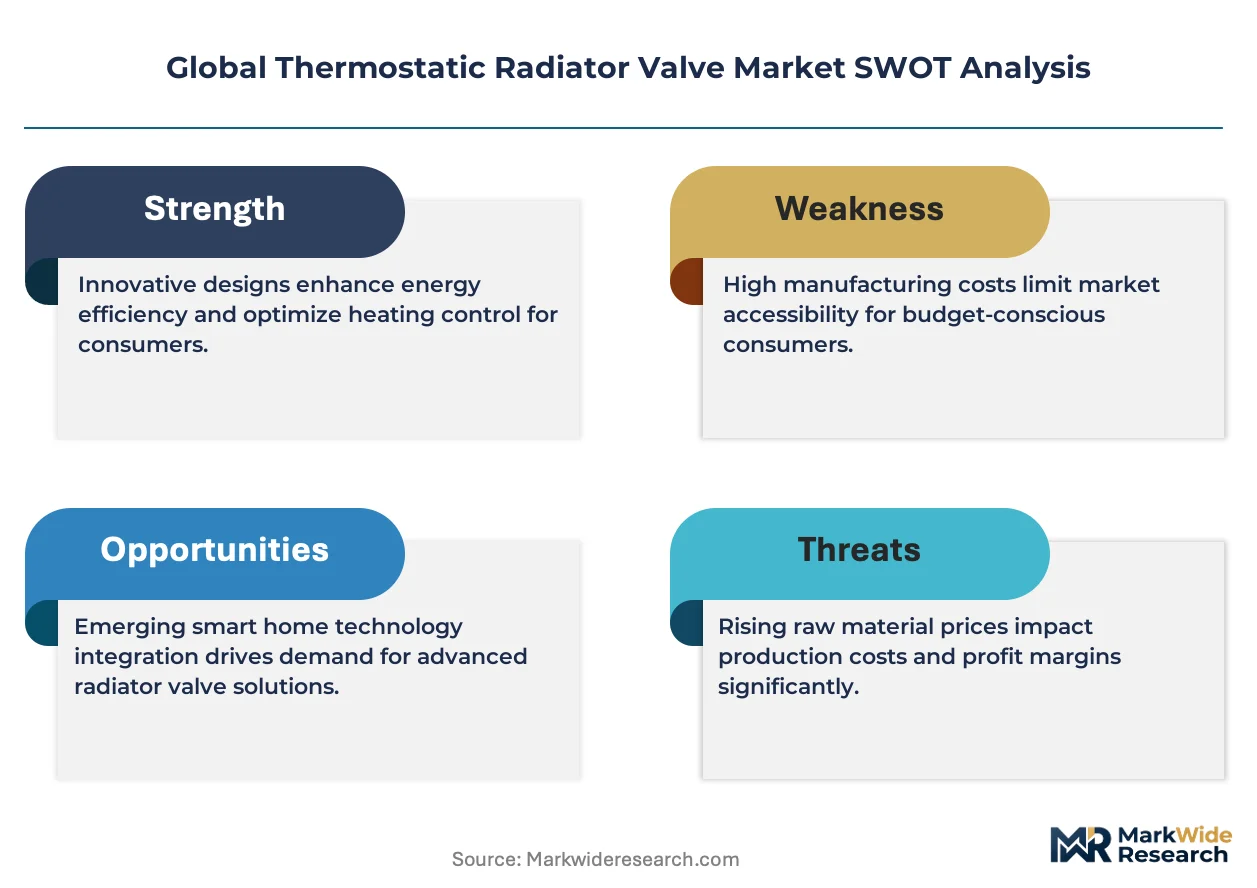
The thermostatic radiator valve sector is experiencing fundamental restructuring as wireless connectivity protocols displace mechanical wax-element designs in residential and commercial building retrofits. This technology migration is compressing replacement cycles while elevating software interoperability requirements above hardware durability as the primary vendor selection criterion.
Growth Catalysts
- EU Green Deal building renovation mandates:Germany's tightened energy codes for residential retrofits are accelerating TRV replacement schedules across multi-unit housing stock.
- Wireless protocol standardization:Zigbee and LoRaWAN integration is enabling utility demand-response participation, expanding addressable market beyond temperature control into grid services.
- Scandinavian district heating expansion:Copenhagen and Stockholm municipal networks are specifying smart TRVs for zone-level optimization in centralized heat distribution systems.
Market Restraints
- Brass alloy cost volatility:Lead-free copper-zinc formulations face price instability from concentrate supply disruptions in Chilean mining operations.
- Electronic component concentration:MEMS temperature sensors and RF modules depend on concentrated Asian semiconductor fabrication capacity.
- Legacy hydronic incompatibility:Older single-pipe steam systems in Northeast US housing stock resist smart valve retrofit without radiator replacement.
Strategic Opportunities
- Polish residential market underpenetration:Warsaw and Krakow apartment districts retain high manual valve penetration rates with EU cohesion funding available for efficiency upgrades.
- Heat pump integration requirements:Low-temperature emitter compatibility specifications are creating specification advantages for electronically actuated valves.
- Netherlands BENG standards:Nearly Energy Neutral Building regulations mandate room-level temperature control in new construction from 2025.
Industry Challenges
- Interoperability certification timelines:OpenTherm and Matter protocol compliance testing creates 8-12 month product launch delays.
- Plumbing contractor skill gaps:Electronic commissioning and smartphone-based setup procedures require training investments beyond traditional mechanical installation expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermostatic Radiator Valve Market |
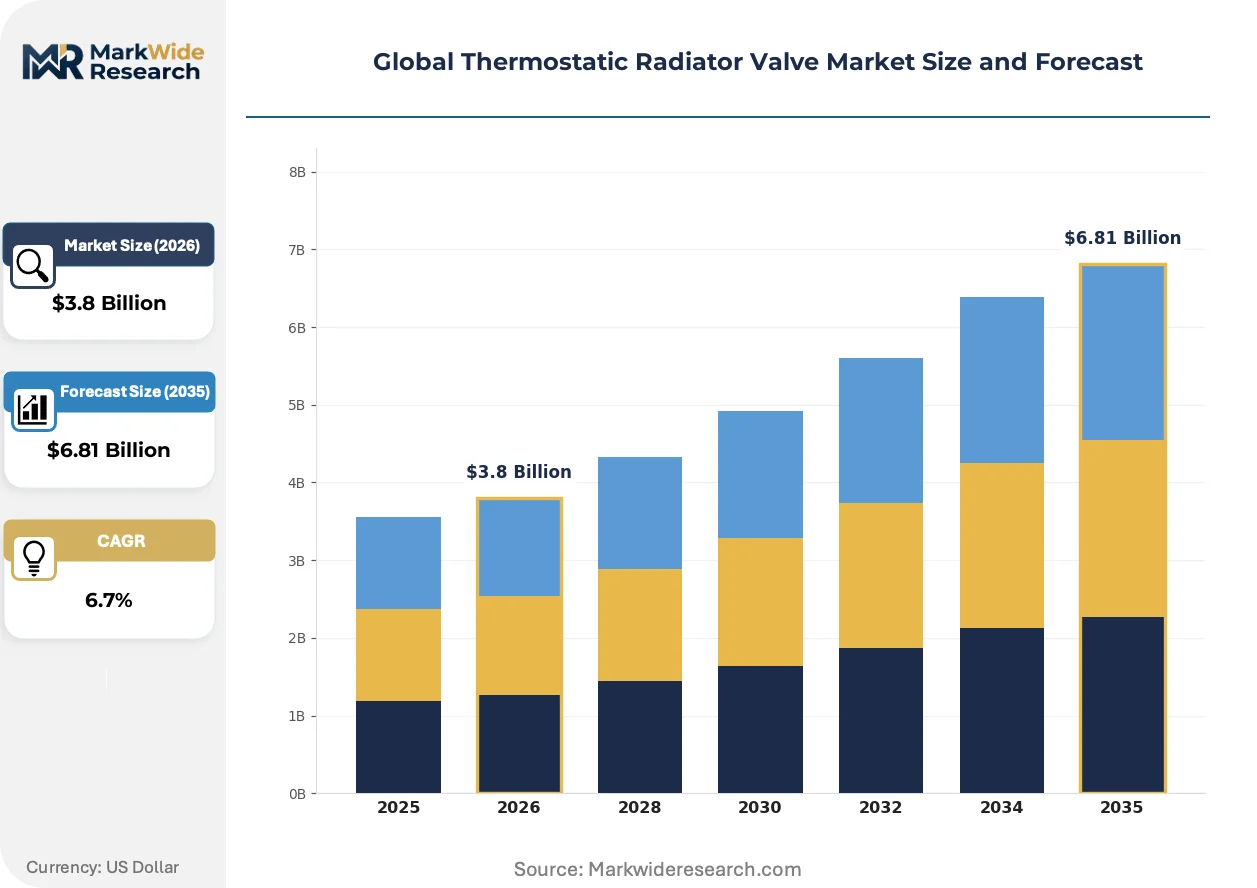
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Valves, Electronic Valves, Wireless Valves, Smart Valves Material: Brass, Plastic, Stainless Steel, Bronze End User: Residential, Commercial, Industrial, Institutional Installation Type: Wall-Mounted, Floor-Mounted, Retrofit, New Construction |
| Companies Covered | Oventrop GmbH & Co. KG, Caleffi, Danfoss A/S, Emmeti S.p.A., Herz Armaturen GmbH, Honeywell International Inc., IMI plc, WATTS Water Technologies, Inc., Giacomini S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermostatic Radiator Valve Market Emerging Trajectories
Product development in thermostatic radiator valves is pivoting from thermal-mechanical precision toward digital ecosystem integration. This shift is elevating firmware update capabilities and API accessibility to parity with flow-control engineering in vendor R&D allocation.
Sensor fusion architectures combining temperature, humidity, and occupancy detection are converging with cloud-based predictive heating algorithms. Netherlands-based building managers are piloting these systems in social housing portfolios. The technology is converging with utility tariff optimization, compressing payback periods for smart valve investments below three years in variable-rate markets.
REACH restrictions on lead content in brass alloys are forcing material transitions toward stainless steel valve bodies and engineered polymer internals. German component suppliers are certifying new alloy formulations through ECHA notification procedures. Residential replacement demand in Northern Europe is absorbing price premiums for compliant materials without volume elasticity.
Facility managers in commercial real estate are consolidating vendor relationships around full-hydronic-system suppliers rather than standalone valve procurement. Copenhagen hospital retrofits exemplify this pattern, specifying integrated valve-actuator-controller packages. Scandinavian public procurement frameworks are embedding this preference into technical specifications, marginalizing component-only vendors.
Global Thermostatic Radiator Valve Market Segmentation
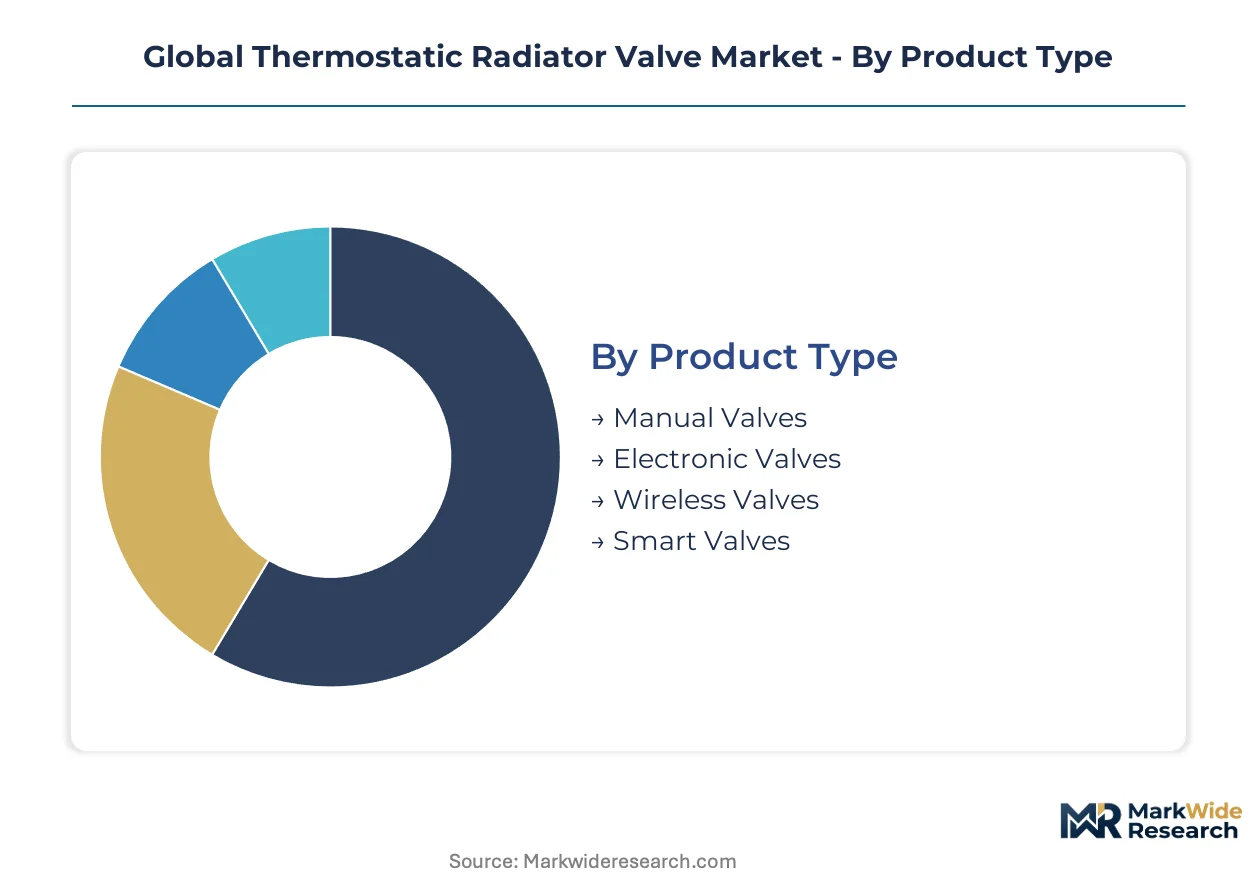
TRV procurement patterns diverge sharply between replacement cycles and new construction specifications, with connectivity requirements and material compliance driving vendor selection across distinct customer workflows.
Product Type:
Standardization dominates at the mechanical end while customization intensity escalates toward connected product tiers, with firmware configurability replacing hardware interchangeability as the flexibility metric.
- Manual Valves:Wax-filled thermostatic elements with spring-loaded valve seats provide temperature modulation without external power. Replacement demand concentrates in German and Polish multi-unit housing stock as building codes mandate individual zone control. Lead-free brass material transitions under REACH compliance are compressing supplier margins.
- Wireless Valves:Battery-powered RF-enabled actuators with Zigbee or LoRaWAN connectivity eliminate wiring infrastructure requirements. Scandinavian social housing portfolios and Netherlands rental properties are absorbing volume as non-invasive retrofit preference hardens. Utility demand-response program participation is extending payback calculations beyond energy savings alone.
- Electronic Valves:Hardwired electronic actuators with proportional control signals interface with building management systems.
- Smart Valves:Cloud-connected devices with sensor fusion, occupancy detection, and predictive heating algorithms.
Most installed capacity flows through manual valves. Expansion is steepest in wireless valves.
Material:
Cost tiers separate commodity replacement components from specification-grade new construction, with regulatory pressure on lead content collapsing the traditional brass premium.
- Brass:Copper-zinc alloys with lead-free formulations under ECHA notification provide machinability and thermal conductivity for valve bodies. German component suppliers are certifying replacement alloys as Chilean concentrate disruptions transmit price volatility. Residential replacement cycles in Northern Europe show inelastic volume response to material cost increases.
- Stainless Steel:Austenitic grades with corrosion resistance and zero lead content satisfy drinking water contact regulations. US EPA lead-free plumbing standards are redirecting specification preferences in commercial retrofits. Fabrication cost premiums are narrowing against brass as alloy prices converge.
- Plastic:Engineered polymers with glass fiber reinforcement for internal valve components and low-pressure applications.
- Bronze:Copper-tin alloys with superior corrosion resistance for marine and harsh environment installations.
Brass retains the largest installed base. Stainless steel is gaining specification share fastest.
End User:
Application maturity separates price-sensitive maintenance procurement from performance-specified system integration, with control granularity requirements escalating across the customer spectrum.
- Residential:Individual room temperature control in single-family and multi-unit dwellings. German energy code retrofits and Netherlands BENG standards are accelerating replacement schedules. Smart valve adoption concentrates in owner-occupied segments with smartphone-based commissioning tolerance.
- Commercial:Office buildings, retail, and hospitality requiring zone-level optimization. Copenhagen hospital retrofits exemplify integrated valve-actuator-controller procurement patterns. Scandinavian public procurement frameworks are embedding full-system vendor preferences into technical specifications.
- Industrial:Process heating and manufacturing facility climate control with durability specifications.
- Institutional:Schools, government buildings, and healthcare facilities with extended lifecycle requirements.
Residential channels move the highest unit volumes. Commercial applications are climbing the fastest.
Installation Type:
Customer disruption tolerance determines channel segmentation, with labor cost avoidance and heritage preservation creating distinct specification requirements.
- Retrofit:Replacement of existing valves without pipework modification or wall disruption. Wireless connectivity protocols are eliminating wiring infrastructure barriers in Northeast US single-pipe steam conversions. Polish apartment districts with EU cohesion funding access represent underpenetrated expansion territory.
- New Construction:Specification-driven procurement with embedded commissioning during building handover. Netherlands Nearly Energy Neutral Building regulations mandate room-level temperature control from 2025. Heat pump integration requirements are elevating electronically actuated valve specifications for low-temperature emitter compatibility.
- Wall-Mounted:Traditional installation with exposed valve bodies and accessible adjustment mechanisms.
- Floor-Mounted:Concealed placement with remote sensor and actuator configurations.
Retrofit installations dominate current demand. New construction specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor dominates thermostatic radiator valve demand through building renovation mandates and district heating modernization. Five national markets concentrate procurement patterns across distinct regulatory and infrastructure contexts.
Germany
Multi-unit housing retrofits and tightened energy codes drive replacement cycles in Berlin and Munich metropolitan zones. The EU Green Deal's building renovation targets accelerate TRV installation schedules through 2030. Bavarian component suppliers certify lead-free brass formulations under ECHA notification procedures.
Netherlands
Social housing portfolios and rental property managers prioritize wireless valve installations for non-invasive upgrades. Nearly Energy Neutral Building regulations mandate room-level temperature control in new construction from 2025. Randstad building managers pilot sensor-fusion systems with cloud-based predictive heating algorithms.
United States
Commercial retrofit channels in Northeast corridor cities grapple with legacy single-pipe steam system incompatibility. EPA lead-free plumbing standards redirect material specifications toward stainless steel valve bodies. Chicago and Boston facility managers consolidate procurement around full-hydronic-system suppliers.
Poland
Warsaw and Krakow apartment districts retain high manual valve penetration with EU cohesion funding available for efficiency upgrades. REACH compliance requirements shape brass alloy sourcing for replacement component manufacturers. Silesian industrial zones supply machined valve bodies to German OEMs.
Sweden
Stockholm municipal district heating networks specify smart TRVs for zone-level optimization in centralized heat distribution. Scandinavian public procurement frameworks embed full-system vendor preferences into technical specifications. Copenhagen hospital retrofits exemplify integrated valve-actuator-controller procurement patterns.
Global Thermostatic Radiator Valve Market Vendor Landscape
Global majors compete with regional champions across material certification and wireless protocol integration. The vendor base separates into consolidated full-system suppliers and specialized component fabricators. Three archetypes dominate: Nordic manufacturing footprint holders, hydronic integration specialists, and channel-controlled North American incumbents. Strategic moves concentrate on interoperability certification investments and backward integration into lead-free alloy supply.
Among German and Italian valve specialists, Oventrop GmbH & Co. KG, Caleffi, and Giacomini S.p.A. occupy positions within the premium mechanical valve tier. These European fabricators exemplify regional manufacturing archetypes focused on brass machining expertise and ECHA-compliant material transitions. Their market presence anchors the mature replacement cycle segment against electronic valve entrants.
| Leading Market Players |
|---|
| Oventrop GmbH & Co. KG |
| Caleffi |
| Danfoss A/S |
| Emmeti S.p.A. |
| Herz Armaturen GmbH |
| Honeywell International Inc. |
| IMI plc |
| WATTS Water Technologies, Inc. |
| Giacomini S.p.A. |
| Others |
Supply Flow & Price Mechanics
Wireless protocol integration is compressing hardware margins while elevating firmware development costs as the dominant cost driver, simultaneously redistributing supply chain value toward semiconductor fabrication capacity in Taiwan and RF module assembly clusters in South Korea. This technology migration concentrates procurement leverage among building management platform vendors who bundle valve specifications into system-level contracts.
Pricing Analysis
Input-cost pass-through from Chilean copper concentrate disruptions and ECHA lead-free brass certification requirements is intensifying margin pressure across mechanical valve tiers. Pricing stratifies across electronic smart valves, wireless retrofit units, and commodity manual replacements, with certification grade and volume scale as primary differentiation drivers. Cost compression in brass-bodied segments reflects raw material volatility, while electronic tiers absorb semiconductor scarcity premiums. Residential retrofit contractors in Poland and Germany exhibit highest price sensitivity; Scandinavian district heating utilities show lowest sensitivity due to lifecycle cost optimization mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor European hub-and-spoke patterns for valve component logistics, with consolidation pressure from full-system vendor procurement preferences. Manufacturing concentration spans Germany for precision machining, Italy for brass forging expertise, and China for electronic actuator assembly. Raw material dependencies encompass Chilean copper concentrate, Taiwanese MEMS sensors, and South Korean RF modules. Single-source vulnerability in semiconductor fabrication creates supply chain risk. Distribution runs through hydronic system integrators and plumbing wholesale channels rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as building energy codes and EU Green Deal renovation mandates shift specification authority toward performance-validated electronic valves over commodity mechanical replacements.
For Market Incumbents: To counter proprietary protocol lock-in by building management platform vendors, prioritize OpenTherm and Matter interoperability certification investments. Deepen backward integration into lead-free brass alloy supply through ECHA-compliant European foundry partnerships. Anchor channel control through training investments that address plumbing contractor skill gaps in electronic commissioning procedures.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium Scandinavian smart valves and economy Polish manual replacements creates white-space opportunity. Target Warsaw and Krakow apartment districts with EU cohesion funding access for wireless retrofit solutions. Pursue utility demand-response program partnerships as the primary go-to-market angle, leveraging tariff optimization value propositions over hardware margins.
For Investors and Strategic Acquirers: Valuations sit cheapest among German and Italian mechanical valve specialists with ECHA-compliant material certifications but lagging wireless protocol integration. Long-term viability favors full-system hydronic integrators over component-only fabricators as procurement consolidation hardens. Watch interoperability certification timelines as the inflection signal—8-12 month compliance delays separate acquisition targets with platform-ready portfolios from stranded mechanical pure-plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | OpenTherm and Matter compliance accelerates platform integration with Netherlands and Scandinavian building management systems. |
| Backward Integration into Alloy Supply | ECHA-compliant lead-free brass foundry control secures material access against Chilean concentrate price volatility. |
| Utility Demand-Response Partnership | Zigbee and LoRaWAN-enabled valve portfolios capture grid services revenue beyond temperature control hardware sales. |
| Contractor Training Program Expansion | Electronic commissioning expertise addresses skill gaps blocking smart valve adoption in German and Polish retrofit channels. |
| Heat Pump Compatibility Specification | Low-temperature emitter validation aligns product portfolios with Netherlands BENG standards and EU Green Deal efficiency mandates. |
Methodological Framework
Bottom-up residential and commercial building stock modeling reconciled against top-down valve manufacturer shipment tracking forms the analytical core of this study. Primary interviews with hydronic system integrators, plumbing wholesale procurement managers, building energy auditors, and district heating network planners combined with secondary validation from EU building renovation databases, ECHA substance notification registries, and national energy agency retrofit statistics. Trade data from German and Italian valve export records triangulates against utility demand-response program enrollment figures.
Input-output matrices map brass alloy consumption and electronic component demand against installed base replacement cycles and new construction specifications across the projection horizon. Segmentation dimensions encompass product type, material grade, end-use application, and installation context. CAGRs derive from regression analysis of historical replacement patterns against regulatory mandate schedules. Forecast inputs incorporate EU Green Deal building renovation targets, Netherlands BENG implementation timelines, and heat pump deployment trajectories.
Caveats apply where semiconductor supply disruptions, REACH regulatory amendments, or interoperability protocol fragmentation could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Naval Actuators and Valves Market
Valves
Curb Valves Market
Valves
Steam Trap Valve Market
Valves
Thermal Power Valve Market
Valves
One-Way Valve Market
Valves
Global Solenoid Valves Market
Valves
Electro Pneumatic Positioner Market
Valves
Cathodic Protection Market
Valves
Global Pipeline Safety Market
Valves
Butterfly Valves Market
Valves
Isolator Valves Market
Valves
Fluid Power Cylinder Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Air Jet Ejectors Market
Valves
Valve Sack Market
Valves
Europe Butterfly Valve Market