
 Pipeline Integrity Market | 2026-2036
Pipeline Integrity Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Integrity Market Outlook
Midstream operators is rotating toward predictive integrity frameworks over reactive repair schedules. SGS S.A. leverages its global inspection footprint to capture cross-border pipeline contracts. Baker Hughes Company anchors its position through integrated sensor-to-software platforms. ROSEN Group dominates specialized smart pig manufacturing for unpiggable lines.
Pipeline integrity encompasses the structural, operational, and leak-tight fitness of hydrocarbon and fluid transport systems, verified through inline inspection tools operating at pressures up to 200 bar and wall-thickness resolutions below 0.1 millimeter. Its primary purpose is preventing catastrophic release, service interruption, and environmental liability across continental transmission corridors. Smart pigs and magnetic flux leakage technology lead current deployment volumes, while inspection robots represent the fastest-growing category as operators target unpiggable geometries. Ultrasonic testing commands premium pricing in subsea and high-temperature lines where alternative methods degrade.
PHMSA in the United States, the Pipeline Safety Regulations under CFR Part 195, and Canada's National Energy Board Onshore Pipeline Regulations shape mandatory inspection intervals, defect response timelines, and data retention requirements that directly drive equipment procurement cycles. The EU's Industrial Emissions Directive and Pressure Equipment Directive extend similar compliance burdens across European transmission networks. Stakeholders must monitor regulatory divergence between jurisdictions that mandate continuous monitoring versus periodic inspection, as this split determines capital allocation between installed sensor networks and contracted inline inspection services.
Market Dynamics
Midstream operators face escalating pressure from aging North American crude infrastructure combined with PHMSA mandates for expanded inline inspection protocols. The structural pivot from reactive repair to predictive integrity frameworks is compressing equipment replacement cycles and elevating demand for sensor-integrated platforms.
Growth Catalysts
- PHMSA Mandate Expansion:The US Pipeline and Hazardous Materials Safety Administration now requires more frequent inline inspection intervals for high-consequence areas, forcing operators to upgrade smart pig fleets and magnetic flux leakage tool inventories.
- Unpiggable Line Robotics:Inspection robots are penetrating previously inaccessible pipeline geometries, opening integrity verification for complex gathering systems and urban distribution networks that conventional pigs cannot traverse.
- Alberta Oil Sands Corrosion:Sour service conditions in Canadian oil sands corridors accelerate wall-thickness degradation, sustaining demand for ultrasonic testing and specialized corrosion-resistant inspection technologies.
Market Restraints
- Specialized Steel Input Volatility:High-grade magnetic alloys and corrosion-resistant sensor housings face price swings tied to nickel and rare earth supply concentration in Southeast Asian processing centers.
- Ultrasonic Transducer Supply Bottleneck:Piezoelectric crystal manufacturing concentrates among limited German and Japanese suppliers, constraining rapid scaling of high-temperature inspection tool production.
- Subsea Tool Recovery Risk:Deepwater inline inspection tools operating below 1,500 meters face non-trivial loss rates, elevating insurance premiums and dampening operator appetite for frontier offshore integrity programs.
Strategic Opportunities
- Mexico Energy Reform Infrastructure:Pemex and private midstream entrants are building new cross-border pipeline capacity without legacy inspection regimes, creating greenfield demand for integrated integrity-as-a-service platforms.
- Continuous Monitoring Convergence:Fiber optic distributed acoustic sensing combined with satellite leak detection is displacing periodic inspection contracts with subscription-based real-time monitoring in Texas Permian corridors.
- Carbon Capture Pipeline Integrity:CO2 transport networks for enhanced oil recovery and sequestration projects require specialized crack-detection protocols and corrosion modeling, opening adjacent equipment categories.
Industry Challenges
- Inline Inspection Data Analyst Shortage:Magnetic flux leakage signal interpretation and flaw-sizing algorithm validation require scarce specialized technicians, extending report delivery timelines and deferring maintenance decisions.
- Legacy SCADA Integration Friction:New sensor-to-software platforms must interface with decades-old pipeline control systems, multiplying deployment costs and cybersecurity exposure windows during retrofit periods.
- Cross-Border Certification Complexity:Tool operators seeking contracts spanning US-Canada corridors face divergent PHMSA and National Energy Board qualification requirements, fragmenting equipment standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Integrity Market |
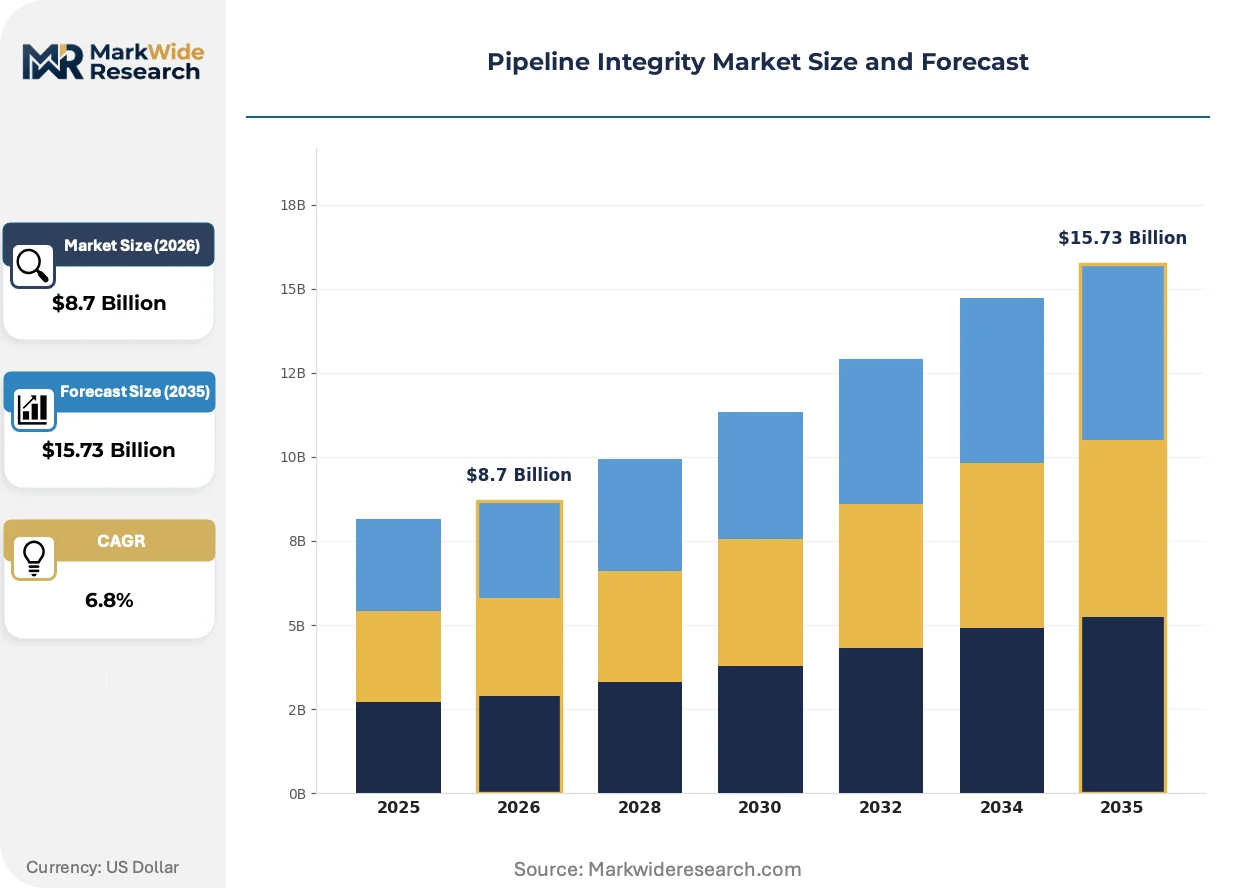
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Pigs, Sensors, Hydrostatic Testing, Inspection Robots Technology: Ultrasonic, Magnetic Flux Leakage, Electromagnetic, Thermal End User: Oil & Gas, Water Supply, Chemical Processing, Power Generation Application: Corrosion Monitoring, Leak Detection, Structural Assessment, Maintenance Planning |
| Companies Covered | T.D. Williamson, Inc., SGS S.A., Baker Hughes Company, Intertek Group plc, Bureau Veritas S.A., ROSEN Group, Applus+ S.A., Quest Integrity Group, MISTRAS Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Integrity Market Strategic Shifts
Pipeline integrity technology is converging around autonomous inspection platforms and real-time data transmission architectures. Equipment manufacturers and service providers are racing to compress inspection cycle times while expanding coverage of geometrically complex infrastructure.
Robotic crawler systems equipped with electromagnetic acoustic transducers are penetrating unpiggable pipeline segments previously excluded from integrity programs. Midstream operators in the Permian Basin and Alberta oil sands are deploying these units quarterly rather than annually. The technology is miniaturizing inspection hardware to diameters below six inches, collapsing the addressable market gap between gathering lines and transmission mains.
Canada's National Energy Board Onshore Pipeline Regulations now mandate defect response timelines measured in days rather than weeks for certain crack indications. This regulatory compression is forcing operators to pre-position inspection assets and accelerate data processing workflows. High-consequence areas near populated zones in Ontario and British Columbia face the most stringent compliance windows, driving demand for rapid-deployment inspection services.
Buying patterns among integrated oil companies are consolidating inspection contracts under multi-year framework agreements with single-source providers. Independent midstream operators in Texas and Oklahoma are responding by forming purchasing cooperatives to match volume leverage. This concentration is most visible in the Gulf Coast refining corridor, where three operators now control over half of third-party inline inspection procurement.
Pipeline Integrity Market Segmentation
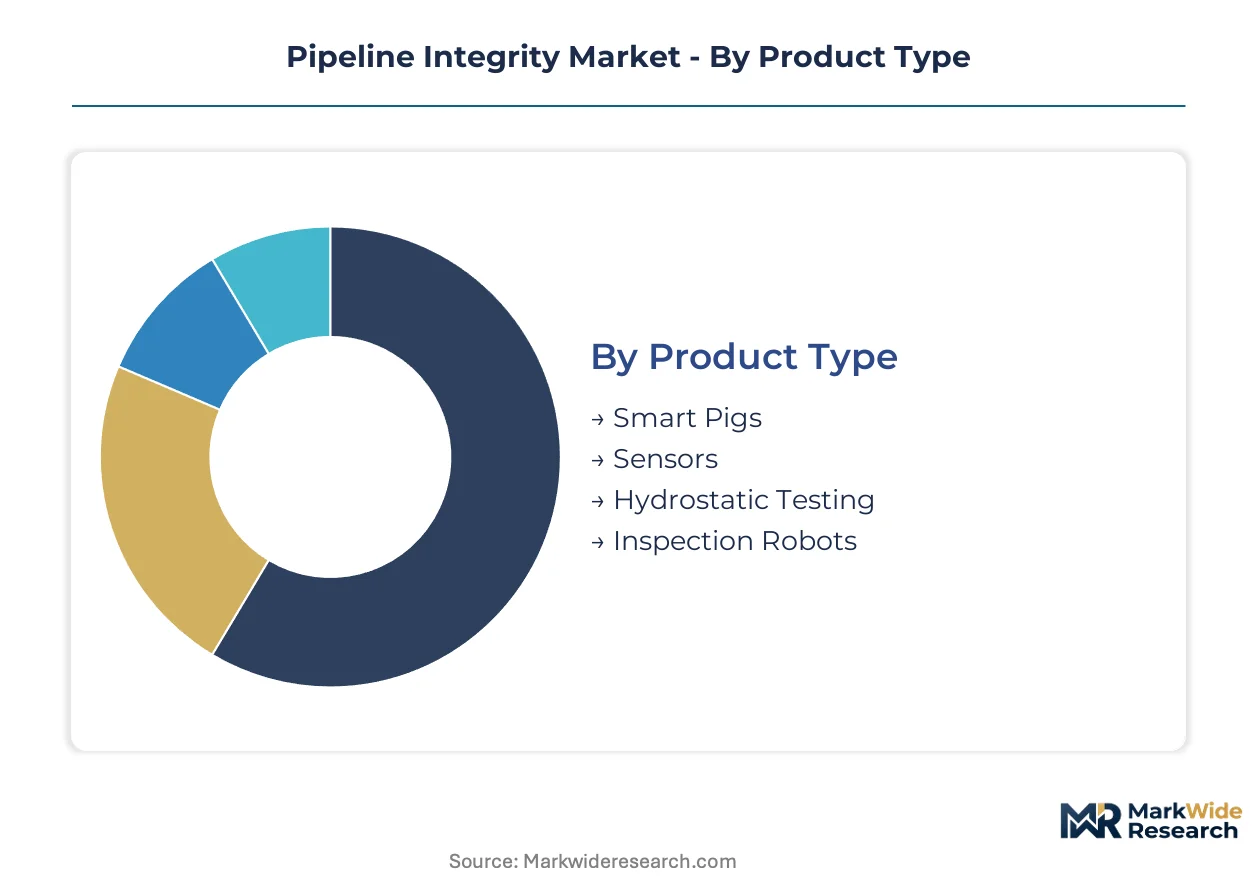
Pipeline integrity procurement patterns diverge sharply across product architectures and inspection methodologies. Technology selection dictates capital intensity cycles, while end-use verticals impose distinct regulatory compliance burdens and operational tempo requirements.
Product Type:
Margin pools concentrate in autonomous inspection platforms that compress cycle times and reduce pipeline downtime costs.
- Smart Pigs:Inline inspection tools equipped with magnetic flux leakage or ultrasonic sensor arrays traverse pressurized pipelines at velocities up to 5 meters per second. PHMSA-mandated inspection intervals for high-consequence areas in Texas and Oklahoma sustain fleet replacement demand among midstream operators.
- Inspection Robots:Robotic crawler systems with electromagnetic acoustic transducers penetrate unpiggable geometries including tight-radius bends and multi-diameter segments. Alberta oil sands operators deploy these units quarterly for sour service corrosion monitoring where conventional pigs cannot operate.
- Sensors:Permanently installed wall-thickness monitors and pressure transducers enable continuous data streams.
- Hydrostatic Testing:Pressure-based integrity verification remains mandatory for new construction certification and post-repair validation.
Smart pigs hold installed capacity. Inspection robots are rotating up the share rankings.
Technology:
Cost tiers separate premium ultrasonic systems from standardized magnetic flux leakage deployments.
- Ultrasonic:High-frequency pulse-echo and phased-array systems deliver sub-millimeter wall-thickness resolution for subsea and high-temperature lines. German and Japanese piezoelectric crystal supply constraints limit rapid scaling of transducer manufacturing for frontier offshore programs.
- Magnetic Flux Leakage:MFL tools detect metal loss anomalies through magnetic field distortion mapping at operating pressures exceeding 200 bar. Texas Permian Basin operators favor this technology for crude trunk lines where speed and cost efficiency outweigh ultrasonic precision requirements.
- Electromagnetic:Eddy current and remote field testing variants address crack detection in ferromagnetic materials.
- Thermal:Infrared and distributed temperature sensing supports leak detection and flow assurance monitoring.
Magnetic flux leakage dominates current deployment volumes. Ultrasonic commands the steepest expansion trajectory in subsea applications.
End User:
Application maturity varies across verticals with divergent risk tolerance and regulatory exposure.
- Oil & Gas:Midstream transmission operators face PHMSA and National Energy Board mandates driving the largest absolute integrity spending. Alberta oil sands and Texas shale corridors generate concentrated demand for corrosion-resistant inspection technologies in sour service and high-paraffin environments.
- Chemical Processing:Petrochemical complexes require specialized crack-detection protocols for stress corrosion cracking in amine and chloride service. Facilities along the US Gulf Coast deploy continuous monitoring systems to satisfy EPA risk management plan requirements.
- Water Supply:Municipal distribution networks prioritize leak detection and pressure management over structural wall-thickness verification.
- Power Generation:Cooling water and feedwater pipelines in thermal plants drive periodic inspection contracts.
Oil & gas holds installed capacity. Chemical processing is rotating up the share rankings.
Application:
Customer type separates continuous monitoring subscriptions from periodic inspection contracts.
- Corrosion Monitoring:Electrochemical and ultrasonic wall-thickness tracking addresses internal and external degradation mechanisms. Canadian oil sands operators combine inline inspection with external direct assessment to satisfy National Energy Board defect response timelines measured in days.
- Leak Detection:Fiber optic distributed acoustic sensing and satellite thermal imaging displace conventional mass-balance methods. Permian Basin midstream operators subscribe to real-time monitoring platforms that reduce response latency from hours to minutes.
- Structural Assessment:Fitness-for-service evaluations and remaining life calculations support maintenance prioritization.
- Maintenance Planning:Predictive integrity frameworks integrate inspection data with corrosion growth models.
Corrosion monitoring holds installed capacity. Leak detection is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Keystone Pipeline System anchors Canadian export capacity to the US Gulf Coast, while the Permian Basin gathering networks in Texas concentrate North American integrity spending. PHMSA mandates and National Energy Board regulations reshape procurement cycles across continental corridors.
United States
Texas shale corridors generate concentrated demand for corrosion-resistant inspection technologies in high-paraffin crude environments. PHMSA now mandates expanded inline inspection intervals for high-consequence areas, compressing equipment replacement cycles. The Permian Basin midstream operators deploy real-time monitoring platforms that reduce leak response latency from hours to minutes.
Canada
Alberta oil sands sour service conditions accelerate wall-thickness degradation, sustaining demand for ultrasonic testing. The National Energy Board Onshore Pipeline Regulations mandate defect response timelines measured in days rather than weeks for certain crack indications. High-consequence areas near populated zones in Ontario and British Columbia face the most stringent compliance windows.
Germany
Industrial pipeline networks serving the Rhine-Ruhr chemical corridor require specialized crack-detection protocols. The EU Pressure Equipment Directive and Industrial Emissions Directive extend compliance burdens across transmission networks. Bavaria's petrochemical complexes deploy continuous monitoring systems to satisfy risk management requirements.
United Kingdom
North Sea subsea infrastructure demands premium ultrasonic systems where alternative methods degrade. Health and Safety Executive offshore regulations govern deepwater inspection protocols below 1,500 meters. Aberdeen's subsea engineering cluster faces elevated insurance premiums due to non-trivial tool recovery risks in frontier programs.
Australia
Coal seam gas pipelines in Queensland and Western Australia iron ore slurry lines drive integrity spending. The country's national pipeline regulator mandates fitness-for-service evaluations for aging onshore transmission assets. Perth-based operators combine inline inspection with external direct assessment for remote desert infrastructure.
Pipeline Integrity Market Competitive Environment
Concentration sits with diversified energy service conglomerates and specialized inspection technology developers. The vendor base separates into three tiers: integrated sensor-to-software platforms, pure-play inline inspection service providers, and niche robotics manufacturers for unpiggable geometries. Dominant competitive moves include multi-year framework agreement consolidation and technology licensing partnerships for electromagnetic acoustic transducer miniaturization.
Within the diversified energy services tier, Baker Hughes Company and SGS S.A. exemplify integrated platform strategies. ROSEN Group occupies a specialized position among smart pig manufacturers for complex pipeline geometries. T.D. Williamson, Inc. represents the established inspection service archetype with deep roots in North American corridor markets.
| Leading Market Players |
|---|
| T.D. Williamson, Inc. |
| SGS S.A. |
| Baker Hughes Company |
| Intertek Group plc |
| Bureau Veritas S.A. |
| ROSEN Group |
| Applus+ S.A. |
| Quest Integrity Group |
| MISTRAS Group, Inc. |
| Others |
Value Chain & Pricing Dynamics
Electromagnetic acoustic transducer miniaturization displacing conventional piezoelectric arrays redraws component sourcing maps from Germany and Japan toward South Korean semiconductor fabrication hubs, compressing sensor procurement costs while introducing new certification bottlenecks for high-temperature tool variants.
Pricing Analysis
Volume-discount tiering structures separate framework agreement holders from spot-contract operators, with three-tier pricing stratification across premium ultrasonic systems, standard magnetic flux leakage platforms, and economy-grade rental pigs. PHMSA certification grade and annual barrel-mile throughput volume constitute the primary price differentiation drivers. Cost compression in the economy tier intensifies as Chinese inspection robot manufacturers penetrate North American markets through Mexico energy reform corridors. Independent midstream operators in Oklahoma and Texas display acute price sensitivity, whereas integrated majors prioritize uptime guarantees over unit economics.
Supply Chain Analysis
German and Japanese piezoelectric crystal manufacturing chokepoints constrain ultrasonic transducer scaling for frontier offshore programs, tethering high-resolution tool production to Southeast Asian rare earth processing centers. High-grade magnetic alloys and corrosion-resistant sensor housings draw from nickel concentrate flows through Indonesian smelters and Chinese refining complexes. Single-source vulnerability in electromagnetic acoustic transducer supply elevates insurance premiums and extends lead times for unpiggable robotics. Distribution runs through authorized service depots in Houston, Calgary, and Aberdeen that pre-position inspection assets for rapid-deployment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pipeline integrity procurement is rotating toward subscription-based monitoring platforms where data-analytics services expand addressable revenue per pipeline mile faster than hardware replacement cycles, creating durable recurring-revenue attach opportunities for equipment manufacturers.
For Market Incumbents: Consolidate inspection contract portfolios through multi-year framework agreements that lock in Permian Basin and Alberta corridor volumes before emerging robotics specialists capture unpiggable line segments. PHMSA mandate expansion threatens to fragment procurement across dozens of qualified vendors; backward integration into electromagnetic acoustic transducer manufacturing secures supply continuity and margin control against German-Japanese supply bottlenecks.
For New Entrants and Emerging Players: NEB-PHMSA cross-border certification fast-tracks open immediate addressable market in US-Canada transmission corridors where established players face qualification friction. Mexico energy reform infrastructure presents the most penetrable geography, with Pemex and private midstream entrants building greenfield capacity without legacy inspection vendor relationships. Target integrity-as-a-service platform positioning that bundles robotic deployment with real-time data subscriptions rather than competing on hardware specifications alone.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors predictive analytics specialists over pure-play hardware manufacturers. Long-term viability across the projection horizon rests on software-enabled recurring revenue models rather than transactional inspection contracts. Acquisition target archetype: electromagnetic acoustic transducer developers with miniaturization IP and established NEB qualification pathways. The signal to watch is fiber optic distributed acoustic sensing displacement rates in Texas Permian corridors as real-time monitoring subscriptions erode periodic pig-run economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Framework Agreement Consolidation | SGS S.A. and Baker Hughes Company leverage volume commitments to lock in PHMSA-mandated inspection intervals across Gulf Coast refining corridors. |
| Electromagnetic Acoustic Transducer Miniaturization | ROSEN Group and Quest Integrity Group penetrate six-inch gathering lines previously excluded from integrity programs in Alberta oil sands. |
| Integrity-as-a-Service Platform Launch | Subscription-based real-time monitoring displaces periodic inspection contracts as Permian Basin operators reduce leak response latency. |
| Cross-Border Certification Harmonization | Tool operators streamline PHMSA and National Energy Board qualification requirements to capture US-Canada corridor contracts. |
| Carbon Capture Pipeline Integrity Protocol Development | Specialized crack-detection and corrosion modeling capabilities open adjacent equipment categories for CO2 transport networks. |
Study Parameters
Cross-validation between inline inspection operator interviews and PHMSA incident database records anchors the qualitative findings on regulatory compliance burdens and defect response timelines. Primary fieldwork encompassed integrity managers at midstream operators, smart pig fleet directors, ultrasonic transducer procurement leads, and NEB qualification specialists. Secondary validation drew from PHMSA pipeline safety reports, National Energy Board regulatory filings, SEC 10-K disclosures from diversified energy service conglomerates, and customs data on high-grade magnetic alloy imports. Bottom-up equipment procurement modeling triangulated against top-down pipeline mileage expansion projections across the analysis window.
Sensitivity analysis around inspection interval compression scenarios and electromagnetic acoustic transducer adoption curves shapes the forecast framework. Segmentation dimensions span product architecture, technology methodology, end-use vertical, and application type, with additional modeling of regulatory jurisdiction clusters distinguishing continuous monitoring mandates from periodic inspection regimes. CAGRs derive from equipment replacement cycle analysis correlated with pipeline age distributions and PHMSA high-consequence area designations. Forecast inputs incorporate Alberta oil sands sour service degradation rates and Permian Basin real-time monitoring subscription growth.
Decision-makers should treat outputs as directional under base assumptions of sustained PHMSA mandate enforcement and stable nickel-rare earth supply flows; material deviation in regulatory stringency or Southeast Asian processing center disruptions would warrant model refresh. Practitioners should keep alternative scenarios live as unpiggable robotics penetration rates and fiber optic sensing displacement dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Whipstocks Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Drill Collar Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Asia- Pacific Drilling Market