
 Oil Drain Valves Market | 2026-2036
Oil Drain Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Drain Valves Market Analytics
Asset-light leasing models for industrial maintenance equipment is tilting competitive dynamics toward suppliers with flexible financing partnerships. Flowserve Corporation leverages its global service network to sustain aftermarket revenue streams. Emerson Electric Co. anchors its position through integrated digital monitoring capabilities embedded in valve systems. Baker Hughes Company differentiates via specialized alloy formulations suited for high-temperature oil and gas applications.
An oil drain valve is a mechanical device engineered to control the release of lubricating fluids from engines, gearboxes, and industrial reservoirs, typically constructed with threaded brass or stainless steel bodies rated for pressures between 50 and 150 psi and temperatures exceeding 200°C. Its primary function is to enable controlled, spill-free fluid evacuation during scheduled maintenance cycles. Automatic valves lead the product type category due to labor cost savings in fleet and industrial settings, while pneumatic variants represent the fastest-growing segment as compressed-air infrastructure expands in automated facilities. Stainless steel dominates the material category on corrosion resistance metrics, though aluminum gains traction in weight-sensitive automotive platforms.
EPA regulations mandate secondary containment provisions for oil handling equipment, directly influencing valve sealing standards and material certification requirements. OSHA workplace safety directives enforce drip-free operation specifications, pushing manufacturers toward enhanced gasket and thread-sealing designs. The EU REACH framework restricts certain brass alloy compositions, compelling European suppliers to reformulate material specifications for export compliance. Stakeholders must monitor evolving refrigerant-fluid compatibility standards as synthetic lubricant formulations proliferate across end-use sectors.
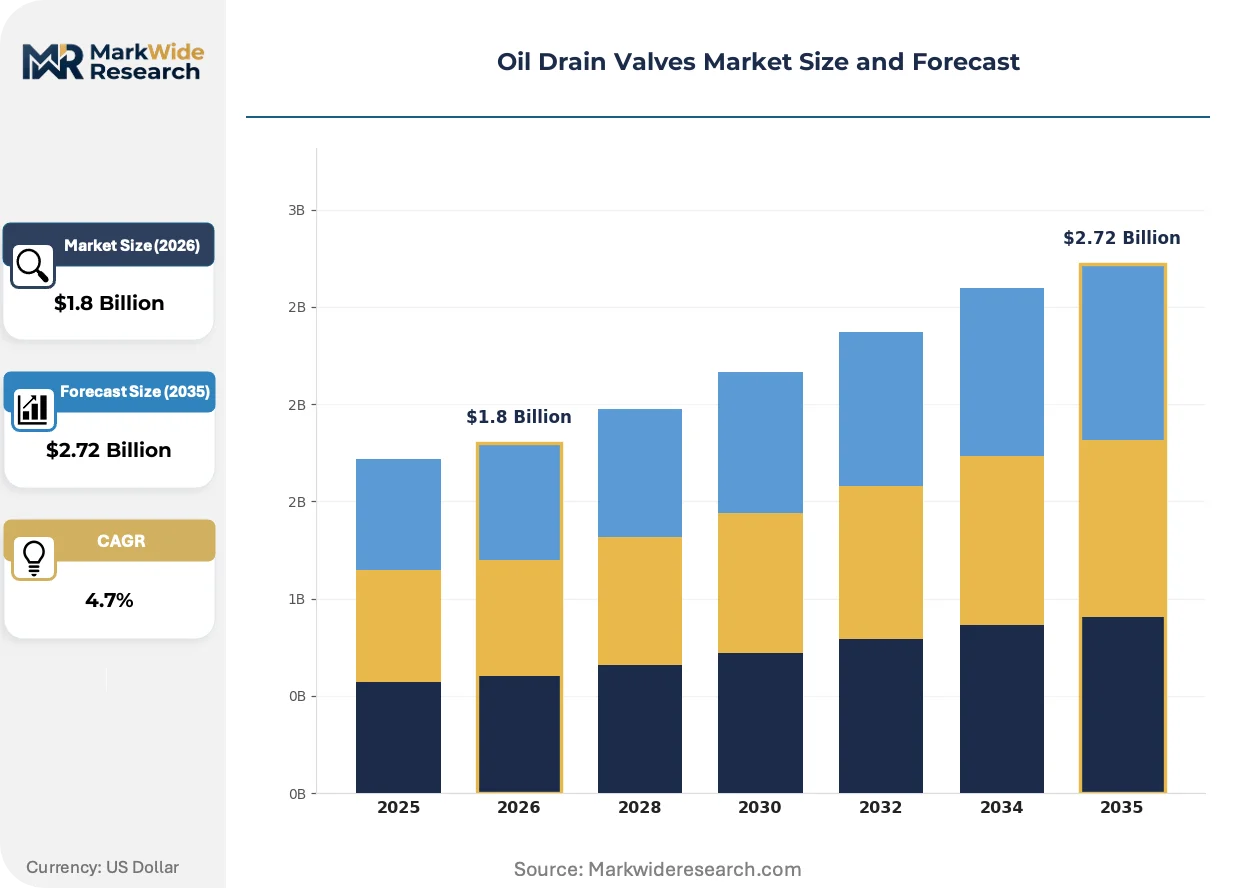
Market Dynamics
Automotive fleet electrification is fragmenting lubrication-system architectures, forcing valve manufacturers to engineer modular designs that span both internal combustion and hybrid thermal management loops without duplicating tooling investments.
Growth Catalysts
- EPA Secondary Containment Mandates:Tighter spill-prevention rules for oil handling equipment are compelling service centers to replace conventional drain plugs with sealed valve systems certified for drip-free operation.
- Compressed-Air Infrastructure Expansion:Pneumatic valve variants are capturing share in automated maintenance facilities where labor cost pressures favor push-button fluid evacuation over manual wrench operations.
- Germany's Precision Manufacturing Corridor:Industrial maintenance protocols in Baden-Württemberg and Bavaria favor premium stainless-steel valve systems with integrated flow monitoring for predictive maintenance integration.
Market Restraints
- Copper-Zinc Alloy Input Volatility:Brass body formulations face cost pressure from fluctuating copper futures, squeezing margin on mid-tier product lines where material substitution remains technically constrained.
- REACH-Compliant Reformulation Costs:EU restrictions on lead-containing brass alloys are forcing European suppliers to retool casting processes, creating compliance friction for export-oriented manufacturers.
- Synthetic Lubricant Compatibility Gaps:Advanced ester-based and polyalkylene glycol formulations degrade conventional nitrile gaskets, requiring accelerated R&D cycles for seal material validation.
Strategic Opportunities
- India's Commercial Vehicle Fleet Modernization:The country's PLI scheme for automotive components is creating localized demand for durable drain valves in heavy-duty truck service networks.
- Digital Monitoring Convergence:Integration of IoT flow sensors with mechanical valve bodies enables condition-based maintenance contracts for industrial lubrication systems.
- Refrigerant-Fluid Standard Evolution:New synthetic lubricant categories for low-GWP refrigerants are opening specification windows for valve suppliers with advanced material testing capabilities.
Industry Challenges
- Multi-Standard Certification Timelines:Simultaneous EPA, REACH, and ISO validation requirements extend product launch cycles by 8-14 months for cross-border suppliers.
- Legacy System Integration Complexity:Retrofit valve installations in aging industrial reservoirs require custom adapter fabrication, fragmenting production economics for low-volume legacy configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Drain Valves Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Valves, Automatic Valves, Pneumatic Valves, Electric Valves End User: Automotive, Industrial Machinery, Marine, Oil & Gas Material: Stainless Steel, Brass, Aluminum, Plastic Application: Engine Oil Change, Lubrication Systems, Fluid Transfer, Maintenance |
| Companies Covered | Flowserve Corporation, Emerson Electric Co., Baker Hughes Company, Valcor Engineering Corporation, Crane Fluid Systems, Zhejiang BaoShiJia Valve Co.ltd., Plast-O-Matic Valves, Inc., SMC, IMI plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Drain Valves Market Evolving Landscape
Material science advances and regulatory tightening are compressing product lifecycles while opening premium tiers for intelligent valve systems with embedded diagnostics and predictive maintenance capability.
Stainless steel valve construction is migrating from corrosion-resistant brass alternatives in marine and chemical processing environments toward mainstream automotive service applications. Fleet maintenance operators in the United States are adopting 316-grade stainless units at triple the pace of five years prior. This migration from premium-niche to volume-standard positioning is compressing price premiums and forcing brass-specialist suppliers to defend position through alloy innovation.
REACH substance restrictions are compelling reformulation of lead-free brass alloys across European supply chains. The industrial consequence spans elevated raw material qualification costs and extended homologation timelines for export-bound product lines. German valve manufacturers are responding fastest, leveraging proximity to ECHA technical guidance and domestic foundry partnerships to front-run compliance deadlines.
Service contract unbundling is fragmenting traditional distribution relationships in North American fleet maintenance. Independent service providers are sourcing valves directly from manufacturers rather than through integrated distributors, compressing channel margins and favoring suppliers with direct digital procurement platforms. This pattern is most visible in California's commercial vehicle service networks, where consolidated fleet operators wield procurement leverage.
Oil Drain Valves Market Segmentation
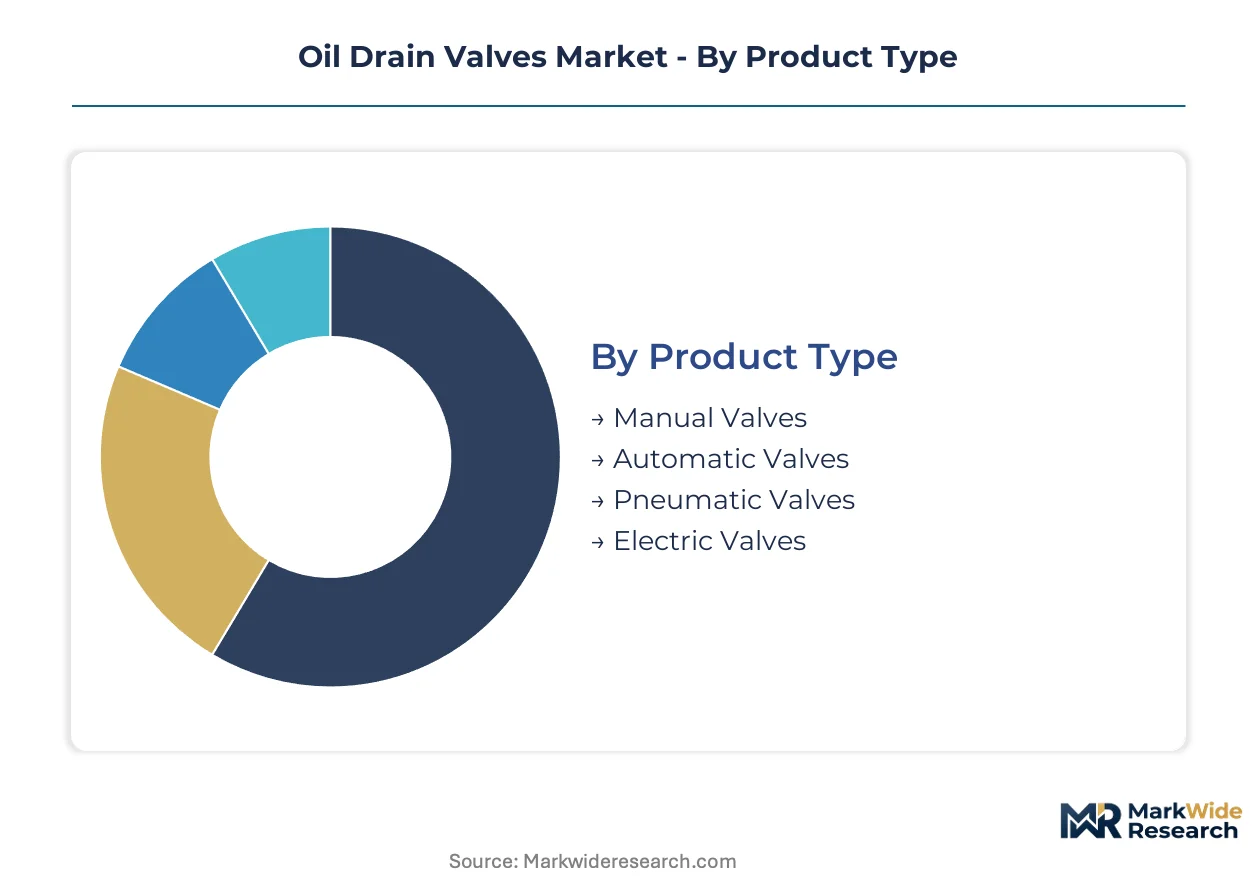
Segmentation in oil drain valves reveals distinct replacement cycles and margin profiles across mechanical, pneumatic, and electric actuation technologies. Material selection and end-use severity create tiered durability requirements that reshape supplier priorities and distribution economics.
Product Type:
Replacement velocity diverges sharply across actuation technologies, with manual units turning over fastest in high-wear fleet environments while pneumatic systems endure longest in controlled industrial settings.
- Automatic Valves:Spring-loaded or gravity-actuated mechanisms eliminate wrench operations and reduce service time in commercial fleet bays. Demand concentrates in United States automotive service centers where labor cost pressures and EPA spill-prevention mandates accelerate plug-to-valve conversions. Fleet operators in California's consolidated truck service networks specify these units for high-frequency oil change intervals.
- Pneumatic Valves:Compressed-air actuation enables push-button fluid evacuation in automated maintenance facilities. Expansion concentrates in Germany's precision manufacturing corridor where Baden-Württemberg industrial protocols favor push-button operation over manual wrenching for predictive maintenance integration.
- Manual Valves:Lever or quarter-turn mechanisms dominate legacy equipment retrofit applications where compressed-air infrastructure remains absent.
- Electric Valves:Solenoid-actuated designs serve specialized fluid transfer systems requiring remote operation capability.
Automatic valves dominate installed base in commercial automotive service. Pneumatic valves are where expansion concentrates fastest.
End User:
Application severity and regulatory exposure create tiered material specifications, with marine and oil & gas environments demanding corrosion-resistant alloys while automotive volume favors cost-optimized formulations.
- Automotive:Passenger vehicle, commercial truck, and fleet maintenance applications drive volume demand with standardized thread patterns and pressure ratings. United States service centers represent the primary demand concentration under tightening EPA secondary containment mandates. California consolidated fleet operators wield direct procurement leverage, bypassing traditional distributors.
- Industrial Machinery:Manufacturing equipment, power generation, and processing plant applications require extended duty cycles and predictive maintenance compatibility. Germany's Bavaria industrial cluster favors premium stainless-steel units with integrated flow monitoring for condition-based service contracts.
- Marine:Saltwater exposure necessitates 316-grade stainless construction for corrosion resistance in offshore and coastal vessel applications.
- Oil & Gas:High-temperature reservoir drainage and hazardous location classifications drive specialized alloy specifications.
Automotive commands volume scale. Industrial machinery is where premium pricing and digital monitoring integration concentrate.
Material:
Corrosion resistance requirements and weight constraints create divergent cost-performance tradeoffs, with stainless steel migrating from premium niche toward mainstream positioning while aluminum gains traction in weight-sensitive platforms.
- Stainless Steel:304 and 316-grade alloys deliver superior corrosion resistance and temperature tolerance exceeding 200°C. United States fleet operators adopt 316-grade units at accelerated pace for marine and chemical-adjacent service applications, compressing historical price premiums.
- Brass:Copper-zinc formulations face input cost volatility and EU REACH compliance pressure for lead-free reformulation. German manufacturers leverage domestic foundry partnerships to front-run ECHA substance restrictions.
- Aluminum:Weight reduction priorities in automotive OEM platforms favor forged aluminum bodies for original equipment fitment.
- Plastic:Polymer formulations serve low-pressure, cost-constrained aftermarket applications with limited temperature exposure.
Stainless steel dominates value capture. Brass retains share where REACH-compliant reformulation costs permit competitive positioning.
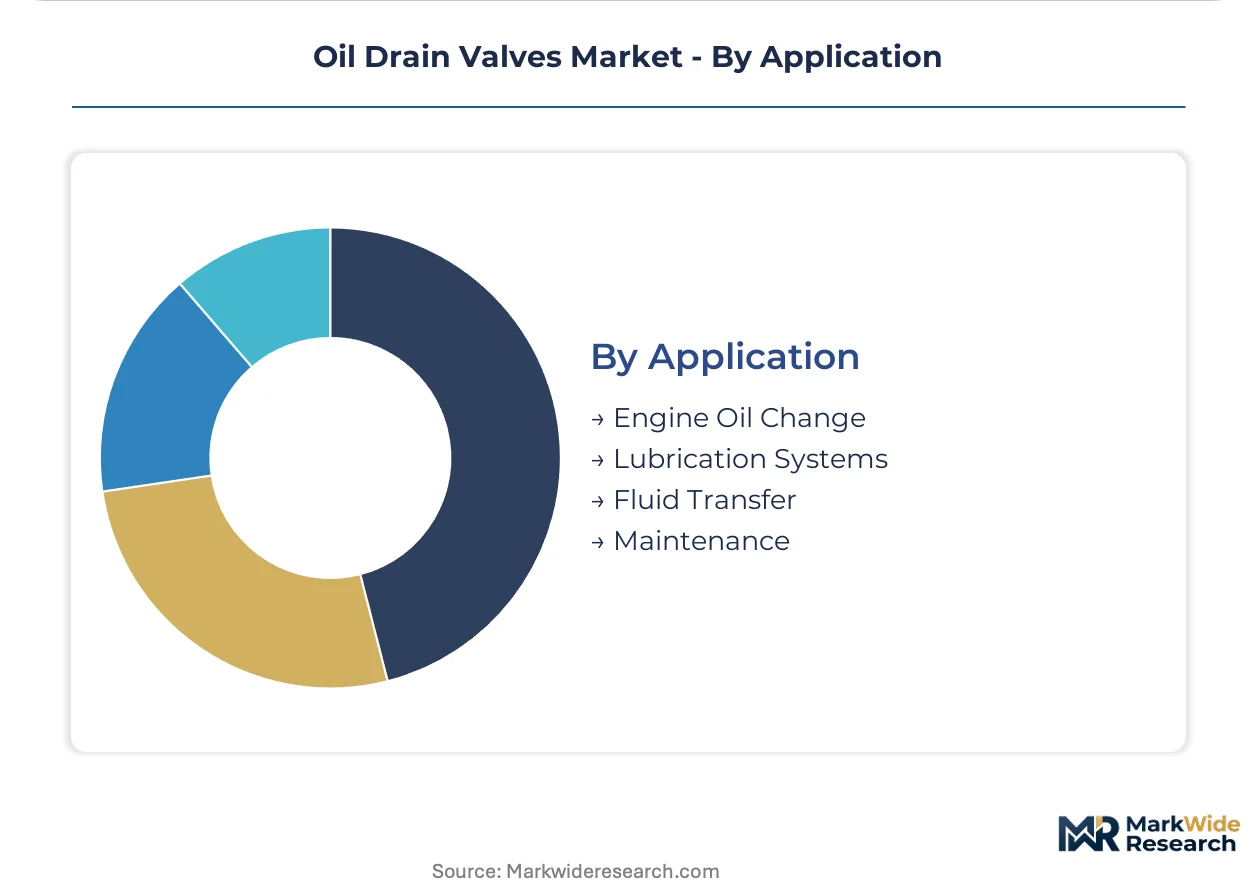
Application:
Service frequency and fluid compatibility requirements segment demand by operational intensity, with engine oil change driving replacement velocity and lubrication systems enabling premium monitoring integration.
- Engine Oil Change:Scheduled drain intervals in internal combustion and hybrid thermal management loops generate recurring replacement demand. India's commercial vehicle fleet modernization under PLI scheme incentives creates localized demand concentration in heavy-duty truck service networks.
- Lubrication Systems:Centralized industrial lubrication circuits enable condition-based maintenance contracts with IoT flow sensor integration. Germany's precision manufacturing corridor favors predictive maintenance compatibility.
- Fluid Transfer:Inter-reservoir pumping and bulk handling applications require specialized port configurations and flow rate specifications.
- Maintenance:General service and repair operations span retrofit installations in aging equipment with custom adapter requirements.
Engine oil change commands replacement frequency. Lubrication systems enable premium tier expansion through digital monitoring convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial buyers extract 15-20% price premiums for predictive-maintenance-compatible valve systems, while Indian fleet operators prioritize unit cost over monitoring integration. This asymmetry fragments supplier strategies across developed and emerging demand centers.
United States
California's consolidated commercial fleet operators wield direct procurement leverage, bypassing traditional distributors for high-volume automatic valve contracts. EPA secondary containment mandates accelerate plug-to-valve conversions in automotive service centers. The Midwest industrial corridor sustains demand for pneumatic variants in automated maintenance facilities.
Germany
Baden-Württemberg and Bavaria industrial clusters favor premium stainless-steel systems with integrated flow monitoring for condition-based service contracts. ECHA REACH substance restrictions compel lead-free brass alloy reformulation across domestic foundry partnerships. Stuttgart-area precision manufacturers specify predictive maintenance compatibility as standard procurement criteria.
India
Heavy-duty truck service networks in Maharashtra and Gujarat generate localized demand under the PLI scheme for automotive components. Central government fleet modernization programs prioritize durable drain valves for commercial vehicle applications. Tamil Nadu automotive manufacturing clusters are developing component supplier ecosystems.
China
Yangtze River Delta industrial zones drive pneumatic valve adoption in automated manufacturing maintenance facilities. MIIT equipment safety standards tighten specifications for fluid handling in heavy machinery applications. Shanghai-area fleet operators are consolidating procurement through digital platforms.
Japan
Kanto region automotive service chains specify corrosion-resistant 316-grade stainless units for hybrid thermal management systems. METI industrial efficiency guidelines promote predictive maintenance integration in lubrication systems. Nagoya-area manufacturing equipment suppliers favor modular valve designs spanning combustion and electric powertrains.
Oil Drain Valves Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and actuation niches. The vendor base stratifies across three tiers: multinational flow-control conglomerates with integrated digital portfolios, regional brass-forging specialists defending mid-market share, and niche pneumatic component suppliers capturing automated facility expansion. Consolidation pressure concentrates among mid-tier brass specialists facing copper input volatility and REACH compliance costs. Strategic moves center on predictive maintenance technology licensing and backward integration into specialty alloy casting.
Within the multinational system tier, Flowserve Corporation and Emerson Electric Co. occupy positions defined by global service infrastructure and embedded monitoring capabilities respectively. Baker Hughes Company anchors the specialized alloy segment for high-temperature applications. Zhejiang BaoShiJia Valve Co.ltd. represents the regional specialist archetype, while Valcor Engineering Corporation exemplifies precision engineering positioning in pneumatic actuation systems.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Emerson Electric Co. |
| Baker Hughes Company |
| Valcor Engineering Corporation |
| Crane Fluid Systems |
| Zhejiang BaoShiJia Valve Co.ltd. |
| Plast-O-Matic Valves, Inc. |
| SMC |
| IMI plc |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese brass-forging operations is compressing mid-tier valve pricing while simultaneously pushing German and US suppliers toward premium stainless-steel positioning to escape margin erosion. This utilization asymmetry creates divergent supplier behaviors: Asian contract manufacturers absorb volume at thin spreads, while Western incumbents capture value through REACH-compliant alloy certification and predictive maintenance integration.
Pricing Analysis
Configured-to-order pricing for custom adapter fabrications commands spreads of 40-60% above standard catalog units, reflecting the engineering overhead for legacy reservoir retrofits. Three-tier pricing structure across premium, standard, and economy levels separates 316-grade stainless systems with IoT flow monitoring from brass-body manual valves and commodity plastic alternatives. Cost compression in brass mid-tiers is intensifying because copper-zinc futures volatility transfers directly to spot pricing. Fleet operators in California's consolidated truck service networks exhibit highest price sensitivity, while Baden-Württemberg precision manufacturers accept premium positioning for predictive maintenance compatibility.
Supply Chain Analysis
Contract-manufacturing concentration rests with Zhejiang and Guangdong province foundries for brass body castings, with German domestic partnerships anchoring lead-free alloy reformulation capacity. Geographic supply concentrates in China for raw brass inputs, Germany for REACH-certified specialty alloys, and the United States for 316-grade stainless distribution. Raw material dependencies draw from copper futures markets, nitrile and fluorocarbon gasket polymers, and precision-machined thread inserts. Single-source vulnerability in lead-free brass alloy formulations creates compliance risk for European export-bound product lines. Distribution runs through direct digital procurement platforms for consolidated fleet operators, bypassing traditional integrated distributors in North American automotive service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA secondary containment mandates and REACH substance restrictions are accelerating product lifecycle compression, creating windows for suppliers with pre-certified material platforms to capture share from reformulation-lagged competitors. This regulatory inflection favors incumbents with existing compliance infrastructure while raising barriers for undifferentiated new entrants.
For Market Incumbents: Insulate margin position through backward integration into specialty alloy casting capabilities, particularly for lead-free brass formulations that European foundry partnerships currently dominate. Secure captive supply of 316-grade stainless steel to defend against commodity price volatility in marine and chemical-processing applications. Prioritize certification investment in multi-standard validation (EPA, REACH, ISO) to compress launch cycles and outrun reformulation-lagged competitors in cross-border segments.
For New Entrants and Emerging Players: Establish a beachhead in India's heavy-duty truck service networks under PLI scheme incentives, where localized demand for durable drain valves outruns established supplier presence. Target pneumatic valve variants for automated maintenance facilities in China's Yangtze River Delta, where compressed-air infrastructure expansion creates specification windows. Pursue direct digital procurement platform partnerships with California consolidated fleet operators to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with condition-based maintenance contracts and IoT-enabled flow monitoring integration in Germany's precision manufacturing corridor. Long-term viability across the analysis window favors targets with REACH-compliant material platforms and predictive maintenance technology licensing capability. Monitor ECHA substance restriction timelines as inflection indicators for consolidation pressure among mid-tier brass specialists facing retooling cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Casting | Captures margin from lead-free brass reformulation costs imposed by ECHA REACH restrictions. |
| IoT Flow Sensor Platform Integration | Enables condition-based maintenance contracts with Stuttgart-area precision manufacturers. |
| Direct Digital Procurement Platform Launch | Bypasses distributor compression in California consolidated fleet operator relationships. |
| REACH-Compliant Material Certification Investment | Accelerates product launch cycles against reformulation-lagged competitors in European export markets. |
| Pneumatic Valve Capacity Expansion | Captures automated facility demand in Baden-Württemberg industrial maintenance protocols. |
Research Methodology
Cross-validation between primary interviews with maintenance directors at automotive service centers and secondary validation through EPA enforcement action databases anchors the qualitative findings on regulatory compliance drivers. Plant engineers at industrial machinery OEMs, aftermarket service heads at fleet operators, procurement leads at valve distributors, and technical R&D directors at specialty alloy foundries contributed primary perspective. Secondary sources include customs/trade data on brass and stainless steel valve imports, SEC 10-K filings from flow-control conglomerates, OSHA workplace safety directive records, and ECHA substance restriction guidance documents. Bottom-up unit economics and top-down market sizing triangulate volume and value estimates.
Calibration against historical replacement velocity patterns in commercial fleet applications and industrial maintenance contract renewal rates validates projection assumptions across the modeling period. Segmentation dimensions include actuation technology (manual, automatic, pneumatic, electric), material grade (304 stainless, 316 stainless, brass, aluminum, polymer), end-use severity (automotive, industrial machinery, marine, oil and gas), and regional regulatory cluster (EPA-mandated US markets, REACH-governed European markets, PLI-incentivized Indian markets). CAGRs derive from fitted growth curves on replacement cycle compression and technology substitution rates. Industry-specific inputs include copper futures price volatility coefficients and synthetic lubricant compatibility test failure rates.
Macroeconomic conditions sit as an overlay; deviation in commercial vehicle production volumes, industrial capital expenditure cycles, or copper commodity pricing would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology adoption elasticity. Quarterly review of ECHA substance restriction proposal timelines, EPA secondary containment inspection frequency data, and fleet operator procurement consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Subsea Valves Market
Valves
Vaneometer Market
Valves
Liner Regulators Market
Valves
Sand Control System Market
Valves
Axial and Radial Seals Market
Valves
Global Pipeline Safety Market
Valves
Global Valves Market
Valves
Three Way Ball Valve Market
Valves
Global Compression Packing Market
Valves
Total Containment Vessels Market
Valves
Pipeline Strainers Market
Valves
Choke and Kill Manifold Market
Valves
Battery Safety Valve Market
Valves
Lined Valves Market
Valves
Industrial Hydraulic Filters Market
Valves
Valve Remote Control System Market