
 Expansion Valves Market | 2026-2036
Expansion Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Expansion Valves Market Analysis
The EU F-Gas Regulation is broadening the addressable market for expansion valves compatible with R32, R454B, and other lower-GWP refrigerants. Danfoss leverages its refrigerant-agnostic valve platforms to capture retrofit cycles across European HVAC infrastructure. Emerson Electric Co. sustains technology leadership through advanced superheat control algorithms embedded in electronic expansion valve controllers. Sanhua anchors cost-competitive manufacturing scale for brass-bodied thermal expansion valves serving Asian residential air conditioning OEMs.
Expansion valves are precision flow-control devices that regulate refrigerant injection into evaporator coils by maintaining optimal superheat, typically operating across orifice diameters from 0.5 mm to 12 mm and pressure differentials up to 45 bar. Electronic expansion valves dominate margin pools due to their integration with variable-speed compressors and IoT-enabled building management systems, while thermal expansion valves retain volume leadership in cost-sensitive residential air conditioning. Stainless steel valve bodies are gaining specification share in industrial cooling and ammonia-based refrigeration applications where corrosion resistance extends service intervals beyond 15 years.
The EPA Significant New Alternatives Policy program shapes refrigerant approval pathways in the United States, directly influencing valve material compatibility requirements and product certification timelines. China's GB standards for refrigerating appliances, administered by the Standardization Administration, mandate energy efficiency thresholds that elevate electronic expansion valve penetration in domestic heat pump production. Stakeholders must monitor refrigerant phase-down schedules and corresponding valve redesign cycles across multiple jurisdictions to align R&D pipelines with regulatory compliance windows.
Market Dynamics
The refrigerant transition mandated by the EU F-Gas Regulation is forcing valve manufacturers to redesign orifice geometries and seal materials for lower-GWP alternatives, compressing product development cycles while expanding retrofit demand across European HVAC infrastructure.
Growth Catalysts
- Refrigerant compliance mandates:The EU F-Gas Regulation's phase-down schedule is accelerating replacement cycles for thermal expansion valves incompatible with R32 and R454B, pulling forward demand in Germany's building renovation sector.
- Heat pump manufacturing:European residential retrofit programs are expanding production capacity for electronic expansion valves with integrated superheat controllers in variable-speed compressor systems.
- Industrial ammonia refrigeration:Stainless steel valve bodies are penetrating food processing and cold storage applications where corrosion resistance extends service intervals beyond thermal alternatives.
Market Restraints
- Brass price volatility:Thermal expansion valve margins compress when copper and zinc input costs spike, squeezing cost-competitive Asian OEM suppliers.
- Electronic controller concentration:Advanced superheat algorithms and stepper motor drivers rely on semiconductor supply chains concentrated in East Asian foundries.
- Refrigerant testing fragmentation:Divergent approval pathways between EPA SNAP, EU F-Gas, and China's GB standards extend certification timelines for multi-territory product launches.
Strategic Opportunities
- Industrial IoT convergence:Electronic expansion valves with embedded sensors and cloud-connected diagnostics are penetrating smart building management systems in commercial HVAC retrofits.
- India's cooling demand:The country's Bureau of Energy Efficiency mandates for room air conditioners are elevating electronic valve penetration in domestic manufacturing.
- Ammonia refrigeration expansion:Carbon reduction targets in European food logistics are specifying stainless steel valves for industrial cold chain infrastructure.
Industry Challenges
- Refrigerant chemistry expertise:Valve engineers must master compatibility with emerging HFO blends and natural refrigerants where seal swelling and lubricant miscibility differ from legacy HFC systems.
- Controller firmware integration:Electronic expansion valves require seamless communication with variable-speed compressor drives and building automation protocols, complicating OEM qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expansion Valves Market |
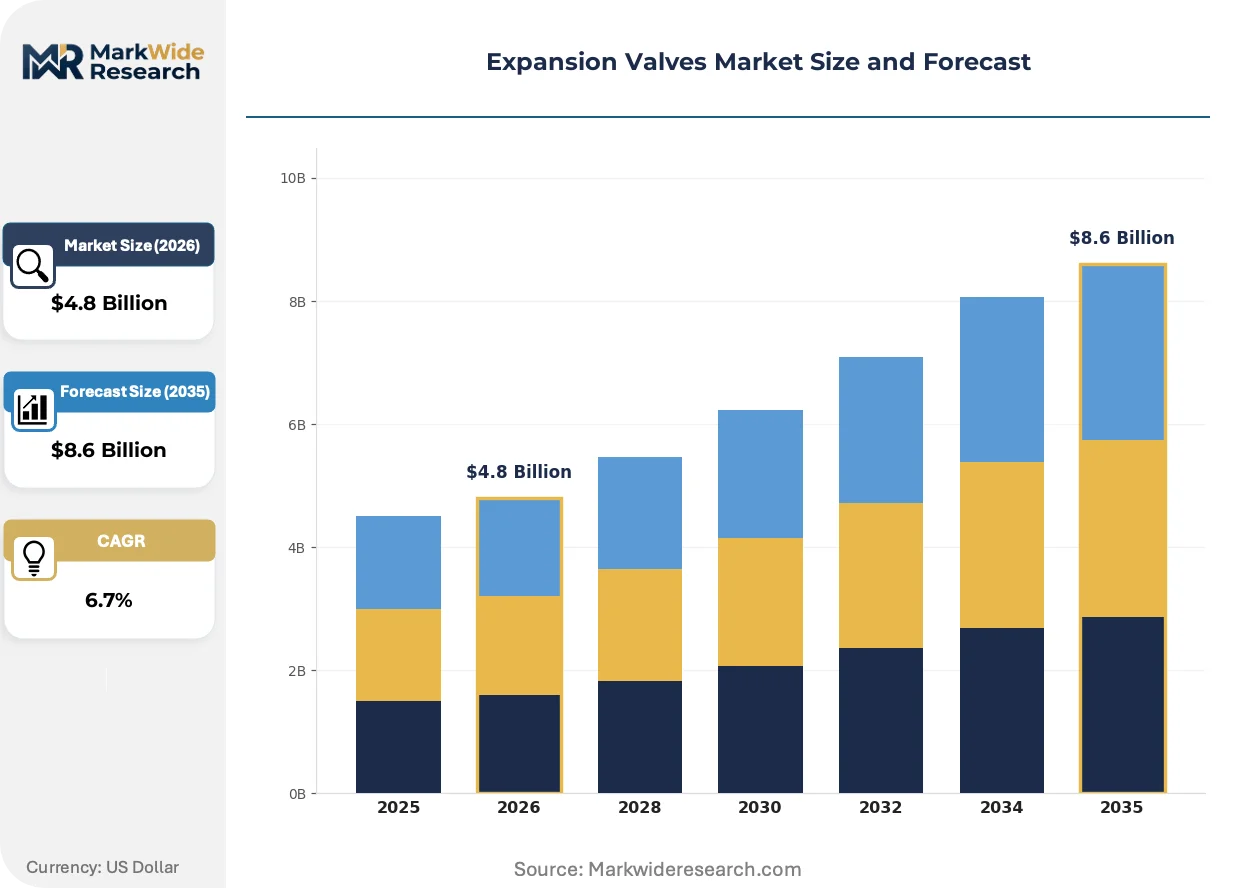
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Expansion Valves, Electronic Expansion Valves, Automatic Expansion Valves, Manual Expansion Valves Application: Air Conditioning Systems, Refrigeration Units, Heat Pumps, Industrial Cooling End User: Residential Users, Commercial Users, Industrial Users, Automotive Sector Material: Copper, Brass, Stainless Steel, Plastic |
| Companies Covered | Danfoss, Emerson Electric Co., Sanhua, Parker Hannifin Corporation, Sporlan, Fujikoki Corporation, CAREL Industries, Alfa Laval, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expansion Valves Market Emerging Trajectories
Refrigerant chemistry evolution is compressing product lifecycles and forcing material science investments across valve portfolios. Three concurrent developments are restructuring competitive positioning.
Electronic superheat control is overtaking capillary tube and thermal bulb architectures in residential heat pump systems. European OEMs are specifying stepper-motor-driven valves with pulse-width modulation for precise refrigerant metering. This precision is compressing warranty claim rates and enabling higher seasonal energy efficiency ratios.
The EPA SNAP program is accelerating refrigerant approval timelines for lower-GWP alternatives in commercial refrigeration. Valve manufacturers must validate elastomer compatibility with R-1234yf and R-454C blends before commercial deployment. Cold storage operators in the United States are delaying equipment procurement until refrigerant-pathway clarity emerges.
Service contracting is unbundling valve replacement from compressor overhaul packages. Industrial refrigeration end-users in Germany are procuring electronic expansion valves through separate maintenance agreements rather than bundled OEM service. This fragmentation is elevating third-party valve distributor influence in aftermarket channels.
Expansion Valves Market Segmentation
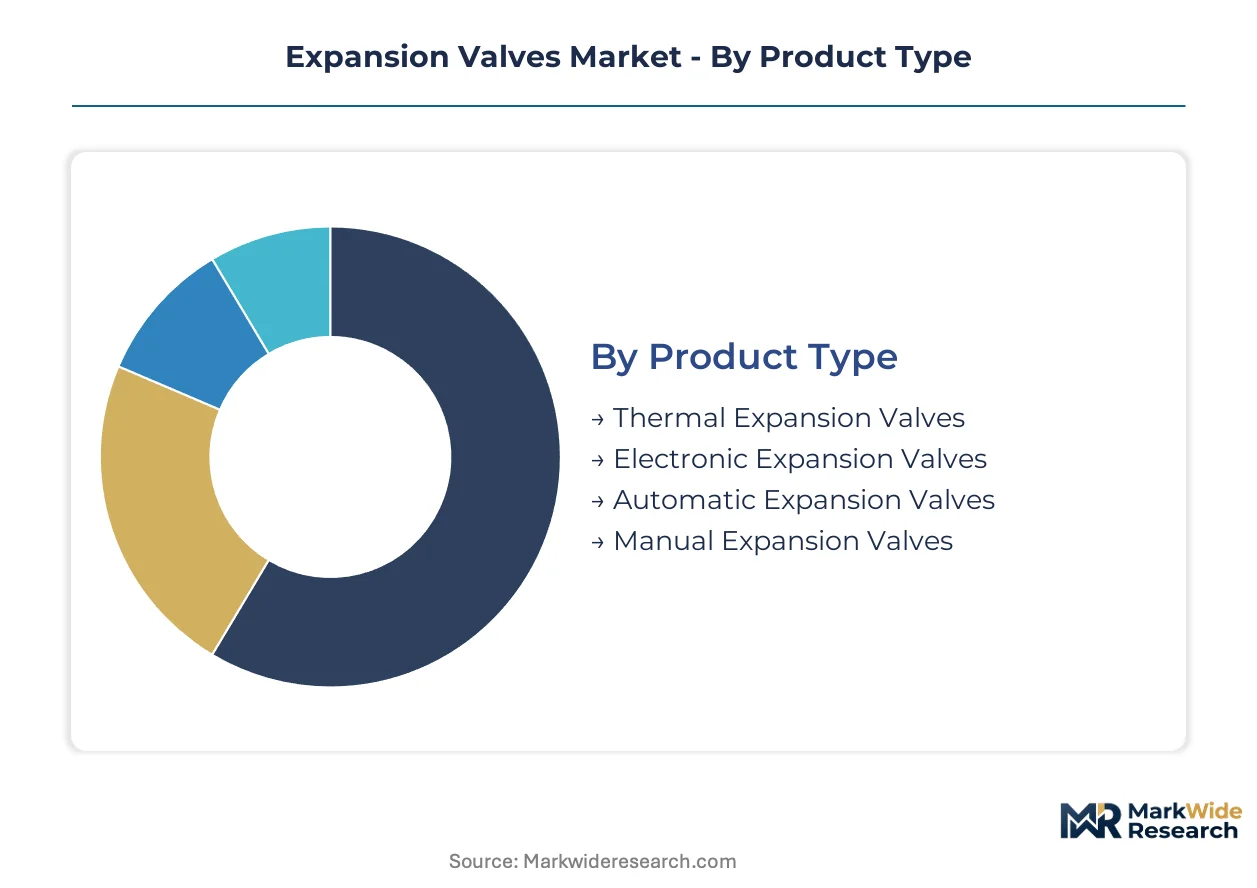
Expansion valve segmentation reveals distinct margin architectures across product architectures and material specifications. Valve manufacturers align R&D portfolios with refrigerant chemistry transitions and end-use durability requirements.
Product Type:
Supply concentration in electronic valve controllers creates tiered competitive dynamics between precision-engineered and commodity flow-control architectures.
- Electronic Expansion Valves:Stepper-motor-driven orifices with pulse-width modulation enable superheat precision within 0.5 Kelvin. Demand concentrates in German residential heat pump retrofits where variable-speed compressor integration is mandatory under EU Ecodesign requirements.
- Thermal Expansion Valves:Brass-bodied bulb-and-capillary architectures rely on refrigerant charge thermodynamics for passive superheat control. Asian residential air conditioning OEMs in China and India specify these for cost-sensitive room units where electronic controller overhead is uneconomical.
- Automatic Expansion Valves:Constant-pressure designs maintain fixed evaporator pressure regardless of load variation.
- Manual Expansion Valves:Hand-adjusted needle mechanisms serve commissioning and service applications where electronic automation is impractical.
Today's leader: Thermal Expansion Valves. Tomorrow's challenger: Electronic Expansion Valves.
Application:
Application-driven procurement patterns split between regulated commercial retrofits and volume residential manufacturing.
- Air Conditioning Systems:Residential and commercial cooling infrastructure specifies expansion valves across ducted, ductless, and packaged rooftop configurations. India's Bureau of Energy Efficiency mandates are elevating electronic valve penetration in domestic room air conditioner production.
- Heat Pumps:Reversible vapor-compression systems for space heating and domestic hot water. European residential retrofit programs in Germany, France, and Poland are expanding production capacity for valves compatible with R32 and R454B refrigerants.
- Refrigeration Units:Commercial and industrial cold storage, display cases, and transport refrigeration.
- Industrial Cooling:Process cooling, data center thermal management, and manufacturing equipment temperature control.
Heat Pumps are climbing the fastest as building decarbonization mandates restructure European HVAC procurement.
End User:
Customer-type segmentation maps to warranty sensitivity, technical specification authority, and aftermarket service contracting models.
- Residential Users:Individual homeowners and multi-family building operators procure valves through OEM equipment channels or emergency replacement. German building renovation subsidies are accelerating heat pump installations with integrated electronic expansion valves.
- Commercial Users:Retail, hospitality, and office building operators specify valves through mechanical contractors and facility management providers.
- Industrial Users:Food processing, chemical manufacturing, and logistics operators demand stainless steel valve bodies with 15-year service intervals in ammonia refrigeration systems.
- Automotive Sector:Electric vehicle thermal management and passenger cabin climate control systems.
Industrial Users command premium pricing for corrosion-resistant specifications. Residential Users drive volume scale through standardized product platforms.
Material:
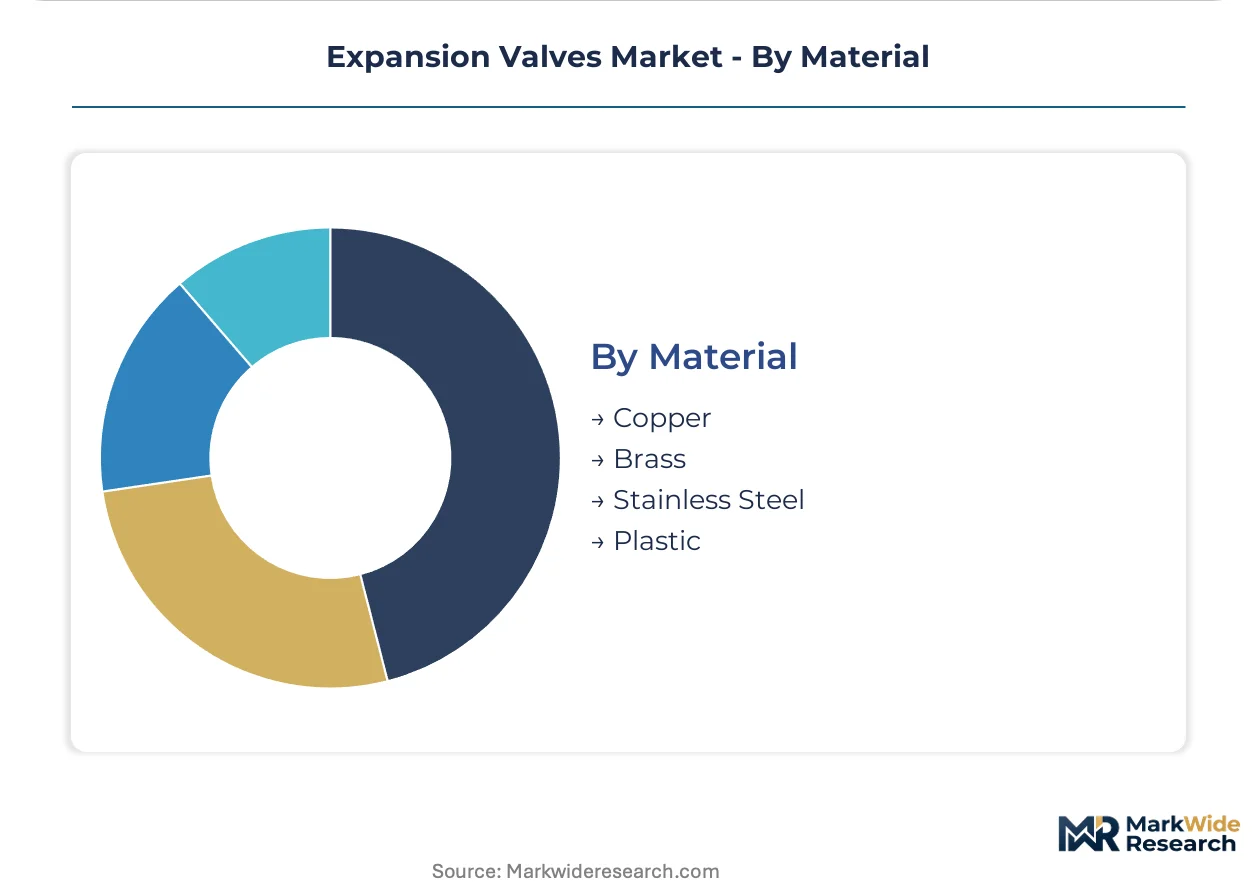
Material selection correlates directly with refrigerant chemistry compatibility and service environment corrosion exposure.
- Brass:Copper-zinc alloys dominate thermal expansion valve bodies for residential air conditioning. Cost volatility in London Metal Exchange copper and zinc pricing compresses margins for Asian OEM suppliers during commodity spikes.
- Stainless Steel:Austenitic grades 304 and 316 penetrate industrial ammonia refrigeration and food processing applications. European cold chain infrastructure operators specify these for extended service intervals under carbon reduction targets.
- Copper:Pure copper and deoxidized grades serve specialized brazing applications and orifice components.
- Plastic:Engineering polymers including PPS and PEEK insulate electrical components and reduce valve assembly weight in automotive applications.
Brass retains volume leadership in cost-optimized residential segments. Stainless Steel is gaining specification share in regulated industrial refrigeration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in precision fluid dynamics and refrigerant systems engineering concentrate in industrial clusters across Germany, the United States, China, Japan, and India. These workforce concentrations anchor manufacturing and R&D capabilities for expansion valve technologies serving HVAC and refrigeration infrastructure worldwide.
Germany
Building renovation subsidies and district heating conversions are accelerating heat pump installations across Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation mandates refrigerant transitions toward R32 and R454B, forcing valve redesigns for compatibility. Stuttgart's industrial corridor hosts precision machining facilities producing electronic expansion valves with integrated superheat controllers for residential retrofit programs.
United States
Commercial refrigeration retrofits and data center cooling expansion are elevating demand for stainless steel valve specifications. The EPA SNAP program governs approval pathways for lower-GWP refrigerants, directly influencing product certification timelines. Texas and California industrial zones concentrate cold storage infrastructure operators procuring ammonia-compatible valves for extended service intervals.
China
Domestic heat pump manufacturing scale and room air conditioner production dominate volume demand for brass-bodied thermal expansion valves. GB standards administered by the Standardization Administration mandate energy efficiency thresholds elevating electronic valve penetration. Yangtze River Delta manufacturing clusters supply cost-optimized valve assemblies for Asian residential OEMs.
Japan
Automotive thermal management for electric vehicles and precision industrial cooling anchor demand for miniaturized electronic expansion valves. METI industrial policy supports refrigerant chemistry research for next-generation heat pump systems. Nagoya's automotive supplier corridor integrates valve technologies into passenger cabin climate control and battery thermal management systems.
India
Bureau of Energy Efficiency mandates for room air conditioners are restructuring domestic manufacturing toward electronic valve architectures. Heat pump deployment in commercial buildings and cold chain infrastructure expansion are broadening addressable demand. Gujarat and Maharashtra industrial zones concentrate HVAC component fabrication serving South Asian residential and commercial markets.
Expansion Valves Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the expansion valve supply base. Integrated manufacturers with captive foundry and machining capabilities command premium positioning in electronic valve controllers, while specialized fabricators focus on thermal expansion valve volumes for cost-sensitive residential segments. Three archetypes dominate: diversified industrial conglomerates with refrigerant-agnostic platforms, precision engineering specialists with stepper-motor control expertise, and commodity-scale brass valve suppliers. Capacity expansion in Asian manufacturing zones and strategic partnerships for IoT-enabled diagnostics represent the dominant competitive vectors reshaping market structure.
Among diversified industrial conglomerates, Danfoss anchors refrigerant-agnostic platform strategies spanning European HVAC retrofit cycles. Emerson Electric Co. exemplifies precision control archetypes with embedded superheat algorithms and building automation integration. Sanhua occupies a position within cost-competitive manufacturing scale for brass-bodied thermal architectures serving Asian residential OEMs. These three represent distinct strategic postures without implying specific market share claims or operational details beyond their visible industry positioning.
| Leading Market Players |
|---|
| Danfoss |
| Emerson Electric Co. |
| Sanhua |
| Parker Hannifin Corporation |
| Sporlan |
| Fujikoki Corporation |
| CAREL Industries |
| Alfa Laval |
| Johnson Controls |
| Others |
Supply Flow & Price Mechanics
German heat pump OEMs and building renovation contractors command pricing leverage through consolidated procurement of electronic expansion valves with integrated superheat controllers. Their specification authority compresses margins for brass-bodied thermal valve suppliers serving cost-sensitive Asian residential air conditioning manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates refrigerant-agnostic electronic controllers from commodity thermal bulb architectures. Price differentiation rests on certification grade for EU F-Gas compliance and volume scale in heat pump retrofit programs. Cost compression in brass thermal valves is intensifying because London Metal Exchange copper and zinc input volatility squeezes Asian OEM supplier margins. Residential air conditioning manufacturers in China and India exhibit highest price sensitivity, while industrial ammonia refrigeration operators in Germany accept premium stainless steel specifications.
Supply Chain Analysis
Direct-to-OEM channels handle European heat pump manufacturer demand for electronic expansion valves with embedded stepper motor drivers. Manufacturing concentrates in China, Germany, and Japan, with Yangtze River Delta clusters supplying cost-optimized brass assemblies and Stuttgart's precision machining facilities producing superheat controllers. Raw material dependencies draw from copper-zinc alloy feedstocks, austenitic stainless steel grades, and semiconductor components for valve actuation. Single-source vulnerability in East Asian foundries supplying stepper motor drivers creates procurement risk. Distribution runs through HVAC equipment OEMs, third-party maintenance contractors, and industrial refrigeration service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European regulatory premiums for F-Gas-compliant electronic valves and Asian cost-optimized manufacturing of thermal architectures for price-sensitive residential cooling.
For Market Incumbents: Acquire refrigerant chemistry testing laboratories and seal material validation facilities to compress product development cycles for R32 and R454B compatibility. Consolidate backward integration into brass forging and precision machining capacity in Yangtze River Delta clusters to defend margin position against commodity input volatility. Prioritize stepper motor driver inventory buffers to mitigate semiconductor supply concentration risk. For New Entrants and Emerging Players: Enter via India's Bureau of Energy Efficiency-mandated electronic valve retrofits in domestic room air conditioner manufacturing, where specification windows remain penetrable before incumbent certification lock-in. Target ammonia refrigeration applications in European food logistics infrastructure, where carbon reduction targets specify stainless steel valves with extended service intervals. Pursue white-label partnerships with third-party maintenance contractors unbundling valve replacement from compressor overhaul packages. For Investors and Strategic Acquirers: Precision control engineering specialists with stepper-motor expertise are the most active acquirer category in this space, consolidating refrigerant-agnostic platform capabilities. Long-term viability hinges on refrigerant transition alignment across multiple regulatory jurisdictions. Monitor EPA SNAP approval timelines for lower-GWP alternatives as inflection indicators for valve redesign cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant-Agnostic Platform Development | Danfoss validates elastomer compatibility across R32, R454B, and HFO blends before commercial deployment. |
| Backward Integration into Precision Machining | Stuttgart industrial corridor facilities capture margin pools in electronic valve superheat controller manufacturing. |
| IoT-Enabled Diagnostics Integration | Cloud-connected valve sensors penetrate smart building management systems in German commercial HVAC retrofits. |
| Stainless Steel Capacity Expansion | Austenitic grade 316 valve bodies extend service intervals beyond 15 years in ammonia refrigeration applications. |
| Third-Party Maintenance Channel Partnerships | Industrial refrigeration operators in Germany procure electronic valves through separate service agreements. |
Methodological Framework
Coverage spans Germany, United States, China, Japan, and India, with primary inputs from each market cluster combining interviews with HVAC OEM procurement directors, refrigerant systems engineers, industrial refrigeration maintenance contractors, and building retrofit program administrators. Secondary validation draws from EPA SNAP filings, EU F-Gas Regulation implementation reports, China GB standards documentation, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume growth from value expansion across product type segmentation by valve architecture, application segmentation by heat pump versus air conditioning versus refrigeration end-use, material segmentation by brass versus stainless steel specifications, and regional regulatory cluster differentiation. CAGRs derive from installed base replacement cycles, refrigerant phase-down schedules, and heat pump deployment trajectories. Forecast inputs incorporate EU Ecodesign efficiency thresholds, India's Bureau of Energy Efficiency mandates, and semiconductor supply availability for electronic controller production.
The model holds under stable refrigerant approval pathways and continuous heat pump subsidy programs; deviation in EPA SNAP timeline acceleration or EU F-Gas phase-down compression would shift replacement demand patterns. Forecasts reflect assumptions regarding brass price volatility bands and stepper motor supply chain normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Vacuum Insulated Pipe Market
Valves
Industrial Vacuum Valves Market
Valves
Global Flow Control Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Penstock Market
Valves
Total Containment Vessels Market
Valves
Global Automotive Valves Market
Valves
Valve Cover Gasket Market
Valves
Explosion Vents Market
Valves
North America Irrigation Valves Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Construction Valve Seat Insert Market
Valves
Pipeline Pigging Valves Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Hybrid Valve Market
Valves
Mechanical Shaft Seal Market