
 Total Containment Vessels Market | 2026-2036
Total Containment Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Total Containment Vessels Market Analytics
Defense procurement offices is collapsing as the dominant buyer archetype for total containment vessels, while pharmaceutical cleanroom operators gain share in the specification process. Allen-Vanguard Corporation leverages its military heritage to dominate blast-resistant vessel contracts across NATO-aligned security services. NABCO Systems LLC anchors North American demand through sustained relationships with federal screening programs. Mistral Group specializes in modular designs that navigate the shift toward mobile containment platforms.
Total containment vessels are engineered enclosures designed to isolate hazardous substances—chemical, biological, or explosive—through sealed construction rated for specific pressure thresholds and leak-tight integrity measured in parts per million. Their primary purpose centers on protecting personnel, infrastructure, and surrounding environments during storage, transport, or processing of dangerous materials. Metal vessels lead product type demand where pressure ratings and structural durability command premium positioning, while composite materials represent the fastest-growing category as fiber-reinforced polymers displace conventional steel in weight-sensitive applications. Chemical storage anchors application demand through established petrochemical infrastructure, though pharmaceuticals exhibits the steepest growth trajectory driven by biologics manufacturing expansion.
The US EPA governs hazardous waste container standards under RCRASubtitle I, while OSHA mandates worker protection protocols that directly shape vessel specification requirements for manufacturing and laboratory environments. The EU REACH framework and CE marking directives constrain material selection and surface coating chemistry for vessels entering European chemical processing facilities. Stakeholders must monitor evolving dual-use export controls, as blast containment technology faces heightened scrutiny under multilateral non-proliferation regimes.
Market Dynamics
The Total Containment Vessels Market is being fundamentally restructured by tightening hazardous materials transport regulations that mandate higher pressure ratings and leak-tight integrity standards, forcing vessel fabricators to retool production lines and recertify legacy designs.
Growth Catalysts
- REACH chemical registration thresholds:The EU ECHA framework now requires enhanced secondary containment for high-volume substances, compelling German chemical manufacturers to upgrade vessel fleets.
- Biologics manufacturing expansion:Pharmaceutical cleanroom operators in Switzerland and Ireland are specifying containment vessels with integrated sterilization ports for mRNA production workflows.
- Fiber-reinforced polymer adoption:Composite vessel fabrication is decomposing weight constraints in aerospace logistics, enabling air transport of previously ground-restricted hazardous materials.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloy production concentrates in a limited supplier base, creating input cost volatility for high-pressure vessel fabricators.
- Dual-use export control friction:Blast containment technology faces heightened scrutiny under multilateral non-proliferation regimes, extending order-to-delivery timelines for security applications.
- Steel vessel substitution ceiling:Conventional carbon steel retains cost advantage in static chemical storage applications, limiting composite penetration in price-sensitive segments.
Strategic Opportunities
- Modular mobile platforms:Mistral Group's containerized vessel architecture opens field-deployable containment for emergency response agencies in Australia and Canada.
- US DOT hazmat certification tightening:The Department of Transportation's revised Special Permit requirements create replacement demand for non-compliant transport vessels.
- India pharmaceutical manufacturing:CDSCO's alignment with ICH Q7 guidelines is driving containment infrastructure investment in Hyderabad and Mumbai production clusters.
Industry Challenges
- Pressure vessel welder certification scarcity:ASME Section IX qualified welders command premium wages, constraining production scaling for certified fabricators.
- Legacy system integration complexity:New composite vessels must interface with existing SCADA monitoring infrastructure in established petrochemical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Total Containment Vessels Market |
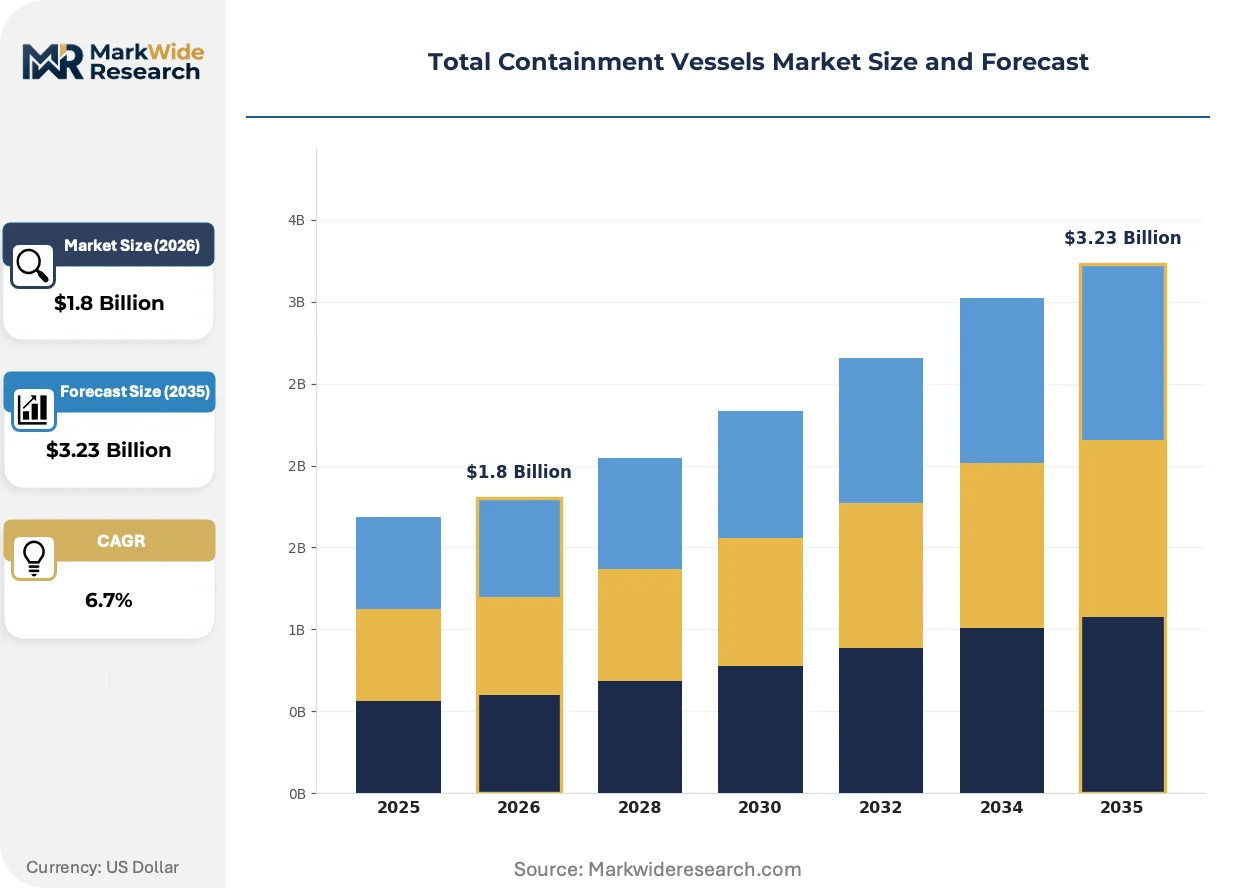
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Composite Application: Chemical Storage, Pharmaceuticals, Food & Beverage, Oil & Gas Feature: High Resistance, Lightweight, Corrosion Resistant, Temperature Control End User: Manufacturing, Laboratories, Hospitals, Research Institutes |
| Companies Covered | Allen-Vanguard Corporation, NABCO Systems LLC, Mistral Group, Surya Telecom Pvt. Ltd., Scanna MSC Ltd., Aquila Nuclear Engineering Ltd, TJ Systems S Pte Ltd., Innovent Engineers, Al Asala International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Total Containment Vessels Market Evolving Landscape
Material science breakthroughs and regulatory harmonization pressures are converging to reshape vessel specification priorities, with weight reduction and certification portability emerging as dominant design imperatives across defense and pharmaceutical end-uses.
Fiber-reinforced polymer composite construction is decomposing traditional steel dominance in weight-critical applications. Aerospace logistics operators in Germany and Japan are specifying carbon-fiber vessels for air-freight explosive ordnance transport. The technology is decomposing the historical trade-off between pressure rating and payload capacity, enabling new deployment scenarios for mobile containment units.
REACH and RoHS alignment is forcing material chemistry disclosure throughout European supply chains. Vessel surface coatings must now document full substance inventories to ECHA standards, eliminating chromate conversion treatments in favor of cerium-based alternatives. German chemical processors are absorbing compliance costs through longer vessel depreciation schedules.
Defense procurement offices are consolidating specifications around NATO-standardized blast containment ratings. Federal screening programs in the US and allied security services are migrating from custom-engineered vessels to catalog-configured platforms with interoperable lifting and transport interfaces. This standardization is compressing vendor qualification cycles and shifting competitive advantage toward modular design specialists.
Total Containment Vessels Market Segmentation
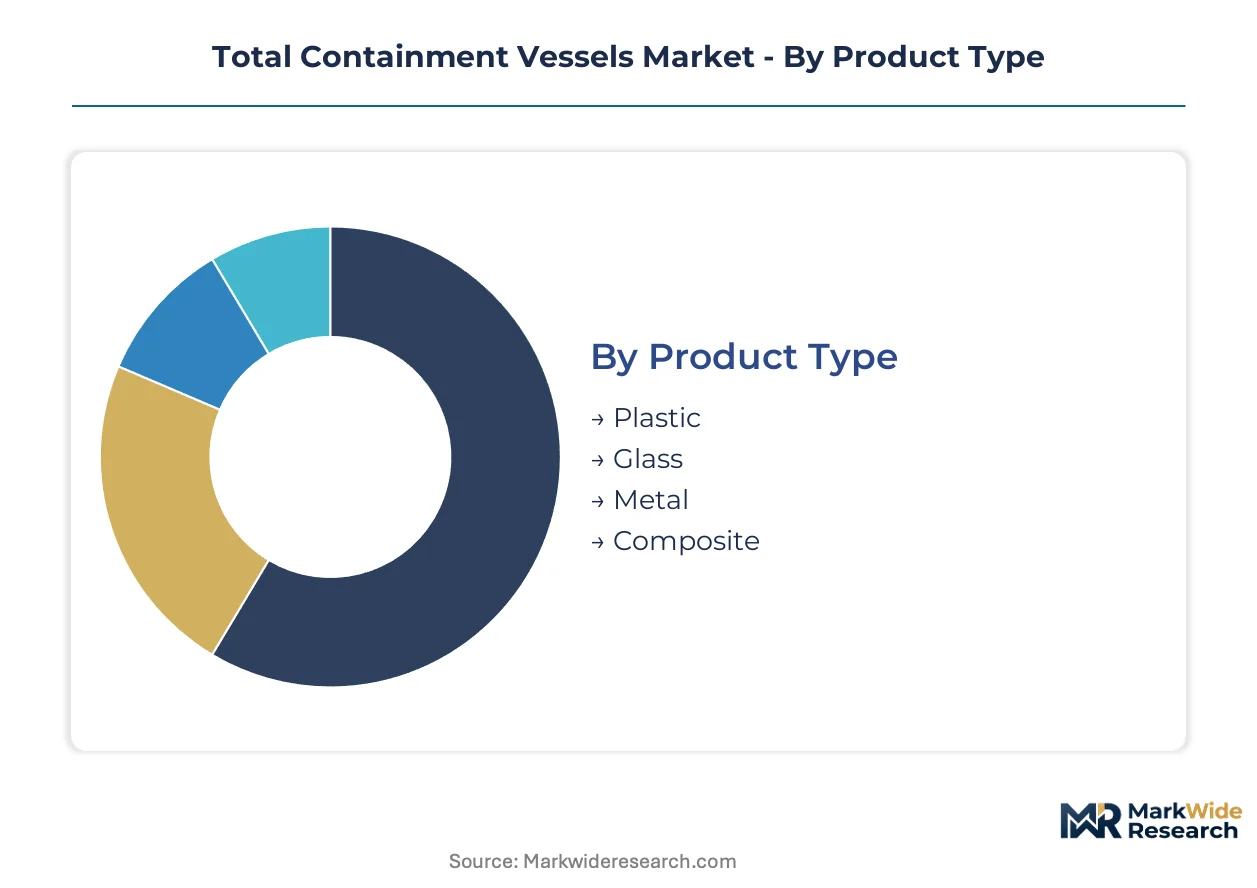
Total containment vessels serve divergent hazard profiles across defense, pharmaceutical, and chemical processing verticals. Segmentation reveals how pressure ratings, sterilization protocols, and transport certification requirements reshape procurement specifications for each end-use environment.
Product Type:
Regulatory pressure thresholds and material chemistry disclosure rules under REACH and RoHS create divergent compliance burdens across fabrication methods.
- Metal:Nickel-based superalloys and carbon steel constructions deliver pressure ratings exceeding 10,000 psi for explosive ordnance containment. German chemical manufacturers specify ASME-certified metal vessels for high-volume chlorine storage under ECHA secondary containment mandates.
- Composite:Fiber-reinforced polymer matrices displace conventional steel in weight-sensitive aerospace logistics. Japanese air-freight operators specify carbon-fiber vessels to exploit payload capacity gains for previously ground-restricted hazardous materials transport.
- Plastic:High-density polyethylene vessels serve low-pressure chemical storage in price-sensitive agricultural applications.
- Glass:Borosilicate constructions isolate reactive intermediates in pharmaceutical synthesis where visual monitoring is essential.
Established volume favors metal; emerging adoption favors composite.
Application:
End-use concentration determines whether procurement prioritizes static storage durability or mobile deployment flexibility.
- Chemical Storage:Petrochemical infrastructure in Germany and the US Gulf Coast anchors demand for large-capacity vessels with integrated secondary containment. ECHA registration thresholds for high-volume substances compel fleet upgrades across Rhine-Ruhr manufacturing clusters.
- Pharmaceuticals:mRNA manufacturing expansion in Switzerland and Ireland drives specification of vessels with sterilization ports and cleanroom-compatible surfaces. CDSCO alignment with ICH Q7 guidelines accelerates containment infrastructure investment in Hyderabad production facilities.
- Oil & Gas:Offshore platform operators specify corrosion-resistant vessels for sour gas handling in North Sea extraction operations.
- Food & Beverage:Aseptic processing applications in dairy and beverage manufacturing employ stainless steel vessels with CIP/SIP integration.
Procurement scale concentrates in chemical storage; steepest expansion trajectory appears in pharmaceuticals.
Feature:
Performance specifications map directly to hazard class and deployment environment constraints.
- High Resistance:Blast-rated constructions with multi-layered wall architectures withstand intentional detonation events. NATO-standardized specifications now consolidate procurement around interoperable lifting and transport interfaces for defense applications.
- Corrosion Resistant:Specialty alloy linings and polymer coatings extend service life in halogenated chemical exposure. REACH-compliant cerium-based surface treatments displace chromate conversion coatings across European supply chains.
- Lightweight:Composite wall constructions reduce logistics costs for field-deployable emergency response units in Australia and Canada.
- Temperature Control:Jacketed vessel designs maintain cryogenic or elevated thermal setpoints for biologics processing workflows.
Specification frequency favors high resistance; technology evolution favors corrosion resistant.
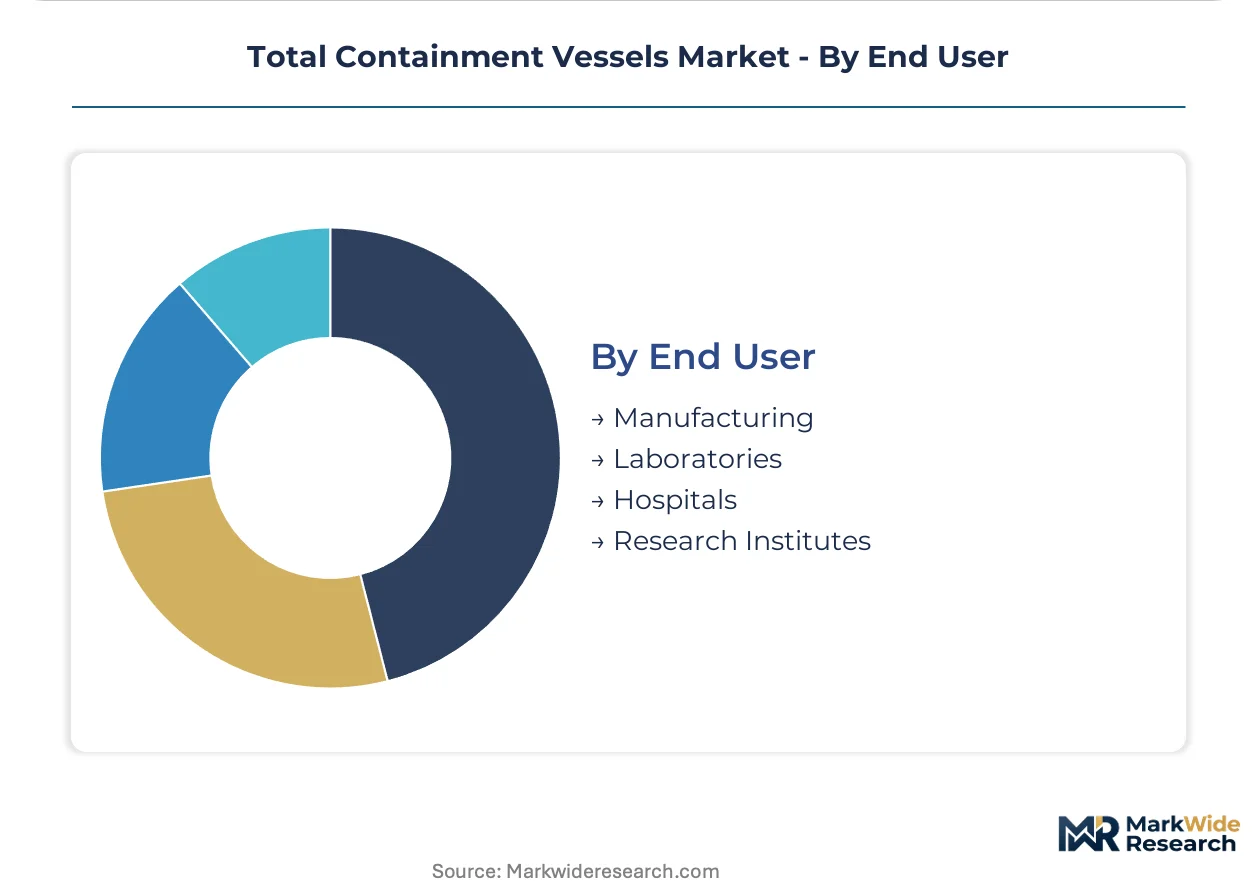
End User:
Facility type dictates integration complexity with existing monitoring infrastructure and sterilization protocols.
- Manufacturing:Petrochemical and specialty chemical producers specify vessels with SCADA-compatible sensor arrays for real-time leak detection. OSHA Process Safety Management requirements mandate specific pressure relief configurations for high-hazard production lines.
- Laboratories:R&D facilities prioritize compact footprints and rapid decontamination cycles for multi-substance handling. EPA RCRA Subtitle I compliance shapes waste container selection for analytical chemistry operations.
- Hospitals:Radiopharmaceutical preparation suites require lead-shielded vessels with dose calibrator integration for nuclear medicine applications.
- Research Institutes:Academic biosafety level-3 facilities specify flexible film isolators for pathogen containment in emerging infectious disease research.
Contract value concentrates in manufacturing; specification sophistication concentrates in laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical manufacturers export specialized containment vessels to Swiss pharmaceutical clusters and Indian production facilities, establishing a trade corridor that shapes procurement specifications across three continents.
United States
Federal screening programs and explosive ordnance disposal units drive procurement of blast-rated vessels. OSHA Process Safety Management mandates pressure relief configurations for high-hazard manufacturing lines. Houston-Gulf Coast petrochemical infrastructure anchors demand for large-capacity storage vessels with integrated secondary containment systems.
Germany
Rhine-Ruhr chemical manufacturing clusters require fleet upgrades under ECHA secondary containment mandates for high-volume substance registration. REACH chemical registration thresholds compel enhanced vessel specifications. BASF and Bayer production sites in Ludwigshafen and Leverkusen drive specialized orders for corrosion-resistant alloy constructions.
Switzerland
mRNA manufacturing expansion in Basel and Geneva drives specification of vessels with sterilization ports and cleanroom-compatible surfaces. Swissmedic pharmaceutical manufacturing guidelines align with EU containment standards. Lonza and Novartis production facilities prioritize integrated sterilization workflows for biologics processing.
India
CDSCO alignment with ICH Q7 guidelines accelerates containment infrastructure investment in Hyderabad and Mumbai pharmaceutical clusters. Domestic chemical manufacturing growth drives demand for ASME-certified transport vessels. Reliance Industries and Sun Pharmaceutical operations in Gujarat and Maharashtra specify vessels with SCADA-compatible sensor arrays.
Japan
Carbon-fiber composite vessels enable air-freight transport of previously ground-restricted hazardous materials for aerospace logistics operators. METI industrial safety standards govern pressure vessel certification for manufacturing environments. Osaka-Kobe industrial corridor concentrates demand for lightweight mobile containment platforms in semiconductor and specialty chemical processing.
Total Containment Vessels Market Competitive Landscape
Player mix skews toward defense-heritage specialists with NATO certification relationships and modular design innovators serving mobile deployment requirements. The structure concentrates around three strategic archetypes: military-contract fabricators leveraging blast-resistant engineering, composite material specialists exploiting weight-sensitive logistics opportunities, and regional system integrators anchoring national screening programs. Competitive positioning depends on certification portability across regulatory jurisdictions and backward integration into specialized alloy supply chains.
Within the defense-heritage tier, Allen-Vanguard Corporation and NABCO Systems LLC exemplify archetypes built on sustained federal and allied security service relationships. Mistral Group occupies a position among modular design specialists, representing the shift toward containerized vessel architectures for field-deployable emergency response. These three anchors demonstrate how competitive advantage concentrates around NATO-standardized specifications and interoperable transport interfaces rather than proprietary technology differentiation.
| Leading Market Players |
|---|
| Allen-Vanguard Corporation |
| NABCO Systems LLC |
| Mistral Group |
| Surya Telecom Pvt. Ltd. |
| Scanna MSC Ltd. |
| Aquila Nuclear Engineering Ltd |
| TJ Systems S Pte Ltd. |
| Innovent Engineers |
| Al Asala International LLC |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German chemical manufacturers and nickel-based superalloy suppliers lock in both raw material access and price visibility across multi-year vessel production cycles, insulating fabricators from spot market volatility in critical inputs.
Pricing Analysis
Current-generation composite vessels command substantial premiums over legacy steel constructions, while next-generation fiber-reinforced polymer platforms with integrated sensor arrays sit at the apex of the pricing hierarchy. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified blast containment units from ASME-certified industrial storage vessels and uncertified agricultural plastic containers. Cost compression in standard-tier metal vessels is intensifying because carbon steel retains cost advantage in static chemical storage applications. Agricultural processors exhibit highest price sensitivity, while defense procurement offices demonstrate lowest sensitivity due to mission-critical specifications.
Supply Chain Analysis
Germany and Japan anchor high-performance vessel fabrication through specialized alloy processing and carbon-fiber composite manufacturing respectively. Production draws from concentrated nickel-based superalloy supply, fiber-reinforced polymer precursors, and precision welding consumables. Single-source vulnerability in nickel alloy supply creates exposure to input cost volatility for pressure-rated constructions. Distribution runs through direct OEM relationships for large chemical processors and specialized industrial distributors for mid-scale laboratory and manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from modular composite platforms that displace conventional steel in weight-sensitive logistics applications, requiring active portfolio repositioning to defend market position.
For Market Incumbents: Consolidate backward integration into nickel-based superalloy supply chains to secure input cost stability against concentrated supplier bases. Deepen certification investment in REACH-compliant surface treatments to preempt regulatory displacement of chromate conversion coatings. Anchor capacity in German chemical manufacturing clusters where ECHA secondary containment mandates drive sustained replacement demand.
For New Entrants and Emerging Players: Lead with containerized mobile containment architectures targeting emergency response agencies in Australia and Canada where field-deployable specifications remain underpenetrated. Exploit white space in Indian pharmaceutical manufacturing clusters where CDSCO alignment with ICH Q7 guidelines accelerates infrastructure investment. Position through integrated sterilization port designs that address mRNA manufacturing workflows in Swiss and Irish cleanroom environments.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors modular design specialists with NATO-standardized certification relationships and interoperable transport interfaces. Long-term viability rests on certification portability across EPA, ECHA, and CDSCO regulatory jurisdictions rather than proprietary technology moats. Watch for inflection in dual-use export control enforcement intensity as the signal for order-to-delivery timeline compression or extension.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Supply | Captive nickel-based alloy production insulates German fabricators from supplier concentration risk. |
| REACH-Compliant Coating Transition | Cerium-based surface treatments replace chromate conversion across European chemical processing supply chains. |
| Modular Mobile Platform Development | Containerized vessel architectures open emergency response procurement channels in Australian and Canadian agencies. |
| NATO Standardization Alignment | Interoperable lifting and transport interfaces compress vendor qualification cycles for defense procurement offices. |
| Integrated Sterilization Port Design | Cleanroom-compatible vessels with sterilization workflows capture mRNA manufacturing expansion in Swiss clusters. |
Research Methodology
A standing panel of vessel fabrication engineers, EHS compliance officers at chemical processors, defense procurement specialists, and pharmaceutical cleanroom operators provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation against ASME certification databases, ECHA substance registration filings, EPA RCRA enforcement records, and customs trade data for specialized alloy imports. Bottom-up vessel shipment tallies by end-use and top-down chemical manufacturing capacity estimates were triangulated to cross-verify market sizing.
Consistency checks validated volume and value outputs against external benchmarks including petrochemical infrastructure investment trackers and pharmaceutical manufacturing capacity announcements across the analysis window. Segmentation modeling incorporated product type, application vertical, pressure rating tier, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to annualized shipment estimates, with biologics manufacturing expansion rates and defense budget appropriation trajectories serving as key industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA RCRA Subtitle I, EU REACH framework, and CDSCO pharmaceutical manufacturing guidelines; material policy shifts would require re-modeling across the projection horizon. Specific risk factors include intensified dual-use export control enforcement, nickel alloy supply disruption, and composite material qualification delays in aerospace logistics applications. Recalibration cycles align with material shifts in hazardous materials transport regulations and biologics manufacturing capacity deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Ball Valves Market
Valves
US Water & Wastewater Valves Market
Valves
Christmas Tree Valves Market
Valves
China Explosion-Proof Equipment Market
Valves
Orifice Reducers Market
Valves
Pneumatic Positioner Market
Valves
Angle Opening Ball Locator Market
Valves
Wind Energy Fasteners Market
Valves
Static Seals Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Industrial Hydraulic Filters Market
Valves
Global Valve Positioners Market
Valves
Explosion Isolation Valves Market
Valves
Pipeline Pigging Valves Market
Valves
Global Compression Packing Market
Valves
HVAC Valves Market