
 Dense Phase Vessels Market | 2026-2036
Dense Phase Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Dense Phase Vessels Market Insights
The capital-intensity divergence between fabrication-scale specialists and component assemblers is rotating competitive advantage toward integrated manufacturers. Coperion GmbH leverages captive steel-forming capacity to control lead times on pressure-rated designs. Schenck Process Holding anchors its position through dense-phase pneumatic systems integration across European process plants. Dynamic Air specializes in custom vessel geometry for abrasive mineral applications, sustaining margin pools that commodity fabricators cannot match.
Dense phase vessels are pressure-rated containment systems engineered for the low-velocity, high-concentration transport of granular and powdered solids, typically constructed from carbon steel or stainless steel with wall thicknesses calculated per ASME Section VIII Division 1 criteria and designed to operate above 15 psig while maintaining material velocities below saltation thresholds to prevent particle degradation and pipeline wear. Their primary industrial purpose is to enable gentle, efficient conveying of friable or abrasive bulk solids from storage through process stages without phase separation or attrition. Pressure vessels command the largest installed base due to universal deployment across pneumatic conveying circuits, while vacuum conveying technology represents the fastest-expanding segment as pharmaceutical and food processors adopt closed-system designs for containment and hygiene compliance. Bulk material handling applications retain mature demand profiles in cement and mining, whereas chemical processing applications generate premium pricing through corrosion-resistant alloy specifications and certified welding protocols.
ASME Boiler and Pressure Vessel Code, EU Pressure Equipment Directive 2014/68/EU, and China's GB 150 pressure vessel standards collectively dictate design margins, inspection intervals, and market access for dense phase vessel suppliers across major manufacturing geographies. These frameworks elevate compliance costs for non-certified fabricators while creating procurement preference for established players with third-party accreditation. Stakeholders must monitor evolving carbon-accounting requirements for steel-intensive equipment, as embodied-emissions disclosure obligations begin penetrating capital-equipment procurement specifications in regulated jurisdictions.
Market Dynamics
Capital equipment procurement in dense phase pneumatic conveying is pivoting toward embodied-carbon disclosure requirements, with steel-intensive pressure vessels now subject to Scope 3 emissions auditing that favors fabricators with verified supply chain documentation over commodity suppliers.
Growth Catalysts
- Infrastructure investment corridors:China's sustained cement capacity expansion and India's National Infrastructure Pipeline are commissioning bulk material handling systems that specify ASME-coded pressure vessels for pneumatic transport circuits.
- REACH chemical containment mandates:European pharmaceutical processors are retrofitting facilities with closed-system dense phase designs to satisfy ECHA occupational exposure limits on high-potency active pharmaceutical ingredients.
- Dual carbon policy framework:China's MIIT efficiency standards for industrial pneumatic systems are accelerating replacement cycles for legacy high-velocity conveying equipment with low-velocity dense phase alternatives.
Market Restraints
- Alloy cost volatility:Nickel and molybdenum price swings for 316L stainless steel specifications compress margins on corrosion-resistant chemical processing vessels.
- Fabrication capacity concentration:Heavy-gauge pressure vessel forming capabilities cluster in Germany, China, and the US Gulf Coast, creating geographic supply bottlenecks for project-delivery timelines.
- Vacuum conveying substitution:Dilute-phase vacuum systems capture share in food-grade applications where pressure-rated containment adds unnecessary cost.
Strategic Opportunities
- Pharmaceutical containment retrofit wave:US FDA containment guidelines for potent compound handling are driving replacement demand in generic API manufacturing clusters across New Jersey and Puerto Rico.
- Modular skid integration:Pre-assembled dense phase modules with integrated controls reduce field welding requirements and accelerate commissioning for brownfield chemical plant expansions.
- EU Green Deal embodied-carbon accounting:CSRD disclosure requirements for capital equipment procurement are creating preference for European fabricators with verified low-carbon steel sourcing.
Industry Challenges
- ASME Section IX welding certification scarcity:Qualified pressure vessel welders command premium wages and extended lead times, constraining fabrication throughput for certified shops.
- Legacy control system integration:Digital pressure monitoring and predictive maintenance retrofits require protocol translation for existing PLC architectures in mature cement and mining installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dense Phase Vessels Market |
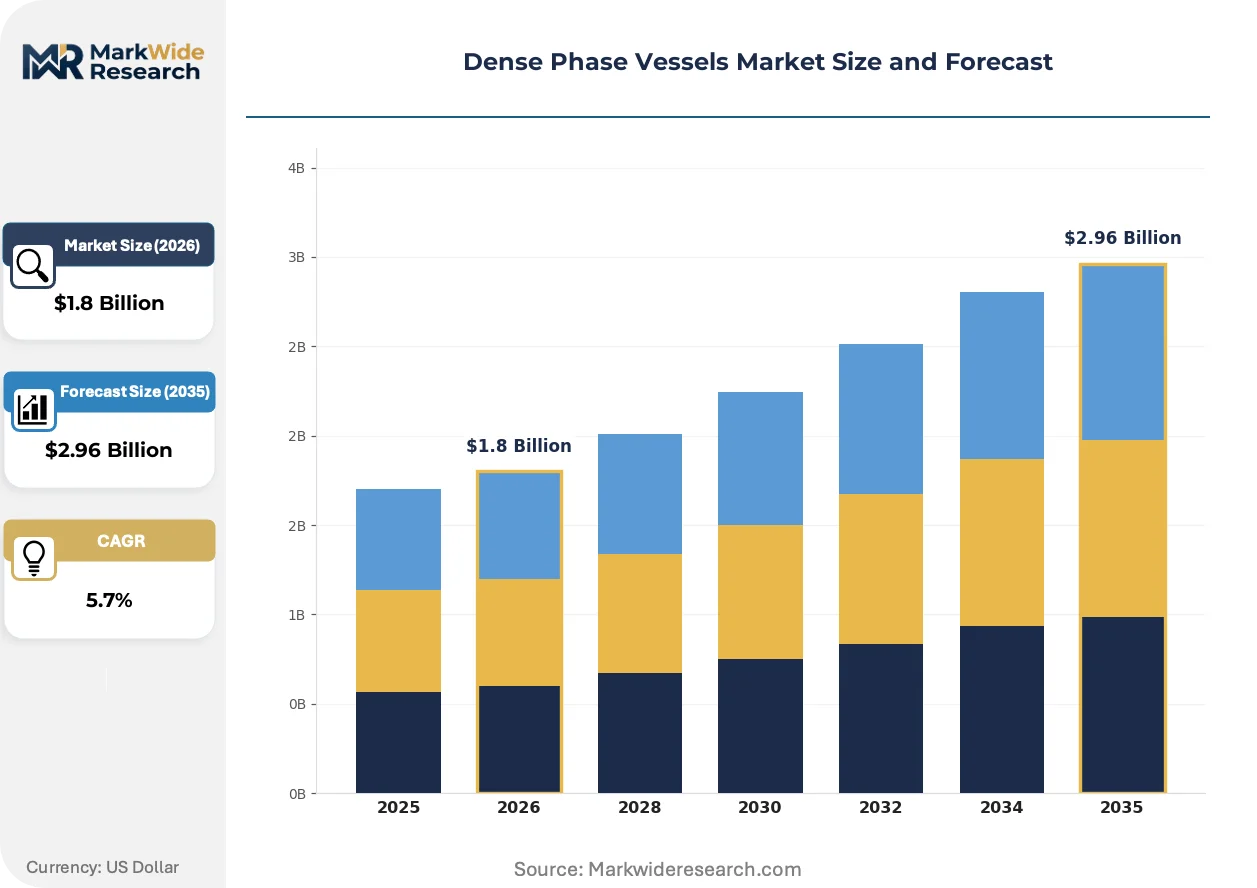
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Vessels, Storage Silos, Bulk Containers, Hopper Tanks, Cyclone Separators Technology: Pneumatic Conveying, Vacuum Conveying, Mechanical Conveying, Screw Conveying, Gravity Flow Application: Bulk Material Handling, Food Processing, Chemical Processing, Mining Operations, Waste Management End User Industry: Cement Manufacturing, Pharmaceutical Production, Mining Contractors, Chemical Manufacturers, Food & Beverage Processors |
| Companies Covered | Coperion GmbH, Schenck Process Holding, Atlas Copco, Gericke AG, GEA Group, AZO GmbH + Co. KG, Dynamic Air, Flexicon Corporation, Cyclonaire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dense Phase Vessels Market Trends and Innovations
Material science advances and regulatory disclosure mandates are converging to redefine vessel specification criteria, with performance metrics expanding beyond pressure ratings to encompass lifecycle carbon intensity and digital traceability.
Ceramic-lined carbon steel pressure vessels are displacing solid alloy construction in abrasive mineral applications. Mining operators in Western Australia and Chile's Atacama region are specifying alumina or silicon carbide tile systems for phosphate and copper concentrate handling. This composite approach preserves ASME structural integrity while reducing specialty alloy dependence by sixty to seventy percent.
EU F-Gas Regulation phase-down schedules are accelerating adoption of dry bulk conveying systems that eliminate compressed air dependency. Food processors in the Netherlands and Denmark are retrofitting nitrogen-based dense phase circuits to satisfy both containment requirements and fluorinated gas reduction targets. Equipment suppliers are responding with modular nitrogen generation skids integrated at the vessel package level.
Buyers are consolidating vendor relationships around full-system accountability rather than component procurement. Cement producers in Germany and Mexico now specify turnkey dense phase loops with guaranteed mass flow rates and maintenance-included contracting. This performance-guarantee model compresses supplier margins while extending contract durations and locking out pure fabrication competitors without pneumatic engineering capabilities.
Dense Phase Vessels Market Segmentation
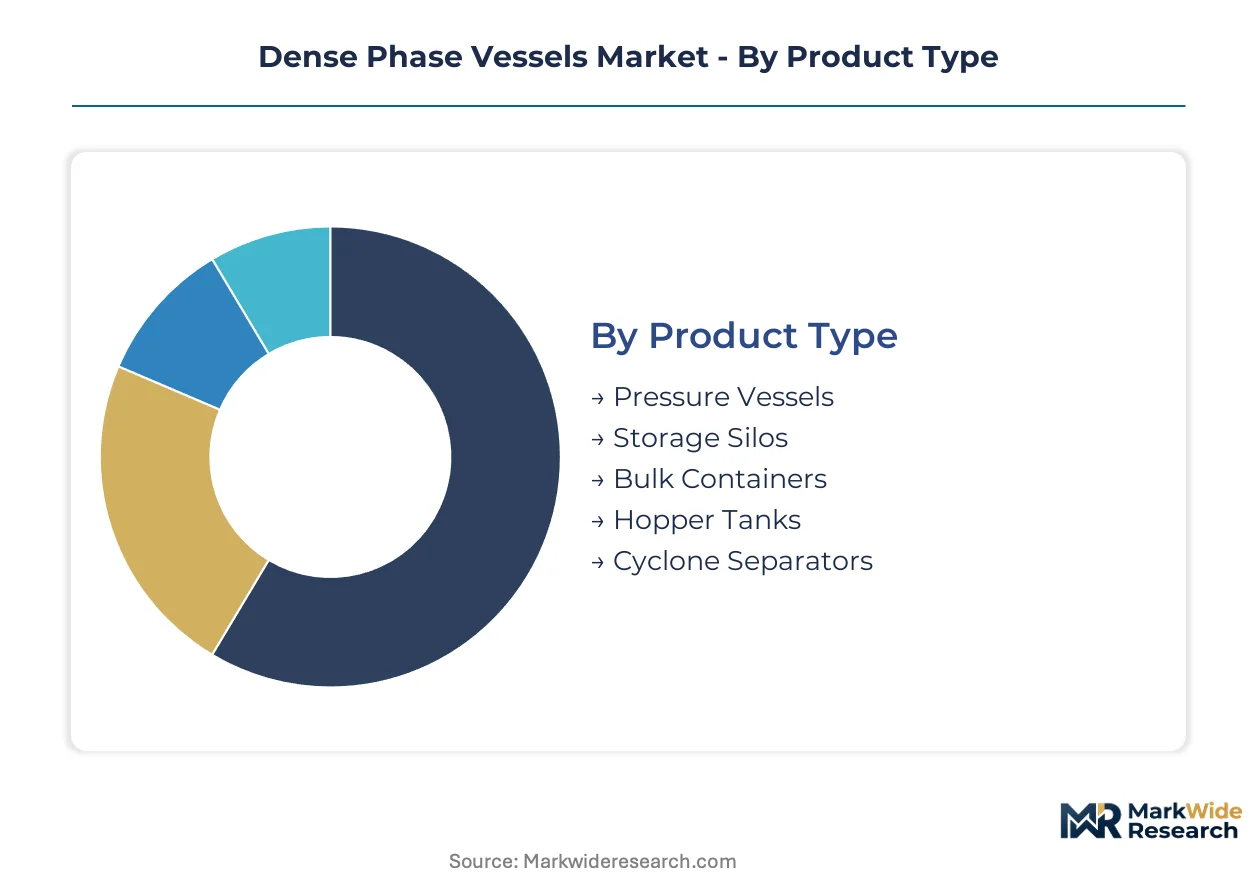
Dense phase vessel procurement decisions pivot on pressure rating requirements, material compatibility, and regulatory certification tiers. Specification mismatches between product categories and end-use operating conditions create costly retrofit cycles. The following segmentation maps how technical attributes align with industrial deployment patterns.
Product Type:
ASME Section VIII Division 1 certification requirements separate pressure-rated designs from atmospheric storage systems, creating procurement bifurcation between certified fabricators and commodity tank suppliers.
- Pressure Vessels:Carbon steel or stainless steel containment systems engineered for operation above 15 psig with wall thicknesses calculated per ASME stress criteria. Cement manufacturing plants in China and India specify these for pneumatic transport circuits handling abrasive clinker and fly ash. MIIT efficiency standards accelerate replacement of legacy high-velocity systems with low-velocity dense phase alternatives.
- Storage Silos:Atmospheric or low-pressure vertical cylinders for intermediate material holding without continuous conveyance integration. Mining contractors in Western Australia deploy these for phosphate concentrate staging ahead of rail loadout. Alumina ceramic tile lining reduces specialty alloy dependence by sixty to seventy percent in abrasive applications.
- Bulk Containers:Modular, transportable vessels for intermodal material transfer between production and distribution nodes. Chemical manufacturers specify corrosion-resistant specifications for intermediate bulk handling of specialty powders.
- Hopper Tanks:Conical-bottom designs engineered for controlled discharge flow into downstream conveying systems. Food processors integrate these with nitrogen-based dense phase circuits to satisfy EU F-Gas Regulation phase-down targets.
- Cyclone Separators:Pressure-rated gas-solid separation vessels for pneumatic circuit particulate recovery. Pharmaceutical production facilities deploy these for high-potency API containment under FDA guidelines.
Pressure vessels handle the majority of throughput; cyclone separators are gaining share fastest on pharmaceutical containment retrofit demand.
Technology:
Capital cost differentials between pneumatic infrastructure and mechanical alternatives rotate specification decisions based on material friability, distance requirements, and energy accounting protocols.
- Pneumatic Conveying:Gas-driven transport systems utilizing pressure differential to move bulk solids through enclosed pipelines at controlled velocities. Cement manufacturing dominates installed base across emerging market infrastructure corridors. China's National Development and Reform Commission prioritizes these for bulk material handling capacity expansions.
- Vacuum Conveying:Negative-pressure systems for contained material pickup and transfer, prevalent in hygiene-critical processing environments. Pharmaceutical production facilities in New Jersey and Puerto Rico retrofit with these designs under FDA containment guidelines for potent compound handling. This segment climbs the fastest on closed-system adoption.
- Mechanical Conveying:Belt, bucket, or chain-driven transport for high-volume, short-distance material movement. Mining operations specify these where particle degradation tolerance permits higher-velocity handling.
- Screw Conveying:Helical flight systems for precise, metered material transfer at controlled rates. Chemical processing applications generate premium pricing through corrosion-resistant alloy specifications.
- Gravity Flow:Unpowered material movement relying on elevation differential and chute geometry. Waste management facilities deploy these for cost-sensitive bulk handling where containment requirements permit open design.
Pneumatic conveying commands the largest installed base; vacuum conveying shows the steepest expansion trajectory on pharmaceutical and food processing containment mandates.
Application:
Operating environment severity—from abrasive mineral wear to chemical corrosion to hygiene compliance—dictates material specification and certification tier across application segments.
- Bulk Material Handling:Integrated systems for storage, transfer, and processing of granular and powdered industrial feedstocks. Cement manufacturing and mining operations sustain mature demand profiles with established specification protocols.
- Food Processing:Hygiene-compliant designs satisfying HACCP and EU food contact material regulations. Dutch and Danish processors specify nitrogen-based dense phase circuits to eliminate compressed air dependency under F-Gas reduction targets.
- Chemical Processing:Corrosion-resistant vessels handling reactive, hazardous, or high-purity materials. REACH chemical containment mandates drive European retrofit demand for closed-system designs satisfying ECHA occupational exposure limits.
- Mining Operations:Abrasion-resistant specifications for mineral concentrate and tailings handling. Chile's Atacama region operators specify ceramic-lined carbon steel to preserve ASME structural integrity without solid alloy construction costs.
- Waste Management:Containment systems for industrial byproduct and hazardous material handling. Regulatory pressure on landfill diversion sustains specification activity for pneumatic transfer of processed waste streams.
Bulk material handling retains the dominant share; food processing exhibits the sharpest share gain on EU regulatory compliance retrofit cycles.
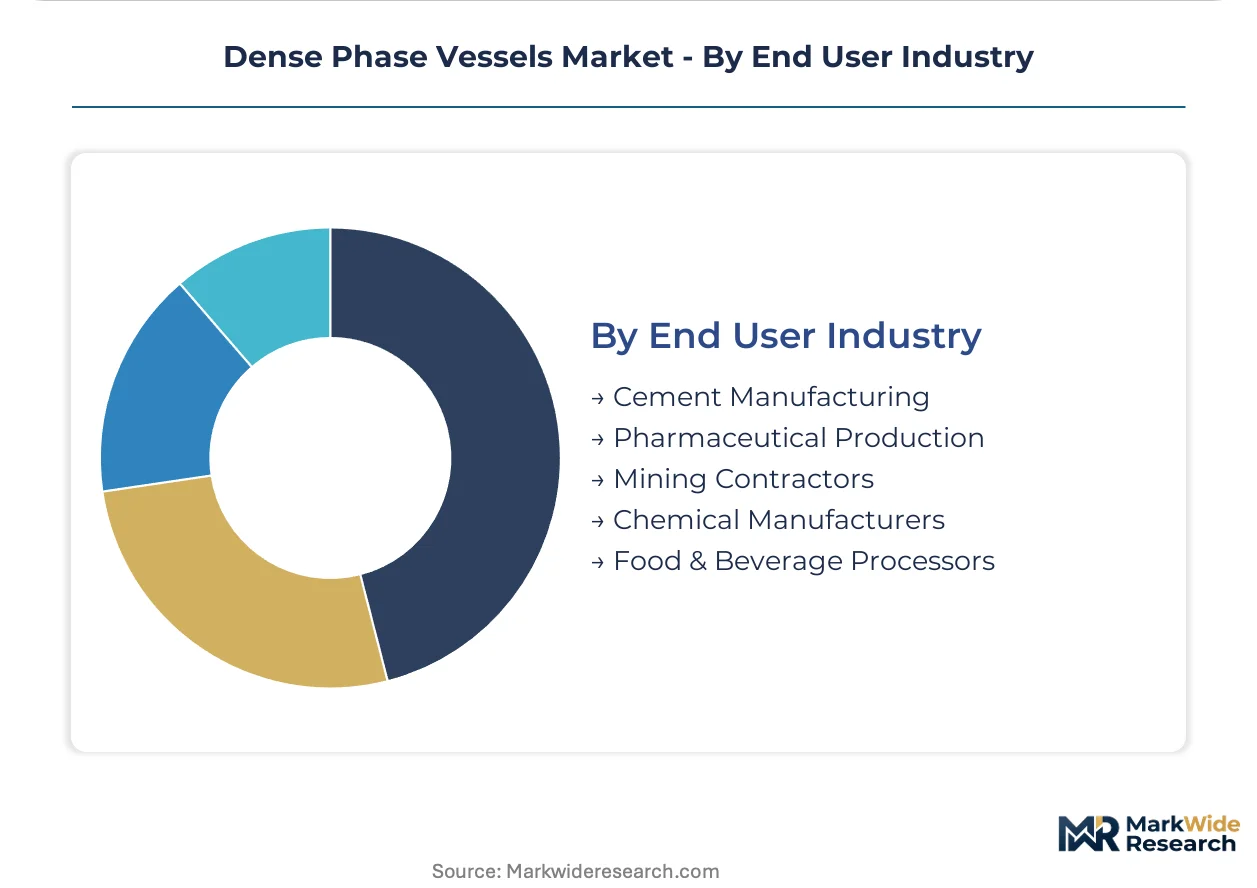
End User Industry:
Procurement sophistication varies sharply across end-user categories, with certified pressure vessel specifications concentrated in regulated process industries versus commodity fabrication acceptance in bulk extractive sectors.
- Cement Manufacturing:High-volume consumers of pressure-rated vessels for clinker, fly ash, and finished cement pneumatic transport. China's sustained infrastructure investment sustains capacity expansion commissioning across provincial production clusters.
- Pharmaceutical Production:Containment-critical specifications for high-potency active pharmaceutical ingredient handling. US FDA guidelines for potent compound handling drive replacement demand in generic API manufacturing clusters.
- Mining Contractors:Abrasive material handling systems for concentrate transport and processing circuit integration. Western Australian iron ore and Chilean copper operations specify ceramic-lined designs for phosphate and copper concentrate handling.
- Chemical Manufacturers:Corrosion-resistant alloy specifications with certified welding protocols and inspection documentation. European chemical processors prioritize fabricators with verified low-carbon steel sourcing under CSRD disclosure requirements.
- Food & Beverage Processors:Hygiene-compliant stainless steel designs with clean-in-place compatibility and contaminant exclusion features. German and Mexican cement producers now specify turnkey dense phase loops with guaranteed mass flow rates and maintenance-included contracting.
Cement manufacturing anchors volume demand; pharmaceutical production demonstrates the most rapid share expansion on containment retrofit mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in dense phase vessels tilt toward fabrication hubs with certified pressure equipment capacity, with China, Germany, and the United States absorbing the bulk of cross-border procurement for cement and chemical processing applications.
China
Provincial cement clusters in Anhui and Jiangsu provinces sustain vessel demand through infrastructure-driven capacity expansions. MIIT efficiency standards for industrial pneumatic systems accelerate replacement of legacy equipment with low-velocity dense phase alternatives. Shanghai-based fabricators dominate domestic supply for ASME-coded export orders.
United States
Pharmaceutical containment retrofits in New Jersey and Puerto Rico drive specification activity for high-potency API handling systems. FDA guidelines for potent compound handling mandate closed-system designs that favor pressure-rated vessel procurement. Gulf Coast fabrication shops concentrate heavy-gauge forming capacity for chemical processing applications.
Germany
CSRD disclosure requirements for capital equipment procurement create preference for domestic fabricators with verified low-carbon steel sourcing. REACH chemical containment mandates push European pharmaceutical processors toward dense phase retrofits. North Rhine-Westphalia hosts integrated pneumatic engineering clusters serving process plant automation.
India
The National Infrastructure Pipeline commissions bulk material handling systems specifying pressure-rated vessels for fly ash and clinker transport. BIS pressure vessel standards align with ASME criteria for multinational cement operator procurement. Gujarat and Rajasthan cement corridors anchor regional demand concentration.
Chile
Copper concentrate handling operations in the Atacama region specify ceramic-lined carbon steel vessels to reduce specialty alloy dependence. Mining contractors prioritize ASME-structural designs for abrasive mineral applications. Antofagasta Province concentrates procurement activity for phosphate and copper processing circuits.
Dense Phase Vessels Market Competitive Landscape
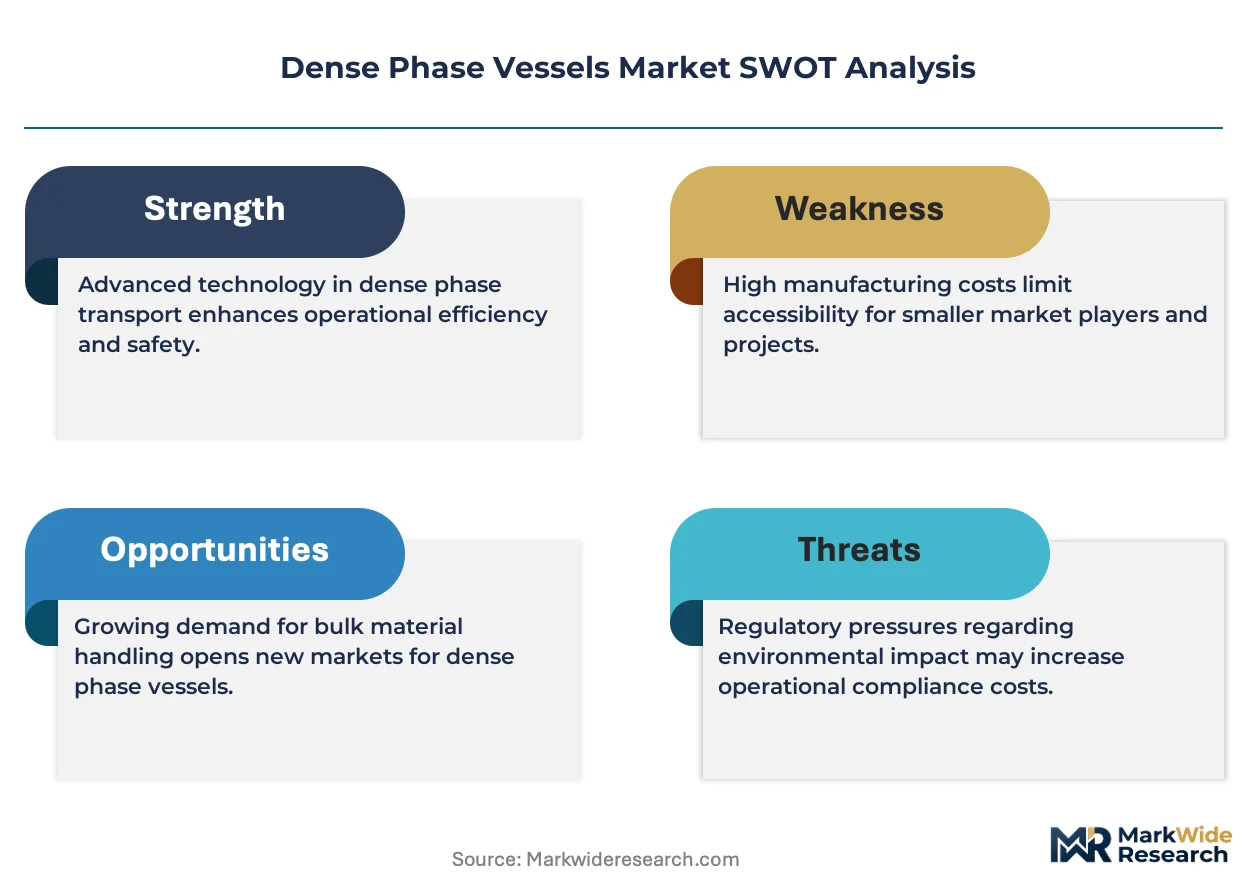
Concentration sits with integrated pneumatic engineering specialists rather than pure fabrication shops, as turnkey system accountability displaces component procurement. The vendor base separates into three tiers: captive steel-forming specialists with pressure-rated design control, full-loop integrators with guaranteed performance contracting, and regional fabricators competing on lead time. Strategic moves center on modular skid pre-assembly to reduce field welding requirements and backward integration into nitrogen generation packages for food-grade containment applications.
Among German-based engineering groups, Coperion GmbH and Schenck Process Holding occupy positions that exemplify the integrated manufacturer archetype, combining captive forming capacity with pneumatic circuit design. Dynamic Air represents the specialization vector, with custom vessel geometry capabilities for abrasive mineral applications that commodity fabricators cannot replicate. These three anchors illustrate how competitive advantage rotates toward players controlling both structural fabrication and conveying system integration.
| Leading Market Players |
|---|
| Coperion GmbH |
| Schenck Process Holding |
| Atlas Copco |
| Gericke AG |
| GEA Group |
| AZO GmbH + Co. KG |
| Dynamic Air |
| Flexicon Corporation |
| Cyclonaire |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-week lead times on ASME-coded pressure vessels concentrate pricing power with German and US Gulf Coast fabricators possessing captive heavy-gauge forming capacity, while commodity tank suppliers without certification credentials absorb margin compression from alloy cost volatility. This delivery-band asymmetry rewards integrated pneumatic engineering specialists who bundle vessel supply with guaranteed performance contracting.
Pricing Analysis
Configured-to-order pricing commands a forty-to-sixty percent premium over standard catalog vessels, with ASME Section VIII Division 1 certification and 316L stainless steel specifications as the primary differentiation drivers. Project-based long-term contracting dominates procurement in cement and pharmaceutical verticals, though price erosion runs through atmospheric storage silos as Chinese fabricators expand export capacity. Mining contractors exhibit highest price sensitivity due to commodity cycle exposure, while European chemical processors under CSRD disclosure requirements show lowest sensitivity for verified low-carbon steel sourcing.
Supply Chain Analysis
Strategic stockpiling of nickel and molybdenum feedstock distinguishes ASME-certified fabricators from just-in-time component assemblers exposed to alloy price spikes. Heavy-gauge pressure vessel forming concentrates in Germany, China, and the United States, with raw material dependencies on specialty steel plate, ceramic tile lining systems, and nitrogen generation packages. Single-source vulnerability sits with qualified pressure vessel welders holding Section IX certification. Distribution runs through direct OEM relationships for turnkey pneumatic systems and regional fabricator networks for replacement vessel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dilute-phase vacuum conveying systems threaten dense phase vessel incumbents in food-grade applications where pressure-rated containment adds unnecessary capital cost. Substitution defense requires incumbents to anchor customer relationships through performance-guaranteed full-loop integration rather than component supply.
For Market Incumbents: Secure backward integration into nitrogen generation packages for EU F-Gas Regulation compliance, locking out commodity fabricators without pneumatic engineering capabilities. Expand modular skid pre-assembly capacity in Gujarat and Rajasthan to capture India's National Infrastructure Pipeline commissioning cycles before regional fabricators achieve ASME certification equivalence. For New Entrants and Emerging Players: Differentiate on ceramic-lined carbon steel vessel geometry for Chilean and Western Australian mining contractors seeking sixty-to-seventy percent alloy cost reduction. Target pharmaceutical containment retrofit demand in New Jersey and Puerto Rico with closed-system dense phase designs satisfying FDA guidelines for potent compound handling, leveraging third-party ASME accreditation as entry credential. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because turnkey system accountability is displacing component procurement and compressing margins for pure fabrication shops. Acquisition candidates include regional ASME-certified shops with underutilized welding capacity and established relationships with cement or mining operators. Watch for inflection when CSRD disclosure requirements penetrate capital-equipment procurement specifications beyond European borders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrogen Generation | Captures EU F-Gas Regulation retrofit demand from Dutch and Danish food processors. |
| Modular Skid Pre-Assembly | Reduces field welding requirements and accelerates commissioning for brownfield chemical expansions. |
| Ceramic-Lined Vessel Specialization | Preserves ASME structural integrity for Chilean copper concentrate handling without solid alloy construction. |
| Performance-Guaranteed Contracting | Locks out commodity fabricators by bundling vessel supply with guaranteed mass flow rates. |
| Low-Carbon Steel Sourcing Verification | Creates procurement preference under CSRD disclosure requirements for European chemical processors. |
Research Methodology
Desk research of ASME Boiler and Pressure Vessel Code filings, EU Pressure Equipment Directive certification databases, and MIIT efficiency standard notifications preceded structured interviews with plant engineers at cement manufacturing clusters, procurement leads at pharmaceutical API facilities, and aftermarket service heads at pneumatic conveying OEMs. Primary intelligence combined with secondary validation from customs trade data, SEC equipment supplier filings, and BIS pressure vessel registration records. Bottom-up vessel shipment analysis triangulated against top-down infrastructure investment flow estimates.
Variance decomposition across product type, technology, application, and end-user industry dimensions shaped volume and value outputs over the projection horizon. CAGRs derived from replacement cycle analysis of legacy high-velocity conveying equipment and capacity expansion pipelines in Chinese provincial cement clusters. Industry-specific forecast inputs incorporated MIIT efficiency standard compliance deadlines and FDA containment guideline implementation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment in emerging markets or accelerated REACH chemical containment enforcement would require recalibration. Forecasts reflect assumptions regarding alloy cost stability and qualified welder availability. Revision becomes warranted when dilute-phase vacuum conveying penetration in food processing crosses twenty-five percent share thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Motorized Valves Market
Valves
Cathodic Protection Market
Valves
Battery Safety Valve Market
Valves
North America Irrigation Valves Market
Valves
Flow Computer Market
Valves
Fluid Handling Systems Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Rupture Discs Market
Valves
Asia Pacific Pipeline Maintenance Market
Valves
Instrumentation Valves and Fittings Market
Valves
Blow - Off Valves Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Deluge Valve Market
Valves
Valve Remote Control System Market
Valves
Sandblast Valves Market
Valves
US Water & Wastewater Valves Market