
 Flare Stack Monitoring Systems Market | 2026-2036
Flare Stack Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Flare Stack Monitoring Systems Market Foresight
Buyer concentration among supermajor oil and gas operators is restructuring procurement patterns across the flare stack monitoring value chain. Emerson Electric Co. leverages its automation platform breadth to bundle monitoring hardware with control system integration. Honeywell International Inc. sustains competitive positioning through its UOP refinery technology relationships that create embedded monitoring opportunities. Siemens AG anchors European demand with its process instrumentation portfolio and regional service density.
Flare stack monitoring systems encompass sensor arrays, analyzers, and software platforms that detect combustion efficiency, flame presence, and emission parameters at elevated industrial vents, typically operating across temperature ranges from ambient to over 1,500°C with response thresholds measured in milliseconds. Infrared systems dominate current installed bases due to their proven reliability in hydrocarbon-rich environments and lower total cost of ownership across decade-long asset cycles. Drone-based monitoring technology represents the fastest-expanding segment as operators seek to reduce manned stack access and satisfy OSHA confined space requirements. Continuous emission monitoring technology commands the deepest margin pools because regulatory compliance mandates create sticky, long-term service contracts with process operators.
EPA flare enforcement under the Clean Air Act and New Source Performance Standards shapes product specifications and replacement cycles for U.S. installations. OSHA process safety management requirements and state-level air quality mandates in California and Texas add layered compliance obligations that expand system functionality requirements. Stakeholders must monitor evolving methane emission accounting rules and determine whether to prioritize sensor fusion architectures or specialized single-technology platforms as regulatory granularity intensifies.
Market Dynamics
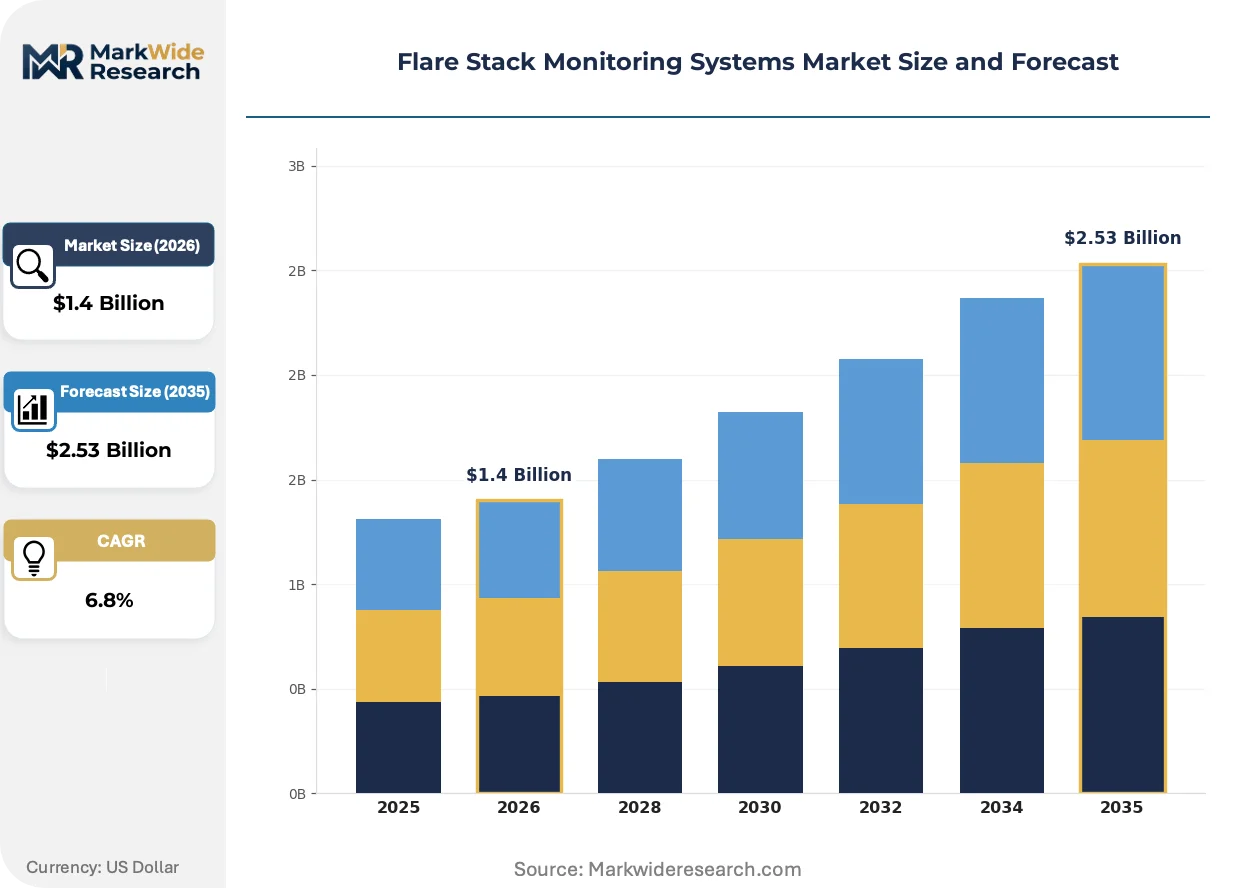
EPA flare enforcement under the Clean Air Act and New Source Performance Standards is compressing replacement cycles and forcing sensor architecture upgrades across U.S. refinery infrastructure. Operators now face simultaneous pressure from methane accounting rules and OSHA process safety mandates, restructuring how monitoring hardware is specified, procured, and maintained.
Growth Catalysts
- EPA New Source Performance Standards:Tightening emission thresholds for refinery flares mandate continuous monitoring upgrades, creating replacement demand across existing installations.
- Drone-based inspection protocols:OSHA confined space requirements are accelerating unmanned stack access adoption, reducing manned entry risks while expanding data collection frequency.
- Texas-Louisiana refinery corridor:Concentrated petrochemical capacity along the Gulf Coast generates clustered procurement volumes and standardized specification patterns.
Market Restraints
- Supply concentration in infrared sensor components:German and Japanese optical component suppliers control critical supply nodes, creating input vulnerability for system integrators.
- High-temperature sensor degradation:Thermal cycling above 1,500°C limits operational lifespan of exposed elements, forcing premature replacement and elevating lifetime ownership costs.
- California Air Resources Board complexity:State-specific monitoring protocols beyond federal requirements fragment product standardization and extend certification timelines.
Strategic Opportunities
- Sensor fusion architectures:Combining infrared, ultraviolet, and acoustic detection layers addresses single-technology blind spots and commands premium positioning.
- Offshore platform retrofits:Gulf of Mexico aging infrastructure requires monitoring system upgrades to meet Bureau of Safety and Environmental Enforcement guidelines.
- Predictive analytics integration:Machine learning overlay on flame stability data enables shift from reactive maintenance to condition-based intervention models.
Industry Challenges
- Certification timeline compression:EPA and state-level approval queues for new monitoring technologies extend product launch windows, delaying revenue recognition for hardware developers.
- Legacy distributed control system integration:Refinery automation platforms from prior decades lack native digital interfaces, requiring costly middleware development for seamless data flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flare Stack Monitoring Systems Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Infrared, Ultraviolet, Thermal Imaging, Acoustic, Electrochemical Monitoring Technology: Continuous Emission, Remote Sensing, Manual Inspection, Drone-based, Fiber Optic Application: Oil Refineries, Petrochemical Plants, LNG Facilities, Chemical Manufacturing, Power Plants End User: Process Operators, Environmental Agencies, Safety Inspectors, Maintenance Teams, Compliance Officers |
| Companies Covered | Emerson Electric Co., ABB, Honeywell International Inc., Thermo Fisher Scientific Inc., Siemens AG, Teledyne FLIR, Zeeco Inc., John Zink Company LLC, AMETEK Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flare Stack Monitoring Systems Market Shifts & Advancements
Flare stack monitoring is transitioning from discrete hardware sales toward integrated platform contracts that bundle sensing, analytics, and compliance reporting. This shift compresses vendor margins on equipment while expanding recurring service revenue pools and locking in long-term operator relationships.
Multi-spectral imaging is electrifying flame detection capabilities by combining short-wave and mid-wave infrared bands into unified sensor heads. Supermajor operators in Texas and Louisiana are deploying these systems at pilot scale, with full refinery-wide rollouts planned within eighteen months. The technology is electrifying competitive positioning by rendering single-band infrared systems technically obsolete for high-value applications.
EPA methane enforcement under the Inflation Reduction Act's waste emissions charge is tightening measurement accuracy requirements for large facility categories. Refineries above 25,000 metric tons CO2e annual emissions must install calibrated continuous monitoring rather than periodic manual sampling. Gulf Coast operators are responding by specifying third-party-certified analyzer systems with documented uncertainty budgets below five percent.
Buyer consolidation among integrated oil and gas majors is consolidating procurement authority into centralized engineering standards teams. Mid-size system vendors face exclusion from approved vendor lists unless they achieve pre-qualified status through extended field trials and documented mean-time-between-failure data. This pattern is most pronounced among operators with headquarters in Houston, where technical specification committees now dictate global facility standards.
Flare Stack Monitoring Systems Market Segmentation
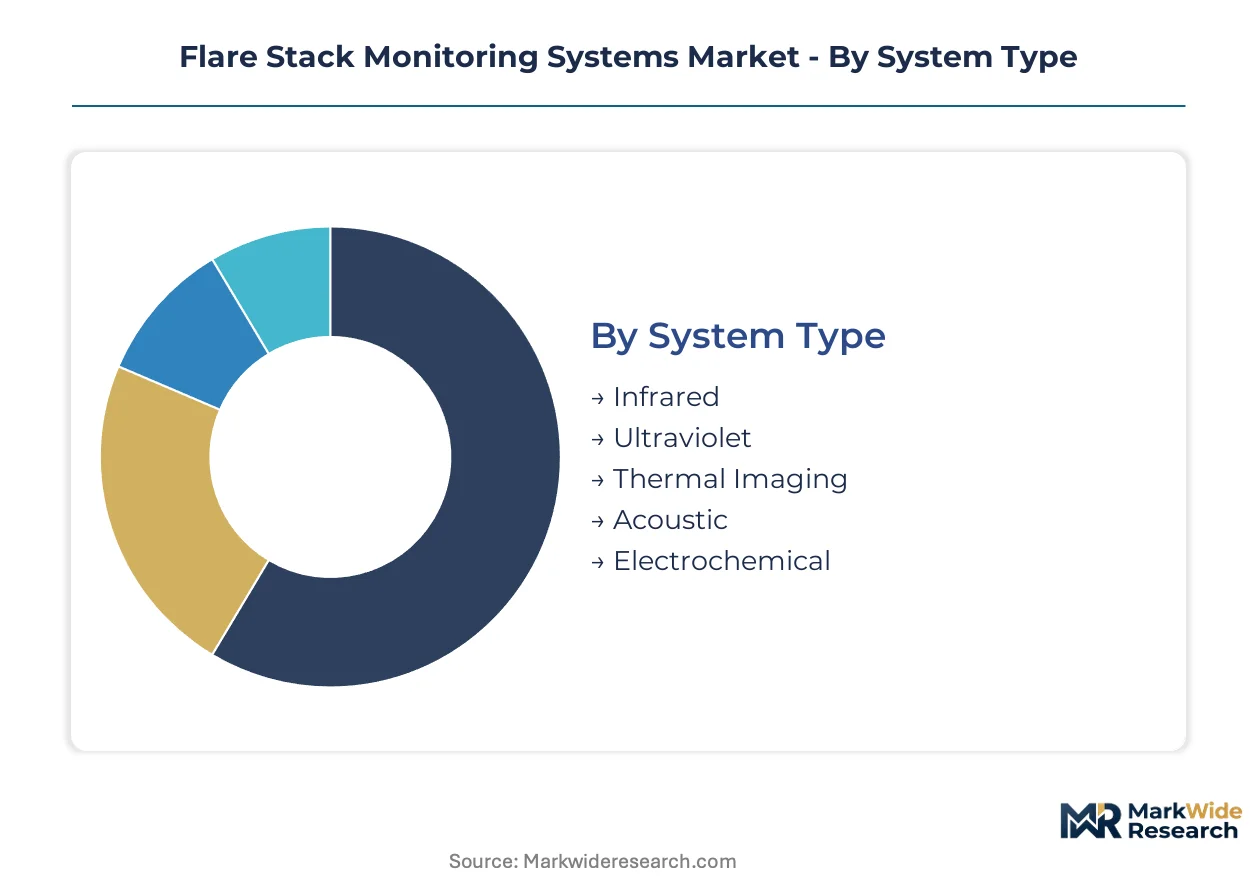
Flare stack monitoring systems fragment across detection physics, deployment architecture, and operator workflow integration. Procurement decisions hinge on emission chemistry, stack geometry, and regulatory jurisdiction rather than universal performance metrics.
System Type:
Optical component sourcing concentrates among German and Japanese suppliers, creating tiered availability of sensor subassemblies across detection modalities.
- Infrared:Detects hydrocarbon flame signatures through short-wave and mid-wave spectral bands. Gulf Coast refineries in Texas and Louisiana specify these systems for their proven reliability in high-humidity, hydrocarbon-rich environments where thermal cycling exceeds 1,500°C.
- Thermal Imaging:Captures two-dimensional temperature distributions across flame fronts and stack mouths. California refineries under CARB scrutiny deploy these for real-time combustion efficiency visualization to satisfy state-specific monitoring protocols beyond federal EPA requirements.
- Ultraviolet:Responds to UV radiation from excited molecular species in hydrocarbon flames. Petrochemical operators favor UV sensors for rapid flame presence detection with millisecond response thresholds.
- Acoustic:Monitors combustion roar frequency signatures to infer flame stability. Offshore platform operators in the Gulf of Mexico adopt these for environments where optical path obstruction from salt spray degrades infrared performance.
- Electrochemical:Measures specific gas concentrations through redox reactions at sensor electrodes. Maintenance teams deploy portable electrochemical units for spot-check validation of continuous monitor readings.
Infrared absorbs the bulk of installed capacity; thermal imaging is expanding most quickly.
Monitoring Technology:
Service contract structures diverge sharply between capital-intensive permanent installations and operational-expense inspection regimes.
- Continuous Emission:Permanently installed analyzer systems with calibrated uncertainty budgets below five percent. EPA methane enforcement under IRA waste emissions charges mandates these for refineries above 25,000 metric tons CO2e, creating sticky long-term service relationships.
- Drone-based:Unmanned aerial platforms carrying multi-spectral payloads. OSHA confined space requirements are accelerating adoption across Texas and Louisiana as operators eliminate manned stack entry risks.
- Remote Sensing:Ground-based or satellite-mounted spectroscopic systems measuring column-integrated emissions. Environmental agencies deploy these for fence-line monitoring of facility-wide emission fluxes.
- Fiber Optic:Distributed temperature sensing along fiber strands routed near stack structures. LNG facilities specify these for cryogenic leak detection concurrent with flare monitoring.
- Manual Inspection:Periodic visual and instrumental survey by certified personnel. Smaller chemical plants maintain these programs where continuous monitor capital costs exceed compliance penalty exposure.
Continuous emission technology locks in the deepest margin pools through regulatory-mandated service contracts; drone-based inspection protocols are climbing the fastest.
Application:
Process intensity and emission volume determine specification sophistication and replacement cycle frequency.
- Oil Refineries:Complex multi-flare installations with varying hydrocarbon streams. Gulf Coast facilities face compressed replacement cycles as EPA New Source Performance Standards tighten emission thresholds.
- Petrochemical Plants:Olefin and aromatics production with high-velocity flares. Texas-Louisiana corridor concentration generates clustered procurement volumes and standardized engineering specifications.
- LNG Facilities:Cryogenic processes with boil-off gas management requirements. Bureau of Safety and Environmental Enforcement guidelines drive monitoring system upgrades across aging Gulf of Mexico infrastructure.
- Chemical Manufacturing:Diverse specialty and commodity chemical operations with variable flare compositions. California facilities navigate CARB complexity that fragments product standardization.
- Power Plants:Natural gas turbine and process heater applications with intermittent flaring. These installations prioritize cost-minimized solutions given lower regulatory scrutiny relative to hydrocarbon processing.
Oil refineries command the specification standards that cascade to adjacent segments; LNG facilities are gaining share fastest on liquefaction capacity expansion.
End User:
Stakeholder incentives diverge between operational efficiency, regulatory enforcement, and asset integrity objectives.
- Process Operators:Refinery and plant personnel responsible for combustion efficiency and throughput. These buyers bundle monitoring hardware with distributed control system integration, favoring vendors with automation platform breadth.
- Compliance Officers:Personnel accountable for EPA, CARB, and state air quality mandate adherence. Their procurement authority centers on third-party-certified analyzer systems with documented uncertainty budgets.
- Safety Inspectors:OSHA process safety management auditors focused on confined space and flame-out risks. These users drive specification of redundant detection layers and unmanned access protocols.
- Maintenance Teams:Technical personnel executing sensor replacement and calibration. Their input favors modular architectures with field-replaceable components to minimize stack downtime.
- Environmental Agencies:Federal and state regulators conducting enforcement and facility permitting. These stakeholders shape baseline technical requirements that cascade through operator procurement specifications.
Process operators control capital allocation authority; compliance officers are expanding their influence fastest as regulatory granularity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery concentration along the Gulf Coast and tightening methane enforcement are redistributing procurement volumes toward jurisdictions with overlapping federal and state regulatory obligations.
United States
Texas and Louisiana host the densest refinery corridor globally, with operators deploying continuous emission monitors to satisfy EPA New Source Performance Standards. The Inflation Reduction Act's waste emissions charge mandates calibrated analyzer systems for facilities above 25,000 metric tons CO2e. Houston engineering teams now dictate global facility standards for supermajors headquartered there.
Germany
Industrial process automation demand concentrates in the chemical manufacturing belt along the Rhine. The EU Green Deal's methane reduction targets and national implementation of the Industrial Emissions Directive are compressing upgrade cycles for aging flare infrastructure. BASF and Bayer facilities in Ludwigshafen and Leverkusen specify multi-spectral detection layers.
China
Petrochemical capacity expansion in the Yangtze River Delta and Pearl River Delta is generating new-build monitoring specifications. The Ministry of Ecology and Environment's tightening standards for volatile organic compound emissions are forcing domestic refiners toward continuous monitoring architectures. Sinopec installations in Zhenhai and Maoming are piloting sensor fusion systems.
Saudi Arabia
Aramco's Master Gas System expansion and downstream integration investments are driving monitoring system procurement across the Eastern Province. The Saudi Green Initiative's methane intensity targets are accelerating replacement of manual inspection regimes with automated detection. Jubail Industrial City facilities are standardizing on third-party-certified analyzer platforms.
India
Reliance Industries' Jamnagar refinery complex and public sector undertakings in Gujarat and Maharashtra are expanding emission monitoring coverage. Central Pollution Control Board mandates for petroleum refinery emissions are tightening measurement frequency requirements. Hazira and Panipat industrial clusters are transitioning from periodic sampling toward continuous analyzer installations.
Flare Stack Monitoring Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue drone-based inspection and predictive analytics overlays to bypass entrenched automation relationships. The vendor base stratifies across three tiers: diversified industrial conglomerates with bundled platform offerings, specialized combustion technology houses with embedded refinery relationships, and component suppliers feeding system integrators. Competitive positioning hinges on pre-qualified vendor status with supermajor engineering committees and documented mean-time-between-failure performance. Consolidation pressure is intensifying as procurement authority centralizes into Houston-based technical specification teams.
Among diversified automation providers, Emerson Electric Co., Honeywell International Inc., and Siemens AG exemplify the platform-bundling archetype that dominates capital allocation authority among process operators. These firms leverage existing distributed control system relationships to embed monitoring hardware within broader automation contracts. Specialized detection technology is represented by Teledyne FLIR and ABB, which occupy positions emphasizing optical and thermal sensing expertise rather than full-stack integration. Component and subsystem specialists including AMETEK Inc. and Zeeco Inc. sit within the supply tier, providing analyzers and combustion hardware to system integrators seeking field-replaceable modular architectures.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB |
| Honeywell International Inc. |
| Thermo Fisher Scientific Inc. |
| Siemens AG |
| Teledyne FLIR |
| Zeeco Inc. |
| John Zink Company LLC |
| AMETEK Inc. |
| Others |
Supply & Pricing Matrix
Optical engineering talent concentration in southwestern Germany and Osaka-Kobe manufacturing corridors feeds labor-cost differentials that separate premium multi-spectral systems from standard infrared configurations. EPA calibration requirements and CARB certification complexity widen these pricing spreads as compliance documentation adds fixed cost layers regardless of production volume.
Pricing Analysis
Volume concentrates in standard-tier infrared systems while margins pool in continuous emission monitoring platforms with bundled service contracts. Price differentiation hinges on EPA third-party certification status and mean-time-between-failure documentation depth. Pricing pressure stems from buyer consolidation among Houston-based supermajor engineering committees standardizing global specifications. Smaller chemical plants exhibit highest price sensitivity where compliance penalty exposure falls below continuous monitor capital costs.
Supply Chain Analysis
Specialized optical coating technicians in Germany and Japan constrain throughput for infrared detector subassemblies. Critical inputs include germanium lenses, indium antimonide detectors, and high-temperature fiber optic cables. Single-source vulnerability concentrates in Japanese precision optical component suppliers. Distribution runs through system integrators with pre-qualified vendor status at major refinery operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into sensor fabrication represents the dominant competitive lever as vendors seek to escape German and Japanese optical component dependency. Control over detector production tightens margin capture and accelerates EPA certification timelines.
For Market Incumbents: Deploy predictive analytics overlays to lock in recurring service revenue and raise switching costs for refinery operators. Deepen embedded relationships with Houston engineering standards committees to exclude emerging drone-based entrants from approved vendor lists. Prioritize in-house production of infrared detector subassemblies to reduce exposure to Japanese supply concentration.
For New Entrants and Emerging Players: Capture unmanned aerial inspection contracts at mid-size chemical plants where supermajor procurement standards do not apply. Target California facilities navigating CARB-specific protocols that fragment standardized vendor lists. Lead with OSHA confined space compliance narratives to bypass entrenched automation platform relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with sensor fusion technology specialists given EPA methane enforcement tightening measurement accuracy requirements. Five-to-ten year viability favors vendors with documented uncertainty budgets below five percent and third-party-certified analyzer platforms. Watch Bureau of Safety and Environmental Enforcement guideline updates for offshore platform retrofit inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Combines infrared, ultraviolet, and acoustic layers to address single-technology blind spots at Gulf Coast refineries. |
| Predictive Analytics Platform Integration | Machine learning overlays on flame stability data enable condition-based maintenance for Texas-Louisiana operators. |
| Backward Integration into Detector Fabrication | In-house production of germanium lenses and indium antimonide sensors reduces Japanese supply chain vulnerability. |
| Drone-Based Inspection Protocol Certification | OSHA-compliant unmanned stack access eliminates confined space risks while expanding data collection frequency. |
| EPA Third-Party Certification Investment | Documented uncertainty budgets below five percent satisfy IRA waste emissions charge mandates for large facilities. |
Research Methodology
EPA enforcement databases, Bureau of Safety and Environmental Enforcement incident reports, and SEC 10-K filings from automation providers formed the secondary backbone for demand quantification. Primary interviews with refinery maintenance directors, compliance officers at Gulf Coast facilities, optical component procurement leads, and drone inspection service operators validated specification trends and replacement cycle assumptions. Bottom-up installation counts across Texas, Louisiana, and California refineries triangulated against top-down vendor revenue disclosures.
Historical trendline analysis of continuous emission monitor deployment rates informed projection elasticity across the modeling period. Segmentation dimensions encompassed detection physics, monitoring technology architecture, application process intensity, and end-user procurement authority. CAGRs derived from fitted growth curves adjusted for regulatory enforcement phase-in schedules and methane accounting rule implementation timelines. Forecast inputs incorporated refinery capacity utilization rates and flare management rule amendment trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA New Source Performance Standards amendment timing and Japanese optical component export restrictions. Projections reflect assumptions regarding supermajor procurement centralization and drone regulatory framework maturation. Material deviation in IRA waste emissions charge enforcement intensity or OSHA confined space rule revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
One-Way Valve Market
Valves
Safety Valve Test Benches Market
Valves
Backflow Preventers Market
Valves
Angle Opening Ball Locator Market
Valves
Stainless Steel Valve Tag Market
Valves
Butterfly Valves Market
Valves
Motorized Valves Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Reciprocating Compressor Components Market
Valves
Steam Safety Valve Market
Valves
Isolator Valves Market
Valves
Aerospace Valves Market
Valves
Global Plastic Valves Market
Valves
Global Flow Control Market
Valves
Magnetic Coupler Market
Valves
Hydraulic Diaphragm Valve Market