
 Safety Valve Test Benches Market | 2026-2036
Safety Valve Test Benches Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Valve Test Benches Market Insights
Stainless steel is consolidating its position as the dominant material in high-pressure test bench construction, displacing carbon steel in corrosive environments where sour gas exposure demands superior metallurgical performance. VYC Industrial leverages captive foundry capacity to control alloy sourcing for offshore-rated systems. Hydratron anchors its position through deep specialization in hyperbaric simulation technology for subsea valve validation. EFCO differentiates by sustaining long-term service contracts with European petrochemical majors.
Safety valve test benches are precision-engineered systems designed to verify set pressure, reseating tolerance, and leak-tightness across spring-loaded, pilot-operated, and safety relief valves, typically achieving accuracy within one percent of calibrated set pressure. Their primary purpose is to certify that pressure-relief devices perform within design parameters before installation or after maintenance turnaround. Automated test benches command the strongest margin pools as end users phase out manual dial-gauge configurations that introduce operator-dependent variability. Digital testing technology is displacing mechanical methods in aerospace applications where data logging and traceability requirements have tightened under NADCAP accreditation protocols.
API standards govern product design and testing protocols in North American oil and gas applications, while the EU Pressure Equipment Directive mandates CE-marked conformity for test systems sold into European process industries. OSHA process safety management rules in the United States drive recurring inspection cycles that sustain aftermarket demand for bench recertification and upgrade services. The central strategic question facing stakeholders is whether to prioritize backward integration into sensor and data-acquisition hardware or to partner with established instrumentation suppliers as test protocols migrate toward fully networked, Industry 4.0 architectures.
Market Dynamics
Automated digital test systems are compressing replacement cycles for mechanical safety valve benches as facilities chase API 527 and ISO 4126 certification deadlines. This technology transition is redistributing margin pools toward sensor-integrated platforms while stranding legacy dial-gauge assets.
Growth Catalysts
- API 527 Certification Mandates:North American refineries face compressed turnaround schedules that demand faster valve validation throughput. Automated benches cut test cycle time by eliminating manual gauge reading and handwritten logging.
- Sour Gas Metallurgy Requirements:Stainless steel construction specifications for H₂S-rich environments in Middle Eastern upstream operations are forcing replacement of carbon steel test infrastructure. Corrosion-resistant alloys now dominate offshore procurement tenders.
- German Chemical Cluster Density:The Rhine-Ruhr and Ludwigshafen industrial corridors sustain concentrated demand for high-precision test benches serving both domestic maintenance and export calibration services.
Market Restraints
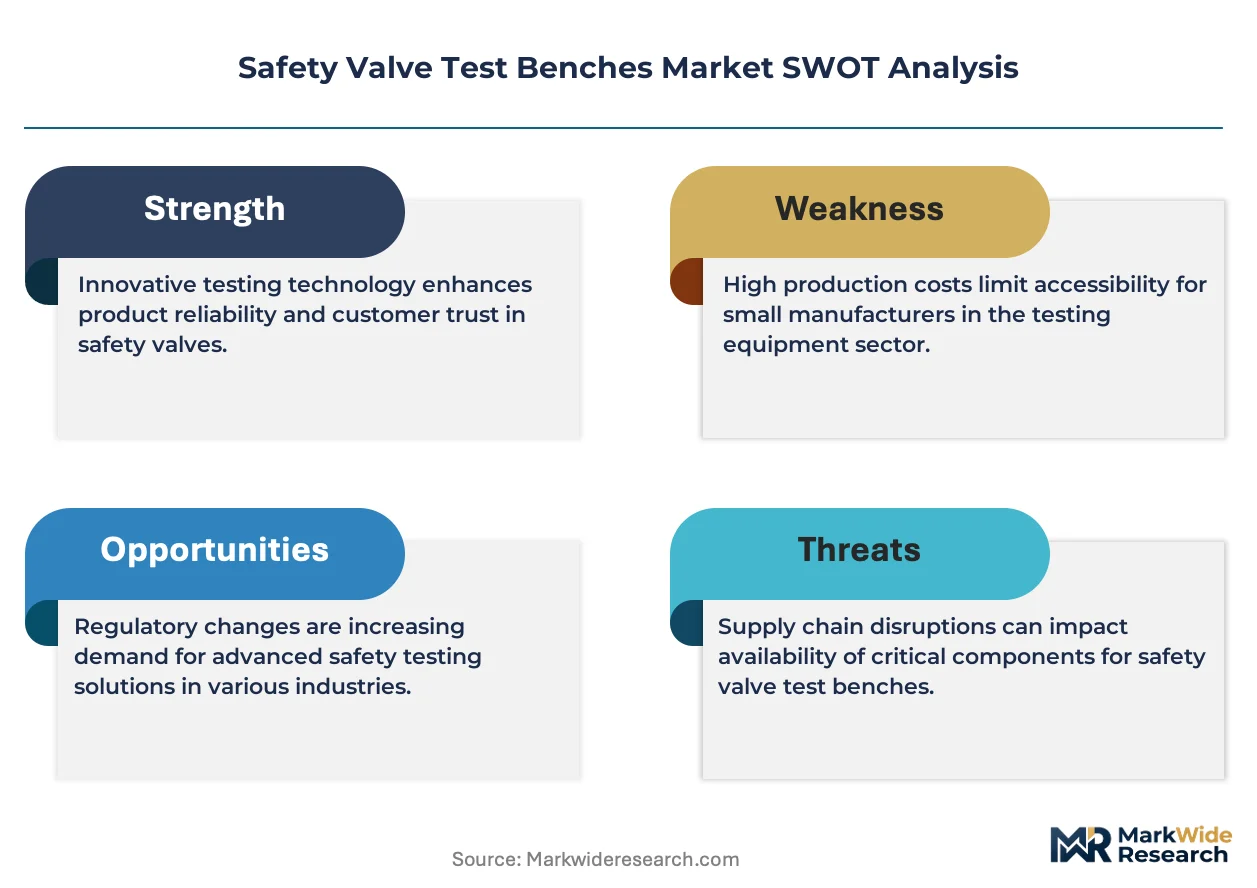
- Sensor Hardware Cost Volatility:Precision pressure transducers and data-acquisition modules face supply concentration among Japanese and German component specialists. Input cost spikes transmit directly to bench manufacturer margins.
- CE Marking Compliance Friction:The EU Pressure Equipment Directive imposes conformity assessment delays that extend sales cycles for non-European manufacturers by four to six months.
- Manual Test Kit Substitution:Low-complexity portable testers serve intermittent maintenance needs in smaller process plants. These units satisfy regulatory minimums without capital-intensive fixed bench investment.
Strategic Opportunities
- India Refinery Expansion:Reliance Industries and Indian Oil are building world-scale petrochemical complexes with integrated valve testing facilities. Domestic production incentives under the PLI scheme favor local bench assembly partnerships.
- Hyperbaric Subsea Validation:Deepwater production systems require pressure simulation beyond standard bench ratings. Hyperbaric chamber integration creates premium pricing tiers for subsea valve specialists.
- NADCAP Aerospace Accreditation:Precision casting and forging suppliers to Boeing and Airbus supply chains must document traceable test data. Digital benches with automated logging satisfy audit protocols that mechanical systems cannot meet.
Industry Challenges
- Cross-Disciplinary Technician Scarcity:Bench operation now demands fluency in pneumatic systems, PLC programming, and calibration software. Training pipelines for mechatronics technicians lag deployment timelines.
- Legacy System Integration Complexity:Brownfield facilities require digital benches to interface with decades-old plant DCS architectures. Custom protocol translation extends commissioning schedules and strains project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Valve Test Benches Market |
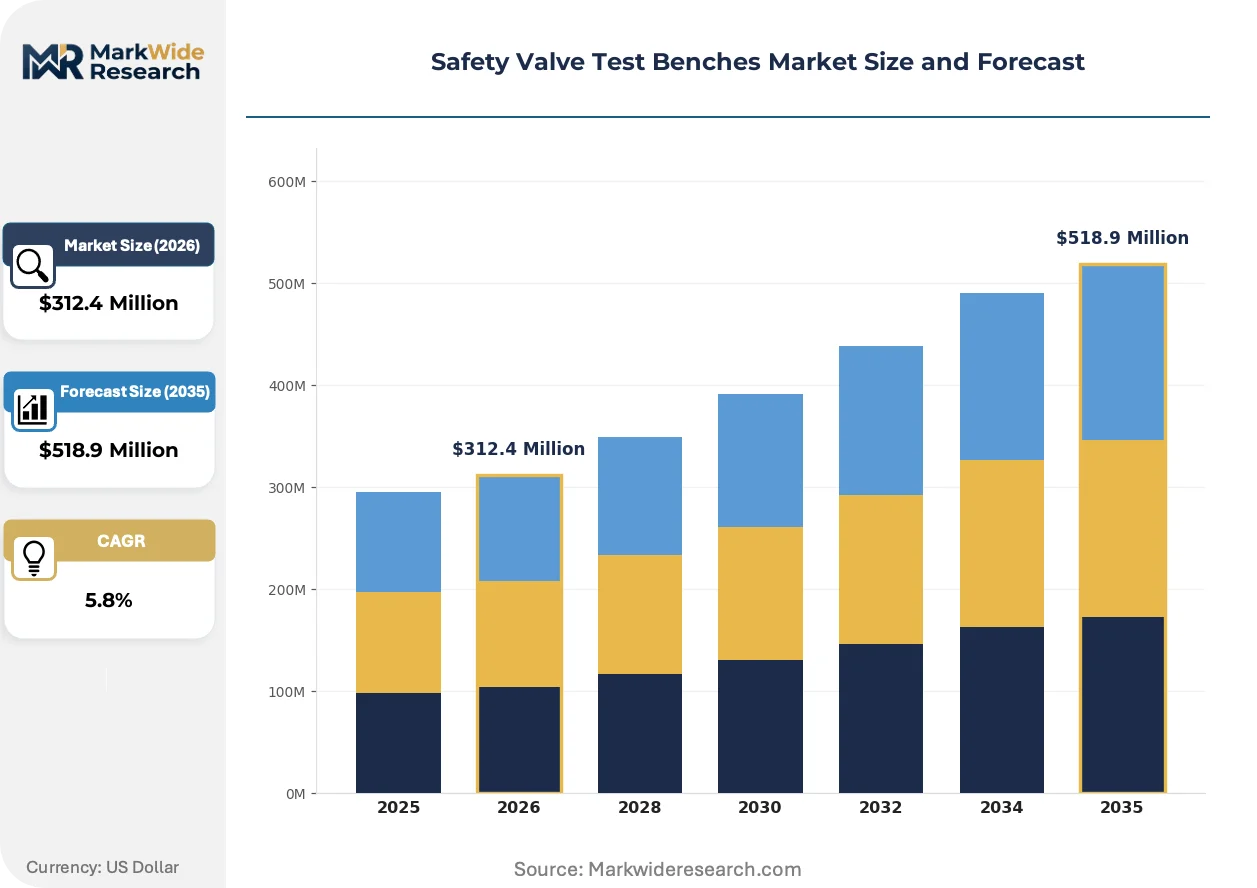
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Test Benches, Pneumatic Test Benches, Manual Test Benches, Automated Test Benches End User: Manufacturers, Maintenance Facilities, Research Institutions, Industrial Users Technology: Digital Testing, Mechanical Testing, Computerized Systems, Analog Testing Application: Aerospace, Oil & Gas, Manufacturing, Water Treatment |
| Companies Covered | VYC Industrial, METRUS, EFCO, Italcontrol, Nagman, Hydratron, REVALVE, Ventil Test Equipment BV, Think PC PROGETTI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Valve Test Benches Market Trends and Innovations
Digital thread architectures are threading through safety valve validation workflows, collapsing the distance between shop-floor testing and enterprise asset management systems. This connectivity shift is redefining how test data flows into regulatory submissions and predictive maintenance algorithms.
Edge-computing test controllers are unifying pressure control, data logging, and cloud transmission within single hardware enclosures. Aerospace suppliers in the US Pacific Northwest are deploying these units to satisfy NADCAP traceability mandates without separate IT infrastructure investments. The technology is unifying what previously required three discrete subsystems, compressing both capital outlay and footprint requirements for new installations.
The EU F-Gas Regulation is tightening containment verification protocols for valves handling fluorinated greenhouse gases. Chemical processors in Belgium and the Netherlands now specify helium leak detection integration as standard bench configuration. Refrigeration equipment manufacturers face parallel pressure from the regulation, driving demand for test systems capable of micro-leak quantification.
Service unbundling is fragmenting traditional bench procurement patterns. European petrochemical majors now separate hardware acquisition from calibration contracts and software subscription renewals. This shift concentrates purchasing authority within procurement functions rather than engineering departments, compressing vendor margins through competitive tendering while extending customer lifetime value for service-capable suppliers. The pattern is most pronounced in Germany, where long-term maintenance outsourcing has normalized multi-year service agreements.
Safety Valve Test Benches Market Segmentation
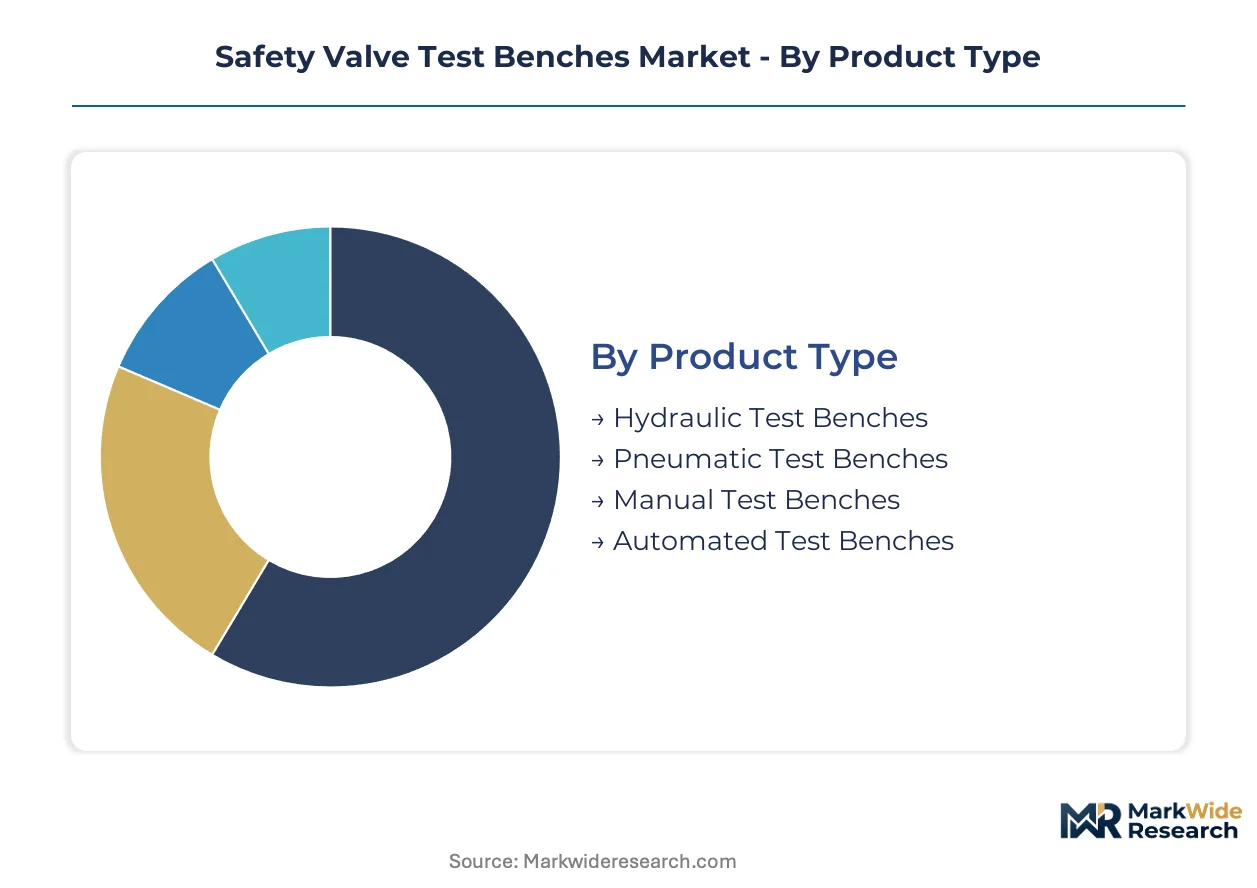
Segmentation in safety valve test benches reveals how specification intensity varies across pressure ratings, automation levels, and end-use certification requirements. Procurement patterns diverge sharply between facilities seeking API 527 compliance and those serving intermittent maintenance needs.
Product Type:
Customization intensity spans from fully configurable automated platforms to standardized portable units, with specification depth directly correlating to pressure range and data logging requirements.
- Automated Test Benches:Sensor-integrated platforms combine precision pressure control with automated data acquisition for API 527 and ISO 4126 certification workflows. Demand concentrates in German chemical clusters and Middle Eastern upstream operations where turnaround compression mandates faster throughput. These systems displace mechanical configurations as facilities face recertification deadlines.
- Hydraulic Test Benches:High-force fluid power systems achieve set pressure verification for large-bore safety relief valves in refinery and petrochemical service. Sour gas exposure in Saudi Arabian and UAE upstream projects drives stainless steel construction specifications that exceed carbon steel ratings.
- Pneumatic Test Benches:Compressed-air systems serve lower-pressure spring-loaded valve validation with faster cycle times.
- Manual Test Benches:Dial-gauge configurations persist in intermittent-use maintenance shops where capital constraints outweigh throughput requirements.
Leading the category by volume: Manual Test Benches. Expanding most quickly: Automated Test Benches.
End User:
Customer sophistication tiers separate capital-intensive validation facilities from intermittent-service operators, with contract structure and service attachment rates varying accordingly.
- Maintenance Facilities:Third-party valve service shops perform recertification under OSHA process safety management inspection cycles and EU Pressure Equipment Directive mandates. These operators in the US Gulf Coast and Rhine-Ruhr corridor sustain recurring aftermarket demand for bench recalibration and software upgrades.
- Manufacturers:OEM validation laboratories certify safety relief valves prior to shipment, requiring NADCAP traceability for aerospace suppliers and CE marking conformity for European process industry sales.
- Industrial Users:In-house maintenance departments at integrated petrochemical sites operate captive test infrastructure.
- Research Institutions:Universities and national laboratories acquire specialized hyperbaric simulation capability for subsea valve development.
Highest specification concentration: Maintenance Facilities. Fastest contract value growth: Manufacturers.
Technology:
Architecture maturity separates legacy electromechanical platforms from digitally native systems, with integration depth determining compliance eligibility for traceability-sensitive applications.
- Digital Testing:Edge-computing controllers unify pressure regulation, automated logging, and cloud transmission within single enclosures. US Pacific Northwest aerospace suppliers deploy these units to satisfy NADCAP accreditation without separate IT infrastructure investments.
- Computerized Systems:PLC-based platforms bridge mechanical actuation with electronic data capture for facilities transitioning from dial-gauge methods.
- Mechanical Testing:Spring-loaded gauge configurations persist where regulatory minimums do not mandate electronic records.
- Analog Testing:Basic pressure measurement systems serve low-complexity validation in non-critical service.
Widest installed base: Mechanical Testing. Steepest replacement trajectory: Digital Testing.
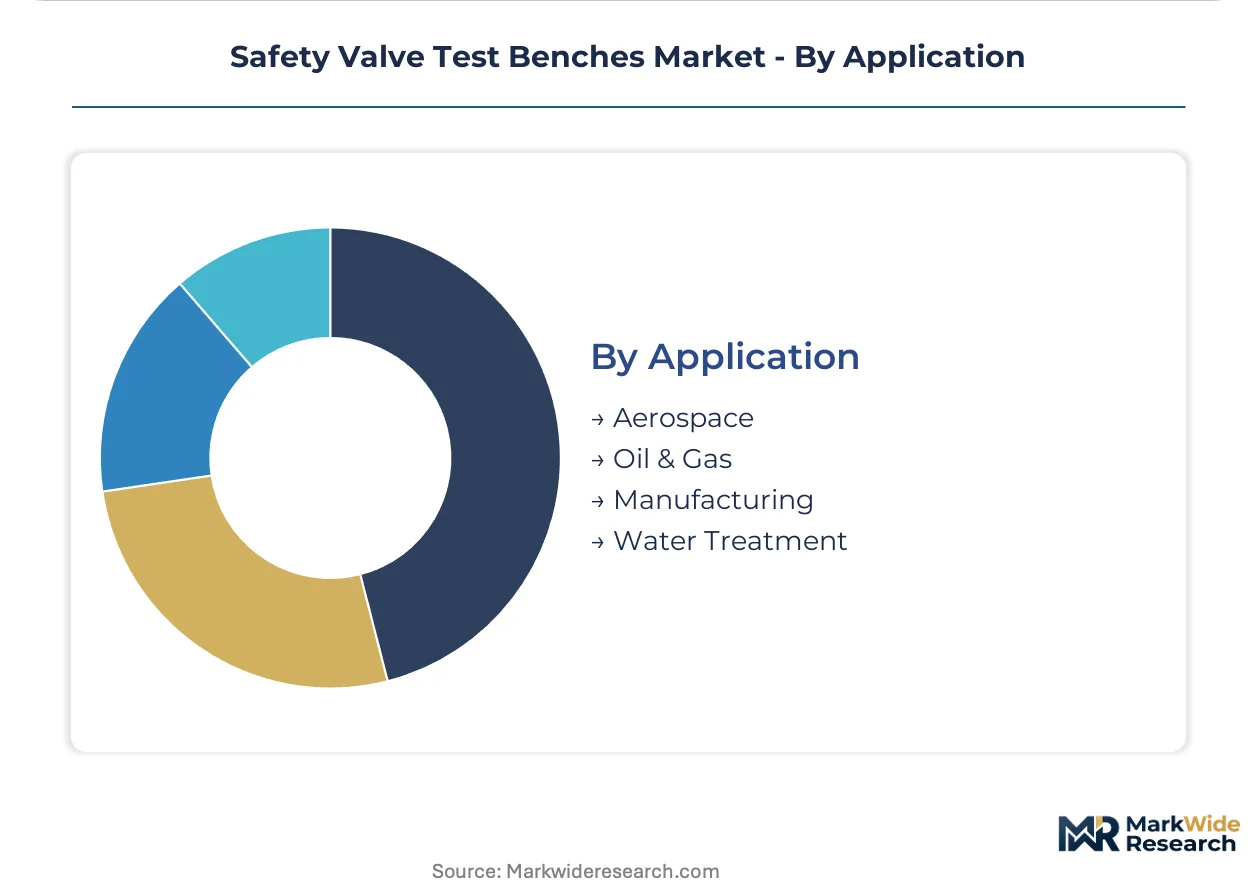
Application:
Operating environment severity drives metallurgy and pressure rating specifications, with offshore and aerospace applications demanding validation capabilities beyond standard industrial ratings.
- Oil & Gas:Upstream, midstream, and downstream facilities require H₂S-resistant alloy construction for sour gas exposure. Middle Eastern operators are expanding valve testing infrastructure to meet compressed turnaround schedules.
- Aerospace:Precision casting and forging suppliers to Boeing and Airbus supply chains must document traceable test data under NADCAP protocols that mechanical systems cannot satisfy.
- Manufacturing:General industrial pressure relief device validation spans boiler safety valves and process equipment protection.
- Water Treatment:Municipal and industrial water systems require lower-pressure validation for pump protection and pipeline safety.
Deepest specification requirements: Oil & Gas. Fastest accreditation-driven upgrade cycle: Aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in the Middle East are concentrating valve testing infrastructure investment as sour gas production scales. Tax incentives in Saudi Arabia's Jubail Industrial City and the UAE's Khalifa Industrial Zone are drawing European and Asian equipment suppliers into long-term service partnerships.
United States
Gulf Coast refineries in Texas and Louisiana are replacing mechanical test benches ahead of OSHA process safety management inspection cycles. The EPA's refinery sector risk rule is compressing turnaround schedules that demand faster valve validation throughput. Houston-area maintenance facilities sustain the densest concentration of third-party recertification shops serving upstream, midstream, and downstream operators.
Germany
The Rhine-Ruhr and Ludwigshafen chemical corridors anchor European demand for high-precision automated test systems. CE marking requirements under the EU Pressure Equipment Directive extend sales cycles for non-European manufacturers by four to six months. Bavaria-based specialized manufacturers export calibration services across European process industry clusters.
Saudi Arabia
Upstream operators in the Eastern Province are expanding valve testing infrastructure to meet compressed turnaround schedules for sour gas facilities. The Saudi Vision 2030 industrial localization program incentivizes domestic assembly partnerships for test bench manufacturers. Jubail Industrial City hosts the region's densest concentration of pressure equipment validation facilities serving Aramco supply chains.
India
Reliance Industries and Indian Oil are building integrated valve testing facilities at world-scale petrochemical complexes in Gujarat and Maharashtra. The PLI scheme for capital goods production favors local bench assembly partnerships over direct imports. The Mumbai-Pune industrial corridor is emerging as a service hub for Middle Eastern export markets.
China
State-owned refiners in Shandong and Liaoning are upgrading test infrastructure to meet stricter GB standards for pressure relief device certification. The MIIT's smart manufacturing initiatives are accelerating digital test bench adoption in provincial chemical clusters. The Yangtze River Delta concentration of precision equipment manufacturers is developing domestic sensor-integrated platforms to reduce reliance on Japanese and German component imports.
Safety Valve Test Benches Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automated system providers commanding premium positioning against portable kit assemblers. The vendor base organizes into three tiers: integrated platform specialists with captive sensor partnerships, regional fabricators serving maintenance facility procurement, and portable equipment distributors addressing intermittent-use demand. Consolidation pressure is building as certification complexity favors vendors with in-house calibration software development and multi-year service contract capabilities. Geographic expansion through local assembly partnerships and technology licensing for hyperbaric simulation features represent the dominant competitive vectors.
Among European-headquartered specialists, VYC Industrial and EFCO occupy positions reflecting distinct strategic archetypes. VYC Industrial exemplifies the vertically integrated model through captive foundry capacity controlling alloy sourcing for offshore-rated systems. EFCo represents the service-anchored approach through sustained long-term maintenance agreements with European petrochemical majors. Hydratron, with its UK-originated name, anchors the hyperbaric specialization tier for subsea valve validation where pressure simulation requirements exceed standard industrial ratings. These three illustrate how metallurgical control, service contract depth, and technical specialization respectively define sustainable positioning as test protocols migrate toward Industry 4.0 architectures.
| Leading Market Players |
|---|
| VYC Industrial |
| METRUS |
| EFCO |
| Italcontrol |
| Nagman |
| Hydratron |
| REVALVE |
| Ventil Test Equipment BV |
| Think PC PROGETTI |
| Others |
Pricing and Supply Chain Analysis
Precision pressure transducers from Japanese and German component specialists feed into three distinct pricing tiers for safety valve test benches, with API 527-certified automated platforms commanding substantial premiums over manual dial-gauge configurations. Sour gas metallurgy requirements for stainless steel construction in Middle Eastern upstream operations further stratify procurement costs, as corrosion-resistant alloys displace carbon steel in offshore-rated systems.
Pricing Analysis
Short lead-time premiums separate urgent replacement procurement from standard-order scheduling, with European petrochemical majors paying elevated rates for CE-marked automated benches during compressed turnaround windows. Pricing stratifies across premium, standard, and economy tiers based on certification level—API 527 and ISO 4126 compliance tiers versus non-certified manual units—and customization depth for hyperbaric subsea applications. Cost compression in the portable manual segment is intensifying because low-complexity testers satisfy regulatory minimums without capital-intensive fixed bench investment. Small process plants with intermittent maintenance needs exhibit the highest price sensitivity, while integrated petrochemical sites prioritize throughput and traceability over unit cost.
Supply Chain Analysis
Saudi Vision 2030 localization mandates and India's PLI scheme for capital goods are reshaping sourcing patterns, pressuring European and Asian suppliers to establish domestic assembly partnerships rather than direct export models. Manufacturing concentration spans Germany for high-precision automated systems, China for sensor-integrated platforms serving provincial chemical clusters, and India for emerging export-oriented production. Component sourcing draws from Japanese specialists for precision pressure transducers, German suppliers for data-acquisition modules, and domestic foundries for stainless steel alloy castings. Single-source vulnerability in sensor hardware creates exposure to input cost spikes that transmit directly to bench manufacturer margins. Distribution runs through specialized industrial equipment distributors serving maintenance facilities, direct OEM relationships with petrochemical majors, and service-anchored long-term contracts with European chemical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The safety valve test benches market functions as a cost-of-compliance arena where API 527 and ISO 4126 certification requirements erect substantial barrier-to-entry moats, privileging incumbents with established calibration software and multi-year service contract capabilities.
For Market Incumbents: Anticipate margin compression from sensor hardware cost volatility by securing captive partnerships with Japanese and German component specialists, while defending against portable manual kit substitution through deeper software subscription bundling. Capacity addition in Jubail Industrial City and Khalifa Industrial Zone captures Middle Eastern sour gas infrastructure expansion, cementing position before local-content rules mature. For New Entrants and Emerging Players: Capture white space in India's PLI-favored domestic assembly partnerships, where Reliance Industries and Indian Oil procurement lacks established supplier relationships for world-scale petrochemical complexes. Hyperbaric subsea validation for deepwater production systems offers penetrable premium tier entry, with pressure simulation requirements exceeding standard industrial ratings and fewer entrenched competitors than onshore automated benches. Go-to-market positioning should anchor on NADCAP aerospace accreditation support, where precision casting suppliers demand traceable test data that mechanical systems cannot deliver. For Investors and Strategic Acquirers: Saudi Aramco supply chain localization announcements are the leading indicator that Middle Eastern market access will soon require domestic manufacturing presence rather than export models. Over the projection horizon, vertically integrated specialists with captive foundry capacity and in-house calibration software development represent the most defensible acquisition archetypes. Watch for hyperbaric simulation technology licensing deals as the inflection signal that subsea valve validation is consolidating toward specialized platform providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | Captive supply of precision pressure transducers insulates margins from Japanese and German component specialist cost volatility. |
| Hyperbaric Chamber Technology Licensing | Subsea valve validation capabilities unlock premium pricing tiers for deepwater production systems beyond standard ratings. |
| Local Assembly Partnership in Saudi Arabia | Saudi Vision 2030 localization requirements position suppliers for Aramco supply chain access under domestic-content rules. |
| NADCAP Accreditation Software Development | Automated logging capabilities satisfy aerospace audit protocols that mechanical systems cannot meet for Boeing and Airbus suppliers. |
| Long-Term Service Contract Unbundling | European petrochemical procurement pattern shifts concentrate purchasing authority while extending customer lifetime value for service-capable vendors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with maintenance facility directors, petrochemical plant engineers, OEM validation laboratory managers, and aftermarket service heads. OSHA process safety management documentation, EU Pressure Equipment Directive conformity assessments, API 527 certification databases, and SEC filings from listed industrial equipment manufacturers provided cross-referenced validation points. Bottom-up demand modeling from individual facility procurement patterns converged with top-down market sizing across pressure rating tiers and automation levels.
Data-stream reconciliation unified shipment volumes from German and Chinese manufacturing clusters with end-user installation records at Middle Eastern upstream facilities and US Gulf Coast refineries. Segmentation dimensions spanned product type, end user sophistication tier, technology architecture maturity, and application severity across oil and gas, aerospace, and chemical processing. CAGRs derived from weighted average replacement cycle compression and certification mandate deadlines, with specific adjustment for sensor hardware supply constraints and CE marking compliance friction extending non-European manufacturer sales cycles.
The model holds under stable regulatory enforcement of API 527 and ISO 4126 standards; deviation in certification timeline delays or sensor trade restrictions would shift replacement trajectories. Forecasts reflect assumptions regarding turnaround schedule compression and sour gas production scaling, with aerospace NADCAP accreditation pace and India PLI scheme implementation representing specific revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Solenoid Valves Market
Valves
Transmission Overload Protectors Market
Valves
Global Pressure Relief Valves Market
Valves
Pipeline Pigging Equipment Market
Valves
Fluid Power Cylinder Market
Valves
Pipeline Pigging System Market
Valves
APAC Valves Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Total Containment Vessels Market
Valves
Pigging Valves Market
Valves
Valve Cover Gasket Market
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Valve Seat Inserts Market
Valves
United States Valves Market
Valves
Air Jet Ejectors Market
Valves
Thermal Power Valve Market