
 United States Valves Market | 2026-2036
United States Valves Market Size, Share, and Industry Trends Forecast 2026-2036
United States Valves Market Analytics
Aftermarket valve monitoring and predictive maintenance subscriptions is restructuring how OEMs capture lifetime value from installed bases. Emerson Electric Co. leverages its Plantweb digital ecosystem to lock in recurring revenue from process plant operators. Flowserve Corporation anchors its position through embedded diagnostics in rotating equipment. Crane Company competes via specialized nuclear-grade valve servicing contracts that extend replacement cycles.
Valves are mechanical flow-control devices engineered to regulate, direct, or shut off fluid passage through piping systems, typically rated by pressure class, temperature tolerance, and Cv flow coefficient. Stainless steel ball valves dominate hydrocarbon processing due to corrosion resistance under high-cycle thermal stress. Butterfly valves lead HVAC and water treatment applications where space constraints and cost sensitivity shape procurement. Gate valves retain share in upstream oil and gas isolation duties where full-bore, low-pressure-drop performance commands premium positioning.
EPA enforcement of Clean Water Act discharge limits and OSHA Process Safety Management standards shape material selection and leak-tightness specifications across US manufacturing and utility end users. The Department of Energy's efficiency mandates for federal buildings redirect HVAC specification toward low-leakage damper and control valve packages. Stakeholders must track how state-level PFAS remediation funding reshapes municipal water infrastructure procurement priorities.
Market Dynamics
Material substitution mandates from EPA's Lead and Copper Rule revisions are forcing wholesale transitions from brass to stainless steel alloys across municipal water infrastructure, compressing supplier qualification timelines and rewiring procurement specifications.
Growth Catalysts
- Smart Metering Infrastructure:Water utilities in Texas and California are embedding pressure-regulating valves within AMI networks to enable real-time leak detection and demand-response optimization.
- EPA Lead and Copper Rule:Federal mandates for lead-free potable water components are accelerating stainless steel and low-lead bronze adoption in residential and commercial building retrofits.
- Gulf Coast Petrochemical Expansion:Capacity additions across Louisiana and Texas chemical corridors are generating demand for high-pressure ball valves rated for hydrogen sulfide service.
Market Restraints
- Stainless Steel Input Volatility:Nickel and molybdenum price swings from Indonesian and Russian supply disruptions compress margin predictability for valve casters.
- Domestic Foundry Concentration:Gray iron and ductile iron casting capacity clusters in Ohio and Pennsylvania, creating geographic single-source vulnerability for waterworks valve OEMs.
- Technical Limitation in Cryogenic Service:Extended stem sealing reliability below minus 196 degrees Celsius remains unproven for domestic butterfly valve architectures, constraining LNG export terminal specification.
Strategic Opportunities
- PFAS Remediation Infrastructure:Congressional infrastructure funding for per- and polyfluoroalkyl substance filtration is opening municipal procurement channels for corrosion-resistant control valve packages.
- Hydrogen Blending Networks:Convergence of electrochemical compression and high-cycle metal-seated valve technologies enables participation in emerging power-to-gas storage projects.
- Direct-to-Utility E-Procurement:Digital platforms are disintermediating traditional distribution layers, allowing specialized manufacturers to capture specification authority in mid-size water authority RFPs.
Industry Challenges
- Welding Certification Bottlenecks:ASME Section IX qualified welder availability constrains nuclear-grade valve repair capacity, extending outage schedules for aging reactor fleets.
- Legacy SCADA Integration:Fieldbus protocol fragmentation between Foundation Fieldbus and HART-IP complicates retrofit of intelligent valve positioners in brownfield process plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Valves Market |
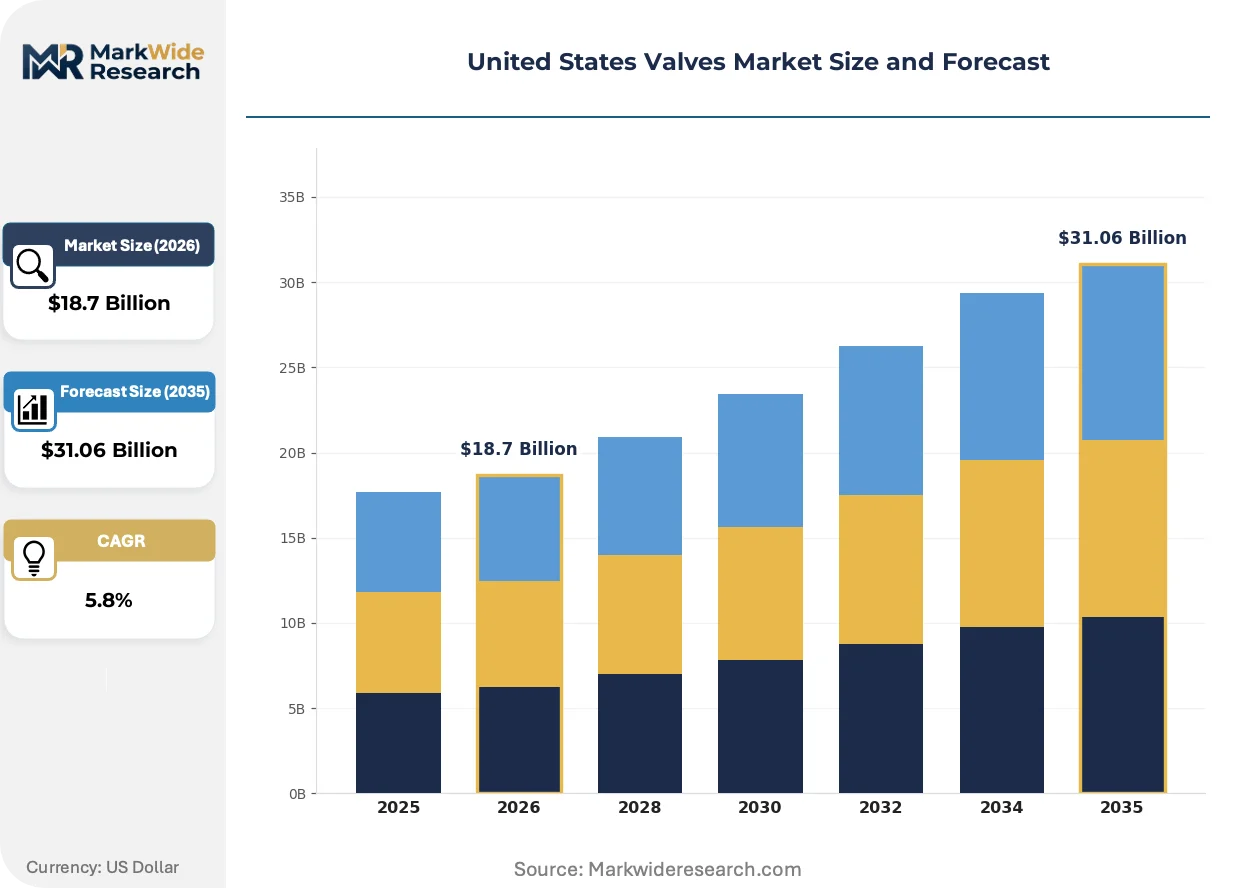
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valve, Gate Valve, Check Valve, Butterfly Valve Material: Metal, Plastic, Brass, Stainless Steel Application: Water Supply, Oil & Gas, Chemical Processing, HVAC End User: Manufacturing, Utilities, Construction, Marine |
| Companies Covered | Crane Company, Velan Inc., Emerson Electric Co., KITZ Corporation, Bray International, Inc., Flowserve Corporation, Parker-Hannifin Corporation, Curtiss-Wright Corporation, Schlumberger Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Valves Market Evolving Landscape
Additive manufacturing of valve body geometries is collapsing lead times for low-volume specialty alloys while enabling topology-optimized flow paths previously impossible through sand casting methods.
Digital twin architectures for predictive valve maintenance are decentralizing asset ownership economics. Mid-size refineries in the Ohio River Valley are piloting subscription-based diagnostics that shift capital expenditure to operational budgets. Equipment OEMs capture recurring revenue streams while plant operators reduce unplanned shutdown frequency.
EPA enforcement of Clean Water Act industrial discharge permits is tightening fugitive emissions standards for chemical processing facilities. Facilities in the Houston Ship Channel corridor are retrofitting bellows-sealed globe valves to eliminate packing leaks. Stainless steel construction with live-loaded packing systems is displacing graphite-based alternatives in high-cycle steam service.
Specification authority is migrating from engineering contractors to owner-operator procurement teams. Integrated EPC firms in the Permian Basin are losing valve selection autonomy as majors enforce corporate material standards. Direct sourcing relationships between end users and certified manufacturers are compressing distributor margins and reshaping channel economics across upstream oil and gas applications.
United States Valves Market Segmentation
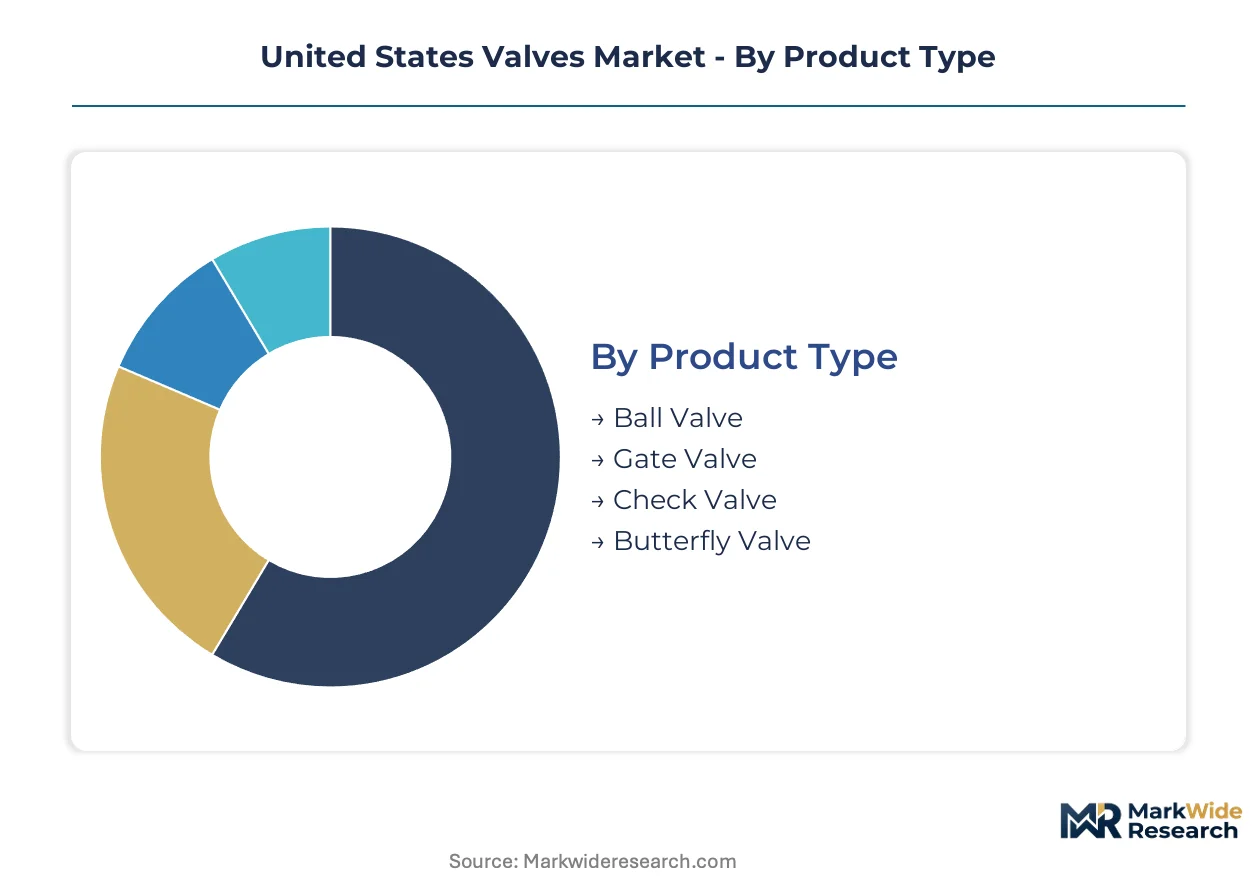
Valve procurement patterns diverge sharply across product architectures, material grades, and end-use environments. Specification authority migrates toward owner-operators who prioritize lifecycle cost over first-cost in capital-intensive process applications.
Product Type:
Capital intensity peaks in precision-machined metal-seated designs requiring multi-axis CNC finishing and pressure-boundary weld overlays. Foundry and machining investments lock in competitive moats for established OEMs.
- Ball Valve:Spherical closure elements rotate 90 degrees to achieve tight shutoff with minimal pressure drop. Hydrocarbon processing clusters along the Texas Gulf Coast specify trunnion-mounted variants for high-cycle hydrogen sulfide service under ANSI Class 600 ratings.
- Gate Valve:Wedge-shaped discs move perpendicular to flow direction, providing full-bore passage with negligible flow restriction. Upstream oil and gas isolation duties in the Permian Basin and Bakken formation favor these for pigging operations and emergency block valve compliance.
- Check Valve:Self-actuating designs prevent backflow without external power or control signals. Water treatment facilities deploy silent check variants to mitigate water hammer in high-head pumping stations.
- Butterfly Valve:Quarter-turn disc rotation enables compact face-to-face dimensions and reduced weight. HVAC retrofit projects in federal buildings under Department of Energy mandates specify low-leakage high-performance configurations.
Most installed capacity flows through Gate Valve architectures. Expansion is steepest in Ball Valve segments driven by petrochemical capacity additions.
Material:
Raw material cost volatility and EPA compliance timelines reshape procurement specifications across municipal and industrial end uses. Alloy selection now carries regulatory liability beyond traditional corrosion and pressure ratings.
- Stainless Steel:Austenitic and duplex grades deliver chloride stress-corrosion resistance in coastal chemical plants and offshore platforms. The EPA's Lead and Copper Rule revisions are accelerating displacement of legacy brass in potable water distribution.
- Metal:Cast carbon steel and alloy steel bodies dominate high-pressure steam and process piping above 1000 psi. Refinery turnaround schedules in the Ohio River Valley and Louisiana chemical corridor sustain demand for weld-end and flanged configurations.
- Brass:Leaded and low-lead bronze alloys retain share in residential plumbing and light commercial HVAC where pressure-temperature ratings remain moderate. California and Texas plumbing codes are tightening allowable lead content thresholds.
- Plastic:PVC, CPVC, and PVDF constructions serve corrosive chemical handling and ultrapure water systems where metallic ion contamination is unacceptable. Semiconductor fabrication facilities in Arizona and Oregon specify fluoropolymer-lined variants.
Stainless Steel commands premium positioning in specification-sensitive applications. Plastic is climbing fastest in corrosive service niches where total installed cost drives selection.
Application:
End-use environments dictate seal technology, actuation method, and inspection protocols. Process severity and regulatory exposure determine whether commoditized or engineered-to-order supply channels capture the buy.
- Oil & Gas:Exploration, production, gathering, and refining operations require fire-safe certification and fugitive emissions compliance. API 6D and API 600 specifications govern pipeline block and control valve selection across the Gulf Coast and Midcontinent.
- Chemical Processing:Aggressive media and thermal cycling demand metallurgical expertise in alloy selection and weld procedure qualification. OSHA Process Safety Management standards mandate material traceability and pressure-boundary integrity documentation.
- Water Supply:Municipal distribution, treatment, and wastewater infrastructure prioritize corrosion resistance and operational longevity. AWWA standards and state-level lead-free mandates are rewiring procurement specifications for buried service valves.
- HVAC:Commercial building climate control emphasizes energy efficiency, low-leakage dampers, and modulating control valve accuracy. Federal building efficiency mandates redirect specification toward smart actuator integration.
Oil & Gas represents the largest installed base by valve count. Chemical Processing is expanding most quickly on capacity additions and replacement of aging units.
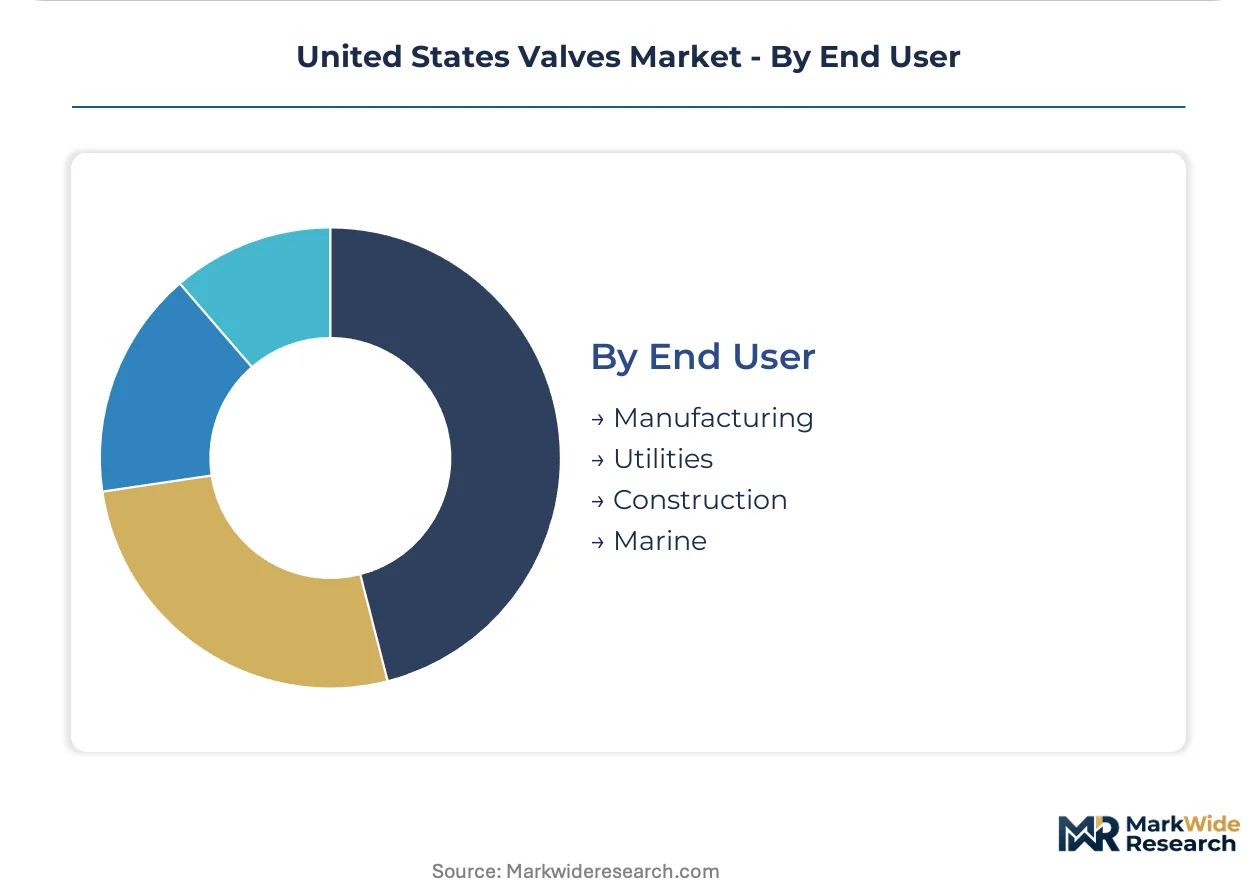
End User:
Buying center structure and procurement sophistication vary dramatically across customer categories. Direct-to-utility digital platforms are disintermediating traditional distribution in mid-size water authority segments.
- Utilities:Water, wastewater, and electric power entities operate under rate-base regulation with extended asset depreciation schedules. AMI integration and predictive maintenance subscriptions are restructuring how valve OEMs capture lifetime value.
- Manufacturing:Process industries including food and beverage, pulp and paper, and primary metals require hygienic or severe-service configurations. Plant reliability teams are migrating specification authority from EPC contractors to owner engineering.
- Construction:Commercial and institutional building projects face compressed timelines and value-engineering pressure. Mechanical contractors balance first-cost constraints against callback risk and warranty exposure.
- Marine:Shipbuilding and offshore platform construction demand classification society certification and salt-spray corrosion resistance. Jones Act requirements sustain domestic foundry and machining capacity for naval and commercial vessel programs.
Utilities account for the majority of recurring replacement demand. Manufacturing is gaining share fastest as reshoring initiatives expand process plant construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between states are redirecting valve procurement toward jurisdictions with faster permitting timelines and consolidated utility purchasing authority. Federal infrastructure funding flows unevenly across regions, creating localized demand surges that outpace national averages.
Texas Gulf Coast
Petrochemical capacity additions along the Houston Ship Channel and Beaumont-Port Arthur corridor sustain demand for high-pressure ball valves rated for sour gas service. EPA Region 6 enforcement of Clean Air Act emissions standards accelerates retrofit cycles for bellows-sealed configurations. The Mont Belvieu NGL hub anchors procurement volume for cryogenic and high-temperature isolation valves.
California
State-level PFAS remediation mandates and Proposition 65 litigation exposure reshape municipal water infrastructure specifications toward stainless steel and fluoropolymer-lined designs. The California Energy Commission's building efficiency standards redirect HVAC specification toward smart actuator integration. Silicon Valley semiconductor fabrication clusters drive demand for ultrapure water system valves with metallic ion contamination controls.
Ohio River Valley
Refinery turnaround schedules and Appalachian shale gas processing sustain demand for weld-end gate valves and pressure-relief configurations. OSHA Process Safety Management audits in Kentucky and West Virginia chemical facilities tighten material traceability requirements. The Parkersburg-Marietta manufacturing corridor hosts specialized valve repair and recertification capacity serving downstream petrochemical operations.
Louisiana Chemical Corridor
Blue hydrogen and ammonia export terminal proposals between Baton Rouge and New Orleans generate specification activity for hydrogen-compatible metal-seated ball valves. Louisiana Department of Environmental Quality discharge permit renewals mandate fugitive emissions monitoring integration. The Lake Charles industrial complex anchors demand for fire-safe certified configurations in high-cycle catalytic reforming service.
Pacific Northwest
Hydropower modernization and salmon habitat restoration funding redirect Army Corps of Engineers procurement toward fish-friendly turbine bypass valves. Washington State's clean building performance standards accelerate HVAC control valve replacement in Seattle and Bellevue commercial stock. The Portland-Vancouver metro sustains demand for waterworks butterfly valves in combined sewer overflow mitigation projects.
United States Valves Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification authority migrating toward owner-operators in process industries while distributors retain influence in municipal waterworks. The vendor base concentrates around three tiers: integrated multinationals with full lifecycle service portfolios, mid-cap specialists with vertical control over casting and machining, and regional fabricators competing on delivery speed. Dominant competitive moves include capacity expansion into nickel alloy foundry operations and strategic partnerships to secure ASME nuclear certification.
Among diversified industrial conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify the integrated service model, while Crane Company occupies a position within the nuclear-grade specialization tier. Velan Inc. and KITZ Corporation represent mid-cap specialists with concentrated exposure to severe-service applications.
| Leading Market Players |
|---|
| Crane Company |
| Velan Inc. |
| Emerson Electric Co. |
| KITZ Corporation |
| Bray International, Inc. |
| Flowserve Corporation |
| Parker-Hannifin Corporation |
| Curtiss-Wright Corporation |
| Schlumberger Limited |
| Others |
Value Network & Pricing Analysis
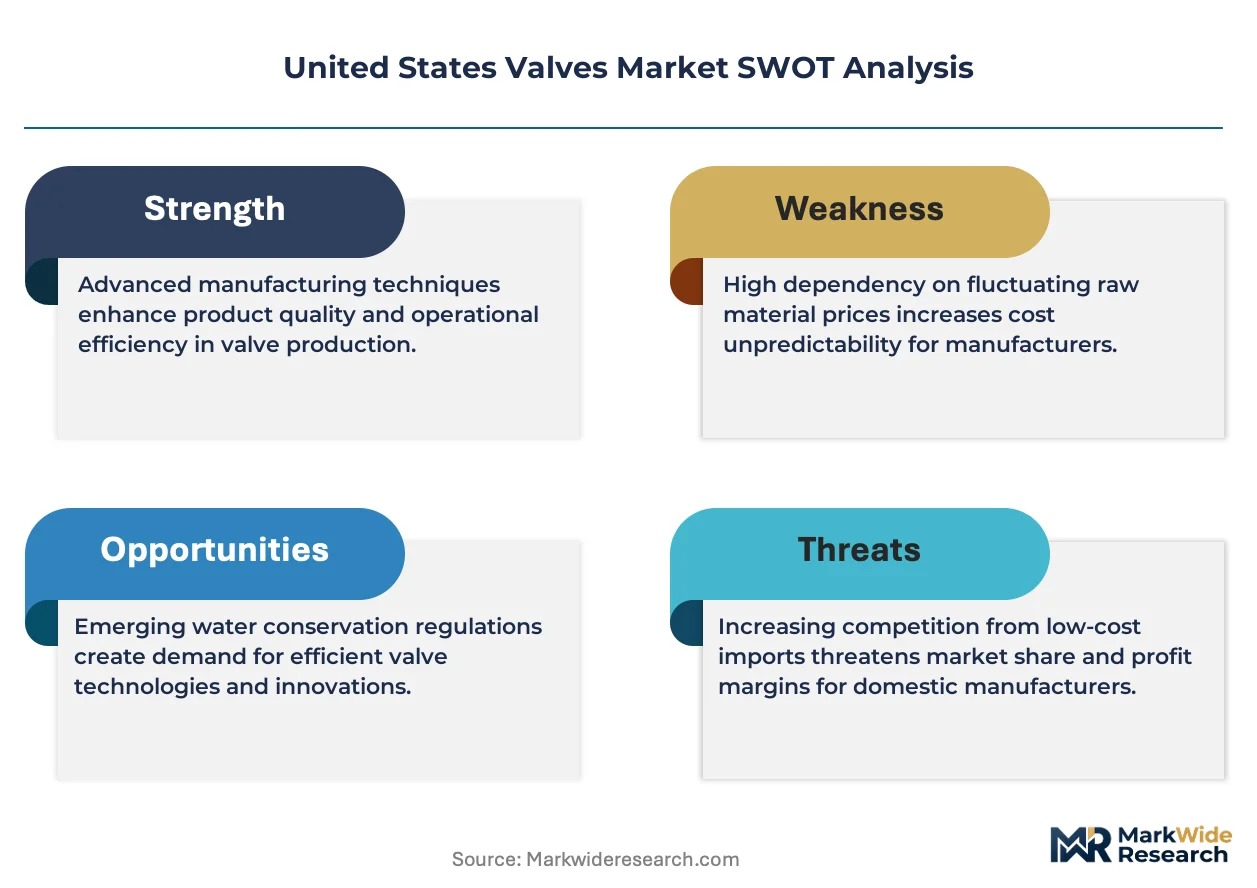
Backward integration into captive nickel alloy foundry operations anchors pricing power for domestic valve OEMs while insulating margin structures from Indonesian and Russian raw material volatility. This supply configuration enables premium positioning in EPA-mandated stainless steel transitions where qualification timelines compress procurement competition.
Pricing Analysis
Distributor margin layers in municipal waterworks channels face compression as direct-to-utility e-procurement platforms disintermediate traditional stocking relationships. Three-tier pricing structure across nuclear-grade certified, industrial-standard, and commercial-economy levels reflects ASME Section IX welding certification investment and material traceability documentation depth. Cost compression in brass-to-stainless transitions intensifies because foundry capacity constraints extend lead times for low-lead bronze alternatives. Water authority procurement teams exhibit highest price sensitivity in below-ground distribution valves where lifecycle cost modeling remains immature.
Supply Chain Analysis
ASME-qualified welder availability constraints in Ohio and Pennsylvania foundry clusters tether production schedules to regional technical workforce development pipelines. Gray iron and ductile iron casting capacity draws from domestic Ohio River Valley operations while nickel and molybdenum alloying elements hinge on Indonesian mine output and Russian processed metal flows. Single-source vulnerability concentrates in nuclear-grade valve repair capacity where Section IX certification bottlenecks extend outage schedules. Distribution runs through integrated EPC contractors in Gulf Coast petrochemical corridors and specialized waterworks distributors in municipal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Valves Market represents a late-cycle quality story as EPA Lead and Copper Rule revisions force specification upgrades toward corrosion-resistant stainless architectures that command sustained premium positioning.
For Market Incumbents: Acquire nickel alloy foundry capacity in the Ohio River Valley to secure captive supply of duplex stainless grades required for hydrogen sulfide service in Gulf Coast petrochemical expansions. Defensive consolidation should prioritize ASME nuclear certification assets to capture aging reactor fleet maintenance contracts while emerging Chinese valve exporters threaten commoditized industrial segments through state-subsidized pricing.
For New Entrants and Emerging Players: Digital procurement platform partnerships offer channel access to mid-size water authorities disintermediating traditional distributor relationships. White-space targets concentrate in PFAS remediation control valve packages where Congressional infrastructure funding flows exceed established supplier qualification capacity. Targeted specification authority capture in hydrogen blending network pilot projects enables technology validation for power-to-gas storage scaling.
For Investors and Strategic Acquirers: Roll-up economics work for regional valve repair and recertification specialists because nuclear-grade welding certification scarcity creates durable local moats around aging infrastructure maintenance demand. Long-term viability centers on service revenue attachment to installed bases through predictive diagnostics subscriptions. Monitor EPA enforcement intensity in Region 6 as inflection indicator for bellows-sealed retrofit cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Nickel Alloy Foundry Acquisition | Captive supply of duplex grades secures margin control against Indonesian nickel volatility. |
| ASME Nuclear Certification Investment | Section IX qualification unlocks aging reactor maintenance contracts with decade-long visibility. |
| Direct-to-Utility E-Procurement Platform | Digital disintermediation captures specification authority in mid-size water authority RFPs. |
| Predictive Diagnostics Subscription Launch | Plantweb-style recurring revenue shifts OEM economics from transactional to lifetime value capture. |
| PFAS Remediation Valve Package Development | Congressional infrastructure funding creates procurement channel for corrosion-resistant control configurations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with plant engineers, maintenance directors at Gulf Coast refineries, water authority procurement managers, and aftermarket service heads with secondary validation against SEC 10-K filings, AWWA standards documentation, and EPA enforcement databases. Bottom-up unit demand modeling triangulated against top-down industry value estimates derived from trade association capacity reports.
Segment-weighting approaches distributed value across material grade tiers, product architecture categories, and end-use intensity levels throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating petrochemical capacity expansion schedules, municipal infrastructure depreciation cycles, and regulatory compliance timeline acceleration. Hydrogen blending network pilot trajectories and PFAS remediation funding disbursement rates served as industry-specific scenario inputs.
Revisions become necessary when EPA enforcement intensity shifts, nickel alloy supply disruptions materialize, or nuclear plant retirement schedules accelerate beyond baseline assumptions. Forecasts reflect documented assumptions about regulatory timeline adherence and foundry capacity expansion completion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Industrial Safety Valves Market
Valves
Global Level Gauge Market
Valves
Choke Valves Market
Valves
Pipeline Pigging Valves Market
Valves
North America High Voltage Switchgear Market
Valves
Mobile Hydraulic Valves Market
Valves
Industrial Valves and Actuators Market
Valves
Rupture Discs Market
Valves
Fin Tube Market
Valves
Global Pipeline Safety Market
Valves
Chemical Injection Skid Market
Valves
Valve Manifold Box (VMB) Market
Valves
Manual Control Valve Market
Valves
Vaneometer Market
Valves
GCC and MENA Valves Market
Valves
Valve Sack Market