
 Middle East and Africa Industrial Valves Market | 2026-2036
Middle East and Africa Industrial Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Industrial Valves Market Foresight
Aftermarket service revenue is reshaping margin pools across the Middle East and Africa Industrial Valves Market, pulling value away from first-sale hardware toward lifecycle contracts. Emerson Electric Co. leverages its digital valve monitoring platforms to capture recurring diagnostics income from Gulf petrochemical complexes. Flowserve Corporation anchors its regional position through localized repair centers in Saudi Arabia and the UAE. AVK Saudi Valves Manufacturing Co. Ltd. dominates municipal water infrastructure with cast-iron distribution valves engineered for desert operating conditions.
Industrial valves are mechanical flow-control devices manufactured from cast or forged metal bodies with internal obturators, seats, and actuation linkages designed to start, stop, throttle, or regulate fluid passage through pressurized piping systems. Ball valves machined with floating or trunnion-mounted spheres deliver tight shutoff in hydrocarbon transmission lines where bubble-tight sealing prevents fugitive emissions. Oil and Gas end users command the largest share of regional valve procurement, while Water Treatment applications are expanding fastest as Egypt and Morocco advance large-scale desalination and wastewater reuse programs. Stainless Steel material grades resist chloride-induced pitting in Middle Eastern offshore platforms, whereas Carbon Steel dominates onshore pipeline gathering systems where cost sensitivity shapes procurement.
Saudi Arabia's national regulator enforces emissions controls that compel valve manufacturers to certify low-leakage packing designs for refinery and upstream installations. South Africa's pressure equipment safety authority mandates third-party inspection of valves rated for high-pressure steam service in power generation. The UAE's civil defense and industrial safety codes require fire-safe valve testing for hydrocarbon facilities, creating compliance barriers for uncertified suppliers. Stakeholders must monitor how national content requirements and local assembly mandates across Gulf states alter sourcing economics and vendor qualification pathways.
Market Dynamics
Saudi Arabia's tightening emissions standards under its national regulator are compressing replacement cycles across upstream and downstream valve installations, pulling capital toward certified low-leakage sealing systems and away from legacy procurement patterns.
Growth Catalysts
- Refinery expansion programs:The United Arab Emirates is commissioning new processing capacity that requires high-specification alloy valves for corrosive hydrocarbon service, creating sustained order flow for super-duplex and Inconel grades.
- SFDA emissions mandates:Saudi Arabia's national regulator is compelling operators to replace conventional packing with certified low-emission designs, accelerating hardware refresh cycles across the Kingdom's installed base.
- Desalination buildouts:Egypt and Morocco are advancing large-scale seawater reverse osmosis plants that demand titanium and super-austenitic stainless valves for chloride-rich intake systems.
Market Restraints
- Alloy input volatility:Nickel and molybdenum price swings directly compress margins on super-duplex valve bodies, forcing manufacturers to absorb cost spikes or risk order deferrals.
- Specialized foundry concentration:Super-alloy casting capacity clusters in Western European and East Asian suppliers, exposing regional valve fabricators to extended lead times and currency risk.
- Legacy infrastructure lock-in:Decades-old flange standards and pipeline specifications in mature Gulf fields resist retrofit to compact valve designs, constraining upgrade penetration.
Strategic Opportunities
- Morocco wastewater reuse:The country's advancing treated effluent distribution networks require resilient ductile-iron valves for non-potable agricultural supply, opening municipal-tier volume.
- Digital valve monitoring convergence:Integration of edge computing with acoustic leak detection is enabling predictive maintenance contracts that capture recurring revenue from petrochemical operators.
- Local assembly incentives:Gulf state national content requirements are creating joint-venture pathways for foreign manufacturers to establish Saudi-based fabrication and testing facilities.
Industry Challenges
- Specialized welding certification scarcity:Qualified orbital welders for exotic alloy valve fabrication are concentrated in European training pipelines, constraining regional production scaling.
- Fire-safe testing backlog:UAE civil defense certification queues for hydrocarbon-service valves are extending project timelines, forcing operators to buffer inventory or defer commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Industrial Valves Market |
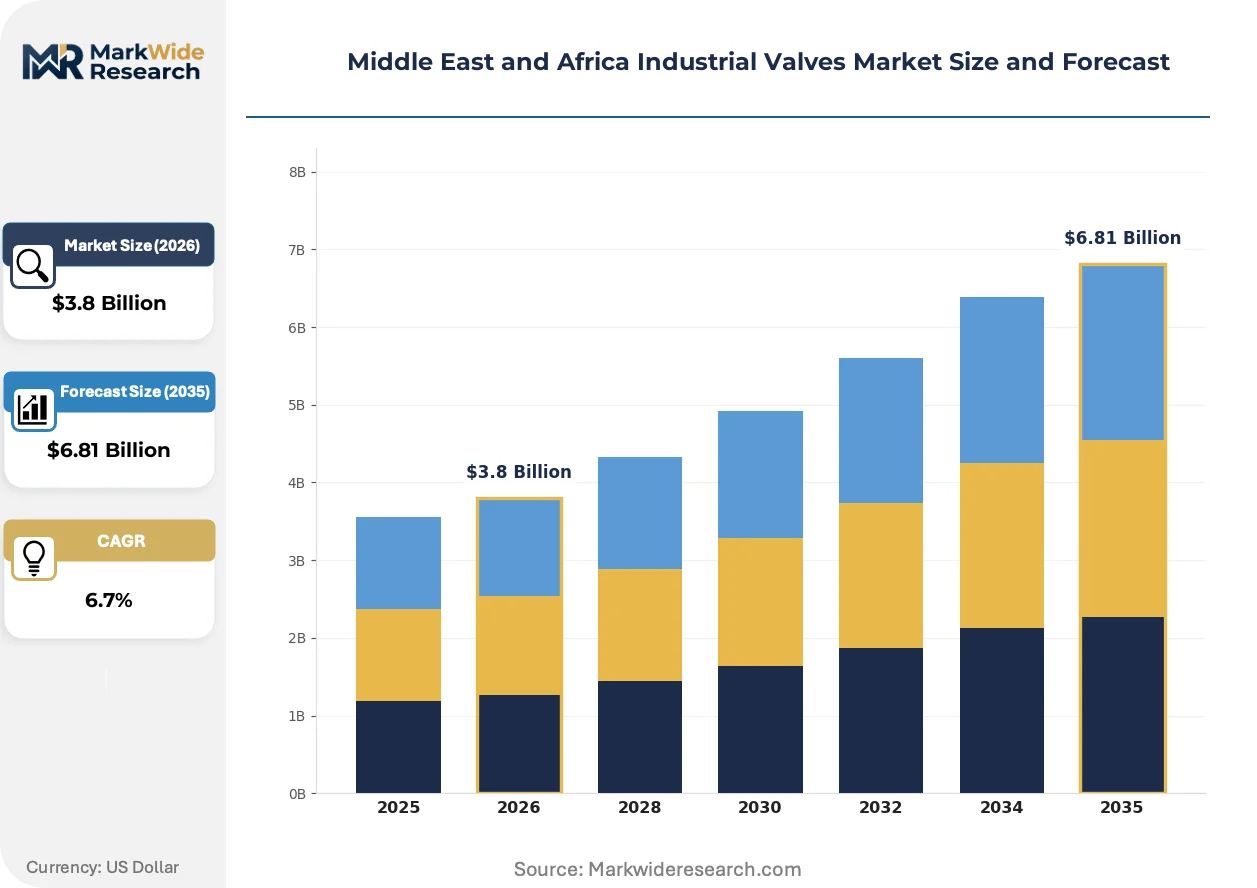
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valve, Globe Valve, Check Valve, Ball Valve End User: Oil & Gas, Water Treatment, Power Generation, Chemical Processing Material: Stainless Steel, Carbon Steel, Bronze, Plastic Size: 1 Inch, 2 Inch, 4 Inch, 6 Inch |
| Companies Covered | Johnson Controls International Plc, IMI Critical Engineering, Emerson Electric Co., Alfa Laval Corporate AB, KITZ Corporation, Flowserve Corporation, Larsen and Toubro Ltd., AVK Saudi Valves Manufacturing Co. Ltd., Schlumberger Limited, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Industrial Valves Market Shifts & Advancements
Digital instrumentation is embedding intelligence directly into valve actuation systems, compressing maintenance intervals and enabling remote diagnostic revenue models across Middle Eastern process industries.
Metal-seated ball valve designs with spray-coated tungsten carbide surfaces are rendering obsolete soft-seated configurations in high-temperature catalytic cracking service. Saudi Aramco and ADNOC affiliates are specifying these for coker and hydrocracker units where thermal cycling degrades elastomer inserts. The shift is compressing supplier margins on conventional carbon-steel ball valves while expanding addressable market for hard-facing specialists.
SFDA enforcement of fugitive emissions protocols is mandating third-party packing certification for all new refinery and upstream installations. The regulation is disqualifying uncertified Asian imports from Saudi procurement tenders and forcing established suppliers to maintain dedicated testing laboratories in-Kingdom. Valve fabricators without local certification partnerships are retreating to lower-specification water and general industrial segments.
Lifecycle service contracts are displacing transactional hardware sales as the dominant commercial model among Gulf petrochemical operators. Buyers are unbundling valve supply from commissioning support and predictive maintenance, awarding multi-year diagnostics agreements to vendors with localized repair infrastructure. The pattern is most pronounced in Jubail and Ruwais industrial cities, where integrated operators prioritize uptime guarantees over capital expenditure minimization.
Middle East and Africa Industrial Valves Market Segmentation
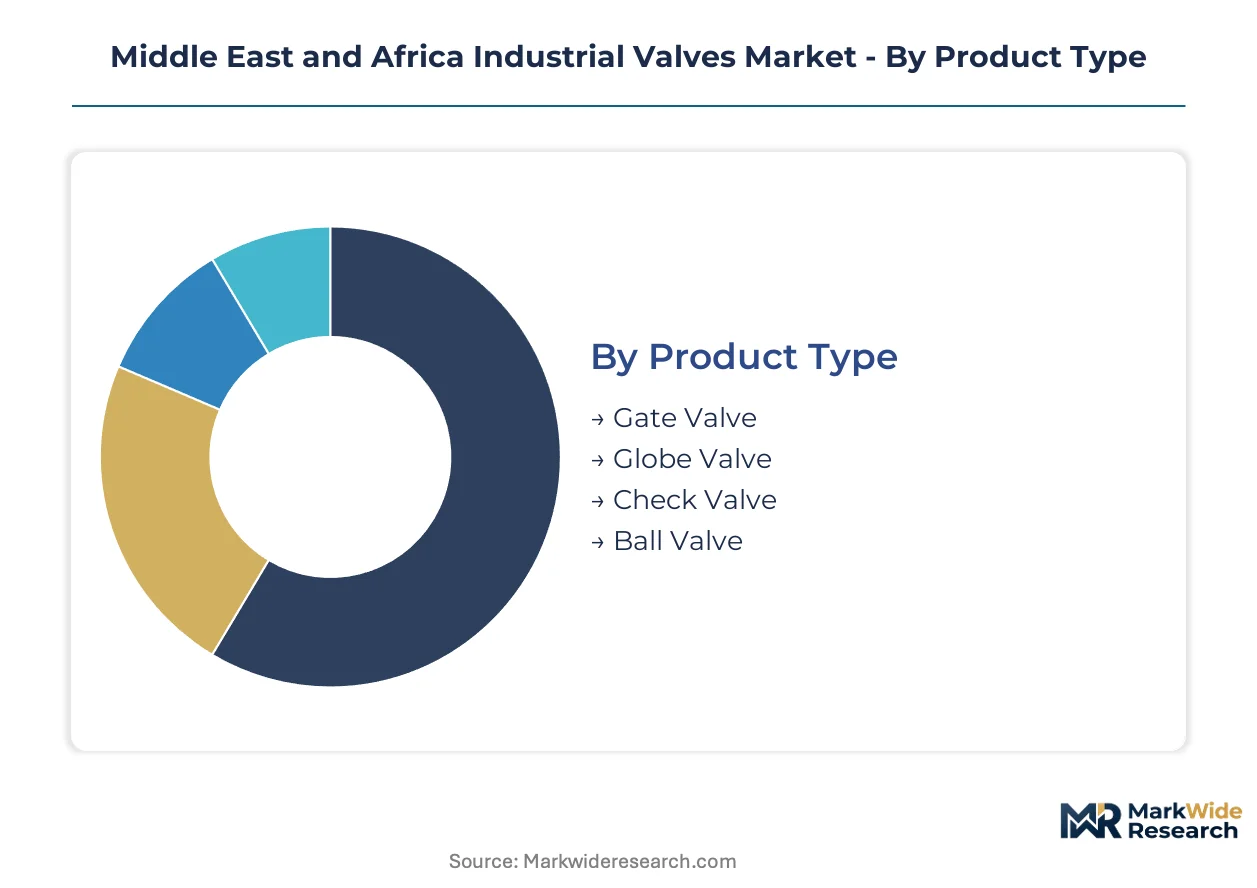
Segmentation reveals how valve specifications diverge across pressure classes, corrosion environments, and actuation requirements. Procurement patterns in the Middle East and Africa Industrial Valves Market cluster around hydrocarbon service demands, municipal infrastructure scale, and alloy performance tiers.
Product Type:
After-sales-service intensity varies sharply by valve mechanism complexity, with multi-turn designs demanding more frequent packing replacement than quarter-turn alternatives.
- Gate Valve:Rising and non-rising stem configurations isolate flow in straight-line piping with minimal pressure drop. Saudi Aramco specifies these for crude oil trunk lines where full-bore passage reduces pumping costs across extended desert transmission corridors.
- Ball Valve:Floating and trunnion-mounted spheres deliver bubble-tight shutoff critical for fugitive emissions compliance. ADNOC processing affiliates in Ruwais specify metal-seated variants for catalytic cracking units where thermal cycling degrades elastomer inserts.
- Globe Valve:Throttling precision suits these for flow modulation in steam and chemical service.
- Check Valve:Swing and lift configurations prevent backflow in pump discharge and compressor piping.
Ball valves hold the largest share; momentum sits with gate valves as pipeline replacement cycles accelerate.
End User:
Cost tier stratification separates specification-grade hydrocarbon procurement from municipal infrastructure volume plays.
- Oil & Gas:Upstream, midstream, and downstream installations command premium alloy specifications for sour service and high-pressure hydrogen environments. SFDA emissions mandates are compressing replacement cycles across the Kingdom's installed base, pulling capital toward certified low-leakage sealing systems.
- Water Treatment:Desalination and wastewater reuse programs in Egypt and Morocco drive demand for titanium and super-austenitic grades resisting chloride-induced pitting. Egypt's large-scale seawater reverse osmosis buildouts are expanding fastest among regional end-use verticals.
- Power Generation:High-pressure steam service requires certified pressure equipment meeting South Africa's safety authority inspection protocols.
- Chemical Processing:Petrochemical complexes in Jubail and Ruwais specify fire-safe designs for hydrocarbon containment.
Oil and Gas commands dominant procurement volume; Water Treatment is climbing the fastest as North African utilities scale desalination capacity.
Material:
Application severity dictates alloy selection, with chloride exposure and hydrogen sulfide presence eliminating lower-grade alternatives.
- Stainless Steel:Austenitic and duplex grades resist chloride-induced pitting in Middle Eastern offshore platforms and desalination intake systems. UAE refinery expansions specify super-duplex and Inconel variants for corrosive hydrocarbon service.
- Carbon Steel:Cost sensitivity dominates onshore pipeline gathering systems where standard grades meet pressure requirements without alloy premium. Procurement concentrates in mature Gulf field gathering networks where flange standards resist retrofit to exotic alternatives.
- Bronze:Marine and potable water applications favor these for corrosion resistance without stainless cost.
- Plastic:PVC and CPVC variants serve low-pressure chemical and water distribution where temperature limits permit.
Stainless Steel dominates high-specification procurement; Carbon Steel anchors volume throughput in cost-sensitive infrastructure.
Size:
Volume concentration clusters in mid-range diameters serving distribution and process header applications.
- 4 Inch:Process headers and distribution mains standardize on this diameter across refinery unit operations and municipal water networks. UAE desalination buildouts and Moroccan wastewater reuse programs specify this scale for trunk line efficiency.
- 6 Inch:Transmission pipelines and main process lines require larger bore for capacity. Saudi pipeline replacement programs and Egyptian desalination intake systems concentrate demand here.
- 1 Inch:Instrumentation and sampling lines employ these for isolation and drain service.
- 2 Inch:Branch connections and utility distribution favor this intermediate scale.
4 Inch diameter holds the largest installed base; 6 Inch specifications are gaining share fastest as transmission capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Egypt and Morocco prioritize cost-efficient carbon-steel valves for municipal water infrastructure, while Gulf petrochemical operators absorb premium alloy pricing for emissions-compliant hydrocarbon service. This demand-elasticity contrast shapes procurement patterns across the Middle East and Africa Industrial Valves Market.
Saudi Arabia
Upstream and downstream operators are accelerating replacement cycles for low-leakage sealing systems under SFDA emissions mandates. The national regulator now requires third-party packing certification for all new refinery installations. Jubail Industrial City hosts concentrated petrochemical complexes where integrated operators favor lifecycle service contracts over transactional hardware procurement.
United Arab Emirates
Refinery expansion programs at Ruwais and Jebel Ali are generating sustained order flow for super-duplex and Inconel valve grades in corrosive hydrocarbon service. MOHAP safety codes and civil defense regulations mandate fire-safe valve testing for all hydrocarbon facilities. Dubai and Abu Dhabi industrial zones are prioritizing vendors with localized repair infrastructure to minimize downtime.
Egypt
Large-scale seawater reverse osmosis buildouts are expanding fastest among regional end-use verticals, driving demand for titanium and super-austenitic stainless valves. The country's national water regulator is advancing treated effluent distribution networks for agricultural reuse. New Cairo and Alexandria industrial corridors are concentrating desalination intake system procurement.
South Africa
Power generation utilities require certified pressure equipment for high-pressure steam service under the national pressure equipment safety authority inspection protocols. The regulator mandates third-party verification for all valves rated above specified pressure thresholds. Gauteng and KwaZulu-Natal industrial basins are retrofitting aging coal-fired plants with compliant isolation valves.
Morocco
Advancing wastewater reuse programs are creating municipal-tier volume for resilient ductile-iron valves in non-potable agricultural supply networks. The country's national water agency is expanding treated effluent distribution infrastructure. Casablanca-Settat and Marrakech-Safi regions are deploying corrosion-resistant distribution valves engineered for desert operating conditions.
Middle East and Africa Industrial Valves Market Competitive Landscape
Capability concentration sits with specialized alloy fabricators possessing exotic-material welding certifications; scale advantage sits with diversified industrial conglomerates with broad foundry networks. The vendor base stratifies into three tiers: international majors with digital monitoring platforms, regional joint-ventures exploiting local assembly incentives, and municipal-tier specialists in cast-iron water infrastructure. Dominant competitive moves include establishing in-Kingdom testing laboratories to satisfy SFDA certification requirements and forming joint ventures to meet Gulf state national content mandates.
Among international majors with Middle Eastern presence, Emerson Electric Co. and Flowserve Corporation exemplify the integrated service-provider archetype, while AVK Saudi Valves Manufacturing Co. Ltd. occupies a specialized position within municipal water infrastructure. These three entities represent distinct strategic postures: digital platform deployment, localized repair infrastructure, and desert-engineered product specialization respectively.
| Leading Market Players |
|---|
| Johnson Controls International Plc |
| IMI Critical Engineering |
| Emerson Electric Co. |
| Alfa Laval Corporate AB |
| KITZ Corporation |
| Flowserve Corporation |
| Larsen and Toubro Ltd. |
| AVK Saudi Valves Manufacturing Co. Ltd. |
| Schlumberger Limited |
| Others |
Supply & Pricing Matrix
Jebel Ali Port freight corridors impose cost volatility that amplifies price spreads between premium alloy valves and standard carbon-steel alternatives. SFDA certification requirements and nickel-molybdenum input swings concentrate pricing power with specialized fabricators possessing in-Kingdom testing infrastructure, while municipal buyers in Egypt and Morocco face divergent landed cost structures.
Pricing Analysis
After-sales service contracts now generate lifetime value exceeding first-sale hardware margins across Gulf petrochemical installations. Pricing stratifies across certified low-emission packing tiers, uncertified standard grades, and municipal ductile-iron volume plays. Cost compression in carbon-steel gate valves is intensifying because Egyptian desalination contractors prioritize procurement minimization over alloy performance. Water treatment utilities exhibit highest price sensitivity; UAE refinery operators absorb premium super-duplex pricing without volume negotiation.
Supply Chain Analysis
Extended payment terms from European super-alloy foundries are constraining working capital for regional valve fabricators lacking supply-chain finance facilities. Super-duplex casting capacity draws from Italy, Germany, and Japan, while titanium billet supply rests on Russian and Chinese export channels. Single-source vulnerability concentrates in specialized welding consumables for exotic alloy fabrication. Distribution runs through Dubai-based stocking distributors serving North African project sites and direct mill relationships for Saudi Aramco frame agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from digital-native valve monitoring platforms that unbundle hardware from predictive maintenance revenue. Equipment suppliers must defend against software-led disintermediation.
For Market Incumbents: Pre-empt platform competitors by embedding edge-computing diagnostics into valve actuation systems before pure-play software vendors capture petrochemical maintenance budgets. SFDA certification barriers protect incumbent position but require sustained in-Kingdom laboratory investment. Backward integration into super-alloy welding consumables production reduces dependency on European orbital welder certification pipelines. For New Entrants and Emerging Players: Establish a beachhead in Moroccan wastewater reuse infrastructure where ductile-iron valve specifications favor new suppliers without legacy hydrocarbon certification burdens. Egypt's desalination buildouts present the most penetrable geography for titanium valve specialists lacking Aramco prequalification. Target agricultural effluent distribution networks with desert-engineered products priced below AVK Saudi Valves Manufacturing's municipal dominance. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming valve divisions lacking digital service platforms. Long-term viability hinges on recurring revenue capture from lifecycle contracts rather than transactional hardware cyclicality. Watch SFDA enforcement intensity as inflection indicator—accelerated certification mandates favor consolidated players with testing infrastructure over fragmented fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| In-Kingdom Testing Laboratory Establishment | SFDA certification requirements disqualify uncertified imports from Saudi Aramco tenders. |
| Digital Valve Monitoring Platform Deployment | Emerson Electric's predictive maintenance contracts capture recurring revenue from Jubail petrochemical complexes. |
| Super-Alloy Welding Certification Investment | Orbital welder scarcity constrains regional production scaling for exotic material valves. |
| Municipal Water Infrastructure Specialization | AVK Saudi Valves dominates desert-engineered cast-iron distribution for Egyptian and Moroccan utilities. |
| Joint Venture Local Assembly Formation | Gulf state national content mandates create pathways for foreign manufacturers to establish Saudi fabrication facilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed valve manufacturers, SFDA regulatory bulletins, and desalination project procurement databases. Interviews with maintenance directors at Saudi Aramco affiliates, procurement leads at UAE refinery operators, Egyptian water utility engineers, and aftermarket service heads at Flowserve regional centers provided operational validation. Bottom-up project pipeline assessment triangulated against top-down alloy consumption estimates from nickel industry associations.
Forecast inputs incorporate valve replacement cycle compression under SFDA emissions mandates, desalination capacity buildout timelines across North Africa, and refinery expansion schedules at Ruwais and Jebel Ali. Segmentation modeling spans product mechanism, end-use vertical, material grade, pressure class, and actuation type. CAGRs derive from installed base depreciation curves overlaid with regulatory-driven upgrade acceleration and project-based new-build demand.
Stress conditions across nickel-molybdenum price volatility, SFDA enforcement intensity, and Egyptian currency convertibility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory continuity and project financing availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Compressor Valves Market
Valves
Global Valve Positioners Market
Valves
Instrumentation Valves and Fittings Market
Valves
Europe Butterfly Valve Market
Valves
Global Globe Valve Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Fluid Handling Systems Market
Valves
Global Fluid Management Systems Market
Valves
Servo Valves Market
Valves
Global Automotive Valves Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Hydraulic Diaphragm Valve Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Rising Stem Ball Valve Market
Valves
Valve Driver Market
Valves
Hybrid Valve Market