
 Kuwait & Iraq Oilfield Chemicals Market | 2026-2036
Kuwait & Iraq Oilfield Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait & Iraq Oilfield Chemicals Market Insights
Digital chemical monitoring and automated dosing is narrowing the performance gap between conventional and smart-enabled oilfield chemical systems. Baker Hughes Company leverages its integrated digital chemistry platform to sustain competitive positioning across Kuwait's maturing fields. Halliburton anchors its regional presence through specialized well stimulation chemical packages tailored to carbonate reservoirs. Solvay SA differentiates via advanced surfactant chemistry for high-salinity formation waters.
Oilfield chemicals comprise specialty formulations including corrosion inhibitors, demulsifiers, and scale inhibitors designed to operate at bottom-hole temperatures exceeding 150°C and pressures above 10,000 psi, primarily functioning to maintain well integrity, optimize hydrocarbon flow, and protect production infrastructure from degradation. Demulsifiers and corrosion inhibitors occupy the largest volume positions given the water-cut challenges and sour gas presence across Kuwait and Iraqi reservoirs. Enhanced oil recovery chemicals represent the fastest-expanding application segment as operators deploy polymer flooding and surfactant-polymer combinations to access remaining mobile oil in mature giants like Burgan and West Qurna.
Kuwait's Environmental Public Authority and Iraq's Ministry of Oil enforce increasingly stringent discharge standards for produced water, compelling reformulation of biocide and oxygen scavenger chemistries toward lower-toxicity alternatives. The analysis notes alignment pressures with REACH-equivalent substance registration protocols affecting import supply chains into both markets. Stakeholders must weigh the capital requirements of localized blending facilities against the flexibility of regional supply hubs serving the northern Gulf basin.
Market Dynamics
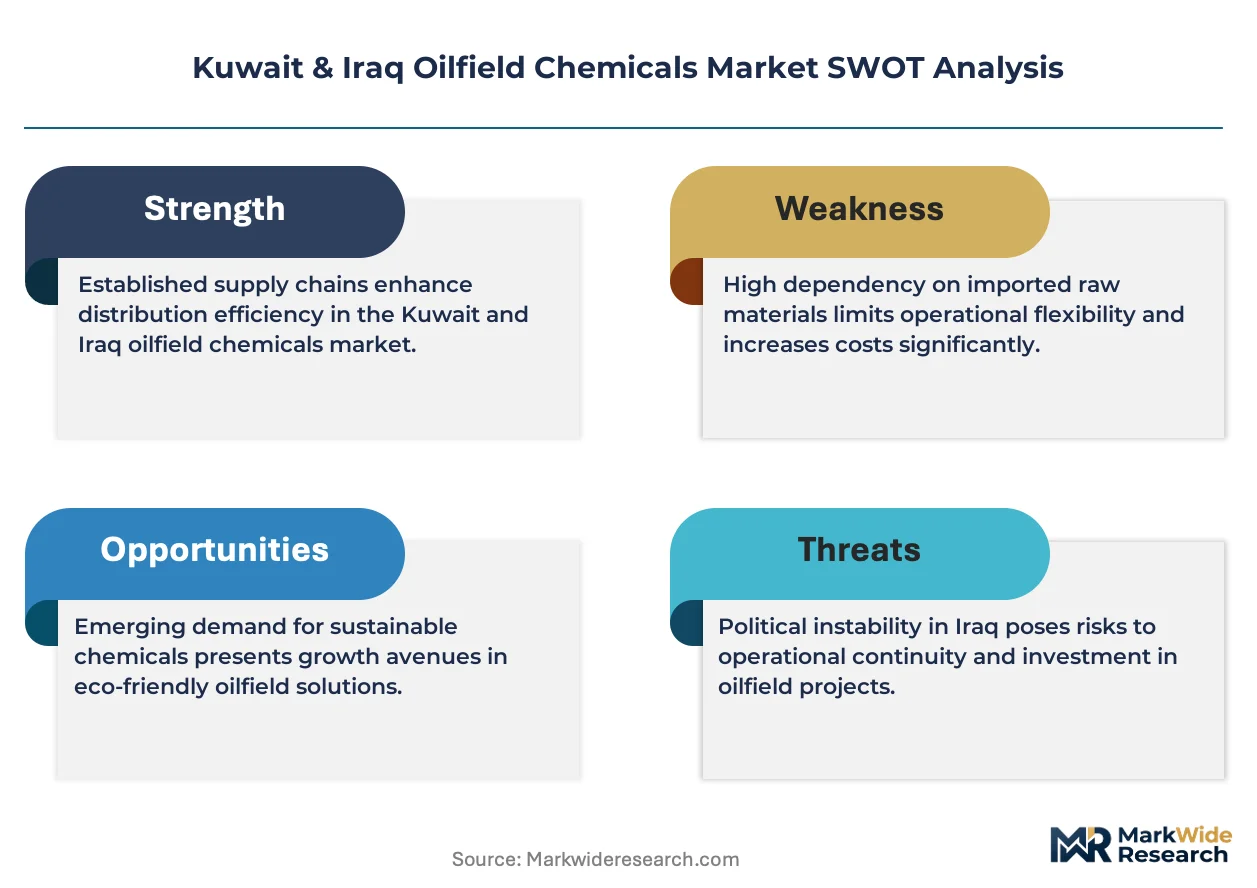
The Kuwait & Iraq Oilfield Chemicals Market is being fundamentally restructured by Iraq's Ministry of Oil mandates that increasingly require localized formulation standards for water treatment and reservoir management chemicals, forcing supply chain reconfiguration across the northern Gulf basin.
Growth Catalysts
- Polymer flooding deployment:Enhanced oil recovery operations in Burgan and West Qurna fields are expanding consumption of specialty chemicals designed for high-temperature carbonate reservoirs. This application segment commands accelerating volume commitments from field operators.
- Kuwait's Environmental Public Authority discharge standards:Stringent produced water regulations are compelling reformulation of biocide and oxygen scavenger chemistries toward lower-toxicity alternatives, creating replacement demand across existing well stock.
- Southern Iraq field clustering:Concentrated drilling activity in Basra province generates economies of scale for chemical logistics and blending infrastructure, reducing delivered costs for high-volume demulsifier and corrosion inhibitor categories.
Market Restraints
- REACH-equivalent registration protocols:Alignment pressures with substance registration frameworks are creating friction in import supply chains, extending qualification timelines for European and Asian chemical suppliers entering both markets.
- Specialized surfactant input concentration:Advanced chemistries for high-salinity formation waters depend on concentrated specialty surfactant manufacturing capacity located outside the region, exposing buyers to currency and freight volatility.
- Bottom-hole temperature thresholds:Conventional corrosion inhibitor formulations face technical ceilings at sustained temperatures exceeding 150°C, limiting deployment in deeper reservoir sections of mature giant fields.
Strategic Opportunities
- Kuwait's southeastern oil cluster:Maturing fields with rising water-cut profiles present underpenetrated demand for smart-enabled chemical monitoring systems that optimize dosing precision and reduce over-treatment costs.
- Surfactant-polymer combination flooding:Emerging EOR application protocols in West Qurna are creating specification windows for advanced formulation providers capable of integrating polymer and surfactant chemistries in single-package delivery systems.
- Localized blending facility investment:Capital deployment into northern Gulf basin supply hubs offers regulatory compliance advantages and import substitution benefits under Iraq's Ministry of Oil domestic content directives.
Industry Challenges
- Reservoir-specific formulation expertise:Shortage of chemists and field engineers capable of customizing demulsifier and scale inhibitor packages for the unique brine chemistry of Kuwaiti and Iraqi carbonate formations constrains technical service capacity expansion.
- Digital-physical system integration:Deployment of automated dosing platforms requires retrofitting legacy wellhead infrastructure, creating project complexity and extended commissioning timelines for integrated chemical monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait & Iraq Oilfield Chemicals Market |
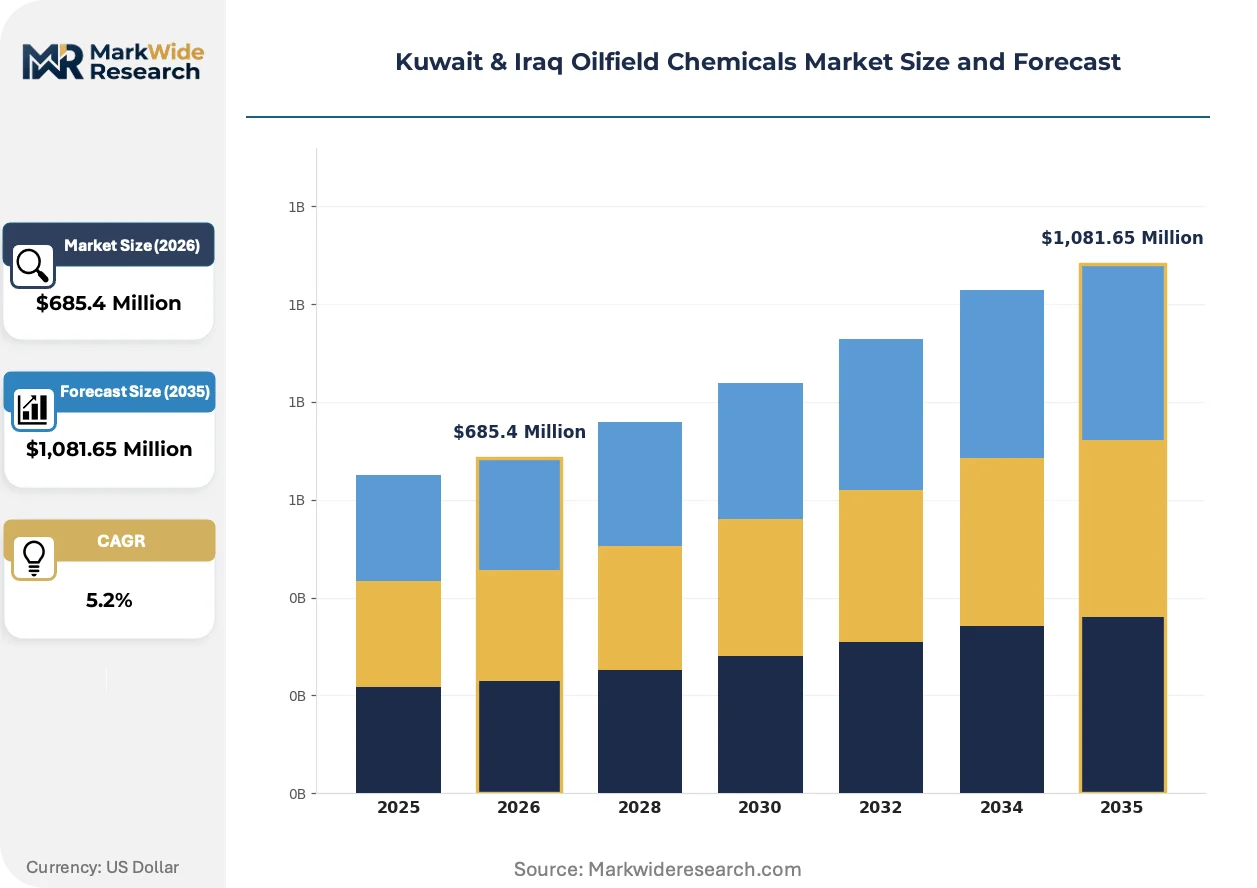
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion Inhibitors, Demulsifiers, Scale Inhibitors, Biocides, Surfactants, Oxygen Scavengers Application: Drilling Fluids, Enhanced Oil Recovery, Well Stimulation, Completion Fluids, Cementing, Hydraulic Fracturing End User: National Oil Companies, Service Contractors, Independent Operators, Oilfield Equipment Suppliers Deployment: Onshore Fields, Offshore Platforms, Subsea Installations, Floating Production Systems |
| Companies Covered | BASF SE, Chevron Corporation, Baker Hughes Company, Al Sanea Chemical Products, Petroleum Equipment Technology Company, Halliburton, Solvay SA, Catalyst LLC, Schlumberger Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait & Iraq Oilfield Chemicals Market Trends and Innovations
Digital chemistry platforms are compressing the performance differentiation between conventional and smart-enabled oilfield chemical systems, while regulatory tightening on produced water discharge and evolving procurement models reshape competitive requirements across Kuwait and Iraq.
Automated chemical dosing and real-time reservoir monitoring systems are virtualizing the traditional service model for corrosion inhibitor and demulsifier deployment. Kuwait Oil Company and Basra Oil Company are accelerating adoption of integrated digital chemistry platforms that combine downhole sensors with cloud-based optimization algorithms. This convergence is virtualizing inventory management and field service scheduling, compressing margins for providers dependent on manual intervention and periodic wellsite visits.
Iraq's Ministry of Oil is enforcing progressively stricter formulation disclosure and environmental impact documentation requirements modeled on REACH substance registration frameworks. These mandates are disqualifying smaller import-dependent suppliers lacking technical dossier preparation capabilities. Water treatment chemical categories face the most immediate compliance pressure, with biocide and oxygen scavenger segments experiencing accelerated supplier consolidation as registration costs rise.
Buyer organizations are consolidating chemical procurement under integrated supply agreements that bundle formulation supply with technical service and performance guarantees. This contractual evolution is displacing spot purchasing and transactional distributor relationships that historically dominated the Basra procurement landscape. The shift is most visible among international oil company joint ventures operating West Qurna and Rumaila fields, where total-cost-of-ownership evaluation criteria now override unit-price selection.
Kuwait & Iraq Oilfield Chemicals Market Segmentation
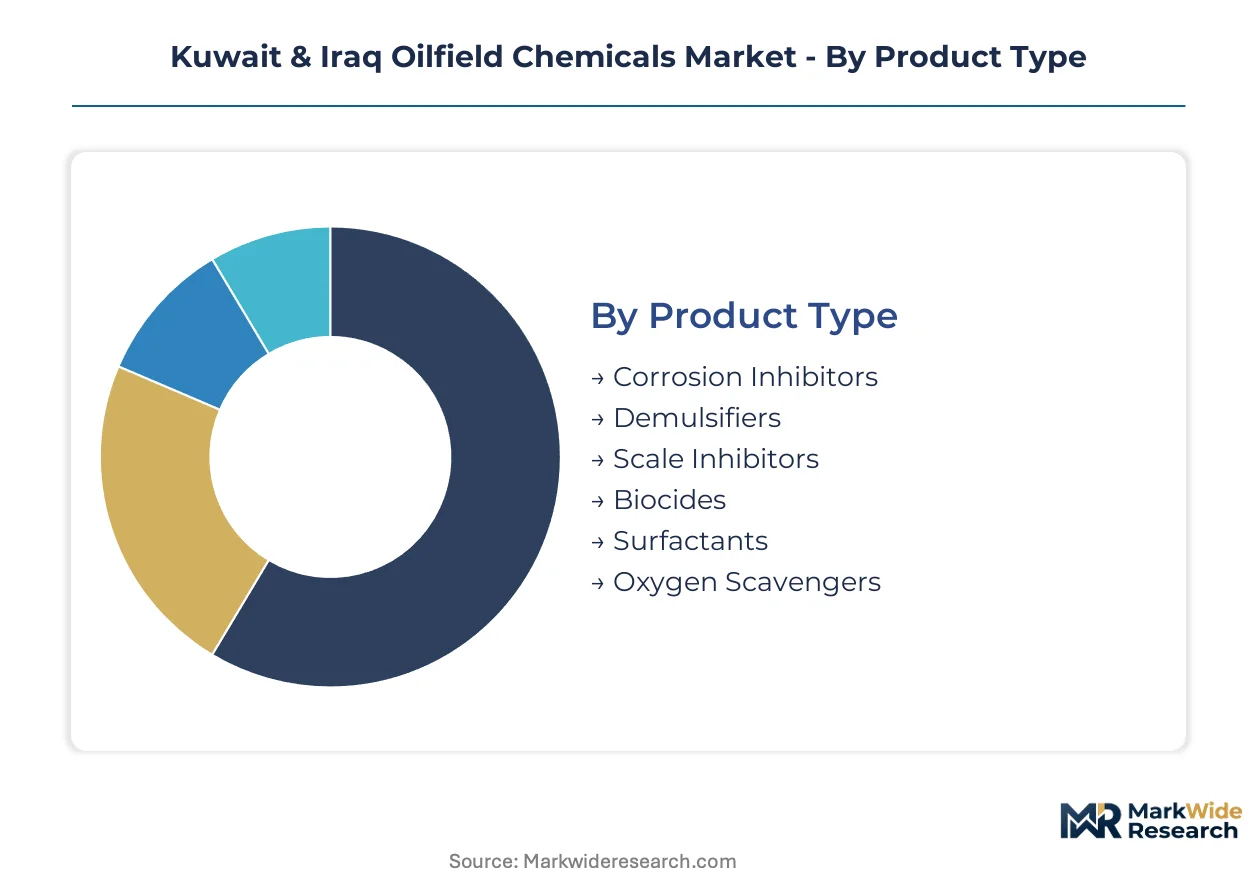
Segmentation in the Kuwait & Iraq Oilfield Chemicals Market reveals distinct performance profiles across formulation chemistry, reservoir application, and procurement channels. Each dimension carries specific technical and commercial implications for suppliers navigating the northern Gulf basin's regulatory and operational complexity.
Product Type:
Formulation chemistry spans the full operational spectrum from well integrity protection to fluid separation and reservoir enhancement.
- Corrosion Inhibitors:Film-forming amine and imidazoline-based chemistries protect carbon steel infrastructure from hydrogen sulfide and carbon dioxide attack at bottom-hole conditions exceeding 150°C. Demand concentrates in Burgan and Rumaila fields where sour gas presence accelerates metal degradation, with Kuwait Oil Company mandating continuous injection systems for all high-water-cut producers.
- Demulsifiers:Polymeric surfactant blends destabilize water-in-oil emulsions prevalent in mature carbonate reservoirs with rising water cuts. Basra Oil Company procurement for West Qurna and Rumaila fields drives volume, as heavy crude characteristics require specialized breaker chemistries tolerant of high-salinity formation brines.
- Scale Inhibitors:Phosphonate and polymer-based crystal growth modifiers address barium sulfate and calcium carbonate precipitation in downhole tubing.
- Biocides:Oxidizing and non-oxidizing formulations control sulfate-reducing bacteria in produced water handling systems.
- Surfactants:Anionic and non-ionic chemistries reduce interfacial tension for enhanced oil recovery flooding operations.
- Oxygen Scavengers:Sulfite and bisulfite derivatives remove dissolved oxygen from injection water to prevent corrosion in waterflood systems.
The dominant share belongs to Demulsifiers, while Surfactants are closing the gap fastest as polymer-surfactant flooding expands across southern Iraq's mature fields.
Application:
Operational deployment varies by reservoir maturity, with mature giant fields prioritizing enhanced recovery over primary drilling chemistry.
- Enhanced Oil Recovery:Polymer flooding and surfactant-polymer combinations target remaining mobile oil in Burgan, West Qurna, and Rumaila fields where primary depletion has passed peak production. Iraq's Ministry of Oil has accelerated EOR chemical procurement through integrated service contracts bundling formulation supply with reservoir engineering support.
- Well Stimulation:Acidizing and fracturing fluid chemistries restore or enhance permeability in carbonate formations characteristic of Kuwait and Iraqi reservoirs. Service contractors Halliburton and Schlumberger dominate technical specification for high-temperature acid systems in Kuwait's southeastern cluster.
- Drilling Fluids:Water-based and synthetic formulations maintain wellbore stability during exploration and development drilling.
- Completion Fluids:Clear brine systems minimize formation damage during well completion operations.
- Cementing:Additives control slurry rheology and set time for zonal isolation in high-pressure, high-temperature wells.
- Hydraulic Fracturing:Proppant transport and friction reducer chemistries enable unconventional reservoir development where applicable.
Enhanced Oil Recovery commands the largest committed volumes, though Well Stimulation shows steepest expansion trajectory as carbonate acidizing intensity increases.
End User:
Procurement concentration reflects Iraq's state-directed operator structure against Kuwait's more diversified contracting environment.
- National Oil Companies:Kuwait Oil Company and Basra Oil Company directly procure high-volume commodity chemistries through annual framework agreements, leveraging scale for price negotiation while maintaining technical specification control. Iraq's Ministry of Oil localization mandates increasingly require domestic blending for NOC-directed contracts.
- Service Contractors:International and regional oilfield service providers bundle chemical supply with technical service delivery under integrated performance contracts. Baker Hughes and Halliburton have captured preferred supplier status through digital chemistry platform deployment in Kuwait's maturing fields.
- Independent Operators:Smaller exploration and production companies purchase spot volumes through distributor networks.
- Oilfield Equipment Suppliers:Original equipment manufacturers specify compatible chemistries for corrosion protection and maintenance of pumps, valves, and processing equipment.
National Oil Companies retain volume leadership, while Service Contractors are gaining procurement influence fastest through integrated digital-physical service models.
Deployment:
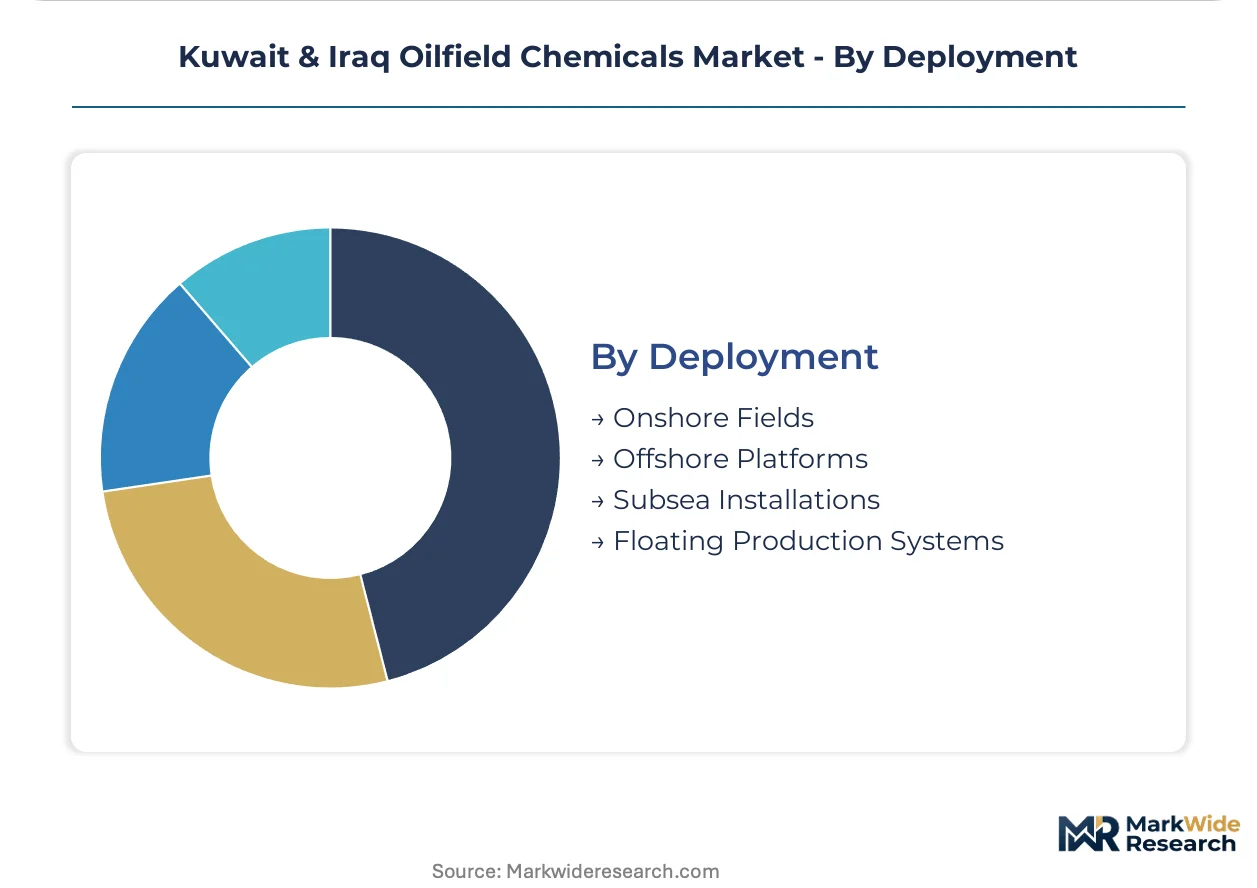
Field architecture determines logistics complexity and chemical delivery system requirements across the northern Gulf basin.
- Onshore Fields:Burgan, Rumaila, West Qurna, and Zubair fields generate concentrated demand accessible by road tanker and pipeline injection systems. Southern Iraq's Basra province clustering enables centralized blending facilities serving multiple adjacent fields with reduced transport costs.
- Offshore Platforms:Kuwait's southeastern offshore extensions and Iraq's limited shallow-water production require marine logistics and platform-based storage with automated dosing systems. Space constraints drive demand for concentrated chemical formulations and remote monitoring capabilities.
- Subsea Installations:Deepwater tiebacks and subsea processing equipment demand specialized umbilical-compatible chemistries.
- Floating Production Systems:FPSO vessels require compact chemical injection packages with high reliability for extended offshore campaigns.
Onshore Fields absorb the dominant chemical volumes, while Offshore Platforms are expanding fastest as Kuwait extends production into marginal offshore extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE supply refined chemical intermediates northward into Kuwait and Iraq's oilfield operations. This trade corridor channels specialty surfactants and polymer feedstocks through Gulf Cooperation Agreement logistics networks.
Southern Iraq
Basra province hosts the Rumaila, West Qurna, and Zubair fields that consume demulsifiers and corrosion inhibitors at scale. Iraq's Ministry of Oil mandates domestic blending for water treatment chemicals under localization directives. The Basra oil cluster generates concentrated demand accessible by road tanker, enabling centralized supply infrastructure serving adjacent fields.
Kuwait Southeastern Oil Cluster
Burgan field maturation drives polymer flooding deployment and smart-enabled chemical monitoring adoption. Kuwait's Environmental Public Authority enforces stringent produced water discharge standards compelling biocide reformulation. The Ahmadi and Magwa sub-regions concentrate wellhead automation investment as water-cut profiles rise.
Northern Gulf Supply Hubs
Jubail Industrial City in Saudi Arabia and Ruwais in the UAE anchor surfactant and polymer manufacturing capacity serving Kuwaiti and Iraqi buyers. Saudi Aramco's downstream integration controls intermediate supply pricing for regional chemical formulators. These hubs face currency and freight volatility exposure from European and Asian specialty surfactant input dependence.
Shuaiba Industrial Area
Kuwait's primary petrochemical corridor houses blending facilities for corrosion inhibitors and scale inhibitors serving offshore platform extensions. Kuwait Oil Company procurement frameworks favor suppliers with localized formulation capabilities. The zone connects to southeastern fields via pipeline injection systems reducing transport costs for high-volume chemical categories.
Kuwait & Iraq Oilfield Chemicals Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Kuwait and Iraq's procurement hierarchies. National oil companies dominate volume allocation through annual framework agreements, while international service contractors capture premium positioning via integrated performance contracts. Three archetypes populate the competitive terrain: integrated energy majors with captive chemical divisions, specialized oilfield service providers bundling supply with technical service, and regional distributors serving spot procurement needs. M&A activity concentrates on digital chemistry platform acquisition, while capacity expansion targets localized blending facilities under Iraq's domestic content mandates.
Among European-headquartered chemical conglomerates, BASF SE and Solvay SA exemplify the integrated formulation archetype, anchoring supply relationships through advanced surfactant chemistry capabilities. Halliburton occupies a position within the service-contractor tier, representing the bundled technical service model that Kuwait Oil Company and Basra Oil Company increasingly favor for complex carbonate reservoir applications. These three entities illustrate the competitive tension between product-centric and service-integrated go-to-market approaches reshaping procurement patterns across the northern Gulf basin.
| Leading Market Players |
|---|
| BASF SE |
| Chevron Corporation |
| Baker Hughes Company |
| Al Sanea Chemical Products |
| Petroleum Equipment Technology Company |
| Halliburton |
| Solvay SA |
| Catalyst LLC |
| Schlumberger Limited |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in European specialty surfactant manufacturing compresses input pricing for Kuwaiti and Iraqi formulators while tightening margins for regional blenders competing on specification compliance. This utilization asymmetry rewards suppliers with backward-integrated feedstock positions and penalizes import-dependent distributors facing qualification delays under REACH-equivalent protocols.
Pricing Analysis
The pricing gap between conventional corrosion inhibitor formulations and next-generation high-temperature chemistries spans three performance tiers. Contract-based long-term offtake dominates procurement for National Oil Companies, with price differentiation driven by certification grade under Iraq's Ministry of Oil disclosure mandates and volume scale commitments across southern Iraq's field clusters. Cost compression in standard-grade demulsifiers intensifies as Saudi and UAE intermediate supply expands, while premium EOR surfactant packages retain pricing power. Service contractors show lowest price sensitivity due to performance-guarantee contracts, with independent operators most exposed to spot market volatility.
Supply Chain Analysis
Tariff exposure between European specialty chemical suppliers and Middle Eastern formulators dominates supply chain risk planning for high-salinity surfactant inputs. Manufacturing concentrates in Germany, Belgium, and the Netherlands for advanced polymer feedstocks, while Saudi Arabia and the UAE anchor regional intermediate production. Raw material dependencies span ethylene oxide derivatives, acrylamide monomers, and quaternary ammonium compounds. Single-source vulnerability persists for concentrated surfactant manufacturing outside the Gulf Cooperation Agreement zone. Distribution runs through Jubail and Ruwais supply hubs serving northern Gulf basin blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment creates switching costs that lock in qualified suppliers. Iraq's Ministry of Oil localization mandates and Kuwait's Environmental Public Authority discharge standards erect compliance barriers that favor incumbents with technical dossier capabilities.
For Market Incumbents: Harden supply chain resilience by securing captive manufacturing of specialty surfactant intermediates in Saudi Arabia or the UAE, reducing exposure to European import qualification timelines. Expand technical service capacity in Basra province to capture integrated performance contracts bundling formulation supply with reservoir engineering support, defending against digital chemistry platform competitors. For New Entrants and Emerging Players: Establish a beachhead in Kuwait's southeastern offshore platform segment where space constraints and remote monitoring requirements favor concentrated formulation providers with automated dosing capabilities. Target smart-enabled chemical monitoring systems as the most penetrable white space, leveraging cloud-based optimization algorithms to differentiate from legacy manual-intervention suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across localized blending facilities under Iraq's domestic content directives, favoring asset-heavy operators with regulatory compliance infrastructure. Long-term viability centers on suppliers with integrated digital-physical service models capable of capturing procurement consolidation trends. Watch Basra Oil Company framework agreement awards as the signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Intermediates | Captive supply of high-salinity surfactants insulates margins from European currency volatility. |
| Localized Blending Facility Deployment | Domestic content compliance unlocks Iraq Ministry of Oil contract eligibility under localization mandates. |
| Digital Chemistry Platform Acquisition | Cloud-based dosing optimization compresses field service costs for Kuwait Oil Company maturing fields. |
| Long-term Supply Agreement with Basra Oil Company | Integrated performance contracts bundle EOR chemicals with reservoir engineering support. |
| Green Certification Program for Biocide Reformulation | Lower-toxicity oxygen scavenger chemistry aligns with Kuwait Environmental Public Authority discharge standards. |
Research Methodology
The analysis maps corrosion inhibitor, demulsifier, and EOR surfactant sub-sectors, each validated through procurement managers at National Oil Companies, technical directors at international service contractors, and plant managers at regional blending facilities. Primary interviews with supply chain executives and regulatory compliance officers combined with secondary validation from customs trade data, Iraq Ministry of Oil procurement disclosures, and SEC filings of listed chemical conglomerates. Bottom-up field-level consumption estimates triangulated against top-down market sizing across the projection horizon.
Assumption sets held fixed Iraq's Ministry of Oil localization trajectory and Kuwait's Environmental Public Authority discharge standards while varying polymer flooding deployment rates and smart-enabled chemical monitoring adoption curves. Segmentation dimensions modeled include formulation chemistry grade, reservoir application type, procurement channel archetype, and field deployment architecture. CAGRs derived from regression analysis of historical chemical consumption against well count and water-cut profiles, incorporating EOR chemical intensity coefficients for carbonate reservoir flooding.
Sensitivities concentrate around Iraq's domestic content enforcement pace and European REACH-equivalent alignment timelines for import qualification. Forecasts reflect documented assumptions on regulatory implementation and field development schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Well Casing Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market