
 Smart Pigging Market | 2026-2036
Smart Pigging Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pigging Market Insights
A shift from single-source to multi-source procurement is rebalancing how pipeline operators secure inspection services. Baker Hughes Company leverages its integrated manufacturing and services footprint to capture bundled contracts across North America and the Middle East. ROSEN Group sustains technology leadership through proprietary ultrasonic and electromagnetic platform development. T.D. Williamson anchors its position with mechanical sealing and pigging hardware that interfaces directly with smart inspection tools.
Smart pigging refers to the inline inspection of pipelines using instrumented devices that detect metal loss, cracks, and geometric anomalies through magnetic flux leakage, ultrasonic testing, or electromagnetic acoustic transducer technologies, with sensor resolution typically measured in millimeters and data capture rates exceeding hundreds of readings per second. These tools serve the critical purpose of preventing catastrophic pipeline failures, hydrocarbon releases, and service interruptions across energy and utility infrastructure. Ultrasonic technology occupies the premium tier of the market due to its precision in wall-thickness measurement and crack detection, while magnetic inspection dominates volume deployment for corrosion mapping in carbon steel transmission lines. The offshore deployment segment commands elevated service margins given logistical complexity, regulatory stringency, and the technical demands of subsea launcher and receiver operations.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration enforces integrity management rules that mandate periodic inline inspection for high-consequence areas, directly sustaining baseline demand for smart pigging services. In Europe, the EU Pipeline Safety Directive and national regulators such as Germany's Federal Network Agency compel transmission system operators to demonstrate fitness-for-service through documented inspection campaigns. Stakeholders must monitor how regulatory harmonization between North American and European standards shapes tool certification requirements and cross-border service mobility.
Market Dynamics
The transition from scheduled maintenance cycles to condition-based monitoring is compressing inspection intervals and expanding the addressable base of pipeline segments requiring smart pigging services. This operational shift is forcing operators to renegotiate service contracts and upgrade data infrastructure.
Growth Catalysts
- PHMSA Integrity Management Rules:Mandatory inline inspection requirements for high-consequence areas in the United States sustain baseline demand for ultrasonic and magnetic flux leakage tools across transmission networks.
- Hydrogen pipeline repurposing:European transmission system operators are certifying existing natural gas infrastructure for hydrogen blending, necessitating enhanced crack detection and material compatibility assessments.
- Subsea tieback expansion:Deepwater field developments in the Gulf of Mexico and offshore West Africa are proliferating subsea launcher and receiver installations that require specialized smart pigging logistics.
Market Restraints
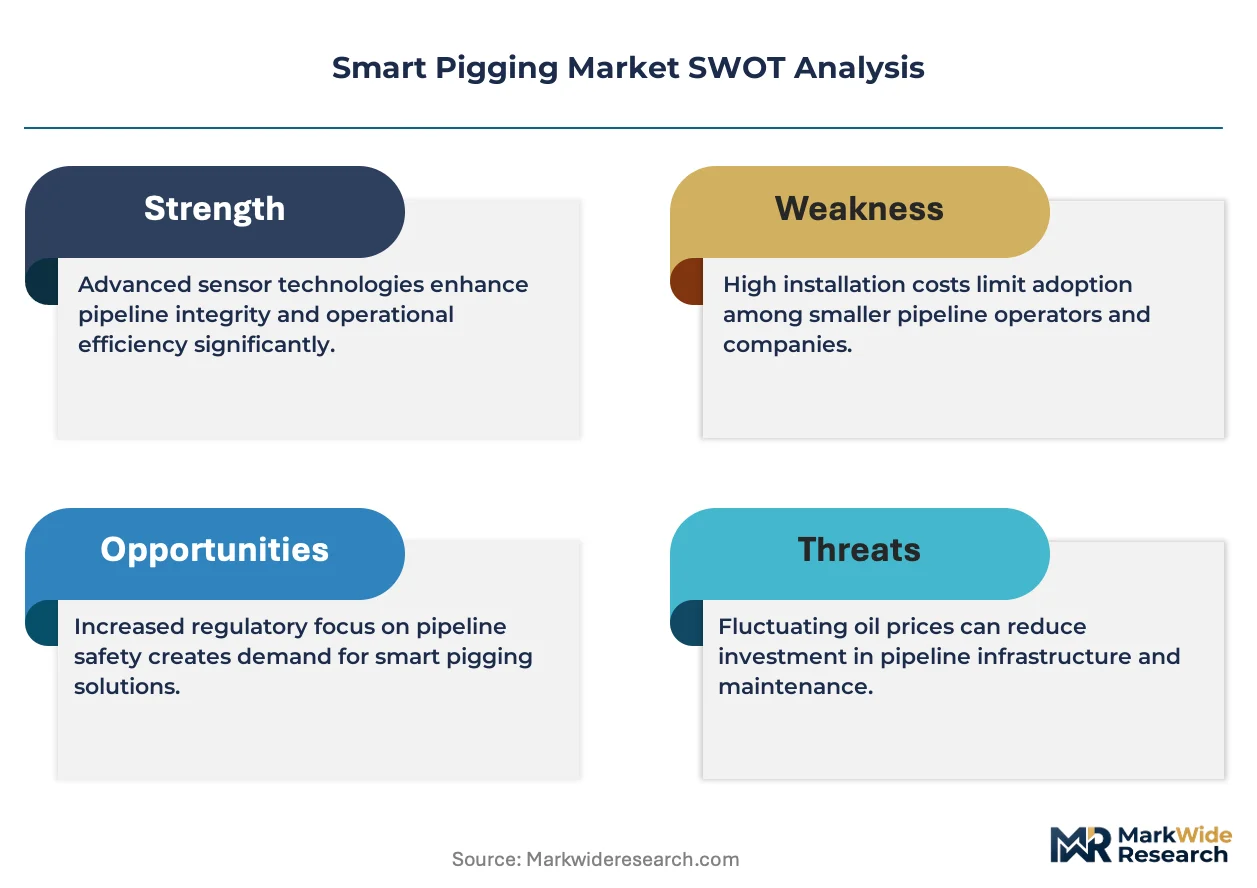
- Specialized steel pricing volatility:Tool body fabrication depends on high-grade alloy steel subject to fluctuating nickel and chromium input costs, compressing hardware margins for inspection equipment manufacturers.
- Transducer supply concentration:Piezoelectric sensor production clusters in Japan and South Korea, creating single-source vulnerability for ultrasonic tool assemblers seeking alternative qualified suppliers.
- Bi-directional pigging limitation:Certain pipeline geometries and valve configurations preclude conventional smart tool retrieval, restricting inspection coverage in complex distribution networks.
Strategic Opportunities
- Carbon capture transport corridors:CO2 pipeline construction in the United States Midwest and Gulf Coast is generating demand for corrosion-resistant inspection protocols tailored to dense-phase fluid properties.
- Real-time data transmission:Integration of fiber-optic telemetry with in-line inspection tools enables immediate anomaly flagging, reducing response latency for critical defect identification.
- Decommissioning liability assessment:Aging North Sea infrastructure requires fitness-for-purpose evaluations prior to abandonment, extending tool utilization into end-of-life asset management services.
Industry Challenges
- Data analyst scarcity:Pipeline operators face recruitment gaps for personnel capable of interpreting multi-terabyte inspection datasets and translating findings into maintenance action plans.
- Tool calibration complexity:Verification of sensor accuracy requires reference standards traceable to national metrology institutes, extending pre-deployment timelines for international projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pigging Market |
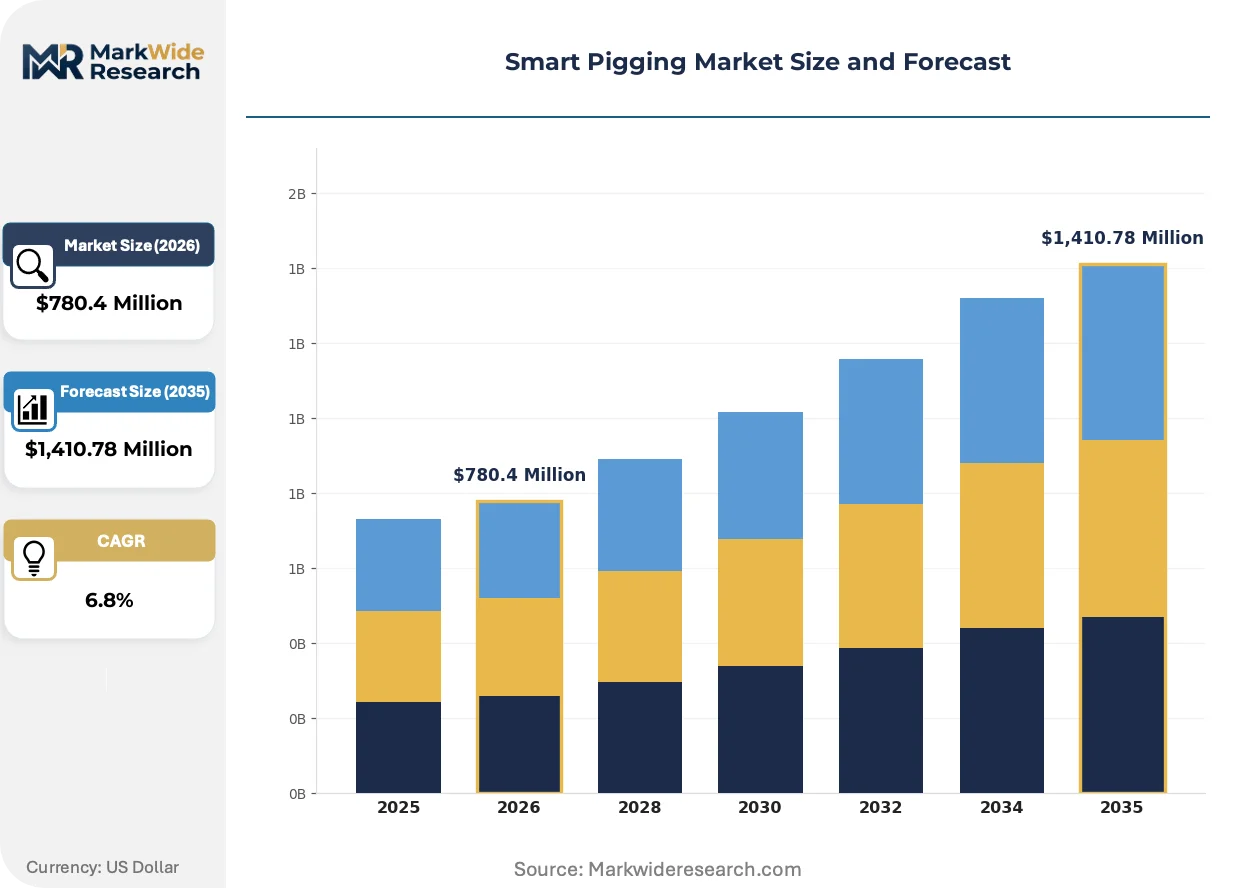
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,410.78 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic, Magnetic, Electromagnetic, Mechanical Application: Oil & Gas, Water Supply, Chemical Processing, Power Generation End User: Utilities, Industrial Manufacturing, Oil Refineries, Pipeline Operators Deployment: Onshore, Offshore, Above Ground, Below Ground |
| Companies Covered | Baker Hughes Company, ROSEN Group, T.D. Williamson, NDT Global, Enduro Pipeline Services, SGS SA, Intertek Group, LIN SCAN, Applus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pigging Market Trends and Innovations
Sensor miniaturization and edge computing are enabling inspection platforms that operate with reduced launcher infrastructure and faster turnaround between runs. These advances are compressing the capital barrier for mid-scale operators to adopt premium-tier ultrasonic technologies.
Electromagnetic acoustic transducer arrays are decentralizing crack detection capabilities previously restricted to laboratory-grade ultrasonic systems. Midstream operators in the Permian Basin and Appalachian shale corridors are deploying EMAT-equipped tools for girth weld inspection without surface preparation. This capability expansion is compressing the price premium between magnetic flux leakage and ultrasonic service tiers.
The EU Pipeline Safety Directive's fitness-for-service documentation requirements are mandating traceable inspection records with defined uncertainty bounds. Transmission system operators in Germany and the Netherlands are upgrading to tools certified under EN 16348 for crack detection and EN 15542 for metal loss measurement. This regulatory harmonization is accelerating tool certification convergence across European national regulators.
Service contract unbundling is separating hardware provision from data interpretation and integrity engineering. Pipeline operators in Alberta and Texas are procuring inspection tools on lease while retaining third-party analysts for defect assessment. This disaggregation is visible most acutely in the United States, where independent engineering firms are capturing analytical workstreams previously bundled within integrated service offerings.
Smart Pigging Market Segmentation
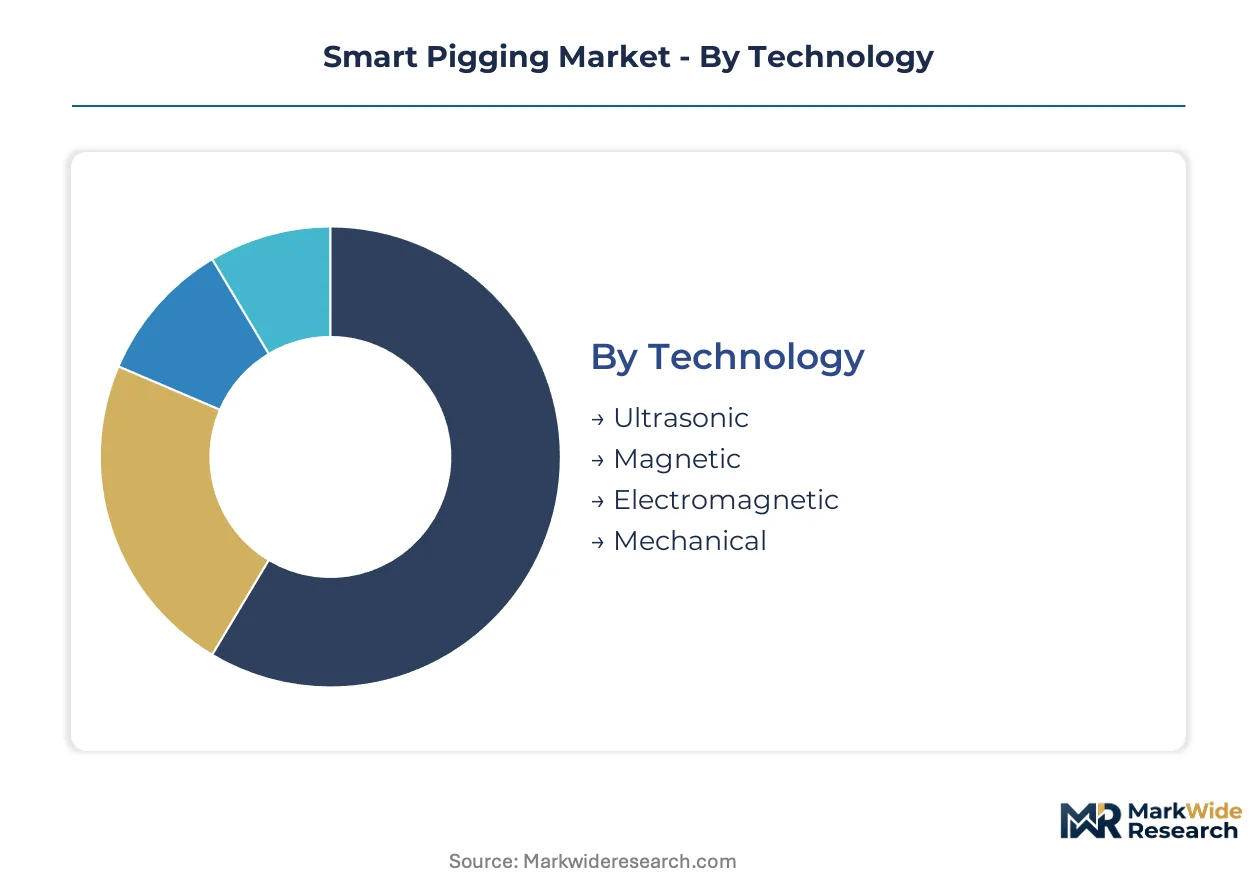
Smart pigging procurement decisions cluster around technology performance tiers and deployment complexity. Pipeline operators match inspection specifications to fluid characteristics, regulatory mandates, and accessibility constraints across their asset portfolios.
Technology:
Supply concentration in piezoelectric sensor fabrication shapes competitive dynamics across technology tiers. Japanese and South Korean component manufacturers control critical transducer supply channels for premium ultrasonic systems.
- Ultrasonic:High-frequency acoustic pulses measure wall thickness and detect crack anomalies with millimeter-scale resolution. Gulf Coast offshore corridors and North Sea subsea networks drive concentrated procurement for crack detection in high-consequence areas subject to PHMSA and EU Pipeline Safety Directive mandates.
- Magnetic:Magnetic flux leakage tools map corrosion patterns across carbon steel transmission lines through induced magnetic fields and flux disturbance detection. Onshore gathering systems in the Permian Basin and Appalachian shale corridors sustain volume deployment for corrosion monitoring in large-diameter pipelines.
- Electromagnetic:EMAT arrays enable girth weld inspection without surface preparation, compressing deployment timelines for midstream operators.
- Mechanical:Gauging and cleaning pigs equipped with geometric measurement capabilities support pre-inspection pipeline conditioning.
Magnetic systems absorb the bulk of installed capacity; ultrasonic platforms are expanding most quickly.
Application:
Cost tier differentiation separates commodity inspection from specialized protocols tailored to fluid reactivity and contamination risk.
- Oil & Gas:Hydrocarbon transmission networks require metal loss, crack, and deformation detection across crude oil, refined products, and natural gas lines. PHMSA integrity management rules mandate periodic inline inspection for high-consequence areas, sustaining baseline demand across United States interstate and intrastate systems.
- Water Supply:Potable and wastewater infrastructure employs geometric inspection and leak detection tools for pressure management and structural integrity assessment. Municipal utilities in Germany and the Netherlands deploy smart pigging for aging cast iron replacement prioritization under national water quality frameworks.
- Chemical Processing:Corrosion-resistant tool specifications address aggressive fluid chemistries in specialty chemical and petrochemical corridors.
- Power Generation:Cooling water and feedwater pipeline networks require inspection protocols for flow assurance and thermal efficiency maintenance.
Oil and gas applications command the steepest pricing premiums; water supply is gaining share fastest as municipal infrastructure ages.
End User:
Customer type determines procurement sophistication, with integrated operators bundling services and independent operators unbundling hardware from analytics.
- Utilities:Gas distribution and water utilities operate extensive pipeline networks requiring systematic inspection programs. United States municipal gas utilities and European transmission system operators balance regulatory compliance costs against asset replacement timelines.
- Industrial Manufacturing:Process industry operators with captive pipeline networks deploy inspection tools for reliability-centered maintenance programs.
- Oil Refineries:Refinery complex operators inspect process piping and tank farm connections for corrosion under insulation and flow-accelerated corrosion.
- Pipeline Operators:Dedicated midstream companies manage third-party transportation infrastructure across interstate and international corridors.
Pipeline operators concentrate procurement volume; utilities are climbing the fastest as distribution integrity rules tighten.
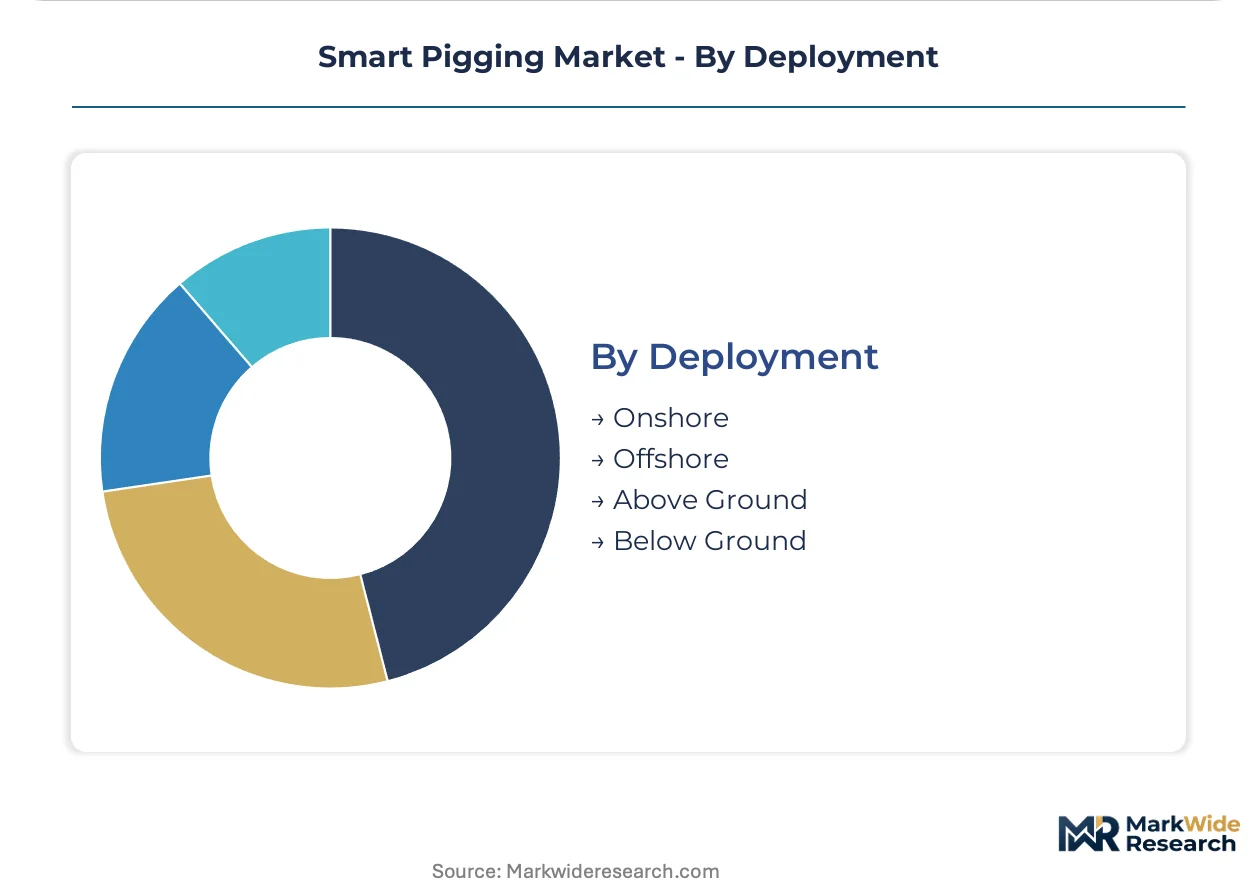
Deployment:
Margin structure escalates with logistical complexity and environmental exposure severity.
- Onshore:Terrestrial pipeline inspection benefits from established launcher and receiver infrastructure across transmission corridors. United States interstate systems and European cross-border connections sustain routine deployment schedules with compressed mobilization costs.
- Offshore:Subsea operations require specialized vessel support, diving intervention capability, and subsea launcher receiver systems. Gulf of Mexico deepwater developments and West African offshore fields command elevated day rates for inspection campaigns.
- Above Ground:Elevated and surface-laid pipelines in arctic and desert environments present thermal expansion and accessibility considerations.
- Below Ground:Buried distribution networks in urban environments require excavation contingency planning and traffic management coordination.
Onshore deployment handles the majority of inspection runs; offshore is expanding most quickly as subsea tieback development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast petrochemical corridors and North Sea subsea infrastructure anchor geographic demand concentration for inline inspection services. Pipeline density in these regions correlates directly with procurement volume for ultrasonic and magnetic flux leakage tool deployment.
United States
PHMSA integrity management rules mandate periodic inline inspection for high-consequence areas across interstate transmission networks. The Gulf Coast corridor concentrates offshore and onshore procurement activity, with subsea launcher installations proliferating in deepwater developments. Houston anchors service provider headquarters and tool fabrication capacity.
Germany
The Federal Network Agency compels transmission system operators to demonstrate fitness-for-service through documented inspection campaigns under EU Pipeline Safety Directive harmonization. Hydrogen pipeline repurposing initiatives drive enhanced crack detection procurement for existing natural gas infrastructure. Ruhr industrial clusters and North Sea port terminals concentrate tool deployment logistics.
United Kingdom
Aging North Sea infrastructure requires fitness-for-purpose evaluations prior to abandonment, extending smart pigging utilization into end-of-life asset management. The Health and Safety Executive enforces offshore pipeline integrity standards that sustain subsea inspection demand. Aberdeen serves as the operational hub for decommissioning assessment campaigns.
Netherlands
Transmission system operators upgrade to tools certified under EN 16348 for crack detection and EN 15542 for metal loss measurement. Port of Rotterdam throughput and cross-border pipeline connections sustain routine deployment schedules. Groningen gas field depletion accelerates infrastructure reassessment requirements.
Saudi Arabia
Aramco pipeline expansion and East-West crude oil corridor maintenance sustain demand for high-temperature inspection tools. The national oil company procures bundled services combining hardware provision with integrity engineering. Dhahran and Jubail industrial cities concentrate deployment coordination for domestic and export pipeline networks.
Smart Pigging Market Competitive Landscape
Global majors compete with regional champions across technology tiers and service integration models. The vendor base separates into consolidated integrated service providers, specialized ultrasonic tool developers, and regional mechanical hardware fabricators. Three archetypes dominate: full-service bundlers capturing multi-year contracts, technology specialists licensing proprietary sensor platforms, and hardware-focused suppliers piggybacking on third-party analytics. Competitive moves concentrate on service contract unbundling and real-time data transmission integration.
Within the full-service bundler tier, Baker Hughes Company and SGS SA represent integrated manufacturing and services footprints. ROSEN Group exemplifies technology specialists with proprietary platform development. T.D. Williamson anchors the hardware-focused segment. These three occupy distinct competitive positions without direct overlap in core capability emphasis.
| Leading Market Players |
|---|
| Baker Hughes Company |
| ROSEN Group |
| T.D. Williamson |
| NDT Global |
| Enduro Pipeline Services |
| SGS SA |
| Intertek Group |
| LIN SCAN |
| Applus |
| Others |
Pricing and Supply Chain Analysis
Nickel and chromium price indices on the London Metal Exchange cascade directly into ultrasonic tool fabrication costs, compressing hardware margins and forcing tiered pricing stratification across premium sensor platforms and standard magnetic flux leakage systems. Pipeline operators absorb these input cost swings through renegotiated service contracts that unbundle hardware provision from data interpretation.
Pricing Analysis
Warranty and service bundling separates integrated offerings from unbundled procurement, with full-service contracts commanding premiums for traceable calibration certificates and post-run integrity engineering. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EN 16348 and EN 15542, volume scale, and geographic delivery complexity. Cost compression in standard magnetic tiers is intensifying because of transducer supply bottlenecks. Independent midstream operators in Texas and Alberta exhibit highest price sensitivity; Gulf Coast offshore operators show least sensitivity due to regulatory mandate rigidity.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean piezoelectric transducer manufacturers, concentrating critical sensor supply channels for premium ultrasonic platforms. Tool body fabrication draws from German and United States alloy steel mills, while electromagnetic acoustic transducer arrays source from specialized European component houses. Tariff exposure on nickel and chromium inputs creates margin volatility for hardware assemblers. Distribution runs through Houston and Dhahran service hubs that coordinate launcher receiver logistics and vessel chartering for offshore campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transducer fabrication capacity constraints prop pricing power for qualified ultrasonic tool suppliers, creating supply-constrained conditions that favor incumbents with captive sensor relationships.
For Market Incumbents: Hedge against EMAT technology displacement by securing backward integration into piezoelectric sensor supply through long-term offtake agreements with Japanese manufacturers. Expand calibration laboratory capacity in the United States Gulf Coast to capture EN 16348 certification demand from European transmission system operators facing hydrogen pipeline repurposing mandates.
For New Entrants and Emerging Players: Launch via lease-based hardware models targeting Alberta and Texas independent midstream operators who unbundle analytics from tool provision. White-space targets include real-time fiber-optic telemetry integration and carbon capture pipeline inspection protocols for United States Midwest corridors. Municipal water utilities in Germany and the Netherlands represent the most penetrable segment given aging cast iron replacement prioritization.
For Investors and Strategic Acquirers: The window for entry favors technology specialists with proprietary EMAT platforms and established EN certification trajectories. Long-term viability hinges on regulatory harmonization between PHMSA and EU Pipeline Safety Directive standards. Watch hydrogen blending certification timelines as the inflection signal for crack detection tool demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Transducer Supply Agreement | Secures qualified sensor channels from Japanese manufacturers against single-source risk. |
| EN 16348 Certification Investment | Unlocks EU transmission system operator procurement under Pipeline Safety Directive harmonization. |
| Real-Time Telemetry Integration | Enables immediate anomaly flagging for Gulf Coast deepwater subsea operations. |
| Hydrogen Compatibility Assessment | Positions tools for European natural gas infrastructure repurposing campaigns. |
| Lease-Based Hardware Model | Captures unbundled procurement demand from Texas and Alberta independent operators. |
Research Methodology
Document review covered PHMSA incident databases, EU Pipeline Safety Directive implementation reports, and EN standard certification registries, complemented by interviews with pipeline integrity managers at United States interstate operators, inspection service procurement leads at European transmission system operators, ultrasonic tool engineering directors, and subsea logistics coordinators. Secondary validation drew from FERC pipeline safety filings, EIA infrastructure databases, and trade customs records for alloy steel and transducer components. Bottom-up segment sizing triangulated against top-down infrastructure investment forecasts.
Segment-level projections across technology tiers, deployment modes, and end-user categories produced volume and value estimates over the projection horizon. The analytical framework modeled ultrasonic, magnetic, electromagnetic, and mechanical platform adoption against regulatory mandate timelines and pipeline age profiles. CAGRs derived from infrastructure replacement cycles, integrity management rule enforcement patterns, and hydrogen corridor development schedules.
Specialized steel pricing volatility, transducer supply disruption, and regulatory certification timeline delays are the dominant revision risks for forecast trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Oil & Gas Equipment MRO Market