
 Tubing Heads Market | 2026-2036
Tubing Heads Market Size, Share, and Industry Trends Forecast 2026-2036
Tubing Heads Market Analytics
North American forging capacity is recalibrating after years of underinvestment in pressure-containing components. Schlumberger Limited leverages captive foundry networks to secure alloy steel supply for high-specification tubing heads. Baker Hughes Company anchors its position through API-licensed machine shops in Houston and Aberdeen. Weatherford International Plc competes on modular adjustable designs that reduce rig-up time for drilling contractors.
A tubing head is a flanged or threaded pressure-control device mounted atop the casing head, typically rated to API 6A pressure classes from 2,000 to 20,000 psi, designed to suspend tubing strings and seal annular spaces between production casing and tubing. Its primary purpose is to provide a pressure barrier and mechanical support interface for Christmas trees and blowout preventers during completion and production operations. Standard tubing heads dominate volume in mature onshore basins where well designs follow predictable templates, while heavy-duty tubing heads capture margin in HPHT offshore applications where material specifications escalate to super-duplex stainless steel. Carbon steel retains share in cost-sensitive land markets, though alloy steel is displacing it in sour-service environments where NACE MR0175 compliance is mandatory.
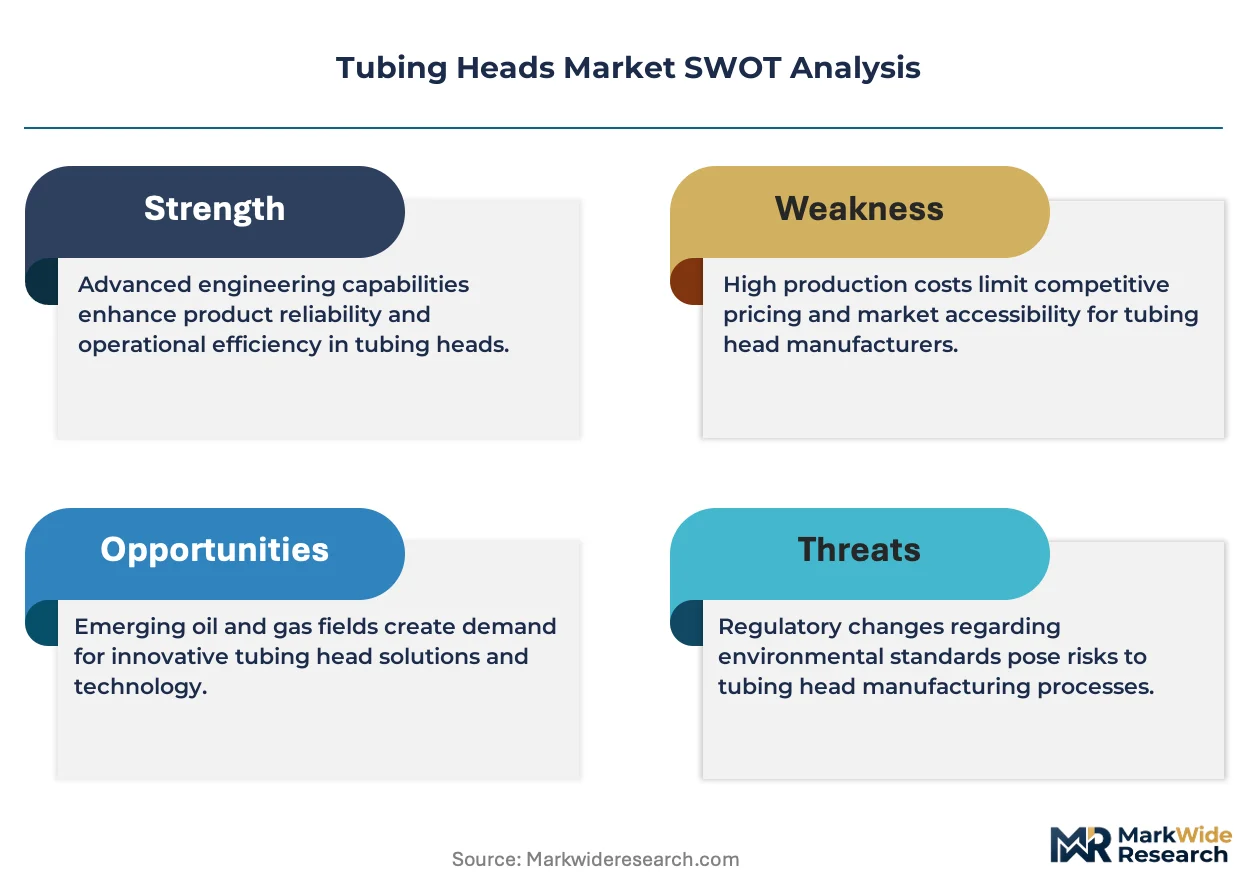
API 6A governs design, materials, and testing for wellhead equipment in the United States, while the EU Pressure Equipment Directive imposes conformity assessment modules on tubing heads imported into European offshore markets. The EPA's methane emissions rules are pushing operators toward tighter annular seal designs that reduce fugitive leaks during well life. Stakeholders must monitor how API's evolving material traceability standards interact with supply chain consolidation among forging houses to avoid qualification bottlenecks.
Market Dynamics
API 6A material traceability mandates are compressing the qualified supplier base for pressure-containing components, forcing procurement teams to consolidate around machine shops with captive metallurgical testing capabilities and documented heat-treatment records.
Growth Catalysts
- Permian Basin HPHT completions:Onshore shale operators in Texas and New Mexico are expanding tubing head procurement to handle higher-pressure well designs, driving specification upgrades across regional supply chains.
- EPA methane emissions rules:The EPA's fugitive leak standards are pushing operators toward tighter annular seal designs that reduce emissions during production operations.
- Super-duplex stainless steel adoption:Sour-service environments are displacing carbon steel with NACE MR0175-compliant alloys in HPHT offshore applications.
Market Restraints
- Forging capacity concentration:North American forging houses face years of underinvestment in pressure-containing components, creating qualification bottlenecks for API 6A-certified material.
- Alloy steel input volatility:Nickel and molybdenum price swings directly impact super-duplex stainless steel tubing head margins.
- EU Pressure Equipment Directive friction:Conformity assessment modules impose extended lead times for tubing heads imported into European offshore markets.
Strategic Opportunities
- Modular adjustable designs:Rig-up time reduction is creating white space for tubing heads that compress drilling contractor mobilization schedules.
- NACE-compliant welding capabilities:Regional machine shops with certified welding programs can capture share from integrated OEM supply chains.
- Texas-New Mexico vendor consolidation:Drilling contractors are narrowing supplier relationships around regional fabrication clusters, favoring proximity over price.
Industry Challenges
- API 6A certification timeline compression:Material traceability documentation requirements are extending qualification cycles for new forging suppliers.
- Welding technician scarcity:NACE-compliant welding certification programs are not producing qualified technicians at the pace of demand growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubing Heads Market |
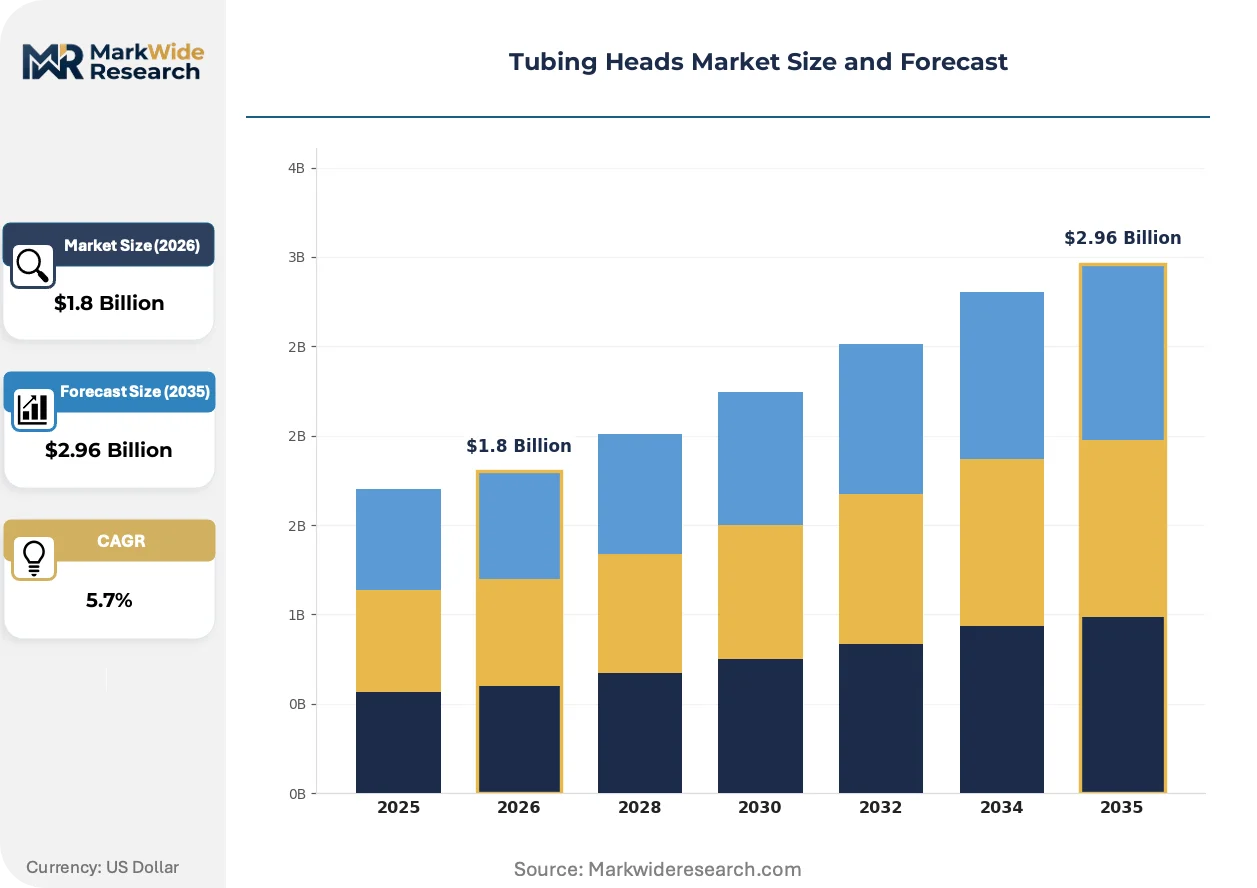
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubing Heads, Heavy-Duty Tubing Heads, Adjustable Tubing Heads, Custom Tubing Heads Material: Carbon Steel, Stainless Steel, Alloy Steel, PVC Application: Oil Extraction, Gas Extraction, Geothermal Applications, Water Well Drilling End User: Oil & Gas Companies, Drilling Contractors, Mining Operations, Water Service Providers |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, TechnipFMC Plc, Cactus Inc, Dril-Quip Inc, Delta Corporation, Weatherford International Plc, Nabors Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubing Heads Market Evolving Landscape
Digital material tracking systems and additive manufacturing prototypes are reshaping how tubing heads are specified, tested, and deployed across pressure-rated applications.
Additive manufacturing for rapid prototyping of complex flange geometries is decentralizing the traditional foundry-to-machine-shop workflow. Smaller regional fabricators in Houston and Aberdeen are adopting metal 3D printing for fixture and prototype production, compressing iteration cycles from months to weeks. This technology is decentralizing design authority away from integrated OEM engineering centers toward field-adjacent machine shops.
REACH substance restrictions in the European Union are tightening the acceptable chemistry range for surface coatings on subsea tubing heads. Manufacturers serving North Sea operators must now document SVHC-free corrosion protection systems or face market exclusion. EU-based fabricators are responding by shifting to thermally sprayed aluminum coatings that satisfy both REACH and NORSOK M-501 standards.
Drilling contractors are unbundling after-sales service contracts from initial equipment purchase, creating separate procurement streams for installation support and field maintenance. This behavioral shift is disrupting the traditional OEM service bundling model in the Permian Basin and Gulf of Mexico shelf operations. Independent service companies with API-licensed technicians are capturing this disaggregated spend.
Tubing Heads Market Segmentation
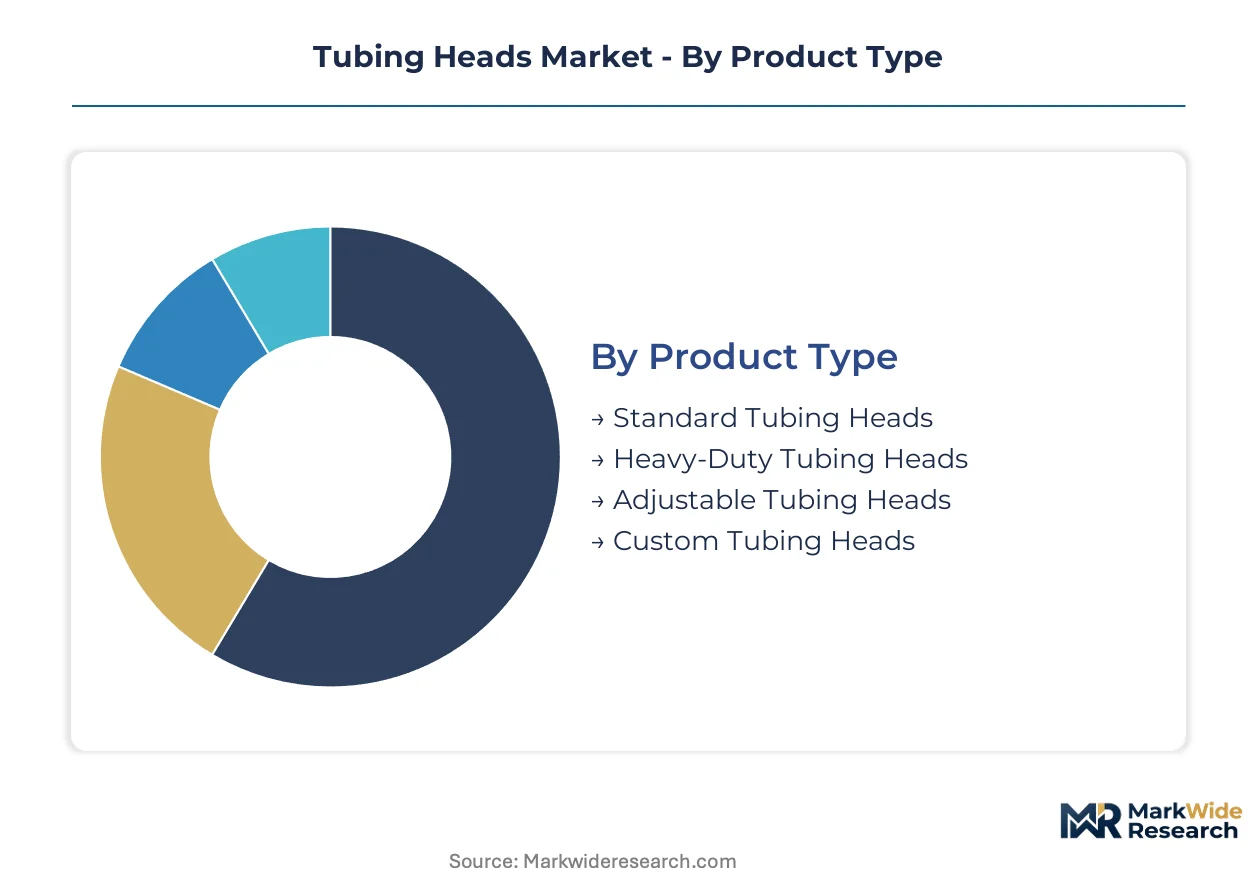
Tubing head procurement patterns diverge sharply between mature onshore basins with predictable well templates and frontier HPHT environments demanding engineered-to-order specifications. Segmentation reveals how material selection and pressure ratings reshape vendor qualification requirements across drilling programs.
Product Type:
Customization intensity spans from catalog-standard flanges to fully engineered assemblies requiring metallurgical witness testing at every production stage.
- Standard Tubing Heads:Fixed-bore flanged designs rated 2,000–10,000 psi dominate Permian Basin land programs where well architectures follow repetitive patterns. Procurement teams in Texas and New Mexico favor these for velocity in high-volume drilling schedules.
- Heavy-Duty Tubing Heads:Forged alloy construction rated 15,000–20,000 psi anchors deepwater Gulf of Mexico completions where super-duplex specifications and NACE MR0175 compliance are mandatory. Demand concentrates with supermajors operating HPHT prospects off Louisiana.
- Adjustable Tubing Heads:Modular designs with variable bore configurations reduce rig-up time for drilling contractors managing multi-well pad developments.
- Custom Tubing Heads:Application-specific geometries with non-standard flange interfaces serve specialized subsea tiebacks and extended-reach horizontals.
Most installed capacity flows through Standard Tubing Heads. Expansion is steepest in Heavy-Duty Tubing Heads.
Material:
Cost-to-performance tradeoffs determine alloy selection, with sour-service mandates displacing baseline grades in corrosive formations.
- Carbon Steel:ASTM A105 forgings retain share in dry-gas land markets where cost sensitivity outweighs corrosion risk. Operators in the Anadarko Basin specify these for shallow vertical wells with limited H2S exposure.
- Alloy Steel:Chromium-molybdenum grades with documented heat-treatment records satisfy API 6A traceability mandates for HPHT completions. Permian operators expanding into deeper Delaware Basin targets are specifying these for 12,000+ psi environments.
- Stainless Steel:410/17-4PH martensitic grades balance corrosion resistance with mechanical strength for moderate-sour service.
- PVC:Thermoplastic construction serves low-pressure water well and monitoring applications outside hydrocarbon extraction.
Carbon Steel retains the largest installed base. Alloy Steel is gaining share fastest as sour-service drilling expands.
Application:
Pressure regime and fluid chemistry dictate specification intensity, with hydrocarbon extraction commanding premium metallurgy over geothermal or water applications.
- Oil Extraction:High-pressure artificial lift configurations and thermal recovery methods drive demand for enhanced seal packages in California heavy oil and Permian unconventional plays.
- Gas Extraction:Dry gas and wet gas completions in the Marcellus and Haynesville shales require tubing heads with robust annular isolation for extended production cycles.
- Geothermal Applications:Corrosive brine environments at elevated temperatures push specification toward nickel-alloy cladding in Nevada and Utah development projects.
- Water Well Drilling:Municipal and agricultural groundwater systems utilize lower-pressure rated heads with simplified installation protocols.
Oil Extraction absorbs the greatest procurement volume. Gas Extraction shows the most rapid specification escalation as deeper targets proliferate.
End User:
Buying power and technical sophistication separate integrated operators from service-dependent contractors, reshaping vendor relationship structures.
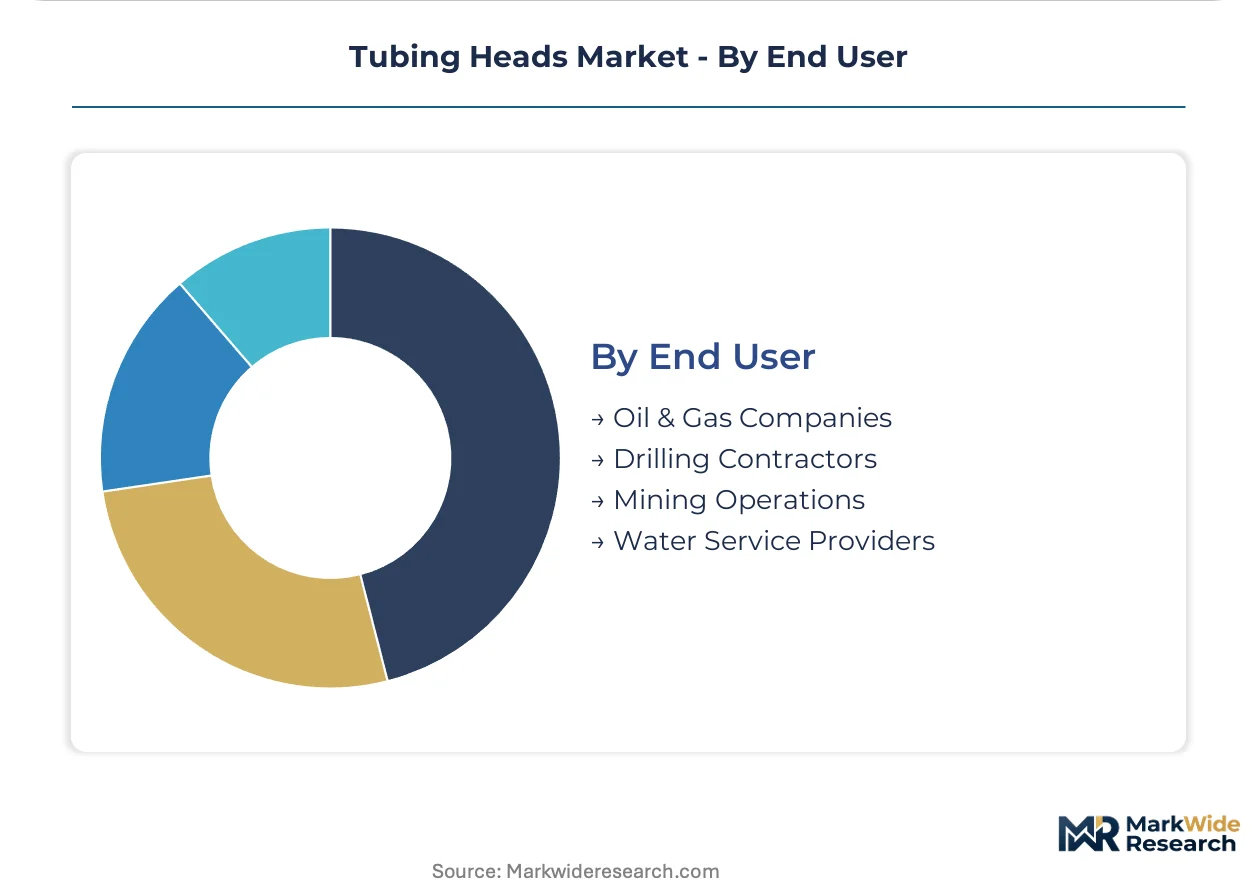
- Oil & Gas Companies:Supermajors and large independents in the Gulf of Mexico mandate captive supply agreements with documented material traceability from melt to final machining.
- Drilling Contractors:Nabors and Helmerich & Payne negotiate fleet-wide pricing for standardized heads while outsourcing HPHT specifications to OEM engineering teams.
- Mining Operations:In-situ leach and solution mining programs in Wyoming and Kazakhstan utilize modified wellhead equipment for injection-production cycles.
- Water Service Providers:Municipal utilities and agricultural districts procure through distributor channels with limited technical specification involvement.
Oil & Gas Companies command the specification authority. Drilling Contractors represent the highest transaction velocity segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redirecting tubing head fabrication toward jurisdictions with streamlined API 6A certification pathways and established pressure-equipment testing infrastructure. Production capacity migrates to regions where material traceability documentation aligns with operator procurement timelines.
United States
Permian Basin HPHT completions drive specification upgrades across Texas and New Mexico drilling programs. EPA methane emissions rules tighten annular seal requirements for production-stage equipment. Houston anchors North American fabrication capacity, with regional machine shops consolidating vendor relationships around NACE-compliant welding capabilities.
Norway
North Sea subsea developments demand super-duplex stainless steel specifications for high-pressure sour-service environments. NORSOK M-501 standards govern surface coating compliance alongside REACH substance restrictions. Stavanger and Bergen host fabrication clusters serving Equinor and Aker BP deepwater projects.
Saudi Arabia
Aramco's unconventional gas program expands HPHT wellhead procurement for Jafurah Basin development. The country's national oil company mandates captive supply agreements with documented material traceability from melt to final machining. Eastern Province fabrication yards concentrate capacity for offshore and onshore mega-projects.
Brazil
Pre-salt carbonate reservoirs push tubing head ratings toward 15,000 psi for ultra-deepwater completions. ANP local content requirements shape procurement decisions for foreign operators. Rio de Janeiro and Macaé host service company clusters supporting Petrobras Búzios and Mero field developments.
China
Shale gas development in Sichuan Basin accelerates demand for sour-service alloy specifications. GB standards and API 6A dual certification requirements filter qualified suppliers. Chengdu and Chongqing machine shops expand capacity for domestic operators developing Fuling and Weirong fields.
Tubing Heads Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular adjustable designs and additive manufacturing capabilities to compress rig-up timelines. The vendor base organizes around three archetypes: integrated oilfield service conglomerates with captive foundry networks, regional fabrication specialists with NACE-certified welding programs, and independent machine shops competing on proximity to Permian and Gulf of Mexico drilling activity. Dominant competitive moves include strategic partnerships between forging houses and machine shops to secure API 6A material traceability, plus capacity expansion in Texas and Aberdeen clusters.
Among integrated service conglomerates, Schlumberger Limited and Baker Hughes Company represent the scale-driven archetype with upstream control over alloy steel supply chains. Weatherford International Plc exemplifies the specialist tier, occupying a position around modular adjustable designs that reduce contractor mobilization schedules. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| TechnipFMC Plc |
| Cactus Inc |
| Dril-Quip Inc |
| Delta Corporation |
| Weatherford International Plc |
| Nabors Industries Ltd. |
| Others |
Value Network & Pricing Analysis
API 6A certification tiers split the tubing head market into sharply divergent value bands, with NACE-compliant alloy specifications commanding premiums that reflect both metallurgical complexity and the concentrated forging capacity capable of delivering documented heat-treatment records. This bifurcation channels procurement toward Houston and Aberdeen machine shops with captive testing capabilities while squeezing margin from carbon steel fabricators competing on spot-market alloy inputs.
Pricing Analysis
Distributor markups on standard tubing heads compress as drilling contractors consolidate direct relationships with regional fabrication clusters. Three-tier pricing structure across premium super-duplex, standard alloy steel, and economy carbon steel levels reflects certification grade and material traceability depth. Cost compression in the standard tier intensifies because Permian Basin operators are unbundling after-sales service from equipment purchase. Drilling contractors exhibit highest price sensitivity on catalog-standard flanges, while Gulf of Mexico supermajors prioritize material documentation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Aramco and Equinor mandate qualified backup suppliers for critical pressure-containing components, stretching qualification timelines across multiple forging houses. Manufacturing concentrates in the United States, Norway, and Saudi Arabia, with raw material supply drawing from nickel and molybdenum markets subject to commodity volatility. Supply chain risk centers on single-source vulnerability for super-duplex stainless steel forgings with documented NACE compliance. Distribution runs through OEM-direct channels for HPHT specifications and regional machine shop networks for standard onshore procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in tubing heads rests on the shift toward engineered-to-order HPHT specifications where alloy complexity and certification documentation create pricing power, alongside additive manufacturing adoption that compresses prototype-to-production cycles for modular adjustable designs.
For Market Incumbents: Anticipate additive manufacturing disruption by securing captive metallurgical testing capabilities and documented heat-treatment partnerships with regional forging houses. API 6A timeline compression threatens qualification bottlenecks; backward integration into NACE-compliant welding programs in Texas and Aberdeen defends position against regional machine shop encroachment. For New Entrants and Emerging Players: Enter via modular adjustable tubing head designs that reduce rig-up time for multi-well pad drilling contractors in the Permian Basin. The most penetrable white space sits in aftermarket service contracts unbundled from initial equipment purchase, with API-licensed technician networks as the critical go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where forging capacity scarcity intersects with tightening material traceability mandates, favoring acquisition of regional machine shops with NACE-certified welding programs and documented supplier relationships. Target vertically integrated fabrication specialists with proximity to Permian and Gulf of Mexico activity. Watch super-duplex stainless steel input costs as the signal for margin inflection across the HPHT tier.| Strategic Initiative | Industry Significance |
|---|---|
| API 6A Certification Investment | Documented material traceability from melt to machining secures Aramco and Equinor captive supply agreements. |
| NACE-Compliant Welding Program Expansion | Regional machine shops in Texas capture share from integrated OEM supply chains through certified technician networks. |
| Additive Manufacturing Capability Buildout | Houston and Aberdeen fabricators compress prototype iteration cycles from months to weeks for custom flange geometries. |
| Backward Integration into Forging Partnerships | Strategic alliances with alloy steel suppliers lock in heat-treatment capacity ahead of qualification bottlenecks. |
| Aftermarket Service Unbundling | Independent API-licensed technician companies capture disaggregated spend from Permian Basin drilling contractors. |
Research Methodology
Coverage spans the United States, Norway, Saudi Arabia, Brazil, and China, with primary inputs from each market combining interviews with drilling contractor procurement directors, wellhead engineering leads at supermajors, NACE-certified welding program managers, regional machine shop owners, and API-licensed aftermarket service technicians. Secondary validation draws from API certification databases, EPA methane emissions filings, NORSOK M-501 compliance records, ANP local content disclosures, and customs trade data for alloy steel forgings. Bottom-up tubing head shipment estimates triangulate against top-down drilling activity projections.
Granularity-level modeling disaggregates volume and value across product type, material grade, pressure rating class, application chemistry, and end-user buying power archetype. CAGRs derive from regression analysis against drilling permit trajectories, completion intensity ratios, and specification escalation patterns in HPHT environments. Forecast inputs include Permian Basin well design evolution, North Sea subsea project timelines, and Aramco Jafurah Basin development pacing.
Inputs from API certification registries and regional drilling contractor spending surveys were available through the study window; gaps in real-time alloy steel inventory positions at forging houses introduce uncertainty bands around near-term capacity utilization assumptions. Deviation in nickel and molybdenum price trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pipeline Pigging Valves Market
Valves
Pipeline Pigging System Market
Valves
HVAC Valves Market
Valves
Global Control Valves Market
Valves
Harmonic Dampers Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Emergency Shutdown Valves Market
Valves
Middle East and Africa Machined Seals Market
Valves
Pigging Valves Market
Valves
Pipeline Equipment Market
Valves
North America Valves Market
Valves
Hydraulic Valves Market
Valves
Curb Valves Market
Valves
Pipeline Strainers Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
Pressure Reducing Valve Market