
 Pipeline Equipment Market | 2026-2036
Pipeline Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Equipment Market Analytics
Buyer concentration among North American midstream operators is rebalancing procurement leverage toward fewer, larger contract holders. Shell sustains integrated project execution across deepwater and LNG export infrastructure. Kiewit Corporation anchors domestic construction capacity with self-performed pipeline spreads. Samsung Engineering competes on modular fabrication scale for Middle Eastern and Asian developments.
Pipeline equipment encompasses pressure-containing components—valves, fittings, flanges, and piping systems—fabricated from carbon steel, stainless alloys, or thermoplastics to convey hydrocarbons, water, or chemicals at rated pressures and temperatures. Manufacturing involves forging, casting, seamless extrusion, and welded fabrication followed by hydrostatic testing and coating per API and ASTM specifications. Valves command the largest product-type margin pool due to actuation complexity and replacement frequency, while below-ground installation dominates capital deployment in urban water and gas distribution networks where trenchless methods reduce surface disruption. Steel remains the default material for high-pressure hydrocarbon service, though PVC gains share in municipal water reticulation where corrosion resistance and lower installed weight offset pressure limitations.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration enforces integrity management rules under 49 CFR Part 195, mandating inline inspection and pressure testing that sustains demand for smart pigging ports and full-encirclement sleeves. The EPA's Clean Water Act and state-level public utility commissions shape material selection and leak detection standards for water transmission infrastructure. Stakeholders must monitor how methane emission regulations and renewable natural gas injection requirements redefine compressor station and gathering line specifications before committing to long-dated manufacturing capacity.
Market Dynamics
Midstream procurement consolidation across North American basins is compressing supplier margins while elevating technical qualification thresholds for API-certified fabricators.
Growth Catalysts
- 49 CFR Part 195 integrity mandates:PHMSA inspection schedules sustain replacement demand for smart pigging launchers and full-encirclement repair sleeves across US transmission networks.
- Permian Basin gathering buildout:Produced water handling and gas lift infrastructure requires high-pressure alloy piping rated for corrosive service.
- Hydrogen blending trials:European network operators in the Netherlands and Germany are retrofitting compressor stations for hydrogen-natural gas mixtures, creating specification lift for embrittlement-resistant steel grades.
Market Restraints
- Scrap steel price volatility:Electric arc furnace operators face margin compression when shredded auto scrap spikes above $400 per ton, squeezing seamless pipe foundries.
- Chinese seamless pipe dominance:Baosteel and Tianjin Pipe account for over half of global OCTG export volume, creating single-source risk for non-integrated distributors.
- Thermoplastic pressure limits:HDPE and PVC piping max out at 250 psi working pressure, excluding them from interstate gas transmission where 1,440 psi is standard.
Strategic Opportunities
- Carbon capture transport corridors:US Gulf Coast CCS projects require dense-phase CO2 pipelines with 316L stainless specifications for acid gas service.
- Renewable natural gas injection:California and Oregon biogas upgrading facilities need corrosion-resistant gathering lines meeting biomethane purity standards.
- Modular skid fabrication:Middle Eastern NOCs are pre-qualifying packaged compressor and metering stations for rapid desert deployment.
Industry Challenges
- ASME Section IX welder certification backlogs:Pipeline construction seasons stall when qualified combination welders for 6G position testing are unavailable.
- API 5L traceability documentation:Heat number tracking through multi-tier subcontracting creates audit failures and shipment holds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Equipment Market |
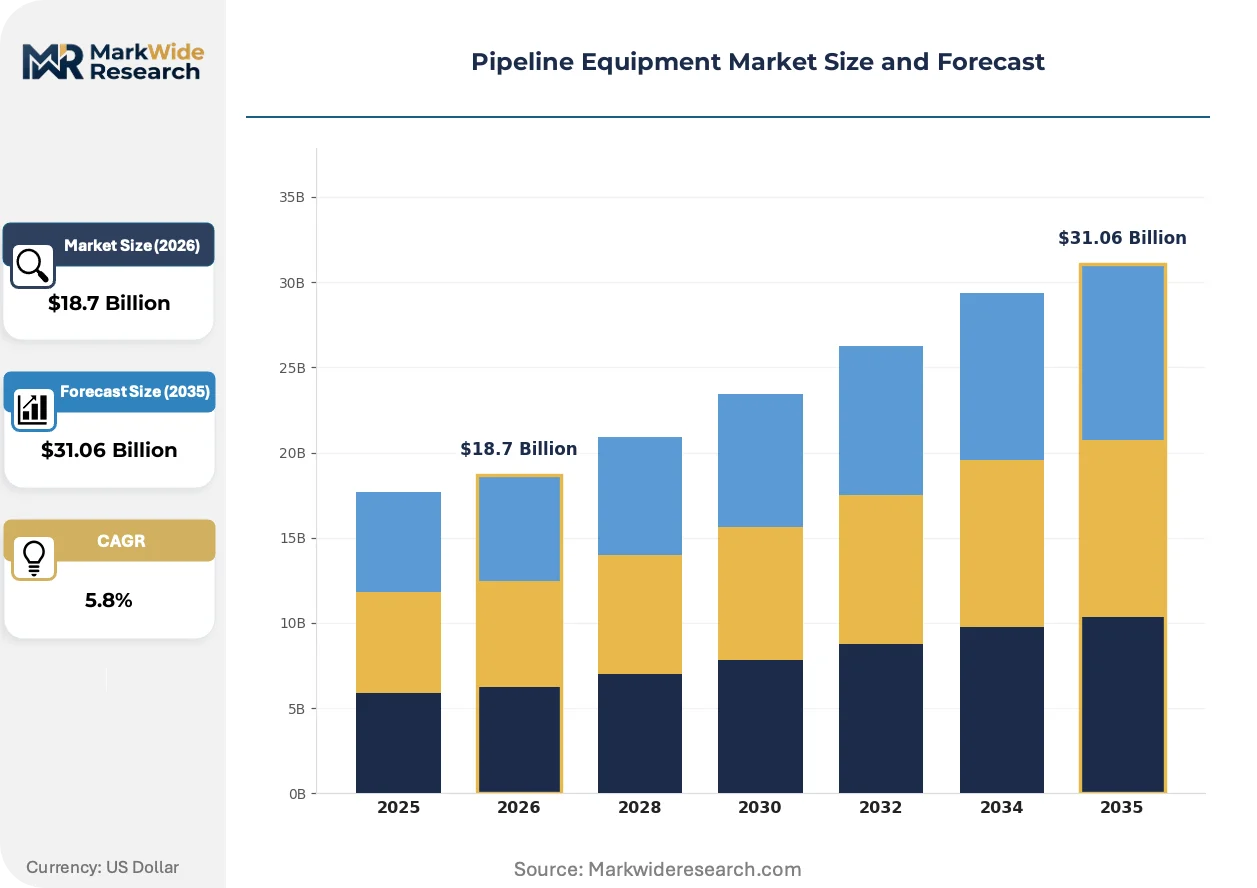
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valves, Fittings, Flanges, Piping End User: Oil & Gas, Water Supply, Chemical Processing, Utilities Material: Steel, PVC, Copper, Aluminum Installation Type: Above Ground, Below Ground, Onshore, Offshore |
| Companies Covered | Woodside Energy Group, Shell, Mastec, Samsung Engineering, PetroVietnam Gas Corporation, Michels Corporation, Equinor Energy, Chevron, Kiewit Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Equipment Market Evolving Landscape
Digital thread integration from mill certificates to installation records is compressing quality assurance cycles while enabling predictive corrosion monitoring across asset lifecycles.
Composite reinforced thermoplastic pipe is expanding into onshore gathering systems where spoolable installation cuts labor hours by two-thirds compared to welded steel. Permian operators including Pioneer Natural Resources and Diamondback Energy are qualifying spoolable composite for 1,500 psi sour gas service. The technology is expanding into brownfield rehabilitation where road crossings and watercourse permits block open-cut replacement.
EU Methane Regulation 2024/1787 imposes quarterly LDAR surveys and ban-on-venting rules for gas transmission operators. The framework forces compressor station upgrades with dry seal retrofits and continuous emissions monitoring systems. German network operator Open Grid Europe is front-loading capital to avoid 2027 non-compliance penalties, accelerating valve and seal procurement cycles.
Integrated suppliers are bundling inline inspection, coating, and logistics under multi-year throughput guarantees. Midstream buyers in the Marcellus and Utica shales are trading unit price discounts for vendor-managed inventory programs that eliminate stockout risk during construction windows. This reconfiguration is most advanced in Appalachia where seasonal freeze constraints compress executable work periods.
Pipeline Equipment Market Segmentation
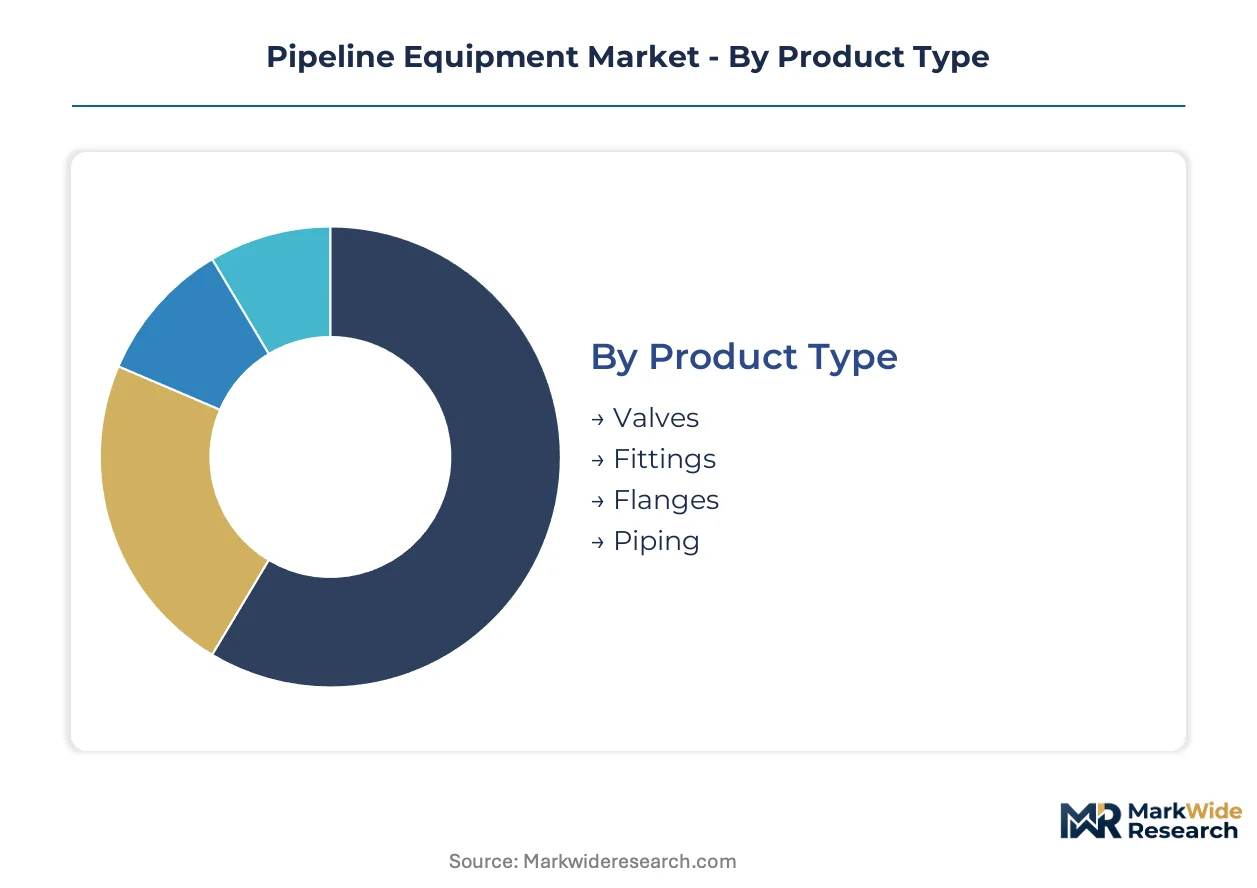
Pipeline equipment segmentation reveals how procurement decisions align with pressure ratings, corrosion environments, and regulatory exposure. Buyers optimize specifications across product type, end-use, material, and installation method to balance capital efficiency with lifecycle compliance costs.
Product Type:
Replacement cycles vary sharply by product type, with actuated components demanding more frequent overhaul than static pressure boundaries.
- Valves:Gate, ball, and check valves incorporate forged steel bodies with API 6D certification for isolation service. Actuation complexity—pneumatic, hydraulic, or electric—drives aftermarket parts demand in Permian Basin gathering systems where sour gas accelerates seal degradation.
- Fittings:Elbows, tees, and reducers fabricated through seamless extrusion or welded construction provide directional changes and diameter transitions. Water utilities in Texas and California specify cement-lined ductile iron fittings for corrosion resistance in aggressive soil conditions.
- Flanges:Weld-neck and slip-on configurations per ASME B16.5 provide demountable joints for maintenance access.
- Piping:Seamless and welded line pipe in API 5L grades forms the primary pressure envelope for transmission corridors.
Valves sit at the top of the volume ranking, with fittings climbing the fastest as water infrastructure rehabilitation accelerates.
End User:
Cost tier differentiation separates specification-intensive hydrocarbon service from standard-pressure municipal applications.
- Oil & Gas:Midstream operators require full material traceability, sour service NACE compliance, and inline inspection compatibility. Gulf Coast LNG export terminals specify cryogenic-grade valves and double-block-and-bleed configurations for liquefaction trains.
- Water Supply:Municipal utilities prioritize corrosion resistance and joint reliability over pressure extremes. California's Central Valley water districts specify PVC C-900 for agricultural distribution where trenching costs dominate project economics.
- Chemical Processing:Refinery and petrochemical complexes demand alloy specifications for high-temperature, high-acid service.
- Utilities:Electric power generators and district heating networks require steam-rated piping and condensate handling equipment.
Oil & Gas commands the largest procurement spend, though Water Supply is expanding most quickly as federal infrastructure funding flows to lead pipe replacement programs.
Material:
Application environment dictates material selection, with pressure-temperature ratings and soil chemistry driving specification splits.
- Steel:Carbon and alloy grades dominate high-pressure hydrocarbon transport. X70 and X80 line pipe grades reduce wall thickness for interstate transmission, cutting welding labor and transportation costs across Appalachian and Rocky Mountain corridors.
- PVC:Thermoplastic pressure piping serves municipal water reticulation and sanitary sewer force mains. C-900 and C-905 dimensions provide corrosion immunity and lower installed weight for trenchless installation methods in urban rights-of-way.
- Copper:Soft-temper tubing and brazed joints serve fuel gas distribution in residential and commercial buildings.
- Aluminum:Lightweight extrusions appear in cryogenic and chemical transfer applications where weight reduction offsets material cost premiums.
Steel maintains the highest shipment tonnage, with PVC gaining share fastest in corrosion-prone water infrastructure.
Installation Type:
Geography and surface constraints determine installation methodology, with offshore and below-ground applications commanding premium specifications.
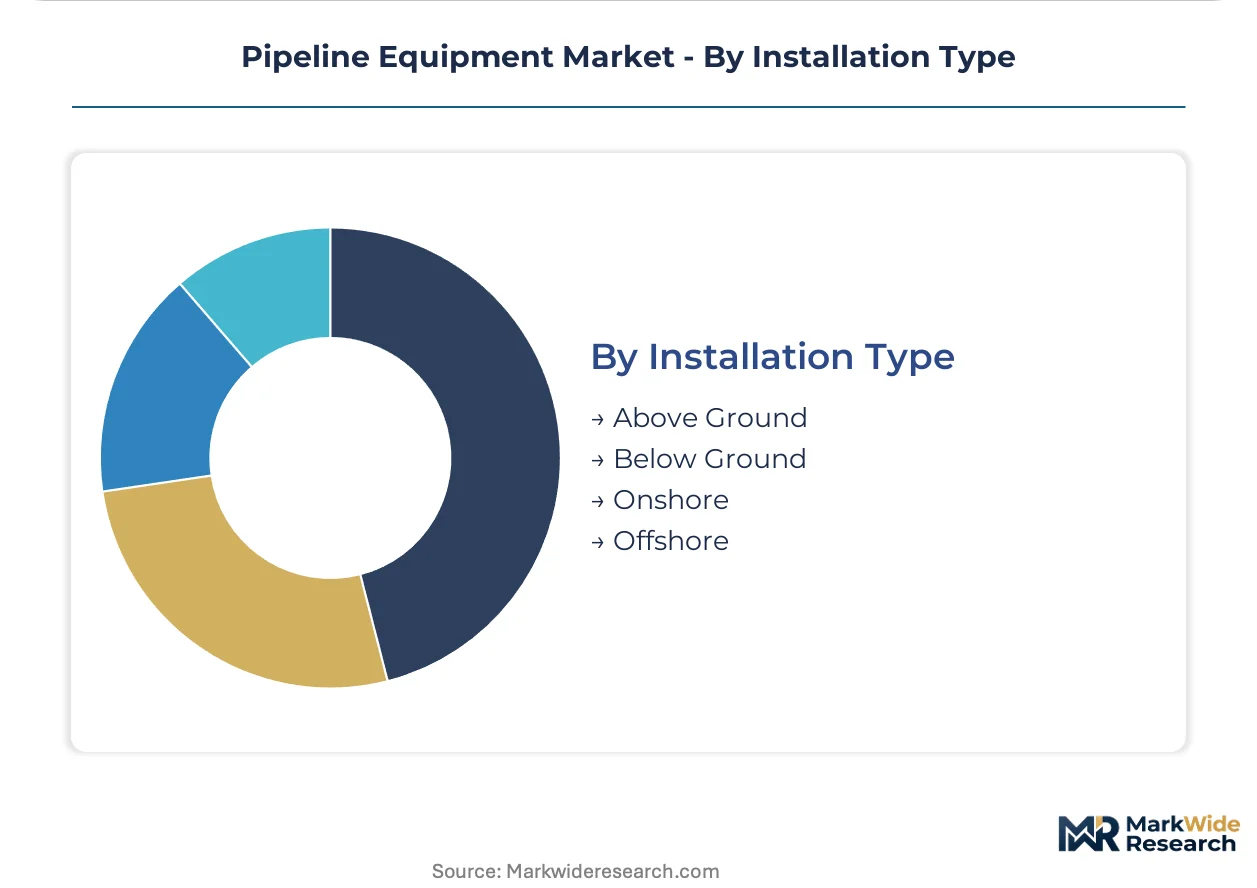
- Above Ground:Elevated piping on pipe racks and sleeper supports simplifies inspection and maintenance access. Refinery complexes in Texas and Louisiana specify above-ground routing for fire safety and leak detection visibility.
- Below Ground:Buried installation protects piping from mechanical damage and temperature extremes. Urban gas distribution networks in the Northeast specify polyethylene fusion-jointed service lines to eliminate corrosion risk in aggressive soils.
- Onshore:Terrestrial pipeline construction spans desert, permafrost, and seismic zones with tailored cathodic protection and bedding specifications.
- Offshore:Subsea production flowlines and export pipelines require corrosion-resistant alloys, concrete weight coating, and reel-lay or S-lay installation compatibility.
Below Ground represents the dominant installation mode by linear footage, with Offshore showing the steepest expansion trajectory as deepwater developments proceed in the Gulf of Mexico.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hydrogen pipeline retrofitting accelerates faster than Canada's carbon capture transport buildout, yet both trail the United States in absolute infrastructure spend. Regional procurement patterns diverge sharply between mature basin maintenance and frontier project development.
United States
PHMSA integrity mandates under 49 CFR Part 195 sustain replacement demand for smart pigging launchers across Texas and Louisiana corridors. The EPA's methane emission rules force compressor station upgrades with dry seal retrofits. Gulf Coast LNG export terminals in Texas specify cryogenic-grade valves and double-block-and-bleed configurations for liquefaction trains.
Germany
Open Grid Europe front-loads capital to avoid 2027 EU Methane Regulation non-compliance penalties, accelerating valve and seal procurement cycles. The EU Green Deal hydrogen backbone initiative drives embrittlement-resistant steel specifications for hydrogen-natural gas blending trials. Industrial clusters in the Ruhr Valley anchor converter station fabrication for pipeline network retrofits.
China
MIIT dual carbon goals redirect state pipeline investment toward CO2 transport infrastructure for enhanced oil recovery projects. GB standards for hydrogen-compatible steel grades tighten material certification requirements. Manufacturing concentration in Tianjin and Shanghai sustains seamless pipe export dominance despite trade friction.
Saudi Arabia
NEOM Northwest development requires dense-phase hydrogen pipelines with 316L stainless specifications for high-purity transport service. The country's national oil company pre-qualifies modular compressor skids for rapid desert deployment. Eastern Province fabrication yards anchor Gulf regional supply for Middle Eastern NOC developments.
Australia
Woodside Energy Group's Scarborough and Browse projects drive subsea flowline demand for corrosion-resistant alloys with concrete weight coating. The country's offshore safety regulator mandates inline inspection compatibility for all new export pipeline installations. Perth-based engineering clusters specialize in reel-lay installation method procurement.
Pipeline Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where scale and technical depth trade off against agility. Midstream consolidation in North America compresses supplier margins while elevating qualification thresholds for API-certified fabricators. Three archetypes dominate: integrated energy majors with captive project execution arms, specialized construction contractors with self-performed pipeline spreads, and modular fabrication houses serving international developments. Competitive moves center on multi-year throughput guarantee bundling and vendor-managed inventory programs that eliminate stockout risk during compressed construction windows.
Within the integrated major tier, Shell and Chevron exemplify project execution scale across deepwater and LNG export infrastructure. Among specialized contractors, Kiewit Corporation anchors domestic construction capacity with self-performed pipeline spreads, while Samsung Engineering occupies a position in modular fabrication scale for Middle Eastern and Asian developments. These three represent distinct competitive vectors: energy-major vertical integration, contractor-led construction dominance, and international modular packaging.
| Leading Market Players |
|---|
| Woodside Energy Group |
| Shell |
| Mastec |
| Samsung Engineering |
| PetroVietnam Gas Corporation |
| Michels Corporation |
| Equinor Energy |
| Chevron |
| Kiewit Corporation |
| Others |
Value Network & Pricing Analysis
Spoolable composite pipe deployment across Permian Basin gathering systems compresses installed cost structures while redistributing fabrication value toward specialized resin and fiber suppliers. This production-method transition simultaneously erodes traditional welded steel premium pricing and concentrates supply leverage among composite material formulators with API 15S certification.
Pricing Analysis
Capacity additions in China are reshaping price floors for seamless OCTG, forcing electric arc furnace mills in the US Gulf Coast to differentiate on API 5L traceability documentation and rapid-turn contract flexibility. Three-tier pricing structure across premium certified, standard mill-run, and economy import grades separates buyers by integrity mandate exposure and construction window certainty. Cost compression in standard grades is intensifying because midstream procurement consolidation extracts volume discounts for multi-year framework agreements. Municipal water utilities exhibit highest price sensitivity due to bond-financed capital constraints, while LNG export terminal operators prioritize specification compliance over unit cost.
Supply Chain Analysis
Freight cost volatility for heavy-wall line pipe from Tianjin and Shanghai to Houston and Rotterdam compresses distributor margins and accelerates regional stocking point expansion. Manufacturing gravity centers on China for seamless pipe, India for forged fittings, and Germany for high-pressure valve actuation systems. Raw material flows draw from Brazilian iron ore, Australian coking coal, and Middle Eastern alloying elements. Single-source vulnerability concentrates in Chinese seamless pipe dominance for X70 and X80 grades. Distribution runs through API-certified stocking distributors with mill-direct relationships for project-specific heat lot segregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Methane Regulation compliance costs in Germany and the Netherlands exceed PHMSA mandate spending in US shale corridors, creating divergent equipment specification premiums.
For Market Incumbents: Hedge carbon steel margin erosion by securing backward integration into scrap processing or resin compounding for composite alternatives. Defensive consolidation should prioritize API 6D valve repair facilities in the Marcellus and Permian basins where replacement frequency outpaces newbuild demand. Threat substitution from thermoplastic pressure limits below 250 psi constrains addressable market expansion; lever certification investment in hydrogen-compatible steel grades to capture European retrofit cycles. For New Entrants and Emerging Players: Capture brownfield rehabilitation demand in the US Northeast where road crossing permits block open-cut replacement and spoolable composite installation cuts labor hours. White-space targets concentrate in California renewable natural gas gathering lines requiring corrosion-resistant specifications and biomethane purity compliance. Go-to-market angle should emphasize rapid mobilization for compressed construction windows in seasonal freeze-constrained regions. For Investors and Strategic Acquirers: Valuations sit cheapest among regional API-certified fabricators without integrated project execution arms. Long-term viability across the analysis window favors suppliers with captive access to embrittlement-resistant steel grades and modular skid packaging capabilities. Acquisition target archetype: mid-cap specialists with NACE sour service qualification and established relationships with North American midstream consolidators. Signal to watch: hydrogen blending trial expansion beyond Netherlands-Germany corridor into Iberian and Italian network operator procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Compatible Steel Certification | Secures specification compliance for EU Green Deal hydrogen backbone retrofits in German industrial clusters. |
| Modular Skid Fabrication Scale-Up | Addresses Middle Eastern NOC demand for rapid desert deployment of packaged compressor stations. |
| Composite Pipe Spoolable Manufacturing | Captures Permian Basin sour gas service qualification from Pioneer Natural Resources and Diamondback Energy. |
| Vendor-Managed Inventory Programs | Eliminates stockout risk for midstream buyers in Appalachia during compressed freeze-limited construction windows. |
| Digital Thread Quality Assurance Integration | Compresses audit cycles from mill certificates through installation records for predictive corrosion monitoring. |
Research Methodology
Multiple input streams — regulatory filing analysis, customs trade records, and equipment procurement databases — were reconciled against primary fieldwork with midstream procurement directors, EPC contractor project managers, API certification auditors, and valve aftermarket service heads. Secondary validation drew from PHMSA incident reports, EPA methane emission disclosures, FERC certificate filings, and EU Methane Regulation implementation guidance. Bottom-up project pipeline tracking and top-down infrastructure spend estimates were triangulated to anchor volume assumptions.
Data-stream reconciliation across the projection horizon applied segment-specific growth coefficients for valves, fittings, flanges, and piping systems by pressure rating, material grade, and installation method. Analytical framework incorporated end-use splits between oil and gas transmission, water supply, and chemical processing with regional regulatory cluster differentiation. CAGRs were derived from installed base replacement cycles, integrity mandate compliance schedules, and frontier project development timelines. Industry-specific inputs included hydrogen blending trial announcements, carbon capture transport corridor permits, and renewable natural gas facility commissioning.
Underlying measurement precision varies by segment; standard-pressure water infrastructure carries tighter precision than speculative hydrogen backbone equipment specifications. Forecasts reflect documented assumptions regarding regulatory enforcement timing and commodity price baselines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Level Gauge Market
Valves
Subsea Control System Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Reciprocating Compressor Components Market
Valves
Fin Tube Market
Valves
Valve Sack Market
Valves
Motorized Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Static Seals Market
Valves
Mobile Hydraulic Valves Market
Valves
Cathodic Protection Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Harmonic Dampers Market
Valves
Global Plastic Valves Market
Valves
Global Flow Control Market
Valves
Deluge Valve Market