
 Pneumatic Slide Gates Market | 2026-2036
Pneumatic Slide Gates Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Slide Gates Market Insights
China's industrial valve manufacturing corridor is fragmenting as regional foundries expand pneumatic actuator capacity to serve bulk material handlers. Vortex Global leverages its North American fabrication network to sustain leadership in heavy-duty mining applications. Schenck Process anchors European demand through integrated material handling systems that incorporate slide gate assemblies.
Pneumatic slide gates are linear shutoff devices that use compressed air to drive a blade or plate across a flow path, typically constructed from carbon steel, stainless steel, or aluminum with seals rated for temperatures exceeding 200°C and pressures up to 15 bar, engineered to isolate or regulate dry bulk solids in pneumatic conveying and gravity flow systems. Automatic slide gates dominate the product category as plant automation investments displace manual operators, while high-pressure configurations capture expanding margin pools in chemical processing where seal integrity failures carry catastrophic cost. Compact slide gates represent the fastest-growing product type as original equipment manufacturers integrate space-constrained designs into mobile material handling systems and modular processing skids.
The EPA enforces Maximum Achievable Control Technology standards that mandate sealed containment in pneumatic conveying lines, directly elevating demand for zero-leakage slide gate architectures in U.S. facilities. ECHA's REACH restrictions on chromium compounds in seal elastomers are forcing European manufacturers to qualify alternative chemistries that maintain abrasion resistance. ISO 9001 quality management certification and ATEX directives for explosive dust atmospheres collectively determine market access thresholds across industrialized economies. Stakeholders must monitor how electrification of pneumatic supply systems and compressed air energy efficiency standards reshape total cost of ownership calculations for gate specification decisions.
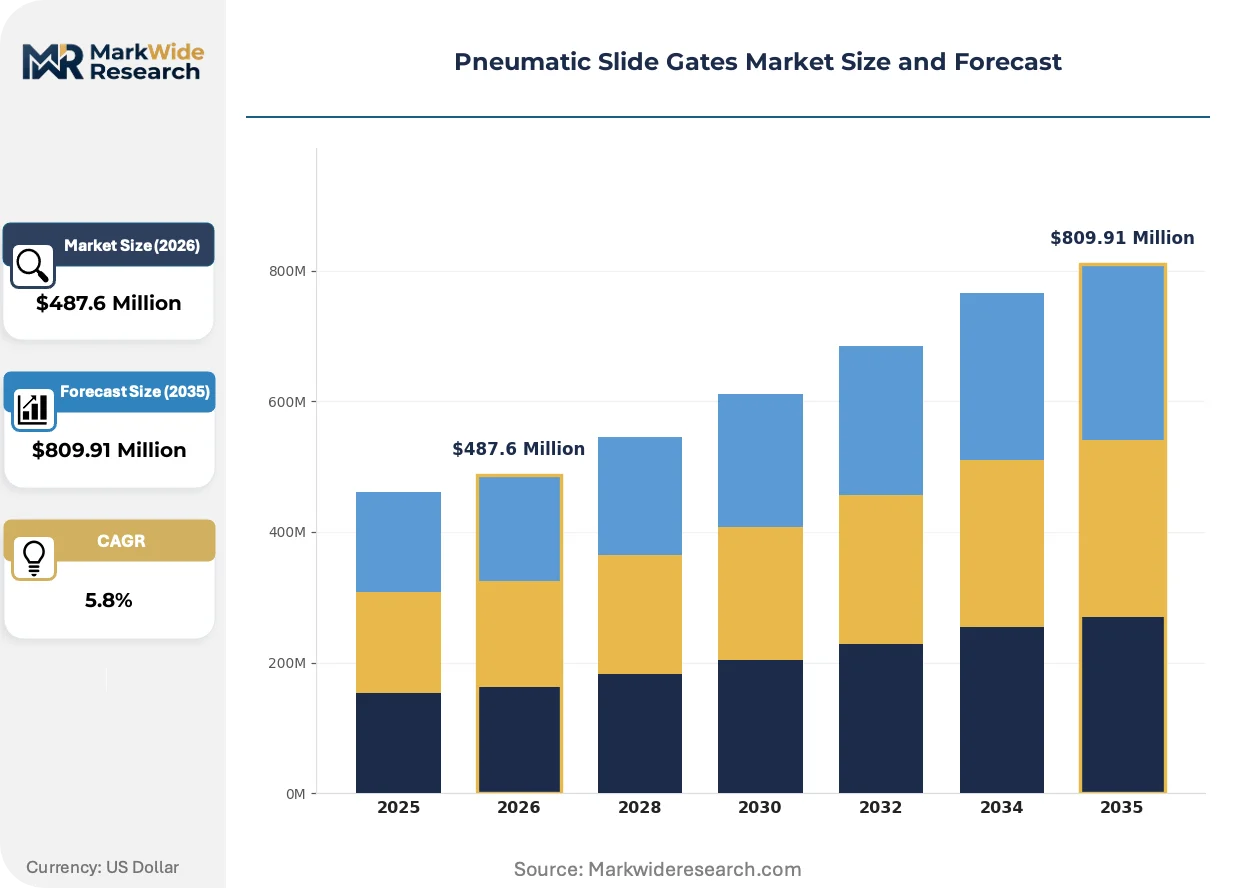
Market Dynamics
Compressed air energy efficiency mandates and electrification of pneumatic supply systems are restructuring total cost of ownership calculations for bulk material handlers specifying slide gate architectures.
Growth Catalysts
- EPA Maximum Achievable Control Technology standards:Mandates for sealed containment in pneumatic conveying lines elevate demand for zero-leakage slide gate designs in U.S. processing facilities.
- Carbon steel fabrication clusters:Regional foundries in China's industrial valve manufacturing corridor expand pneumatic actuator capacity to serve domestic bulk material infrastructure upgrades.
- Plant automation investments:Manufacturing facilities displace manual operators with automatic slide gate systems to reduce labor exposure in dust-heavy environments.
Market Restraints
- Seal elastomer input costs:ECHA REACH restrictions on chromium compounds force European manufacturers to qualify alternative chemistries, compressing margin on abrasion-resistant configurations.
- Supply concentration in heavy-duty mining:North American fabrication networks dominate severe-service applications, creating geographic dependency for high-pressure rated assemblies.
- Electrification substitution:Electric actuators displace pneumatic drives in food-grade and pharmaceutical applications where compressed air contamination risks outweigh speed advantages.
Strategic Opportunities
- Modular processing skids:Compact slide gate designs penetrate mobile material handling systems as original equipment manufacturers prioritize space-constrained integration.
- German integrated material handling systems:Schenck Process anchors European demand through slide gate assemblies bundled with complete pneumatic conveying solutions.
- ATEX directive compliance services:Certification support for explosive dust atmospheres creates attach revenue streams alongside hardware sales in chemical processing verticals.
Industry Challenges
- Pneumatic systems integration:Legacy gravity flow installations require extensive retrofit engineering to accommodate automated slide gate actuation and control architecture.
- ISO 9001 quality management certification timelines:Extended audit cycles delay market entry for regional foundries seeking access to industrialized economy procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Slide Gates Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Slide Gates, Automatic Slide Gates, Semi-Automatic Slide Gates, Compact Slide Gates Operating Pressure: Low Pressure, Medium Pressure, High Pressure, Ultra High Pressure Application: Mining Equipment, Material Handling Systems, Chemical Processing Units, Waste Management Facilities End User: Manufacturing Plants, Power Generation Facilities, Water Treatment Plants, Food Processing Companies |
| Companies Covered | Vortex Global, DMN-WESTINGHOUSE, Schenck Process, Emerson Electric, Flowserve, Weir Group, KSB, Pentair, Orbinox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Slide Gates Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are actively reconfiguring seal technology specifications while automation architectures reshape gate control integration patterns across bulk handling verticals.
Self-lubricating polymer seal compounds are replacing traditional elastomer formulations in high-temperature pneumatic slide gate applications. Mining operators in Australia and South Africa specify these materials for continuous duty cycles exceeding 200°C. Seal technology is migrating from commodity rubber compounds toward engineered polymer matrices that eliminate external lubrication systems and reduce maintenance intervals.
ECHA's REACH restrictions on hexavalent chromium compounds in seal elastomers are forcing qualification of alternative abrasion-resistant chemistries across European manufacturing. Compound suppliers must demonstrate equivalent service life under pneumatic conveying abrasion loads without regulated substances. German valve manufacturers face compressed product development timelines to maintain CE marking compliance for chemical processing exports.
Buyer specifications now unbundle after-sales service contracts from initial equipment procurement in North American bulk material handling. Engineering-procurement-construction firms negotiate separate maintenance agreements with specialized pneumatic service providers rather than original gate suppliers. This pattern concentrates most visibly in U.S. grain handling and cement processing facilities where uptime guarantees override brand loyalty in supplier selection.
Pneumatic Slide Gates Market Segmentation
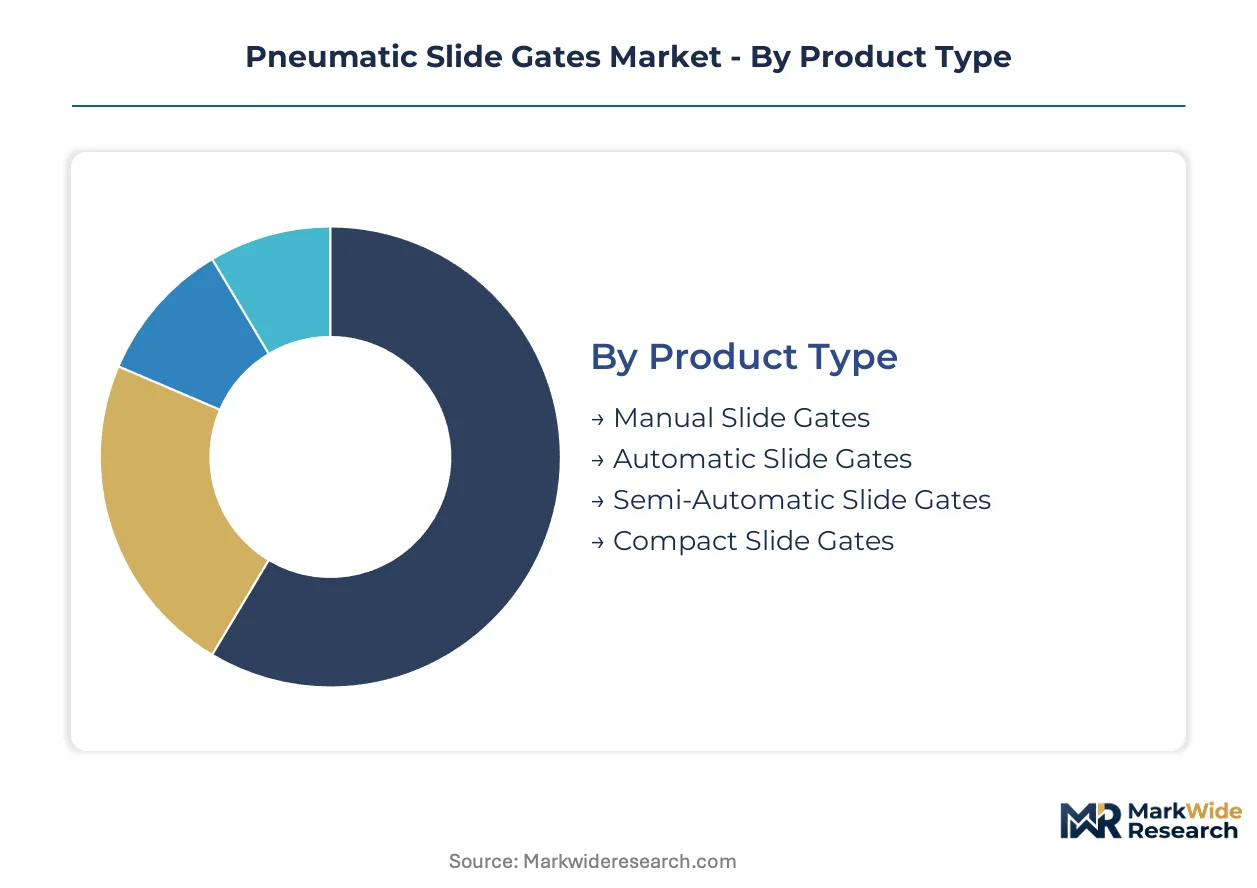
Pneumatic slide gate specification varies sharply by duty cycle intensity and automation architecture. Procurement patterns diverge between capital-intensive greenfield projects and maintenance-driven replacement cycles across bulk material handling verticals.
Product Type:
Cycle times compress fastest in automated configurations where predictive maintenance algorithms reduce unplanned downtime, while manual variants turn over slowest in legacy gravity flow installations.
- Automatic Slide Gates:Compressed air drives blade actuation through integrated solenoid valves and position feedback sensors. Manufacturing plants in Germany and the United States specify these for dust-heavy environments where OSHA exposure limits mandate operator removal from material streams.
- Compact Slide Gates:Space-constrained designs with reduced face-to-face dimensions and lightweight aluminum construction suit modular processing skids. Mobile material handling system OEMs in China integrate these for port logistics and construction aggregate processing where equipment mobility determines contract awards.
- Manual Slide Gates:Handwheel or lever-actuated shutoff for low-cycle isolation points in small-batch material handling.
- Semi-Automatic Slide Gates:Hybrid designs combining pneumatic assist with manual override for maintenance access in power generation facilities.
Automatic slide gates dominate installed base in industrialized economies. Compact variants are where expansion concentrates as OEMs prioritize space-constrained integration.
Operating Pressure:
Cost tiers stratify sharply by seal technology and actuator sizing, with ultra-high-pressure configurations commanding premium multiples due to metallurgical complexity and ATEX certification requirements.
- High Pressure:Rated to 15 bar with reinforced carbon steel bodies and PTFE-composite seals. Chemical processing units in the United States specify these for pneumatic conveying lines where EPA Maximum Achievable Control Technology standards mandate zero-leakage containment.
- Medium Pressure:5-10 bar rating with standard elastomer seals serves bulk material handling in mining equipment and cement processing where duty cycles balance abrasion resistance against capital cost.
- Low Pressure:Gravity-fed applications with minimal pneumatic assist for light-duty material isolation in food processing.
- Ultra High Pressure:Specialized metallurgy and multi-layer sealing for severe-service chemical injection and dense-phase conveying systems.
Medium-pressure configurations anchor volume shipments. High-pressure systems are climbing the fastest as emissions containment standards tighten across chemical processing verticals.
Application:
Volume concentrates in material handling systems where standardized gate dimensions enable economies of scale, while mining equipment demands custom engineering with extended lead times.
- Material Handling Systems:Integrated pneumatic conveying and gravity flow architectures in manufacturing plants. Schenck Process bundles slide gate assemblies with complete system packages for German industrial customers requiring CE-marked compliance.
- Chemical Processing Units:Corrosion-resistant stainless steel construction with specialized seal chemistries. ECHA REACH restrictions on chromium compounds force European manufacturers to qualify alternative abrasion-resistant formulations for these installations.
- Mining Equipment:Severe-service carbon steel fabrication for continuous duty in abrasive ore and aggregate processing.
- Waste Management Facilities:Sealed containment for municipal and industrial solid waste pneumatic transfer systems.
Material handling systems represent the deepest installed base. Chemical processing is gaining share fastest as emissions standards elevate sealed containment specifications.
End User:
Customer procurement maturity varies by sector, with power generation facilities emphasizing lifecycle cost models and food processing companies prioritizing quick-change seal protocols for contamination control.
- Manufacturing Plants:Broadest specification range from manual isolation gates to fully automated process control integration. China's regional foundries expand pneumatic actuator capacity to serve domestic manufacturing infrastructure upgrades.
- Power Generation Facilities:High-reliability requirements for coal handling, biomass feed systems, and flue gas treatment. Extended procurement cycles prioritize ISO 9001-certified suppliers with documented mean-time-between-failure data.
- Water Treatment Plants:Dewatered sludge and lime handling applications with moderate pressure ratings.
- Food Processing Companies:Stainless steel sanitary designs with FDA-compliant seals and rapid-clean architectures.
Manufacturing plants dominate unit demand. Power generation facilities concentrate expansion as coal-to-biomass conversions retrofit material handling infrastructure.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's bulk material throughput infrastructure anchors European demand for sealed containment systems in pneumatic conveying networks. Germany's integrated material handling corridor and China's Yangtze River Delta manufacturing belt concentrate procurement for automated slide gate architectures.
United States
Grain handling elevators along the Mississippi River corridor and cement processing facilities in the Southwest drive specification of zero-leakage slide gate designs. EPA Maximum Achievable Control Technology standards mandate sealed containment in pneumatic conveying lines at U.S. processing facilities. Houston's petrochemical fabrication cluster houses carbon steel foundries expanding capacity for high-pressure rated assemblies.
Germany
Integrated material handling system bundling and chemical processing exports sustain demand for CE-marked slide gate configurations. ECHA REACH restrictions on chromium compounds in seal elastomers force qualification of alternative abrasion-resistant chemistries. The Ruhr industrial belt hosts valve manufacturers compressing product development timelines to maintain compliance for chemical processing exports.
China
Port logistics automation and construction aggregate processing equipment sustain procurement for compact slide gate designs. GB standards for industrial valve manufacturing and MIIT pneumatic equipment regulations shape certification requirements. Zhengzhou's regional foundry cluster expands pneumatic actuator capacity to serve domestic bulk material infrastructure upgrades.
Australia
Iron ore export terminals and coal handling facilities in Western Australia specify severe-service slide gate configurations for continuous duty cycles. The country's national mining safety regulator enforces dust exposure limits that elevate automatic slide gate adoption. Perth's mining equipment engineering corridor concentrates fabrication expertise for high-temperature rated assemblies.
South Africa
Platinum group metal processing and manganese export infrastructure sustain demand for abrasion-resistant slide gate architectures. The Department of Mineral Resources and Energy enforces mine health and safety regulations that mandate operator removal from dust-heavy material streams. Johannesburg's industrial valve distribution network channels procurement toward ISO 9001-certified suppliers.
Pneumatic Slide Gates Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying standardized gate assemblies to bulk material handlers. The market structures around three tiers: multinational industrial conglomerates bundling slide gates within complete pneumatic conveying packages; mid-cap valve manufacturers with regional fabrication networks; and specialized slide gate producers focused on severe-service mining applications. Competitive moves concentrate on backward integration into seal compound formulation and geographic expansion through local foundry partnerships.
Among North American fabricators, Vortex Global occupies a position exemplifying the severe-service mining specialist archetype. Schenck Process represents the platform integrator model through its German-based integrated material handling systems. DMN-WESTINGHOUSE anchors the European component specialist tier with Netherlands-origin engineering heritage.
| Leading Market Players |
|---|
| Vortex Global |
| DMN-WESTINGHOUSE |
| Schenck Process |
| Emerson Electric |
| Flowserve |
| Weir Group |
| KSB |
| Pentair |
| Orbinox |
| Others |
Pricing and Supply Chain Analysis
REACH-driven seal elastomer chemistry restrictions determine both pricing tier spreads and supply chain shape, forcing European manufacturers to absorb reformulation costs while North American fabricators exploit zero-leakage specification premiums.
Pricing Analysis
Volume-discount tiering structures separate ATEX-certified premium configurations from standard medium-pressure assemblies and economy manual gates. Price differentiation hinges on certification grade and after-sales service bundling, with CE-marked chemical processing units commanding substantial premiums over bulk material handling specifications. Cost compression in standard elastomer tiers is intensifying because ECHA restrictions on chromium compounds have eliminated low-cost seal suppliers. Grain handling elevators in the United States exhibit highest price sensitivity, while German chemical processors prioritize lifecycle cost models over initial procurement outlays.
Supply Chain Analysis
Supplier-financing facilities have proliferated among Chinese regional foundries seeking to capture domestic infrastructure upgrade contracts. Manufacturing gravity centers on China, Germany, and the United States, with carbon steel fabrication drawing from Australian iron ore and South African manganese inputs. Single-source vulnerability concentrates in PTFE-composite seal compounds where qualified European compound suppliers face compressed development timelines. Distribution runs through engineering-procurement-construction firms that unbundle maintenance contracts from initial hardware procurement.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pneumatic slide gates market functions as a service-attach opportunity where ATEX compliance certification and predictive maintenance contracts expand faster than hardware shipments.
For Market Incumbents: Build captive seal compound formulation capabilities to defend margin pools against REACH-driven chemistry substitution. Schenck Process anchors European demand through integrated system bundling that locks out component specialists. Vortex Global sustains position in severe-service mining through North American fabrication network control. Capacity addition in China's Yangtze River Delta manufacturing belt captures domestic bulk material infrastructure upgrades. For New Entrants and Emerging Players: Establish a beachhead in compact slide gate designs for modular processing skid OEMs where space-constrained integration requirements outpace incumbent development cycles. Mobile material handling system builders in China's port logistics sector represent the most penetrable customer archetype. Aftermarket service specialization offers the cleanest go-to-market angle against bundled system providers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap valve manufacturers with regional fabrication networks and backward integration into seal technology. Long-term viability over the coming decade rests on chemistry qualification capabilities and pneumatic-electrification hybrid architectures. Acquisition targets should demonstrate ISO 9001 certification with documented mean-time-between-failure data in power generation applications. The signal to monitor is EPA enforcement intensity for Maximum Achievable Control Technology standards in U.S. chemical processing facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Compound Formulation | ECHA REACH restrictions on chromium compounds force in-house chemistry qualification to preserve margin. |
| Geographic Expansion through Local Foundry Partnerships | China's regional foundry clusters expand pneumatic actuator capacity to serve domestic bulk material handlers. |
| ATEX Compliance Certification Services | Certification support for explosive dust atmospheres creates attach revenue streams alongside hardware sales. |
| Predictive Maintenance Algorithm Development | Automated slide gate configurations reduce unplanned downtime through integrated sensor feedback systems. |
| Compact Design Portfolio Expansion | Space-constrained architectures penetrate mobile material handling systems and modular processing skids. |
Research Methodology
A spread of perspectives from maintenance directors at bulk material handling facilities, OEM procurement teams specifying slide gate assemblies, aftermarket service heads, and plant engineers converged on the working assumptions. Primary interviews combined with secondary validation from customs and trade data, SEC filings of industrial valve manufacturers, and EPA enforcement records. Bottom-up unit shipment estimates triangulated against top-down pneumatic conveying equipment market sizing.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, operating pressure tier, application vertical, and end-user procurement maturity. CAGRs were derived from weighted average growth rates across segment-specific demand drivers. Industry-specific forecast inputs incorporated EPA Maximum Achievable Control Technology enforcement trajectories and ECHA REACH restriction implementation timelines.
Sensitivities concentrate around regulatory enforcement intensity, compressed air energy efficiency mandate adoption rates, and electrification substitution patterns in food-grade applications. Forecasts reflect documented assumptions about plant automation investment cycles and regional infrastructure upgrade schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Hot Blast Valves Market
Valves
Middle East and Africa Machined Seals Market
Valves
Valve Interlocks Market
Valves
Backflow Preventers Market
Valves
Global Fluid Management Systems Market
Valves
Wind Energy Fasteners Market
Valves
North America Residential Ball Valves Market
Valves
Electro Pneumatic Positioner Market
Valves
Manual Control Valve Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Vaneometer Market
Valves
Global Gas Pressure Regulator Market
Valves
Axial and Radial Seals Market
Valves
Europe Medium Voltage Switchgear Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Valve Sack Market