
 Solar Vacuum Receiver Market | 2026-2036
Solar Vacuum Receiver Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Vacuum Receiver Market Insights
High-temperature vacuum receiver specifications is reorganizing competitive dynamics across the solar thermal supply chain. Schott leverages its borosilicate glass expertise and European manufacturing footprint to sustain premium positioning in concentrated solar power projects. Shandong Yaoguo Solar Thermal Technology anchors cost-engineered production lines serving domestic Chinese installations and export markets across Central Asia. Abengoa Solar differentiates through integrated project development capabilities that extend from receiver supply through to full plant engineering.
A solar vacuum receiver consists of a selectively coated metal absorber tube enclosed within a transparent glass envelope, with the annular space evacuated to pressures below 0.01 Pa to eliminate convective heat loss; this architecture enables operating temperatures exceeding 400°C in parabolic trough collectors while maintaining thermal efficiencies above 70% across the receiver length. The primary commercial purpose centers on converting concentrated solar irradiance into thermal energy for electricity generation, industrial process heat, and district heating networks. Parabolic trough receivers occupy the dominant installed base due to decades of operational validation in utility-scale plants, while concentrated solar power applications command the highest value per receiver unit given the extreme thermal cycling and optical precision requirements. Flat plate vacuum receivers compete in distributed commercial and residential segments where lower temperature differentials align with simpler system architectures.
FERC guidelines for renewable energy grid interconnection in the United States, the EU Green Deal's decarbonization benchmarks for industrial heat, and China's GB standards for solar thermal product certification collectively shape product qualification pathways and market access conditions across major demand centers. These frameworks elevate minimum performance thresholds, particularly for vacuum longevity and selective coating degradation rates, effectively filtering supplier participation toward vertically integrated manufacturers with in-house glass-to-metal sealing capabilities. Stakeholders must monitor evolving national renewable portfolio standards and carbon border adjustment mechanisms to anticipate which receiver specifications will unlock priority project finance.
Market Dynamics
Utility-scale concentrated solar power developers in Saudi Arabia, Morocco, and the southwestern United States are consolidating procurement around high-temperature vacuum receiver specifications above 400°C, compressing supplier margins for legacy mid-temperature designs and forcing manufacturing retooling across the supply base.
Growth Catalysts
- EU Green Deal thermal efficiency mandates:Decarbonization benchmarks for industrial heat are accelerating replacement cycles in European parabolic trough installations, creating pull-through demand for receivers with enhanced selective coatings.
- China's dual carbon goals:GB standards for solar thermal product certification are tightening vacuum longevity requirements, filtering domestic procurement toward vertically integrated manufacturers with captive glass-to-metal sealing capabilities.
- Middle East utility-scale expansion:Saudi Arabia's renewable energy procurement authority is tendering multi-gigawatt concentrated solar power blocks with explicit receiver performance guarantees, concentrating demand for proven high-temperature architectures.
Market Restraints
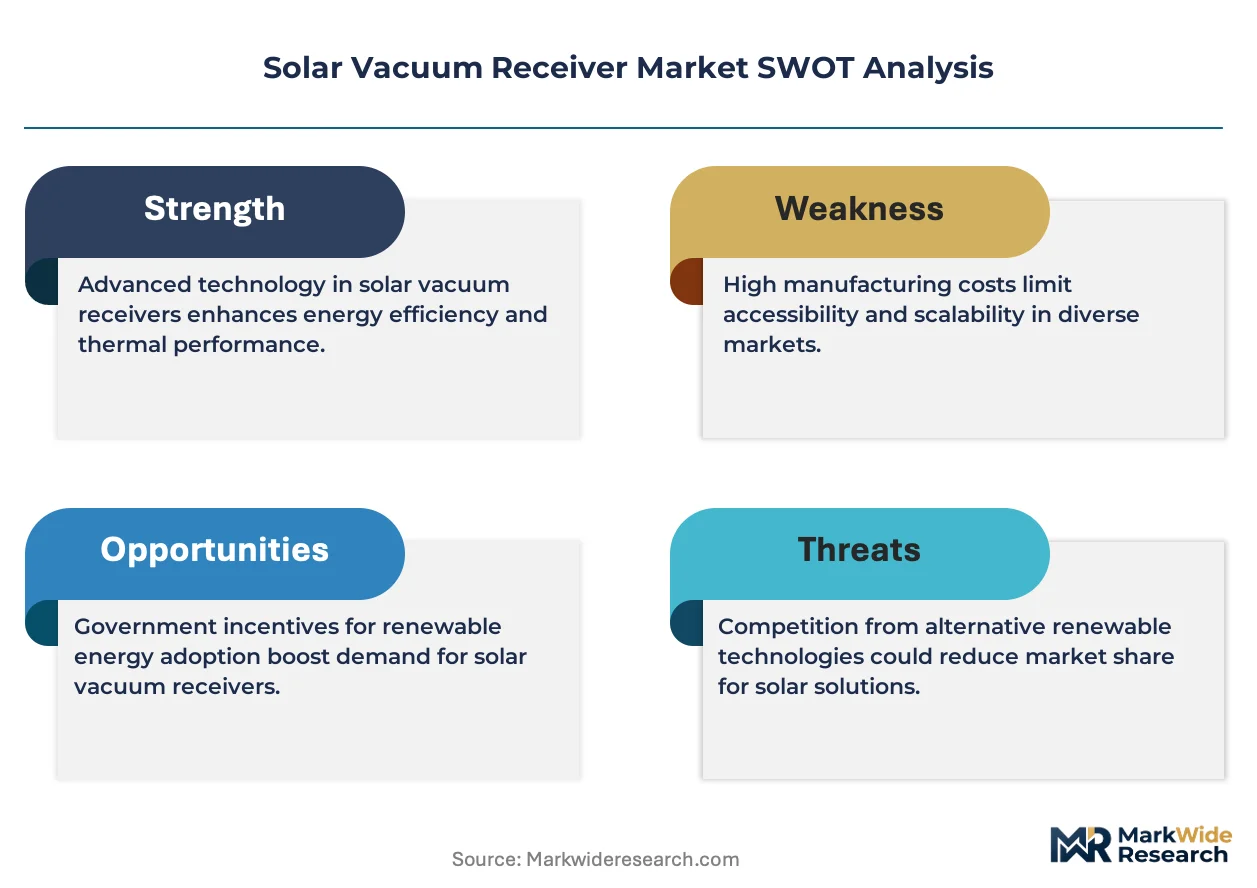
- Borosilicate glass supply concentration:European and Chinese glass manufacturers control 80% of high-transmissivity tubing output, exposing receiver assemblers to input cost volatility and allocation risk during capacity constraints.
- Selective coating degradation physics:Thermal cycling above 450°C accelerates coating delamination rates, limiting operational lifespans below 25-year project finance requirements and elevating replacement reserve calculations.
- Flat plate collector substitution:Distributed commercial and residential segments below 200°C operating temperatures are migrating toward simpler non-evacuated flat plate architectures, compressing addressable market for vacuum receivers in the building sector.
Strategic Opportunities
- Industrial process heat underpenetration:Food processing and chemical manufacturing facilities in India and Southeast Asia remain below 5% solar thermal penetration, presenting white space for medium-temperature vacuum receiver deployments.
- Hybrid concentrated solar power-photovoltaic configurations:Co-location designs with shared grid infrastructure are enabling receiver suppliers to bundle thermal storage with photovoltaic generation, accessing new project finance structures.
- US Inflation Reduction Act manufacturing credits:Domestic content bonuses for solar thermal components are incentivizing North American receiver assembly investments to serve southwestern utility-scale pipelines.
Industry Challenges
- Glass-to-metal sealing technician scarcity:Hermetic joint fabrication requires specialized vacuum brazing expertise concentrated in European and Chinese industrial clusters, constraining capacity expansion timelines for new market entrants.
- Multi-jurisdiction certification complexity:Parallel qualification pathways under FERC interconnection guidelines, EU CE marking, and China's GB standards extend product validation cycles to 18-24 months, delaying revenue recognition for novel receiver designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Vacuum Receiver Market |
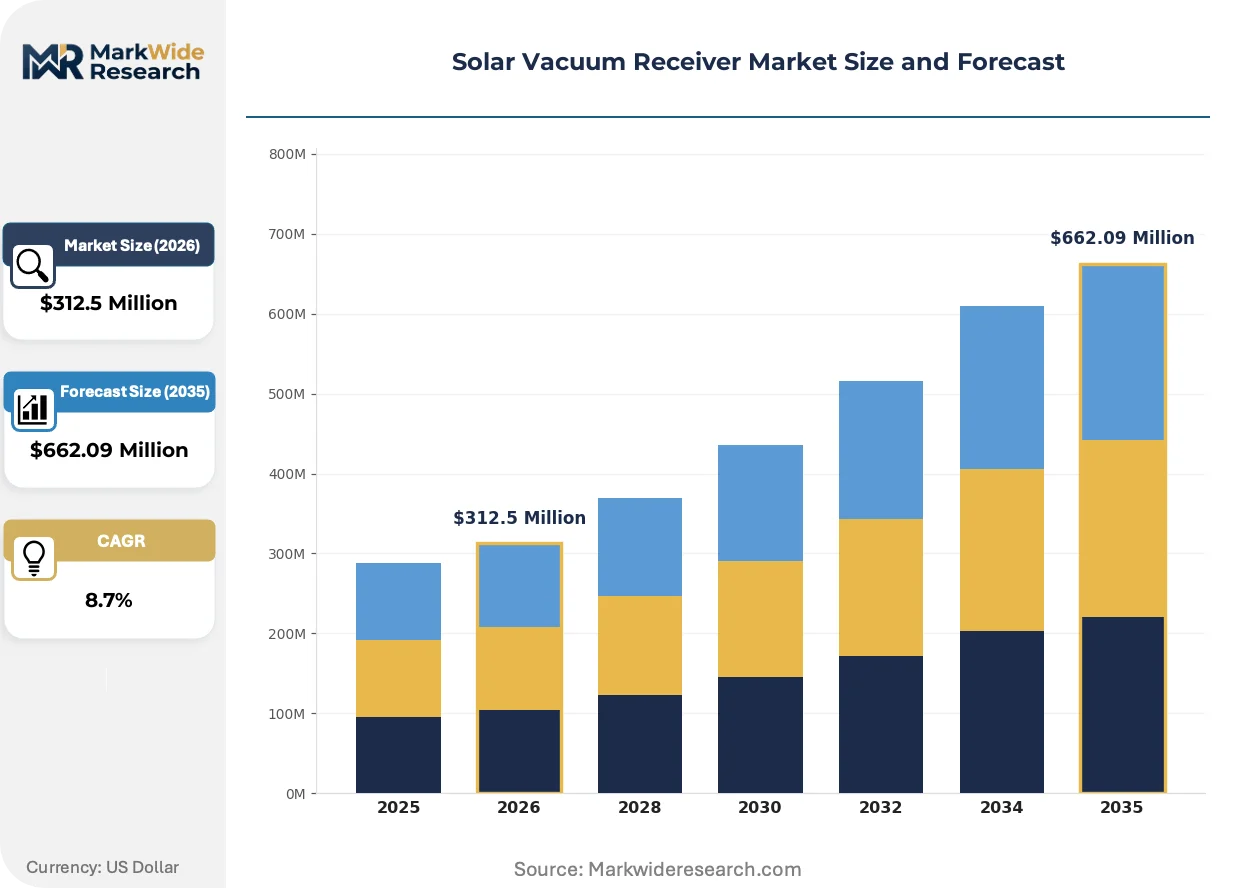
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate, Parabolic Trough, Concentrated Solar Power, Linear Fresnel Material: Glass, Metal, Polymer, Composite Application: Commercial, Industrial, Residential, Utility Technology: Vacuum Insulation, Thermal Energy Storage, Heat Transfer Fluid, Integrated Systems |
| Companies Covered | Schott, Shandong Yaoguo Solar Thermal Technology, Abengoa Solar, SolarReserve, BrightSource Energy, SCHOTT Envases Argentina S.A., Sunrain, GREENoneTEC Solarindustrie GmbH, Solimpeks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Vacuum Receiver Market Trends and Innovations
Receiver architecture evolution is compressing the performance gap between parabolic trough and power tower technologies, while regulatory frameworks are hardening qualification barriers and procurement centralization is restructuring channel economics across the supply chain.
Advanced sputtered cermet selective coatings with graded metal-ceramic composition are achieving absorptance above 96% and thermal emittance below 8% at 450°C operating temperatures. Saudi Aramco and ACWA Power are specifying these coatings in their latest concentrated solar power tenders, demanding 30-year degradation guarantees. This coating technology is supplanting older electrodeposited black chrome layers that suffered emittance drift above 400°C, effectively rendering mid-temperature receiver designs obsolete for new utility-scale procurement.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents used in receiver insulation systems, forcing manufacturers to reformulate annular space evacuation protocols and getter material specifications. Industrial heat decarbonization mandates under the EU Green Deal are accelerating this transition, as project developers face carbon border adjustment exposure on imported receivers. Spanish and Italian engineering-procurement-construction contractors are now pre-qualifying suppliers based on fluorinated gas-free manufacturing certifications.
Long-term service agreements unbundling receiver replacement from original equipment supply are emerging as the dominant contracting model in Middle Eastern markets. ACWA Power and Masdar are negotiating 15-year thermal performance guarantees with separate pricing for receiver strings, maintenance intervals, and degradation insurance. This structure is displacing traditional capital-sale contracts in Saudi Arabia and the UAE, compressing upfront equipment margins while extending supplier revenue recognition over project lifespans and elevating working capital requirements for receiver manufacturers.
Solar Vacuum Receiver Market Segmentation
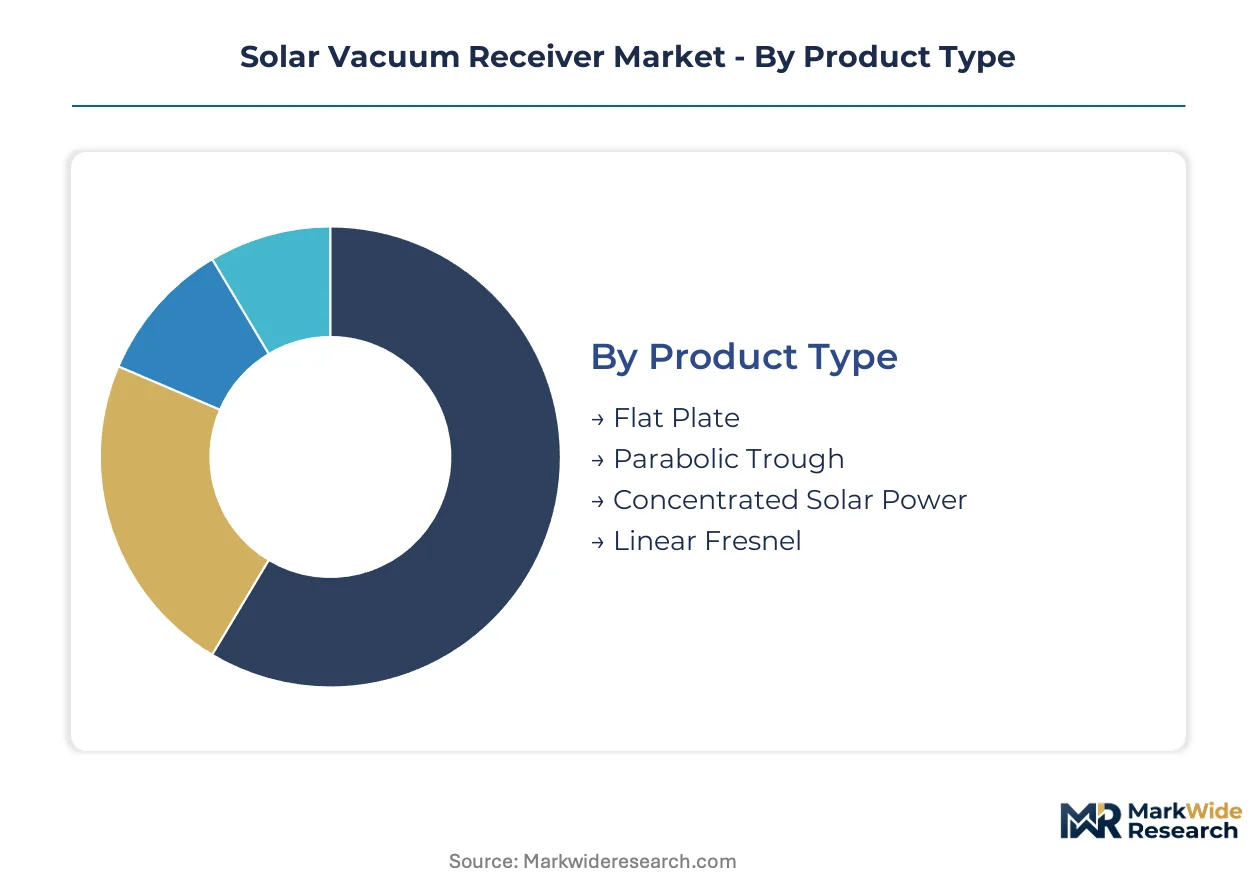
Solar vacuum receiver segmentation reveals stark margin divergences across thermal architectures and end-use applications. Procurement patterns in Saudi Arabia and the southwestern United States are compressing supplier economics for legacy designs while rewarding high-temperature specifications with premium positioning.
Product Type:
Margin pools concentrate in high-temperature architectures serving utility-scale concentrated solar power developers, where thermal cycling tolerance and optical precision command substantial price premiums over distributed commercial alternatives.
- Parabolic Trough:The dominant installed base employs evacuated annular space below 0.01 Pa surrounding selectively coated steel absorber tubes, achieving thermal efficiencies above 70% at 400°C-plus operating temperatures. ACWA Power and Masdar procurement in Saudi Arabia and the UAE is consolidating around these specifications, forcing receiver assemblers to guarantee 30-year coating degradation performance under extreme thermal cycling.
- Concentrated Solar Power:Utility-scale tower and dish configurations demand the most stringent vacuum longevity and optical precision, with Saudi Aramco tenders specifying advanced sputtered cermet coatings achieving absorptance above 96%. These receivers capture the highest value per unit given extreme service conditions and project finance scrutiny.
- Flat Plate:Non-concentrating evacuated designs serve distributed commercial and residential segments below 200°C, facing substitution pressure from simpler non-evacuated alternatives as thermal efficiency requirements moderate.
- Linear Fresnel:Fixed-mirror concentrating architectures employ simplified receiver geometries with lower optical concentration ratios, finding niche deployment in industrial process heat applications where cost engineering outweighs peak efficiency.
The dominant share belongs to Parabolic Trough, while Concentrated Solar Power is closing the gap fastest as Middle Eastern utility procurement accelerates.
Material:
Cost tier stratification separates premium borosilicate glass envelopes from commodity metal substrates, with supply concentration in European and Chinese glass manufacturers dictating input cost volatility for receiver assemblers.
- Glass:High-transmissivity borosilicate tubing from Schott and Chinese suppliers constitutes the transparent envelope enabling solar irradiance transmission with minimal reflection losses. The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents in insulation systems, forcing reformulation of annular space evacuation protocols.
- Metal:Selectively coated steel or aluminum absorber tubes form the thermal conversion core, with sputtered cermet coatings supplanting electrodeposited black chrome layers that suffered emittance drift above 400°C.
- Polymer:Experimental polymer envelopes target cost reduction in low-temperature distributed applications, though vacuum integrity and UV degradation resistance remain unresolved for commercial deployment.
- Composite:Glass-metal hybrid structures and ceramic matrix composites are emerging in research-phase receiver designs targeting power tower applications above 500°C.
Glass commands the dominant procurement volume, though Metal coating innovations are expanding margin capture fastest through performance differentiation.
Application:
Customer type determines contracting structure and revenue recognition patterns, with utility developers unbundling long-term service agreements from original equipment supply while commercial and industrial buyers favor capital-sale procurement.
- Utility:Multi-gigawatt concentrated solar power blocks in Saudi Arabia, Morocco, and the southwestern United States specify receiver performance guarantees spanning 25-30 year project finance horizons. ACWA Power and Masdar are negotiating 15-year thermal performance contracts with separate pricing for receiver strings, maintenance intervals, and degradation insurance.
- Industrial:Food processing and chemical manufacturing facilities in India and Southeast Asia remain below 5% solar thermal penetration, presenting expansion opportunity for medium-temperature vacuum receiver deployments in process heat integration.
- Commercial:Distributed commercial installations favor flat plate vacuum receivers where lower temperature differentials align with simpler system architectures and faster payback periods.
- Residential:Building-integrated solar thermal applications are migrating toward non-evacuated flat plate collectors, compressing addressable market for vacuum receivers in this segment.
Utility applications dominate absolute revenue, while Industrial process heat is expanding most quickly as decarbonization mandates tighten across manufacturing sectors.
Technology:
Technology maturity separates proven vacuum insulation architectures from emerging thermal energy storage integration, with qualification complexity under FERC, EU CE marking, and China's GB standards extending validation cycles to 18-24 months.
- Vacuum Insulation:Evacuated annular space with getter materials maintaining pressures below 0.01 Pa eliminates convective heat loss, enabling the operating temperature thresholds that distinguish receiver performance. Glass-to-metal sealing expertise concentrated in European and Chinese industrial clusters constrains capacity expansion for new entrants.
- Thermal Energy Storage:Molten salt and concrete storage integration is enabling hybrid concentrated solar power-photovoltaic configurations with shared grid infrastructure, allowing receiver suppliers to bundle thermal storage with photovoltaic generation.
- Heat Transfer Fluid:Synthetic oil, molten salt, and direct steam generation compatibility requirements shape receiver material selection and coating specifications across different plant configurations.
- Integrated Systems:Receiver-heat exchanger-collector integrated designs are emerging in engineering-procurement-construction contractor specifications, compressing supplier scope toward subsystem provision rather than component supply.
Vacuum Insulation retains the dominant installed base, though Thermal Energy Storage integration is gaining share fastest through hybrid project finance structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borosilicate glass manufacturing clusters in Germany and China control the transparent envelope supply for receiver assemblers worldwide. Utility-scale procurement concentrates in Saudi Arabia, the southwestern United States, and Spain, where project developers specify 30-year thermal performance guarantees.
United States
FERC interconnection guidelines and IRA manufacturing credits are accelerating southwestern concentrated solar power development. Arizona and California host the primary installation clusters, with developers in Mojave and Imperial Valley specifying high-temperature receivers above 400°C for molten salt storage integration.
Saudi Arabia
ACWA Power and Masdar tenders for multi-gigawatt solar blocks are consolidating procurement around advanced receiver specifications. The Kingdom's renewable energy procurement authority mandates explicit thermal performance guarantees, concentrating demand in Riyadh-led project development corridors.
China
Dual carbon goals and tightening GB standards for solar thermal certification are filtering domestic procurement toward vertically integrated manufacturers. Shandong Province anchors cost-engineered production lines serving Central Asian export markets alongside domestic installations.
Spain
EU Green Deal industrial heat decarbonization mandates and F-Gas Regulation compliance requirements are accelerating replacement cycles in Andalusian parabolic trough plants. Seville-based engineering-procurement-construction contractors now pre-qualify suppliers on fluorinated gas-free manufacturing certifications.
Morocco
Noor Ouarzazate complex expansion and subsequent utility-scale blocks are sustaining North African demand for proven high-temperature architectures. Moroccan procurement aligns with European thermal efficiency standards, creating qualification pathways for Spanish and German receiver suppliers.
Solar Vacuum Receiver Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the solar vacuum receiver supply chain. The market structure concentrates around three strategic tiers: premium European manufacturers with glass-to-metal sealing expertise, Chinese cost-engineered producers serving volume markets, and integrated project developers bundling receiver supply with plant construction. Dominant competitive moves include captive control over borosilicate glass supply and long-term service agreement structures that extend revenue recognition across project lifespans.
Among European specialists, Schott exemplifies the premium-tier archetype through its borosilicate glass heritage and manufacturing footprint. Shandong Yaoguo Solar Thermal Technology occupies the scale-driven position serving Chinese domestic and Central Asian markets. Abengoa Solar represents the integrated developer model, extending from component supply through full plant engineering.
| Leading Market Players |
|---|
| Schott |
| Shandong Yaoguo Solar Thermal Technology |
| Abengoa Solar |
| SolarReserve |
| BrightSource Energy |
| SCHOTT Envases Argentina S.A. |
| Sunrain |
| GREENoneTEC Solarindustrie GmbH |
| Solimpeks |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month qualification cycles for new receiver designs compress inventory turnover and amplify pricing power for incumbent glass-to-metal sealing specialists in Germany and China. This lead-time rigidity concentrates procurement leverage among vertically integrated manufacturers while forcing project developers to absorb premium pricing for certified high-temperature architectures.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across the solar vacuum receiver supply base, separating fluorinated gas-free certified suppliers from legacy manufacturers facing compliance retrofit costs. Pricing stratifies across premium certified, standard compliant, and economy non-certified tiers based on thermal efficiency guarantees and vacuum longevity performance. Cost compression in mid-temperature legacy designs is intensifying because Saudi Aramco and ACWA Power procurement mandates now specify 30-year degradation guarantees above 400°C. Utility-scale developers demonstrate lowest price sensitivity given project finance scrutiny, while distributed commercial installers in India and Southeast Asia prioritize capital expenditure minimization over performance premiums.
Supply Chain Analysis
Strategic stockpiling of borosilicate glass tubing dominates inventory strategy among receiver assemblers seeking insulation from European and Chinese glass manufacturer allocation constraints. Supply concentrates in Germany and China for high-transmissivity borosilicate envelopes, with selective coating chemicals sourced from specialized chemical processors in Japan and the United States. Raw material dependencies center on soda-lime and borosilicate glass formulations, sputtered cermet coating precursors, and high-purity getter materials for vacuum maintenance. Single-source vulnerability in glass-to-metal sealing technician expertise constrains capacity expansion. Distribution runs through engineering-procurement-construction contractors in Spain, Saudi Arabia, and the southwestern United States who bundle receiver procurement with plant construction contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced sputtered cermet coatings achieving absorptance above 96% are disrupting competitive positioning and compressing replacement cycles for legacy electrodeposited designs. This technological inflection, combined with tightening EU Green Deal thermal efficiency mandates, creates asymmetric growth opportunities across supplier tiers.
For Market Incumbents: Compound glass-to-metal sealing capability advantages through captive technician training programs in Shandong and Bavaria industrial clusters. Accelerate backward integration into borosilicate glass tubing production to neutralize input cost volatility from Schott and Chinese glass manufacturers. Defend against emerging Chinese cost-engineered producers by locking 15-year thermal performance guarantee contracts with ACWA Power and Masdar before qualification pathways widen.
For New Entrants and Emerging Players: Lead with industrial process heat white space in Indian food processing and Southeast Asian chemical manufacturing facilities where solar thermal penetration remains below 5%. Target medium-temperature vacuum receiver deployments between 200-350°C where certification complexity is lower and incumbent pricing premiums are less entrenched. Pursue joint venture structures with established engineering-procurement-construction contractors to bypass 18-24 month standalone qualification timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial glass manufacturers with dormant solar thermal receiver divisions and intact sealing expertise. Long-term viability hinges on positioning for post-2030 concentrated solar power expansion as photovoltaic saturation elevates thermal storage value. Monitor Saudi Arabia renewable energy procurement authority tender announcements as the inflection signal for multi-gigawatt demand blocks.
| Strategic Initiative | Industry Significance |
|---|---|
| Glass-to-Metal Sealing Capability Expansion | Captive vacuum brazing expertise in European and Chinese industrial clusters locks in supplier tier positioning. |
| Sputtered Cermet Coating Scale-Up | Absorptance above 96% at 450°C meets Saudi Aramco 30-year degradation guarantee requirements. |
| Backward Integration into Borosilicate Glass | Control over high-transmissivity tubing supply neutralizes allocation risk from Schott and Chinese manufacturers. |
| Long-Term Service Agreement Structuring | 15-year thermal performance contracts with ACWA Power extend revenue recognition and elevate working capital barriers. |
| Industrial Process Heat Market Development | Food processing and chemical manufacturing penetration in India and Southeast Asia opens medium-temperature white space. |
Research Methodology
A spread of perspectives from concentrated solar power project developers, engineering-procurement-construction contractors, receiver manufacturing engineers, and glass-to-metal sealing technicians converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FERC interconnection filings, EU CE marking databases, Chinese GB standard certification records, and IEA concentrated solar power project tracking data. Bottom-up unit economics from receiver bill-of-materials analysis were triangulated against top-down market sizing from utility-scale procurement pipelines.
Segmentation dimensions modeled span product type, material composition, end-use application, and technology integration across the projection horizon. The analytical framework incorporated parabolic trough, concentrated solar power tower, flat plate, and linear Fresnel architectures with vacuum insulation and thermal energy storage variants. CAGRs were derived from project development pipeline velocity, replacement cycle acceleration from regulatory mandates, and penetration assumptions for industrial process heat applications. Forecast inputs included Saudi Arabia renewable energy procurement authority tender schedules, EU F-Gas Regulation phase-down timelines, and US Inflation Reduction Act domestic content bonus qualification pathways.
Forecasts assume regulatory continuity in EU Green Deal implementation, Chinese dual carbon goal enforcement, and FERC interconnection guideline stability; material policy shifts would require re-modeling. Revision becomes warranted when Saudi Aramco or ACWA Power tender specifications cross thermal performance thresholds that obsolete incumbent coating technologies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Argentina Solar Energy Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
PV Array Combiner Box Sales Market