
 One-Way Valve Market | 2026-2036
One-Way Valve Market Size, Share, and Industry Trends Forecast 2026-2036
One-Way Valve Market Intelligence
Premium alloy specifications for sour gas service is decoupling from commodity brass and plastic alternatives in pricing and procurement criteria. Flowserve Corporation leverages its forged steel foundry network to anchor high-margin positions in subsea and LNG applications. Emerson Electric Co. sustains technology leadership through digital valve monitoring platforms that integrate with distributed control systems. SLB competes aggressively in Middle Eastern upstream contracts by controlling local service infrastructure and aftermarket parts logistics.
A one-way valve permits fluid flow in a single direction while automatically preventing reverse flow, typically achieving shutoff through gravity, spring force, or line pressure acting on a disc, ball, or elastomeric diaphragm seated against a precision-machined orifice; operating pressures range from near-vacuum conditions to exceeding 10,000 psi in subsea hydrocarbon extraction. Check valves dominate volume across water supply and HVAC installations where low cost and minimal maintenance override precision requirements, while diaphragm valves capture disproportionate margin in pharmaceutical and food processing lines where crevice-free surfaces and CIP compatibility command specification premiums. Ball valves lead replacement cycles in chemical processing as operators prioritize zero-leakage stem seals under API 6D and ISO 17292 testing protocols.
API 6D pipeline valve standards, ISO 17292 floating ball valve specifications, and EPA lead-free plumbing product mandates under the Safe Drinking Water Act collectively shape material selection, testing documentation, and market access eligibility across North American and European procurement channels. China's SAMR enforces GB/T national standards for urban water supply valves that increasingly reference stainless steel corrosion resistance metrics aligned with ISO 7005 flange dimensions. Stakeholders must monitor divergence between API's evolving fugitive emissions testing protocols and EU Ecodesign requirements for energy-related products, as misalignment threatens to fragment qualification costs for manufacturers serving both regulatory spheres.
Market Dynamics
Stainless steel specification upgrades in wastewater infrastructure are forcing foundries to retool casting lines while petrochemical operators in China's Ningbo corridor demand API 6D-certified high-pressure assemblies at accelerating volumes.
Growth Catalysts
- EU Urban Wastewater Treatment Directive revisions:German utilities must replace legacy cast iron with corrosion-resistant stainless steel check valves, triggering replacement cycles across municipal procurement networks.
- Japan MEE water quality benchmarks:Japanese treatment plants face mandatory effluent nitrogen reduction targets that require precision flow control and redundant valve isolation systems.
- Subsea hydrocarbon extraction depths:Extended-reach drilling below 3,000 meters demands forged steel valve bodies rated for 10,000+ psi operating pressure with sour gas metallurgy.
Market Restraints
- Nickel alloy input volatility:Super duplex and Inconel specifications for sour gas service expose valve manufacturers to London Metal Exchange price swings that compress margin on fixed-price contracts.
- Foundry capacity concentration:Premium forged steel forging for subsea applications concentrates among North American and European tier-one suppliers, creating 18-24 month lead time bottlenecks.
- Plastic check valve substitution:Polypropylene and PVDF alternatives capture HVAC and residential water supply volume where pressure ratings below 150 psi permit polymer construction.
Strategic Opportunities
- Saudi Aramco upstream expansion:Master Gas System Phase II and Jafurah unconventional gas development create demand for 50,000+ wellhead valves with local content requirements.
- Digital valve monitoring convergence:Integration of acoustic emission sensors with distributed control systems enables predictive maintenance contracts that capture 15-year lifecycle revenue.
- India Jal Jeevan Mission rural water supply:Federal mandate to connect 190 million rural households requires millions of low-cost brass and thermoplastic check valves with BIS certification.
Industry Challenges
- API 6D fugitive emissions testing backlog:Third-party certification laboratories face 6-9 month queue delays that stall product launches for pipeline valve manufacturers.
- Legacy DCS integration complexity:Digital valve positioners must communicate via HART, Foundation Fieldbus, and proprietary protocols simultaneously, requiring firmware customization per end-user.
- Welding technician scarcity:Orbital welding certification for hygienic diaphragm valve installation in pharmaceutical lines commands 40% wage premiums that inflate project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | One-Way Valve Market |
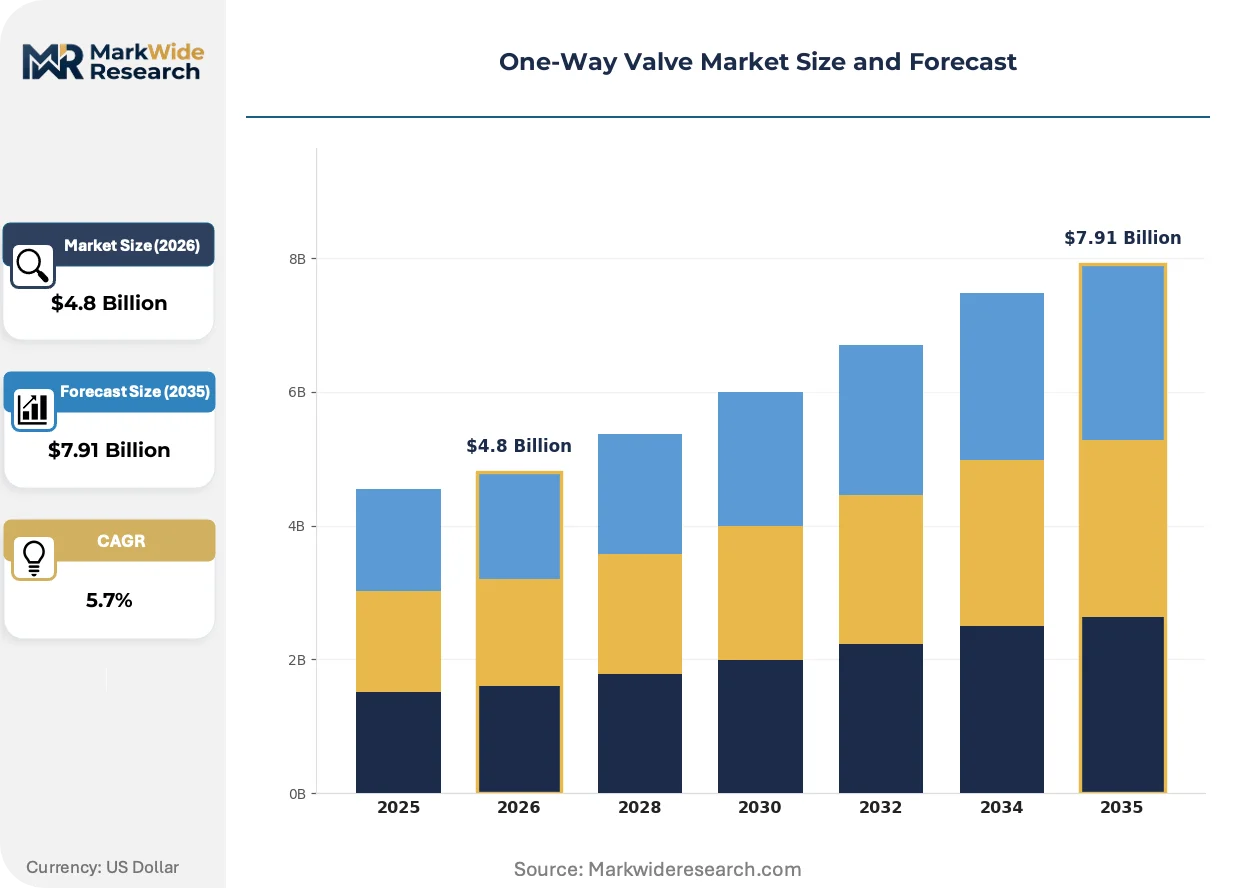
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valve, Check Valve, Diaphragm Valve, Duckbill Valve Material: Plastic, Stainless Steel, Brass, Rubber Application: Water Supply, HVAC Systems, Chemical Processing, Food Processing End User: Municipal, Industrial, Residential, Commercial |
| Companies Covered | AVK UK Ltd, SPX FLOW Inc., Emerson Electric Co., DHV Industries Inc., The Weir Group PLC, Flowserve Corporation, SLB, PetrolValves S.p.A., CIRCOR International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
One-Way Valve Market Strategic Shifts & Innovations
Electrification of valve actuation systems is compressing pneumatic infrastructure requirements while smart diagnostics embed directly into valve bodies. Material science advances in additive manufacturing are reshaping prototyping timelines for complex flow geometries.
Additive manufacturing of titanium valve bodies is electrifying rapid prototyping for subsea choke valve geometries that conventional five-axis machining cannot produce economically. Baker Hughes and SLB now print production-grade Inconel 718 trim components for wellhead applications, collapsing lead times from 26 weeks to 10 days. This capability is compressing competitive differentiation around design iteration speed rather than foundry scale.
EPA's evolving fugitive emissions testing protocols under New Source Performance Standards are forcing valve manufacturers to redesign packing systems and document methane leakage rates below 100 ppm. The rule tightens most aggressively on natural gas transmission pipelines and storage facilities, compelling operators to specify low-emission ball valves with live-loaded stem seals. European manufacturers serving both EPA and EU Ecodesign jurisdictions face diverging test methodologies that fragment qualification investments.
Buyer consolidation among integrated supermajors is concentrating procurement authority into centralized technical standards teams that unbundle valve supply from installation and commissioning services. ExxonMobil and Shell now specify valve-plus-digital-twin packages that require suppliers to deliver 3D models and predictive maintenance algorithms, displacing traditional distributor channels in the Gulf of Mexico and North Sea. This pattern is most visible in LNG liquefaction train projects where single-source accountability reduces interface risk.
One-Way Valve Market Segmentation
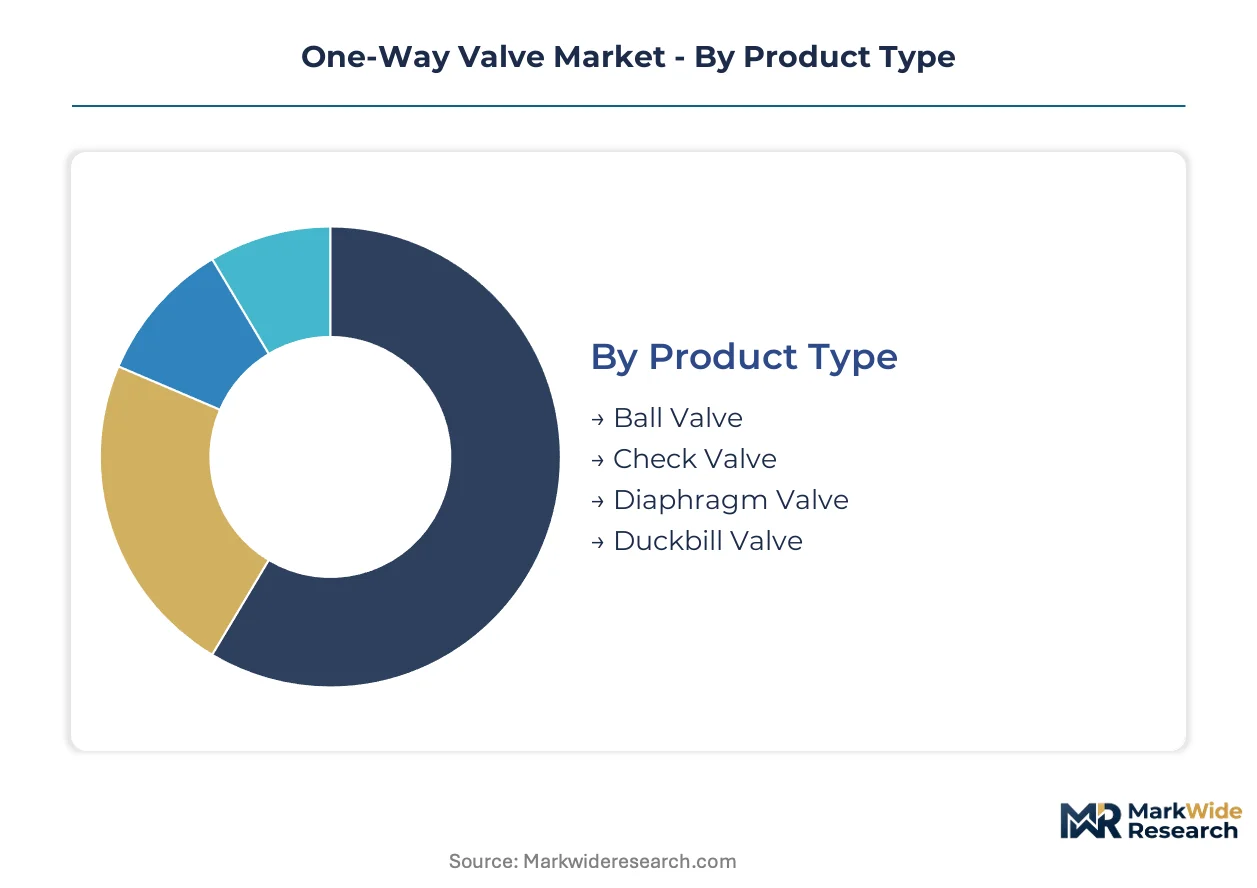
One-way valve procurement splits sharply between specification-driven industrial buyers and cost-sensitive residential contractors, with certification requirements determining market access eligibility across each segment boundary. Material selection and pressure rating specifications cascade through product type choices, creating distinct competitive arenas that rarely overlap.
Product Type:
API 6D certification governs pipeline ball valves, while FDA compliance dominates diaphragm valve specifications for hygienic applications; check valves face municipal procurement standards that vary by water authority.
- Ball Valve:Forged steel or cast body construction with floating or trunnion-mounted ball designs achieves zero-leakage shutoff through spring-loaded stem seals tested to API 6D protocols. Demand concentrates in China's Ningbo petrochemical corridor where state-backed refinery expansions require high-pressure assemblies rated for sour gas service.
- Check Valve:Swing, lift, and silent check configurations use gravity or spring-assisted discs to prevent reverse flow in water distribution and hydrocarbon transport systems. German wastewater treatment utilities are replacing legacy cast iron models with stainless steel variants under EU Urban Wastewater Treatment Directive revisions.
- Diaphragm Valve:Elastomeric diaphragm isolates working fluid from mechanical components, enabling crevice-free surfaces essential for CIP protocols in pharmaceutical manufacturing.
- Duckbill Valve:Molded elastomer sleeve opens under forward pressure and seals against backflow through its self-acting geometry, serving low-pressure drainage and marine applications.
Check valves sit at the top of the volume ranking, with ball valves climbing the fastest.
Material:
Cost tiers separate commodity polymers from premium alloys, with nickel price volatility compressing margins on fixed-price super duplex contracts.
- Plastic:Polypropylene and PVDF formulations deliver corrosion resistance at sub-150 psi ratings for HVAC condensate and residential water supply where metal alternatives over-specify. Polymer substitution is accelerating in cost-sensitive segments as injection molding scales drive unit economics below brass equivalents.
- Stainless Steel:Austenitic and duplex grades provide chloride corrosion resistance for seawater intake, chemical processing, and food contact applications requiring surface finish documentation. Japanese treatment plants specify 316L and super duplex for MEE-mandated nitrogen reduction systems.
- Brass:Lead-free alloys meeting EPA Safe Drinking Water Act mandates dominate North American residential plumbing through compression and sweat joint configurations.
- Rubber:EPDM, nitrile, and fluorocarbon elastomers form diaphragms, duckbill sleeves, and valve seats selected for chemical compatibility and temperature exposure.
Brass commands the largest installed base, though stainless steel is gaining share fastest in wastewater and chemical processing conversions.
Application:
Precision requirements and maintenance access determine whether commodity check valves suffice or specification premiums justify diaphragm and ball valve investments.
- Water Supply:Municipal distribution networks specify resilient-seated gate valves and swing check valves for pump station protection, with ductile iron and stainless steel competing on lifecycle cost models. India's Jal Jeevan Mission rural connection mandate is driving volume for low-cost brass and thermoplastic check valves with BIS certification.
- HVAC Systems:Chilled water and steam distribution employ silent check valves and bronze-body ball valves where pressure ratings below 300 psi permit lighter construction. Commercial building codes in multiple jurisdictions are tightening energy efficiency standards that favor low-pressure-drop valve designs.
- Chemical Processing:PTFE-lined ball valves and alloy-bodied check valves resist aggressive media while meeting ISO 17292 leakage test protocols.
- Food Processing:3A sanitary standards and EHEDG guidelines mandate diaphragm valves with surface finishes below 0.8 micrometers Ra for dairy and beverage lines.
Water supply dominates current procurement volume, while food processing exhibits the steepest expansion trajectory as hygienic specification premiums attract specialized suppliers.
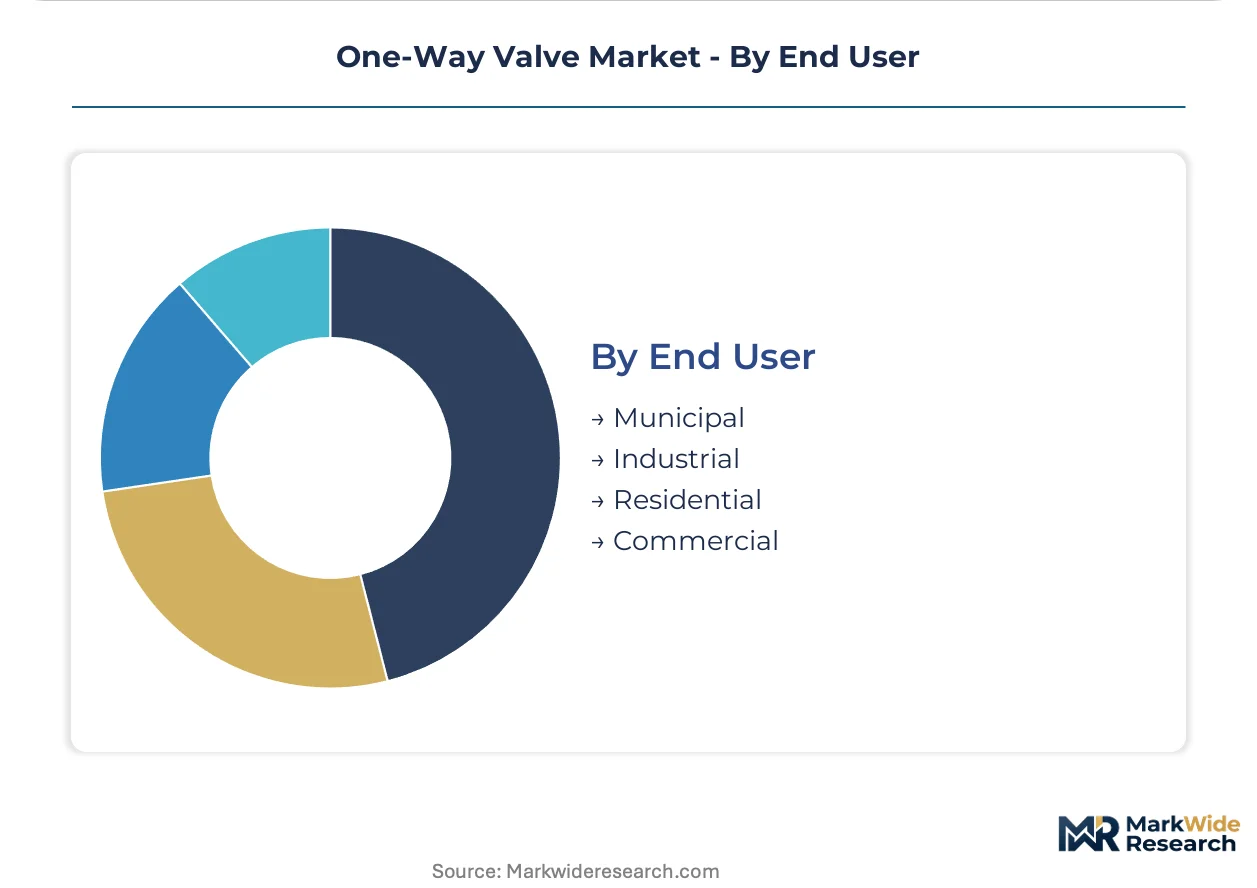
End User:
Procurement authority concentrates differently across segments: municipal buyers run competitive bidding, industrial operators bundle valve supply with digital monitoring packages, and residential demand flows through distributor channels.
- Municipal:Water and wastewater utilities specify corrosion-resistant check valves for pump stations and treatment plants, with EU directive compliance forcing stainless steel upgrades in German networks. Public procurement cycles extend 12-18 months but anchor long-term maintenance contract revenue.
- Industrial:Petrochemical, pharmaceutical, and power generation operators prioritize API-certified ball valves and hygienic diaphragm valves with predictive maintenance integration. ExxonMobil and Shell now require valve-plus-digital-twin packages that displace traditional distribution channels.
- Residential:Plumbing contractors select brass and thermoplastic check valves based on local code compliance and distributor availability, with lead-free mandates shaping material specifications.
- Commercial:Building owners and facility managers balance first cost against energy efficiency in HVAC valve selection, with smart building integration emerging as a specification factor.
Municipal procurement generates the highest absolute volume, though industrial end users are expanding fastest as digital valve monitoring converges with predictive maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized foundry technicians and orbital welding specialists concentrate in Germany's Ruhr industrial belt, Japan's Chubu region, and the US Gulf Coast petrochemical corridor, anchoring premium valve fabrication capacity.
Germany
Wastewater treatment utilities in North Rhine-Westphalia and Bavaria are replacing legacy cast iron check valves with super duplex stainless steel variants. The EU Urban Wastewater Treatment Directive revisions mandate corrosion-resistant specifications for effluent compliance. Municipal procurement networks in the Ruhr industrial belt are triggering 12-18 month replacement cycles.
China
State-backed refinery expansions in the Ningbo-Shanghai petrochemical corridor demand API 6D-certified high-pressure ball valve assemblies. SAMR enforces GB/T national standards for urban water supply valves with stainless steel corrosion resistance metrics. Local fabricators in Zhejiang province are scaling forged steel foundry capacity to meet sour gas service requirements.
Japan
MEE water quality benchmarks are forcing treatment plants in the Chubu and Kansai regions to install precision flow control systems with redundant valve isolation. Nitrogen reduction targets require 316L and super duplex specifications for coastal facilities. Yokohama-based engineering contractors are bundling valve procurement with predictive maintenance contracts.
United States
EPA fugitive emissions testing protocols under New Source Performance Standards are compelling natural gas transmission operators to specify low-emission ball valves. The Gulf Coast petrochemical corridor anchors demand for forged steel bodies rated for 10,000+ psi subsea applications. Houston-based distributors are consolidating procurement authority for valve-plus-digital-twin packages.
Saudi Arabia
Master Gas System Phase II and Jafurah unconventional gas development are creating demand for wellhead valves with local content requirements. The country's national oil company mandates in-country value thresholds for upstream contracts. Eastern Province fabrication yards are expanding orbital welding capacity for sour gas metallurgy.
One-Way Valve Market Key Industry Players
Top-tier vendors anchor premium alloy specification tiers, while mid-scale fabricators compete on municipal procurement cycles and distributor channel access. The vendor base stratifies around three strategic archetypes: integrated supermajors with digital monitoring platforms, forged steel specialists with captive foundry networks, and regional brass valve fabricators serving residential plumbing codes. Dominant competitive moves include backward integration into alloy foundry capacity and technology licensing for predictive maintenance algorithms.
Among US-based industrial conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify the integrated platform archetype, while SLB occupies a position bridging subsea fabrication and digital service infrastructure. PetrolValves S.p.A. represents the European forged steel specialist tier, and AVK UK Ltd sits within the municipal water supply specification segment. These anchors illustrate how competitive positioning decouples between specification-driven industrial procurement and cost-sensitive residential distribution channels.
| Leading Market Players |
|---|
| AVK UK Ltd |
| SPX FLOW Inc. |
| Emerson Electric Co. |
| DHV Industries Inc. |
| The Weir Group PLC |
| Flowserve Corporation |
| SLB |
| PetrolValves S.p.A. |
| CIRCOR International, Inc. |
| Others |
Cost & Logistics Intelligence
EU Urban Wastewater Treatment Directive revisions are compelling German utilities to specify super duplex stainless steel check valves, forcing foundries to absorb nickel alloy cost volatility while petrochemical buyers in China's Ningbo corridor consolidate procurement into long-term offtake contracts that compress spot-market pricing power.
Pricing Analysis
Valve-plus-digital-twin bundling by ExxonMobil and Shell is unbundling traditional distributor markups from specification premiums. Three-tier pricing structure across API-certified forged steel, municipal-grade stainless steel, and commodity brass-thermoplastic separates procurement channels by certification burden. Cost compression in polymer alternatives is intensifying because injection molding scales erode brass unit economics. Residential plumbing contractors exhibit highest price sensitivity; subsea operators accept premium positioning for sour gas metallurgy.
Supply Chain Analysis
Saudi Aramco's local content mandates and India's BIS certification requirements are reshaping sourcing patterns toward in-country fabrication. Premium forged steel capacity concentrates in Germany, Japan, and the United States Gulf Coast. Supply chains draw from nickel alloy feedstock, elastomer diaphragm compounds, and precision-machined trim components. Single-source vulnerability sits with North American and European tier-one foundries for subsea applications. Distribution runs through engineering-procurement-construction contractors for industrial projects and wholesale distributors for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where specification premiums in German wastewater and Saudi upstream contracts offset margin compression in commoditized residential brass valves.
For Market Incumbents: Anticipate additive manufacturing disruption by securing titanium and Inconel powder supply agreements before SLB and Baker Hughes consolidate print-service networks. Defend position by deepening backward integration into super duplex foundry capacity in the Ruhr industrial belt. Certification investment in API 6D fugitive emissions protocols anchors access to pipeline valve procurement cycles. For New Entrants and Emerging Players: Additive manufacturing of complex flow geometries offers a technology-first wedge into subsea choke valve prototyping where conventional machining cannot compete. Target India's Jal Jeevan Mission rural water supply for low-cost brass and thermoplastic check valves with BIS certification. Pursue direct contracting with Yokohama-based engineering contractors bundling predictive maintenance services. For Investors and Strategic Acquirers: Asymmetric upside sits with regional brass valve fabricators possessing distributor channel control and lead-free EPA compliance. Five-to-ten year viability hinges on digital valve monitoring convergence capturing lifecycle revenue. Watch for API 6D certification laboratory queue delays as inflection signal for qualified-manufacturer scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forged Steel Foundry Capacity | Captive supply of super duplex bodies insulates margin from London Metal Exchange nickel volatility. |
| Digital Valve Monitoring Platform Development | Acoustic emission sensor integration with Emerson-style distributed control systems locks in predictive maintenance contracts. |
| API 6D Fugitive Emissions Certification Investment | EPA New Source Performance Standards compliance opens natural gas transmission pipeline procurement channels. |
| Additive Manufacturing Capability Buildout | Inconel 718 print production collapses subsea choke valve lead times from forged-steel foundry bottlenecks. |
| Local Content Joint Venture in Saudi Eastern Province | Aramco in-country value thresholds mandate fabrication yard partnerships for wellhead valve contracts. |
Research Approach
Multiple input streams — primary interviews with valve procurement managers at German wastewater utilities and Saudi Aramco engineering teams, secondary validation through API certification databases and SAMR GB/T standard filings, and trade data from customs records — were reconciled through bottom-up and top-down triangulation. Plant engineers at Ningbo petrochemical facilities, aftermarket service heads at Gulf Coast distributors, and municipal procurement officers in North Rhine-Westphalia provided operational context. SEC 10-K disclosures from Emerson and Flowserve, EIA energy infrastructure reports, and EU Urban Wastewater Treatment Directive implementation timelines furnished secondary anchors.
Data-stream reconciliation across product type, material grade, application severity, and end-user procurement authority dimensions shaped the analytical framework. Modeled segments spanned ball valve, check valve, diaphragm valve, and duckbill valve categories crossed with stainless steel, brass, plastic, and rubber material tiers. CAGRs were derived from installed base replacement cycles and greenfield project pipelines across the projection horizon. Forecast inputs incorporated nickel alloy price volatility assumptions and digital valve monitoring adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to API 6D fugitive emissions testing protocol divergence between EPA and EU Ecodesign jurisdictions. Foundry capacity concentration in subsea applications and orbital welding technician scarcity for pharmaceutical installations represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Hot Blast Valves Market
Valves
Sandblast Valves Market
Valves
Pneumatic Positioner Market
Valves
Hybrid Valve Market
Valves
Pressure Reducing Valve Market
Valves
Liner Regulators Market
Valves
Blasting Stemming Plugs Market
Valves
Pipeline and Process Services Market
Valves
Refrigeration Valves Market
Valves
Global Automotive Valves Market
Valves
Steam Trap Valve Market
Valves
Penstock Market
Valves
Aerospace Valves Market
Valves
Angle Opening Ball Locator Market
Valves
Pipeline Equipment Market
Valves
China Explosion-Proof Equipment Market