
 Pigging Valves Market | 2026-2036
Pigging Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Pigging Valves Market Analysis
North American specialty valve foundries is rebalancing capacity toward pigging-specific configurations as pipeline integrity mandates tighten. Hartmann Valves GmbH leverages its precision-machining heritage to dominate European offshore pipeline retrofits. SAMSON Controls Inc. sustains a broad automation-integrated portfolio that anchors its position in chemical processing applications. Frontier Valve International specializes in severe-service metallurgy for sour gas environments, differentiating its offering from standard commodity valves.
Pigging valves are process isolation devices engineered with full-bore through-conduit geometry and dual-seal integrity to allow mechanical scrapers, gauges, or cleaning pigs to pass without flow restriction, typically rated for pressures exceeding ANSI Class 600 and temperatures from cryogenic to elevated service. Ball valve configurations occupy the largest installed base due to their bidirectional sealing reliability and lower operating torque requirements in automated pipeline stations. Stainless steel material grades command premium positioning in corrosive hydrocarbon service, while carbon steel variants compete aggressively on total cost in water transmission and standard crude oil gathering systems.
PHMSA pipeline safety regulations in the United States, the EU Pressure Equipment Directive, and Saudi Aramco engineering standards collectively mandate traceable material certification and pressure-testing documentation for all inline isolation assets. These compliance layers extend procurement cycles but protect incumbent suppliers with established quality management systems. Stakeholders must monitor evolving hydrogen blending specifications in European pipeline networks, as embrittlement-resistant metallurgy will reshape material selection criteria and qualification protocols for next-generation pigging valve designs.
Market Dynamics
Pipeline integrity mandates from PHMSA and comparable regulators in Germany and Saudi Arabia are compelling asset owners to replace legacy isolation infrastructure with automated pigging systems that reduce downtime and satisfy traceability requirements.
Growth Catalysts
- PHMSA Safety Regulations:Mandatory inline inspection intervals and pressure-testing documentation accelerate replacement cycles for aging valve assets across United States transmission networks.
- Hydrogen Blending Specifications:European pipeline operators are qualifying embrittlement-resistant metallurgies for dual-service natural gas and hydrogen transport, creating specification upgrades.
- Offshore Retrofit Cycles:North Sea and Gulf of Mexico brownfield projects require specialized subsea pigging valve configurations with extended design life.
Market Restraints
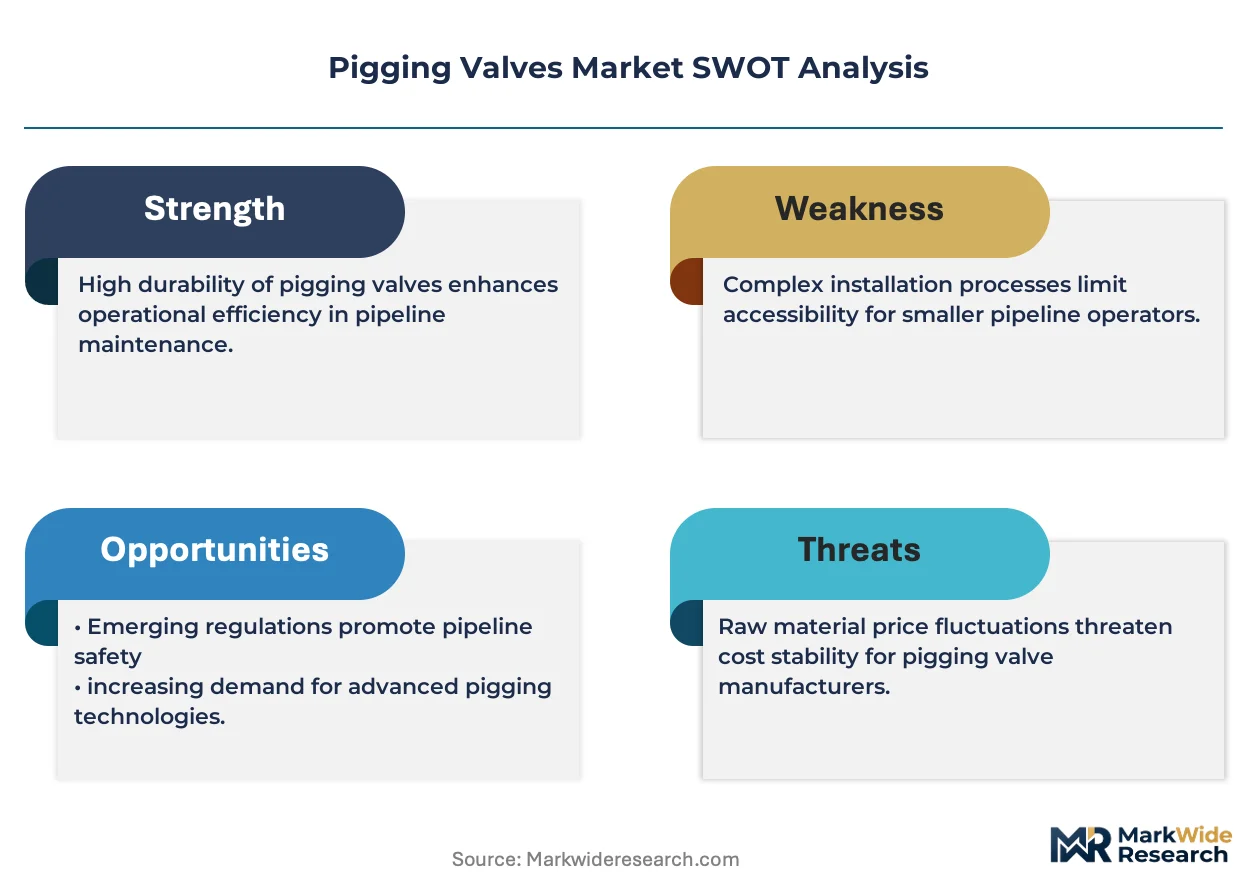
- Nickel Alloy Price Volatility:Sour service specifications depend on Inconel and duplex stainless grades subject to mining supply disruptions and tariff exposure.
- Foundry Capacity Concentration:Large-bore forging capacity for ANSI Class 900+ ratings concentrates in United States Gulf Coast and German industrial clusters, creating queue bottlenecks.
- Extended Qualification Timelines:Saudi Aramco engineering standards and EU Pressure Equipment Directive certification cycles stretch procurement lead times to 18-24 months.
Strategic Opportunities
- CCUS Injection Networks:Carbon capture projects in Norway and Netherlands require corrosion-resistant pigging valves for supercritical CO2 transport.
- Modular Skid Integration:Pre-fabricated pipeline station designs are compressing field welding requirements and favoring flange-ready valve assemblies.
- India Pipeline Expansion:The Petroleum and Natural Gas Regulatory Board's city gas distribution mandates are creating demand for standardized 6-inch and 8-inch pigging valve configurations.
Industry Challenges
- Weld Procedure Qualification:ASME Section IX and API 1104 compliance for sour service applications requires specialized welder certification that outstrips training pipeline capacity.
- Legacy System Integration:Brownfield automation retrofits must reconcile pneumatic actuator signals with digital control architectures without triggering full station shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigging Valves Market |
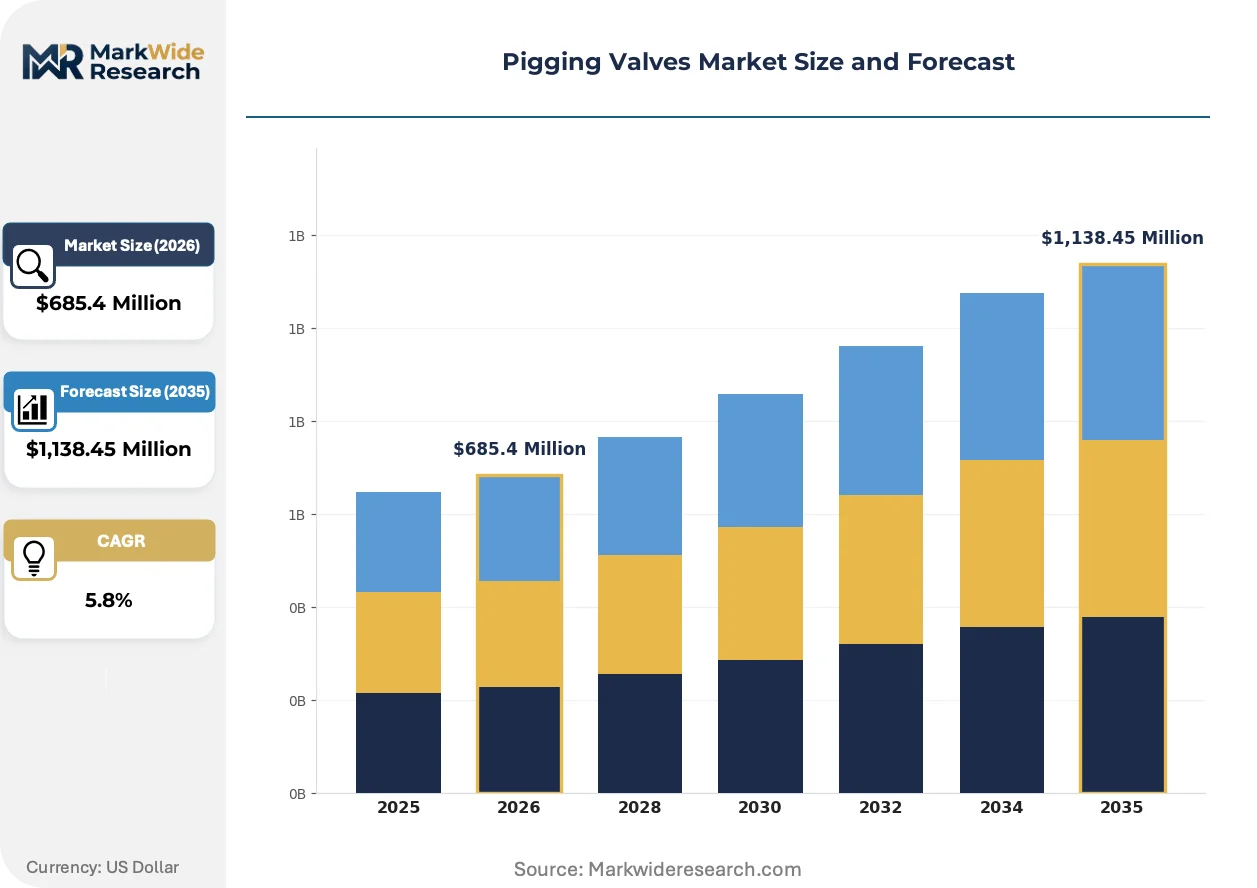
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Check Valves, Butterfly Valves Material: Stainless Steel, Carbon Steel, PVC, Alloy End User: Oil & Gas, Water & Wastewater, Chemical, Food & Beverage Size: Small, Medium, Large, Extra Large |
| Companies Covered | Argus Machine Co. Ltd, PBM Valve, Hartmann Valves GmbH, SAMSON Controls Inc., Frontier Valve International, Tiger Valve Company, Master Flo Valve Inc., CGIS, Jag Valves, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigging Valves Market Emerging Trajectories
Automation architectures and material science advances are compressing valve procurement cycles while expanding service temperature and pressure envelopes. These developments favor suppliers with integrated design-for-manufacturing capabilities.
Metal-seated ball valve technology is modularizing across pressure classes and bore sizes to reduce engineering-to-order lead times. Offshore operators in Norway and Brazil are specifying these configurable platforms for standardized subsea manifolds. The approach compresses project-specific engineering hours and enables volume purchasing across multiple field developments.
REACH substance restrictions and the EU F-Gas Regulation are phasing out certain seal elastomers and lubricants used in cryogenic and high-temperature service. Valve manufacturers are qualifying perfluoroelastomer and thermoplastic alternatives with extended temperature ranges. Chemical processing installations in Germany and Belgium are absorbing qualification costs earliest due to proximity to regulatory enforcement.
Buyer consolidation among supermajor pipeline operators is compressing supplier panels and unbundling aftermarket service contracts from initial equipment procurement. Integrated energy companies in the United States Gulf Coast and Saudi Arabia are negotiating enterprise pricing agreements that separate valve supply from actuator commissioning and maintenance. This bifurcation pressures mid-tier manufacturers to choose between volume positioning or specialized service differentiation.
Pigging Valves Market Segmentation
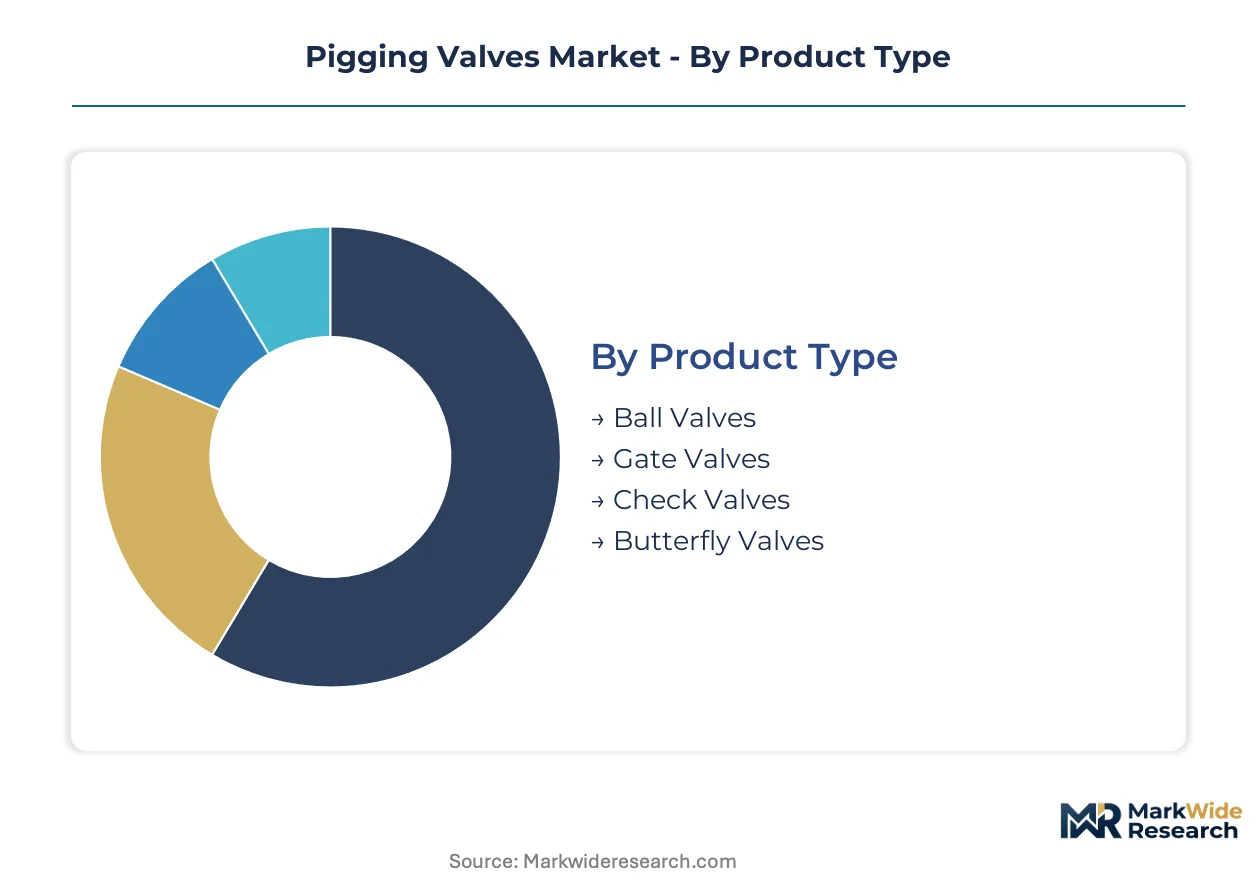
Pigging valve procurement patterns diverge sharply between standalone replacement cycles and integrated greenfield systems. Segmentation reveals where specification complexity concentrates versus where standardization drives volume economics.
Product Type:
Standalone pigging stations favor discrete valve configurations with dedicated actuation packages, while manifold-embedded designs demand compact, modular geometries.
- Ball Valves:Full-bore through-conduit geometry with bidirectional metal-to-metal sealing dominates automated pipeline stations. Demand concentrates in United States Gulf Coast petrochemical corridors where PHMSA-mandated inline inspection intervals accelerate replacement cycles for legacy gate valve infrastructure.
- Gate Valves:Rising-stem designs with expanding gate mechanisms suit manual bypass stations and maintenance isolation points. German North Sea offshore retrofits specify these for low-cycle isolation duties where automated actuation adds unnecessary cost.
- Check Valves:Piston and swing configurations prevent backflow in multi-pig launcher assemblies. Saudi Aramco engineering standards mandate these for sour gas gathering headers.
- Butterfly Valves:Triple-offset metal-seated variants serve large-bore water transmission lines where pressure ratings permit lighter construction. Indian city gas distribution networks specify these for cost-sensitive 6-inch and 8-inch lateral connections.
Volume placements concentrate in Ball Valves; the faster expansion belongs to Check Valves as multi-pig automation spreads.
Material:
Cost tiers separate corrosion-resistant alloys from commodity grades, with specification intensity tracking hydrogen sulfide exposure and chloride content.
- Stainless Steel:Austenitic and duplex grades resist chloride stress corrosion in offshore environments. Norwegian carbon capture injection networks specify super-duplex 2507 for supercritical CO2 service.
- Carbon Steel:ASTM A105 and A350 LF2 forgings compete aggressively on total installed cost for sweet crude and water transmission. United States midstream operators specify these for non-corrosive gathering lines.
- PVC:Thermoplastic construction suits low-pressure water and chemical transfer with minimal pigging frequency. Belgian chemical processors specify these for caustic service where metallic corrosion would accelerate.
- Alloy:Inconel 625 and Hastelloy C276 address severe sour service with hydrogen sulfide partial pressures exceeding 10 psi. Dutch hydrogen blending pilot lines are qualifying nickel alloys for embrittlement resistance.
Carbon Steel dominates unit placements; Alloy grades are climbing the fastest as hydrogen infrastructure specifications tighten.
End User:
Customer type determines specification intensity, with integrated energy companies demanding traceable quality systems versus municipal buyers prioritizing lifecycle cost.
- Oil & Gas:Exploration, production, and transmission operators require ANSI Class 600+ ratings with full material certification. United States supermajors unbundle aftermarket contracts from initial procurement.
- Water & Wastewater:Municipal utilities and industrial water treatment specify epoxy-coated ductile iron and carbon steel for lower operating pressures. German utilities favor these for large-diameter transmission mains.
- Chemical:Process plants demand tight shutoff and chemical compatibility across temperature extremes. REACH substance restrictions are forcing seal elastomer transitions in Belgian and German installations.
- Food & Beverage:Sanitary pigging systems for product recovery and CIP cycles require polished surfaces and FDA-compliant materials. Saudi food-grade pipeline projects specify these for dairy and juice transport.
Oil & Gas commands the specification premium; Food & Beverage is gaining share fastest as hygienic pipeline transport expands.
Size:
Foundry capacity constraints and forging press limits concentrate supply for large-bore ratings, creating queue bottlenecks that reshape procurement timelines.
- Small:2-inch through 4-inch bore sizes serve instrument and sample lines with minimal pigging duty. Indian city gas distribution mandates are standardizing these for residential lateral connections.
- Medium:6-inch through 12-inch configurations balance automation compatibility with forging availability. United States Gulf Coast brownfield expansions specify these for process unit tie-ins.
- Large:16-inch through 24-inch bores dominate transmission trunk lines requiring full-bore inspection pig passage. German and United States foundries concentrate capacity here.
- Extra Large:30-inch and above ratings require specialized forging presses and extended lead times. Saudi Aramco and Norwegian offshore projects queue 18-24 months for these configurations.
Medium sizes anchor procurement volume; Extra Large faces the steepest supply constraint expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized forging capacity for large-bore ANSI Class 900+ ratings concentrates along the United States Gulf Coast and in German industrial clusters, creating geographic bottlenecks that reshape procurement timelines for transmission operators.
United States
PHMSA pipeline safety regulations mandate inline inspection intervals and pressure-testing documentation that accelerate replacement cycles for aging valve assets. The Gulf Coast petrochemical corridor hosts brownfield expansion projects requiring specialized large-bore pigging valve configurations. Houston-area foundries are rebalancing capacity toward pigging-specific geometries as integrity mandates tighten.
Germany
EU Pressure Equipment Directive certification requirements stretch procurement lead times to 18-24 months for critical isolation assets. The F-Gas Regulation phases out certain seal elastomers, forcing qualification of perfluoroelastomer alternatives in chemical processing installations. North Sea offshore retrofits specify rising-stem gate valves for low-cycle isolation duties where automated actuation adds unnecessary cost.
Saudi Arabia
Saudi Aramco engineering standards mandate traceable material certification for all inline isolation assets in sour gas gathering headers. National pipeline expansion programs create queue bottlenecks for extra-large 30-inch and above valve configurations. Eastern Province industrial clusters concentrate demand for embrittlement-resistant metallurgies as hydrogen blending pilots advance.
Norway
Carbon capture injection networks require corrosion-resistant pigging valves for supercritical CO2 transport in North Sea storage projects. National regulators enforce extended design life specifications for subsea pigging valve configurations in brownfield developments. Stavanger-area engineering centers qualify super-duplex 2507 grades for severe service environments.
India
Petroleum and Natural Gas Regulatory Board city gas distribution mandates create demand for standardized 6-inch and 8-inch pigging valve configurations. Maharashtra and Gujarat industrial corridors absorb volume placements for residential lateral connections. Domestic fabricators compete on total installed cost for non-corrosive gathering line specifications.
Pigging Valves Market Vendor Landscape
Global majors compete with regional champions across metallurgical specialization and automation integration capabilities. The vendor base organizes into three tiers: integrated automation suppliers with broad actuator portfolios, precision-machining specialists leveraging heritage foundry relationships, and severe-service metallurgists addressing sour gas and hydrogen embrittlement challenges. Consolidation pressures intensify as buyer panel compression unbundles aftermarket contracts from initial equipment procurement. Capacity expansion and strategic partnerships dominate competitive moves as foundries queue large-bore forging orders.
Among German precision fabricators, Hartmann Valves GmbH occupies a position exemplifying European offshore retrofit specialization. SAMSON Controls Inc. represents the integrated automation tier with broad actuator portfolios anchoring chemical processing applications. Frontier Valve International sits within the severe-service metallurgy archetype, differentiating through embrittlement-resistant specifications for hydrogen and sour gas environments. These three anchors illustrate how competitive positioning stratifies across technical capability rather than geographic coverage alone.
| Leading Market Players |
|---|
| Argus Machine Co. Ltd |
| PBM Valve |
| Hartmann Valves GmbH |
| SAMSON Controls Inc. |
| Frontier Valve International |
| Tiger Valve Company |
| Master Flo Valve Inc. |
| CGIS |
| Jag Valves |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-outs for seal elastomers gate qualified supply access and premium-tier pricing power, as manufacturers absorbing perfluoroelastomer qualification costs in Germany and Belgium command material-certification premiums unavailable to commodity competitors.
Pricing Analysis
Aftermarket service unbundling from initial equipment procurement is compressing valve-only price points while elevating actuator-commissioning premiums. Three-tier pricing structure across certified-premium, standard-traceable, and economy-commodity levels tracks PHMSA documentation intensity and material-grade specifications. Pricing pressure stems from supermajor enterprise agreements consolidating supplier panels. Municipal water utilities exhibit highest price sensitivity; offshore operators in Norway and Brazil absorb premium positioning for extended design-life configurations.
Supply Chain Analysis
Freight costs for large-bore forgings concentrate supply planning around United States Gulf Coast and German industrial clusters where ANSI Class 900+ pressing capacity localizes. Nickel alloy feedstock draws from mining operations in Canada and Indonesia, with Inconel 625 and duplex stainless grades subject to tariff exposure. Single-source vulnerability concentrates in specialized forging presses for extra-large 30-inch-plus configurations. Distribution runs through EPC contractors and integrated energy company procurement centers rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PHMSA pipeline safety regulations erect a cost-of-compliance barrier-to-entry moat, as traceable material certification and pressure-testing documentation requirements favor incumbent suppliers with established quality management systems over unqualified aspirants.
For Market Incumbents: Cement market position by deepening captive forging relationships in Houston-area and German industrial clusters to secure large-bore capacity allocation against queue bottlenecks. Accelerate embrittlement-resistant metallurgy R&D to capture hydrogen blending specification upgrades before commodity competitors qualify alternative designs. Threat of buyer consolidation unbundling aftermarket contracts demands proactive service-contract innovation. For New Entrants and Emerging Players: Engineering-procurement contractors represent the most viable channel pathway for qualification-light market entry. Target Indian city gas distribution standardization mandates for 6-inch and 8-inch carbon steel configurations where domestic fabricators compete on total installed cost. White-space exists in CCUS injection network corrosion-resistant specifications where supercritical CO2 service requirements outstrip established supplier qualification speed. For Investors and Strategic Acquirers: Saudi Aramco engineering standard adoption by international operators is the leading indicator that severe-service metallurgy specialists will command acquisition premiums. Five-to-ten-year viability favors precision-machining heritage foundries with hydrogen-embrittlement qualification capabilities over automation-integrated generalists. Signal to monitor: European hydrogen blending pilot line qualification timelines accelerating specification lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Forging | Houston-area foundries rebalancing toward pigging-specific geometries reduce queue bottlenecks for large-bore orders. |
| Backward Integration into Nickel Alloys | Captive supply of Inconel 625 and duplex grades insulates against mining disruption and tariff exposure. |
| Hydrogen Qualification Program | Embrittlement-resistant metallurgy certification captures European pipeline network specification upgrades. |
| Modular Skid Partnership | Pre-fabricated pipeline station designs compress field welding requirements and favor flange-ready assemblies. |
| CCUS Corrosion-Resistant Line | Super-duplex 2507 configurations for supercritical CO2 transport address Norwegian carbon capture storage demand. |
Methodological Framework
Document review covered PHMSA regulatory filings, EU Pressure Equipment Directive guidance, Saudi Aramco engineering standards, and industry trade data, complemented by interviews with pipeline integrity managers, valve procurement leads at supermajor operators, foundry operations directors, and EPC project engineers. Secondary sources included customs records, SEC filings from publicly traded valve manufacturers, and national pipeline development databases. Bottom-up unit economics triangulated against top-down market sizing across product type, material grade, end-use sector, and regional regulatory cluster dimensions.
Segment-level demand outputs tracked ball valve, gate valve, check valve, and butterfly valve configurations across stainless steel, carbon steel, and alloy material tiers, with oil and gas, water and wastewater, chemical, and food and beverage end-use splits modeled throughout the projection horizon. CAGRs derived from regression analysis against pipeline mileage expansion, regulatory replacement cycle mandates, and hydrogen infrastructure qualification timelines. Industry-specific inputs incorporated PHMSA-mandated inline inspection intervals and EU F-Gas Regulation elastomer transition schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to nickel alloy mining supply, abrupt regulatory relaxation of material certification requirements, and breakthroughs in non-metallic valve construction. Forecasts reflect documented assumptions about foundry capacity expansion rates and qualification timeline stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Reciprocating Compressor Components Market
Valves
Europe Valves Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Mechanical Shaft Seal Market
Valves
Battery Safety Valve Market
Valves
Global Fluid Management Systems Market
Valves
Industrial Vacuum Valves Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Global Thermostatic Radiator Valve Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Industrial Valves and Actuators Market
Valves
Backflow Preventers Market
Valves
Carbon Seal Rings Market
Valves
India Industrial Valves Market
Valves
Harmonic Dampers Market
Valves
Cathodic Protection Market