
 Backflow Preventers Market | 2026-2036
Backflow Preventers Market Size, Share, and Industry Trends Forecast 2026-2036
Backflow Preventers Market Analysis
Equipment leasing and performance-based service contracts is rewriting competitive dynamics for smaller contractors seeking certified assemblies without heavy capital outlay. Mueller Water Products leverages its municipal channel depth to sustain recurring specification wins across North American water districts. Watts Water Technologies anchors its position through backward integration into brass foundry operations, controlling alloy quality for corrosion-resistant valve bodies. Xylem competes via digital monitoring add-ons that extend traditional hardware into predictive maintenance revenue streams.
Backflow preventers are hydromechanical safety devices engineered to block reverse flow in potable water distribution networks, typically rated for pressure differentials between 150 and 175 psi and constructed from lead-free brass or engineered polymers to comply with NSF/ANSI 61 drinking water standards. Their primary purpose is protecting public health by isolating contamination risks from cross-connections in plumbing, irrigation, and industrial process lines. Reduced Pressure Zone assemblies dominate commercial and institutional specifications due to their fail-safe discharge mechanism under backpressure conditions, while Atmospheric Vacuum Breaker units occupy the residential segment where cost sensitivity and simpler installation requirements govern selection. Double Check Valve configurations lead in fire suppression applications where non-health-hazard fluid separation satisfies code minimums.
The EPA Safe Drinking Water Act, NSF/ANSI 372 lead-content standards, and state plumbing codes collectively mandate certified backflow assemblies in high-hazard applications, creating structural demand that resists cyclical downturns. AWWA cross-connection control manuals and ICC model plumbing codes further standardize product acceptance criteria, narrowing market access for uncertified manufacturers. Stakeholders must monitor evolving state adoption of reduced lead thresholds and smart water infrastructure mandates that will determine which product portfolios retain specification relevance.
Market Dynamics
Municipal water infrastructure aging and EPA Safe Drinking Water Act enforcement are forcing utility operators toward certified assembly replacements, compressing replacement cycles and elevating specification stringency for corrosion-resistant valve materials.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Federal mandates for cross-connection control programs in high-hazard applications create structural replacement demand across US public water systems.
- Lead-free brass material standards:NSF/ANSI 372 compliance requirements accelerate obsolescence of legacy cast-iron and leaded bronze installations in potable water networks.
- Sun Belt urbanization:Rapid population growth in Arizona, Texas, and Florida elevates irrigation backflow risk profiles and inspection frequency requirements.
Market Restraints
- Copper and brass alloy volatility:Foundry-grade copper cathode price swings compress margin stability for valve body manufacturers dependent on spot metal purchasing.
- Certified assembly supply concentration:Limited US-based foundry capacity for AWWA-compliant castings creates bottleneck risk during municipal procurement surges.
- Double Check Valve substitution ceiling:Fire suppression contractors favor DCV assemblies over RPZ units where code permits, capping premium product penetration in non-health-hazard applications.
Strategic Opportunities
- Smart water infrastructure convergence:Pressure sensor integration with RPZ assemblies enables predictive maintenance revenue streams for municipal fleet operators.
- California Title 22 expansion:State-level cross-connection control program adoption creates specification pull for reduced pressure zone units in agricultural processing.
- Equipment leasing channel development:Performance-based service contracts allow smaller plumbing contractors to deploy certified assemblies without capital-intensive inventory positions.
Industry Challenges
- Cross-connection control specialist certification scarcity:AWWA-certified backflow assembly tester shortages in rural water districts delay inspection compliance and replacement scheduling.
- Legacy brass foundry integration complexity:Municipal procurement systems require ISO 9001 and NSF product certification alignment that fragmented regional suppliers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backflow Preventers Market |
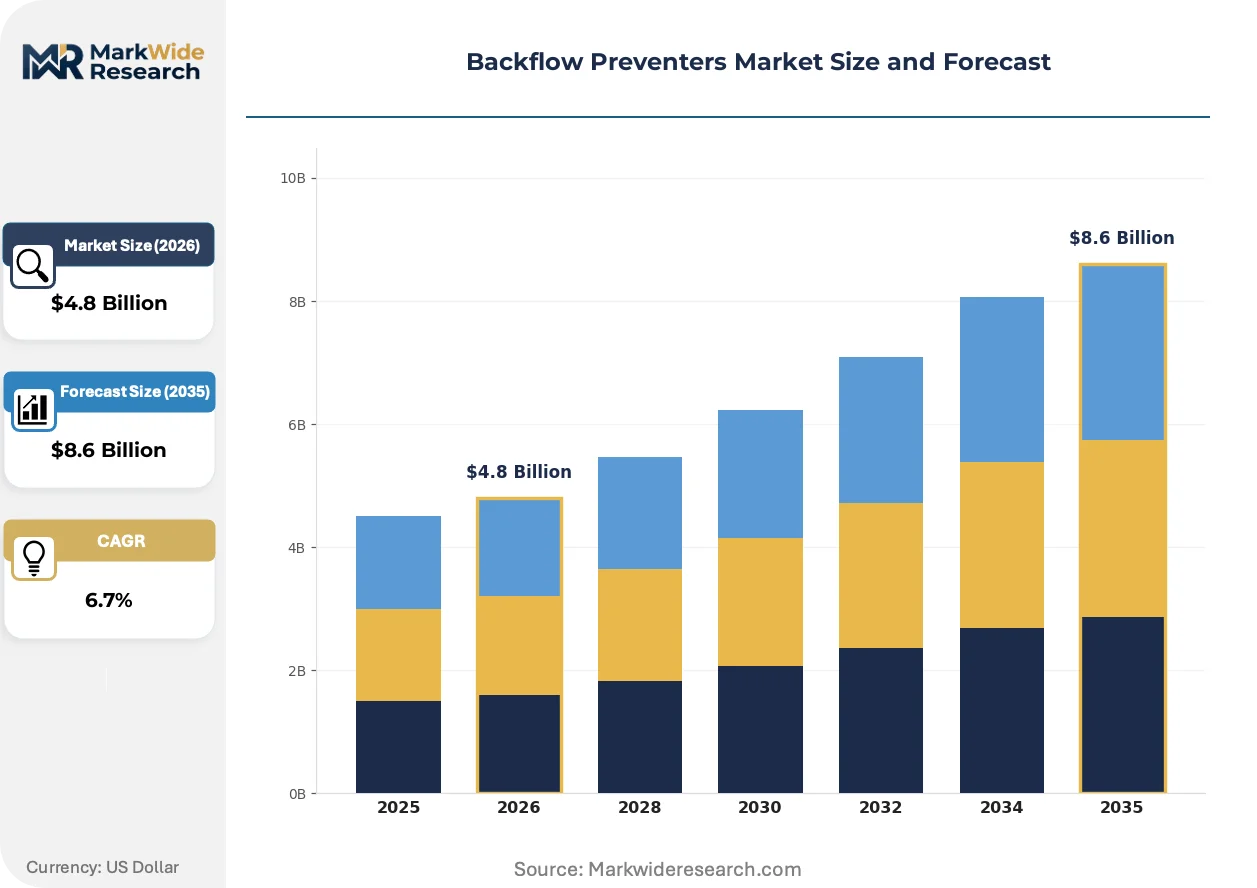
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reduced Pressure Zone, Double Check Valve, Atmospheric Vacuum Breaker, Duplex Valve Application: Residential Plumbing, Commercial Plumbing, Irrigation Systems, Wastewater Treatment Installation Type: Above Ground, Below Ground, Inline, Wall Mounted End User: Contractors, Municipalities, Property Managers, Industrial Facilities |
| Companies Covered | Honeywell International, Mueller Water Products, Apollo Valves, Xylem, Pentair, Watts Water Technologies, Schneider Electric, Flowserve Corporation, Zurn Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backflow Preventers Market Emerging Trajectories
Digital monitoring capabilities and material science advances are redefining backflow preventer value propositions, shifting competitive differentiation from mechanical reliability toward data-enabled lifecycle management.
Smart pressure sensing modules embedded in RPZ assemblies is migrating from pilot municipal deployments toward standard specification in Sun Belt water districts. Phoenix and Dallas utilities now require telemetry-ready valves for remote monitoring of discharge events. This technology is migrating from high-value commercial installations toward mid-tier residential and light commercial specifications, compressing the premium window for basic mechanical-only units.
EPA enforcement of NSF/ANSI 61 drinking water system component standards is tightening lead-content thresholds for valve body castings. Foundry operators face reformulation requirements for traditional silicon brass alloys to meet sub-0.25% lead mandates. California and Illinois plumbing code adoptions are most affected, with specification committees accelerating compliant product list updates.
Consolidated procurement by regional water authorities is displacing fragmented contractor-driven purchasing across the Southwest. Maricopa County and Central Texas municipal utility districts now issue multi-year assembly framework agreements that bundle installation, testing, and replacement services. This concentration is most visible in Arizona and Texas, where rapid service territory expansion favors single-source vendor relationships over distributed supplier networks.
Backflow Preventers Market Segmentation
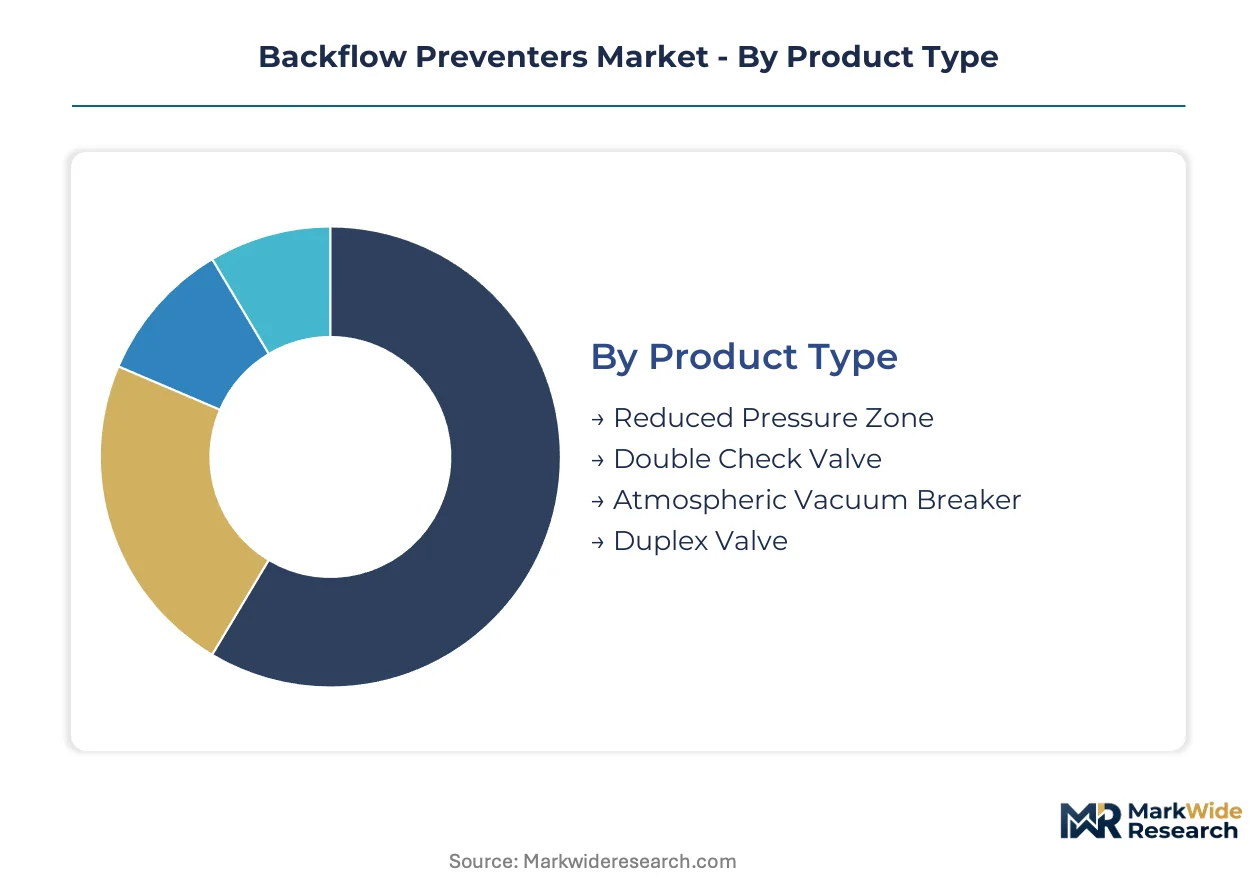
Segmentation in backflow preventers reveals how specification requirements diverge across hazard classifications and installation environments. Material standards, pressure ratings, and certification tiers create natural product boundaries that dictate channel strategy and margin structure for manufacturers.
Product Type:
Mature mechanical designs dominate high-hazard specifications while emerging configurations address niche pressure conditions.
- Reduced Pressure Zone:These assemblies incorporate a hydraulically operated relief valve between two independent check valves, creating a physically separated intermediate zone that vents to atmosphere under backpressure failure. Commercial and institutional specifications in Texas and Arizona municipal districts favor RPZ units for their fail-safe discharge mechanism, though foundry capacity constraints periodically extend lead times for AWWA-compliant castings.
- Double Check Valve:Two independently acting spring-loaded check valves arranged in series provide backflow protection without atmospheric venting, suitable for non-health-hazard applications. Fire suppression contractors in Sun Belt states specify DCV assemblies where plumbing codes permit substitution, capping premium RPZ penetration in lower-risk installations.
- Atmospheric Vacuum Breaker:Simple, non-testable devices relying on atmospheric air inlet to prevent backsiphonage; cost-sensitive residential irrigation applications in Florida and Arizona.
- Duplex Valve:Parallel-installed dual assemblies enabling isolation and service without flow interruption; continuous-process industrial facilities with zero-downtime requirements.
Reduced Pressure Zone handles the majority of throughput; Atmospheric Vacuum Breaker is the fastest mover on share.
Application:
Demand concentration tracks urbanization intensity and regulatory inspection frequency across end-use categories.
- Commercial Plumbing:Multi-tenant buildings, healthcare facilities, and educational institutions require testable assemblies with documented maintenance records. Phoenix and Dallas utilities now mandate telemetry-ready valves for remote discharge monitoring, compressing specification windows for basic mechanical-only units.
- Irrigation Systems:Landscape and agricultural watering networks present elevated backflow risk from fertilizer and pesticide injection. Rapid Arizona and Texas suburban expansion drives inspection frequency requirements and replacement cycle compression.
- Residential Plumbing:Single-family and small multi-family installations favor lower-cost, non-testable devices where code permits; Sun Belt new construction.
- Wastewater Treatment:Industrial process and reclamation facilities require corrosion-resistant alloys for aggressive fluid environments; NSF/ANSI 61 compliance critical.
Commercial Plumbing captures the largest revenue base; Irrigation Systems are expanding most quickly as Sun Belt urbanization accelerates.
Installation Type:
Physical mounting configuration determines material selection, access requirements, and service contract structures.
- Above Ground:Accessible installations in mechanical rooms and utility closets permit routine testing and maintenance without excavation. Municipal procurement frameworks in Maricopa County and Central Texas favor above-ground specifications for reduced lifecycle service costs.
- Below Ground:Buried vault and pit installations protect assemblies from freezing and mechanical damage in northern climates; specialized corrosion-resistant enclosures required.
- Inline:Direct pipeline integration for space-constrained retrofits; common in industrial process lines.
- Wall Mounted:Compact bracket installations for commercial kitchen and laboratory sink protection; ease of access drives specification.
Above Ground dominates replacement volume; Below Ground is gaining share fastest as frost-protection requirements spread.
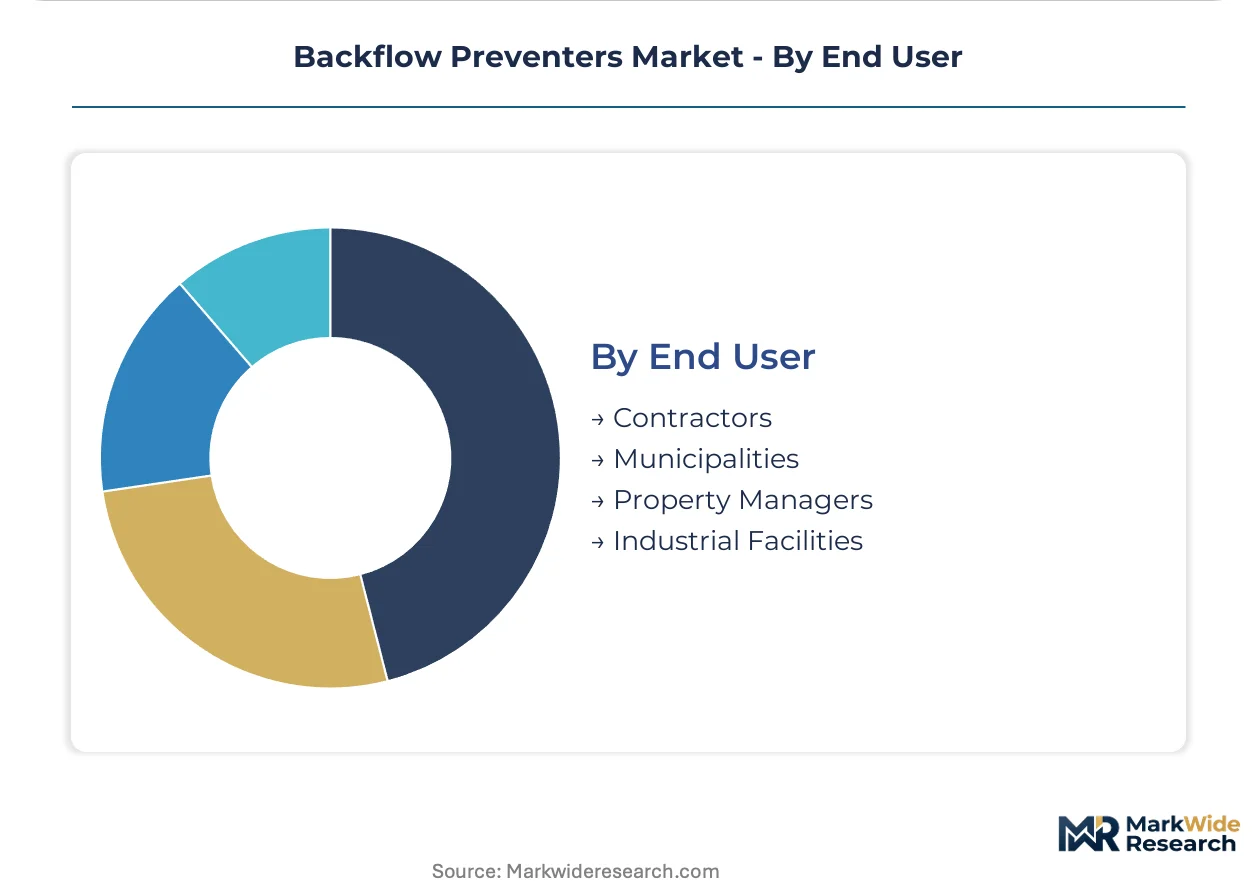
End User:
Procurement authority and technical sophistication vary sharply across customer categories, reshaping channel economics.
- Municipalities:Public water systems and regional utility districts issue multi-year framework agreements bundling installation, testing, and replacement services. Consolidated procurement in Arizona and Texas favors single-source vendor relationships with ISO 9001 and NSF certification alignment.
- Contractors:Plumbing and fire protection installers face working capital constraints that equipment leasing and performance-based service contracts address; smaller operators seeking certified assemblies without inventory-heavy positions.
- Property Managers:Commercial and multi-family facility operators responsible for cross-connection control compliance; inspection scheduling and documentation requirements drive recurring service relationships.
- Industrial Facilities:Process manufacturers with specialized fluid handling requirements; custom alloy specifications and zero-downtime redundancy needs.
Municipalities control the deepest specification authority; Contractors represent the steepest expansion trajectory as leasing channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal utility districts and commercial plumbing contractors concentrate procurement authority across distinct geographic clusters, with Sun Belt states and European industrial corridors driving specification volume.
United States
EPA Safe Drinking Water Act amendments compel cross-connection control program expansion across public water systems. State plumbing codes in California and Illinois enforce NSF/ANSI 372 lead-content thresholds below 0.25 percent. Phoenix and Dallas utilities now mandate telemetry-ready Reduced Pressure Zone assemblies for remote discharge monitoring.
Germany
Industrial process manufacturers demand corrosion-resistant duplex valve configurations for zero-downtime redundancy. The country's national drinking water regulator enforces strict material compliance for potable water system components. Bavarian chemical processing clusters anchor specification pull for high-performance alloy castings.
China
Rapid urban water infrastructure buildout elevates backflow preventer installation mandates in municipal distribution networks. The Ministry of Ecology and Environment tightens discharge monitoring requirements for cross-connection control. Yangtze River Delta megacities drive standardization toward smart pressure sensing integration.
Australia
Drought-responsive irrigation backflow regulations intensify inspection frequency across agricultural water districts. State plumbing authorities harmonize with AS/NZS 3500 standards for testable assembly specifications. New South Wales and Victoria municipal utilities consolidate procurement through multi-year framework agreements.
Canada
Cold-climate below-ground installation requirements spread frost-protected vault specifications across prairie provinces. Health Canada enforces lead-content limits for drinking water system components aligned with NSF/ANSI 61. Ontario municipal water authorities bundle testing and replacement services in consolidated vendor contracts.
Backflow Preventers Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered specification tiers. The vendor base organizes around three strategic archetypes: municipal-framework incumbents with ISO 9001 alignment, brass foundry-integrated manufacturers controlling alloy quality, and digital monitoring specialists extending hardware into predictive service revenue. Dominant competitive moves include backward integration into captive foundry operations and smart sensor technology licensing for telemetry-ready valve portfolios.
Among North American water infrastructure specialists, Mueller Water Products, Watts Water Technologies, and Xylem occupy distinct positioning within the competitive structure. Mueller Water Products exemplifies the municipal-channel archetype through recurring specification wins across water district procurement frameworks. Watts Water Technologies represents foundry-integrated manufacturing with in-house brass casting operations. Xylem anchors the digital convergence vector through pressure sensor integration that extends traditional assemblies into predictive maintenance revenue streams.
| Leading Market Players |
|---|
| Honeywell International |
| Mueller Water Products |
| Apollo Valves |
| Xylem |
| Pentair |
| Watts Water Technologies |
| Schneider Electric |
| Flowserve Corporation |
| Zurn Industries |
| Others |
Supply Flow & Price Mechanics
Brass foundry capacity concentration in the United States determines both pricing tier spreads and supply chain shape, with AWWA-compliant casting bottlenecks compressing margins for spot purchasers while integrated manufacturers capture premium positioning through alloy quality control.
Pricing Analysis
Cost-plus municipal framework agreements with London Metal Exchange copper indexation dominate procurement structures for public water systems. Pricing stratifies across premium certified assemblies, standard commercial-grade units, and economy residential devices based on NSF/ANSI 372 certification tier and telemetry integration. Cost compression in economy-tier atmospheric vacuum breakers is intensifying because irrigation contractors prioritize lowest first-cost options. Municipalities exhibit least price sensitivity due to compliance-driven replacement mandates, while residential end-users show highest elasticity.
Supply Chain Analysis
Captive brass foundry operations at Watts Water Technologies and Mueller Water Products hold the majority of AWWA-compliant casting capacity for lead-free valve bodies. Supply concentrates in the United States for finished assemblies, with brass billet feedstock drawing from domestic and Mexican smelter networks. Raw material dependencies center on copper cathode, silicon brass alloy formulations, and engineered polymer seals. Single-source vulnerability runs through certified foundry capacity during municipal procurement surges. Distribution runs through regional water authority framework agreements and plumbing contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backflow preventer markets reward service-attach strategies, with predictive maintenance telemetry and testing-certification subscriptions expanding faster than hardware unit sales across Sun Belt water districts.
For Market Incumbents: Insulate specification position by deepening backward integration into captive brass foundry operations and accelerating smart sensor R&D to match Xylem's telemetry-ready portfolio. Double Check Valve substitution in fire suppression applications threatens premium RPZ penetration, requiring differentiated health-hazard messaging for commercial plumbing channels.
For New Entrants and Emerging Players: Pursue equipment leasing channel partnerships with smaller plumbing contractors seeking certified assemblies without inventory-heavy capital positions. California Title 22 agricultural processing expansions represent the most penetrable white-space, with cross-connection control program adoption lagging municipal water system mandates. Target performance-based service contract structures that bundle installation, testing, and replacement.
For Investors and Strategic Acquirers: EPA Safe Drinking Water Act amendments reshaping the acquisition landscape favor targets with ISO 9001 and NSF certification alignment already embedded. Long-term viability over the projection horizon rests on smart water infrastructure convergence capabilities. The signal to monitor is state-level adoption of telemetry-ready valve mandates in Arizona and Texas municipal procurement frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Integration | Phoenix and Dallas utilities now mandate telemetry-ready RPZ assemblies for remote discharge monitoring. |
| Backward Integration into Foundry Operations | Watts Water Technologies controls alloy quality for corrosion-resistant valve bodies through in-house brass casting. |
| Equipment Leasing Channel Development | Performance-based service contracts allow smaller contractors to deploy certified assemblies without capital-intensive inventory. |
| California Title 22 Program Alignment | State-level cross-connection control expansion creates specification pull for reduced pressure zone units in agricultural processing. |
| Municipal Framework Agreement Positioning | Maricopa County and Central Texas utility districts bundle installation, testing, and replacement through multi-year vendor contracts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across municipal water districts, plumbing contractors, property management firms, and brass foundry operators. Primary fieldwork with AWWA-certified backflow assembly testers, regional utility procurement officers, and fire protection system engineers informed operational constraints. Secondary validation drew from EPA Safe Drinking Water Act filings, AWWA cross-connection control manual updates, state plumbing code adoption records, and municipal procurement database extracts. Bottom-up unit shipment estimates triangulated against top-down infrastructure spending projections.
Calibration anchored volume and value outputs to documented municipal replacement cycles and Sun Belt urbanization trajectories across the analysis window. Segmentation dimensions modeled include product type tier, application hazard classification, installation configuration, and end-user procurement authority. CAGRs were derived from infrastructure investment pipelines and regulatory compliance deadlines. Forecast inputs incorporated copper alloy price volatility assumptions and smart water infrastructure adoption curves.
Sensitivities concentrate around brass foundry capacity constraints, state-level lead-content threshold accelerations, and certified tester availability bottlenecks in rural water districts. Cross-checking against AWWA annual cross-connection control program survey data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Three Way Ball Valve Market
Valves
Europe Medium Voltage Switchgear Market
Valves
Global Compression Packing Market
Valves
Fluid Power Cylinder Market
Valves
Pressure Reducing Valve Market
Valves
Christmas Tree Valves Market
Valves
Mobile Hydraulic Valves Market
Valves
Global Plug Valve Market
Valves
Pinch Valve Market
Valves
North America Butterfly Valve Market
Valves
Blasting Stemming Plugs Market
Valves
Global Stainless Steel Control Valves Market
Valves
Explosion Isolation Valves Market
Valves
Flare Stack Monitoring Systems Market
Valves
Hybrid Valve Market