
 Cathodic Protection Market | 2026-2036
Cathodic Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Cathodic Protection Market Analysis
Aluminum-zinc-indium alloy chemistry is hardening as the dominant anode material for deepwater applications, displacing traditional zinc compositions in projects below 500 meters. Aegion Corporation leverages its integrated engineering-services model across pipeline and marine contracts. MATCOR, Inc. specializes in custom-designed impressed current groundbed systems for refinery and power plant clients. Farwest Corrosion Control Company anchors its position through extensive distributor coverage across North American industrial corridors.
Cathodic protection is an electrochemical technique that applies direct electrical current or sacrificial anodes to metal surfaces, maintaining a negative potential of typically minus 850 millivolts relative to a copper-copper sulfate reference electrode to halt oxidation reactions. Its primary purpose is preventing corrosion failure in steel infrastructure exposed to soil, seawater, or chemical environments, thereby extending asset life and preventing containment breaches. Impressed current systems command the largest revenue share due to their adaptability for large-diameter pipelines and marine structures with high current-density requirements. Galvanic anodes retain strong positions in retrofit applications and remote installations where power availability is constrained. Monitoring systems within the technology dimension are gaining traction as operators integrate real-time potential logging with SCADA infrastructure.
The US PHMSA pipeline safety regulations and NACE International SP0169 standard govern cathodic protection design, testing, and maintenance intervals for interstate pipelines, creating recurring compliance expenditure that sustains service-provider revenues. The EU F-Gas Regulation and REACH directives influence anode alloy compositions and coating chemistries available to European operators, constraining supplier formulation choices. Brazil's national petroleum regulator ANP mandates cathodic protection for all subsea production equipment, reinforcing specification requirements for pre-salt field developments. Stakeholders must evaluate remote monitoring technology investments against the operational cost of manual survey compliance across geographically dispersed asset portfolios.
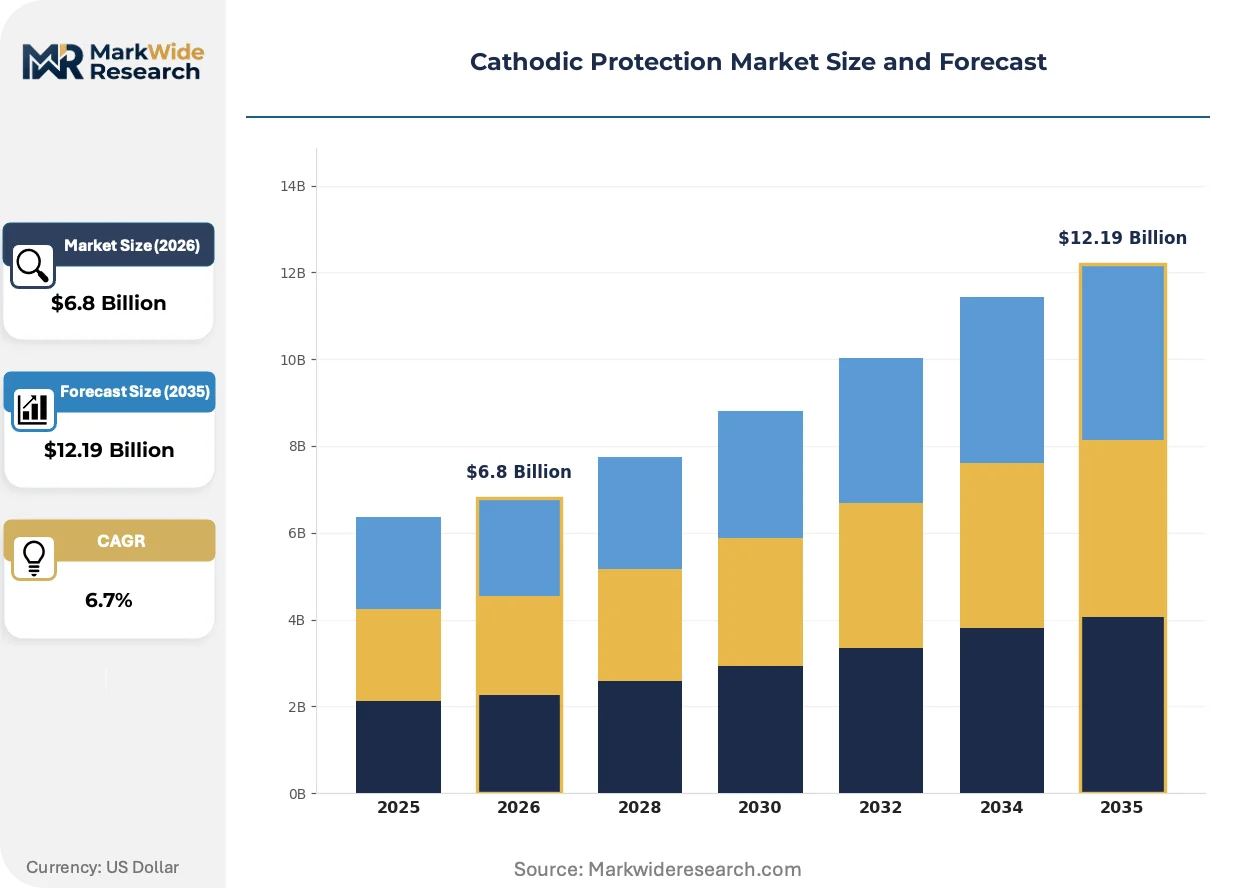
Market Dynamics
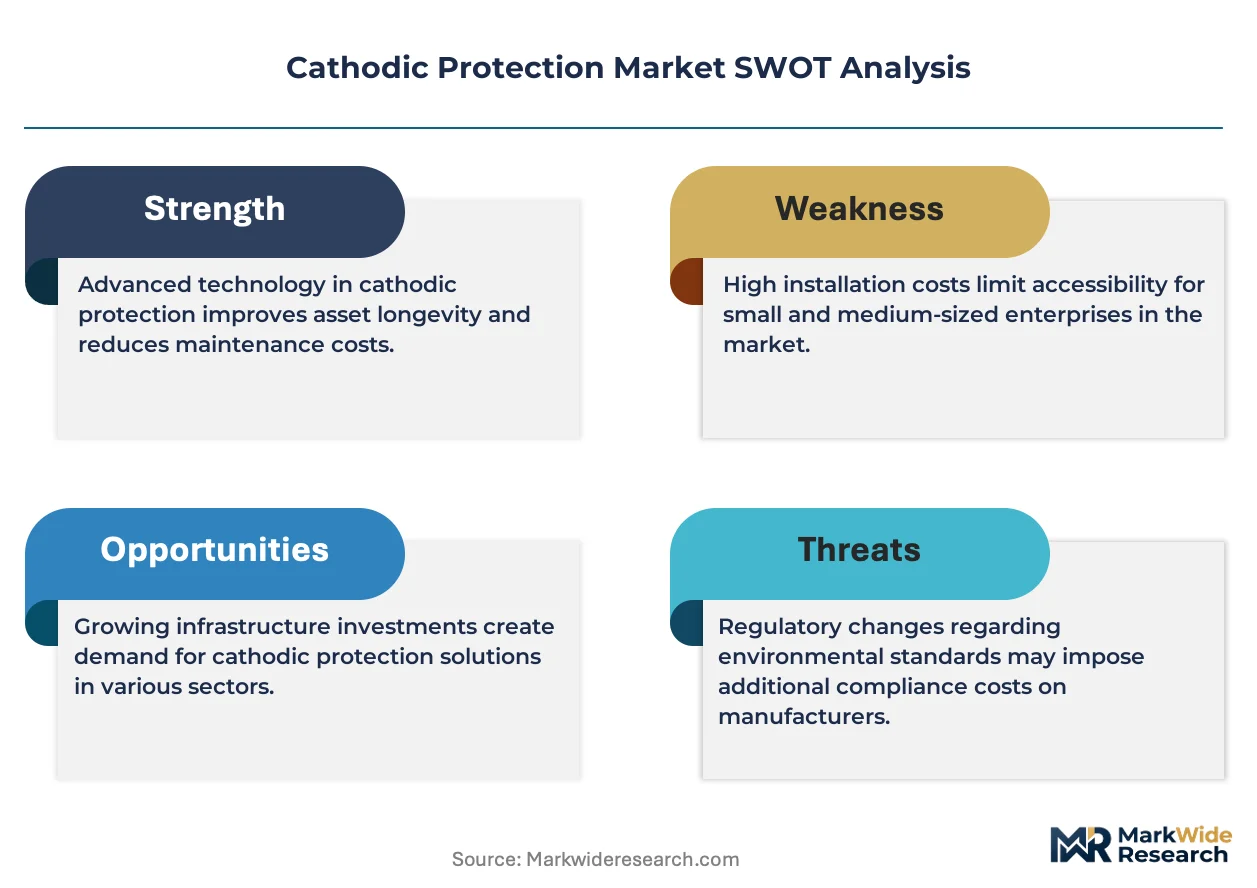
Aluminum-zinc-indium alloy chemistry is hardening as the dominant specification for deepwater cathodic protection, displacing traditional zinc compositions below 500 meters and forcing specification upgrades across subsea engineering procurement.
Growth Catalysts
- US PHMSA integrity mandates:Pipeline operators must replace legacy impressed current systems on accelerated cycles, sustaining demand for retrofit engineering services across interstate networks.
- Pre-salt basin developments:Brazil's ANP requires cathodic protection for all subsea production equipment, reinforcing specialized aluminum-zinc-indium anode specifications for Petrobras-led deepwater projects.
- SCADA-integrated monitoring:Real-time potential logging systems are penetrating marine and pipeline installations as operators automate compliance documentation.
Market Restraints
- Indium supply concentration:Refining capacity for this critical alloying element clusters in Chinese smelters, exposing anode manufacturers to raw material availability shocks.
- EU F-Gas and REACH constraints:These frameworks restrict coating chemistries and alloy compositions available to European operators, limiting supplier formulation flexibility.
- Zinc anode residual performance:Traditional compositions retain cost advantages in shallow-water applications below 150 meters, slowing full conversion to aluminum-based systems.
Strategic Opportunities
- Floating offshore wind foundations:Jacket structures and mooring chains in the North Sea and Gulf of Maine require cathodic protection designs adapted to dynamic loading conditions.
- Hydrogen pipeline repurposing:Existing natural gas networks undergoing hydrogen service conversion need upgraded impressed current systems to manage embrittlement-sensitive steel chemistries.
- Remote monitoring subscriptions:Asset operators are unbundling compliance survey services from equipment supply, creating recurring revenue streams for telemetry providers.
Industry Challenges
- Electrochemical modeling expertise:Deepwater projects require specialists capable of simulating current distribution across complex subsea geometries, and this talent pool remains thin.
- Legacy system integration:Retrofit impressed current installations must interface with decades-old pipeline coatings of variable integrity, complicating design validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cathodic Protection Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Galvanic Anodes, Impressed Current Systems, Portable Systems, Rectifiers Application: Pipeline Protection, Marine Structures, Storage Tanks, Underground Tanks End User: Oil & Gas, Water Utilities, Power Generation, Marine Technology: Electrochemical, Monitoring Systems, Cathodic Protection Survey, Data Analysis Tools |
| Companies Covered | Aegion Corporation, MATCOR, Inc., BAC Corrosion Control Ltd., Corrpro Companies Inc, Farwest Corrosion Control Company, Cathodic Protection Co. Ltd., Savcor Group Ltd., Imenco AS, CMP Europe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cathodic Protection Market Emerging Trajectories
Digital telemetry and advanced alloy formulations are compressing inspection intervals while extending design lives for subsea assets. Three developments merit particular attention.
Remote monitoring platforms are expanding into cathodic protection infrastructure. These systems transmit potential readings from subsea reference electrodes to shore-based control centers. North Sea pipeline operators now specify integrated data loggers as standard equipment. This capability is compressing the market for manual survey vessels and accelerating predictive maintenance adoption.
EU F-Gas Regulation amendments are tightening restrictions on fluorinated greenhouse gases used in certain coating applications. Anode manufacturers serving European offshore wind projects must reformulate protective finishes. German and Danish developers are requiring REACH-compliant supply chain documentation ahead of installation contracts.
Asset owners are unbundling cathodic protection system procurement from long-term performance guarantees. Engineering-procurement-construction contractors now compete separately with specialized monitoring service providers. This bifurcation is most visible in Brazil's pre-salt developments, where Petrobras separates anode supply contracts from integrity management services.
Cathodic Protection Market Segmentation
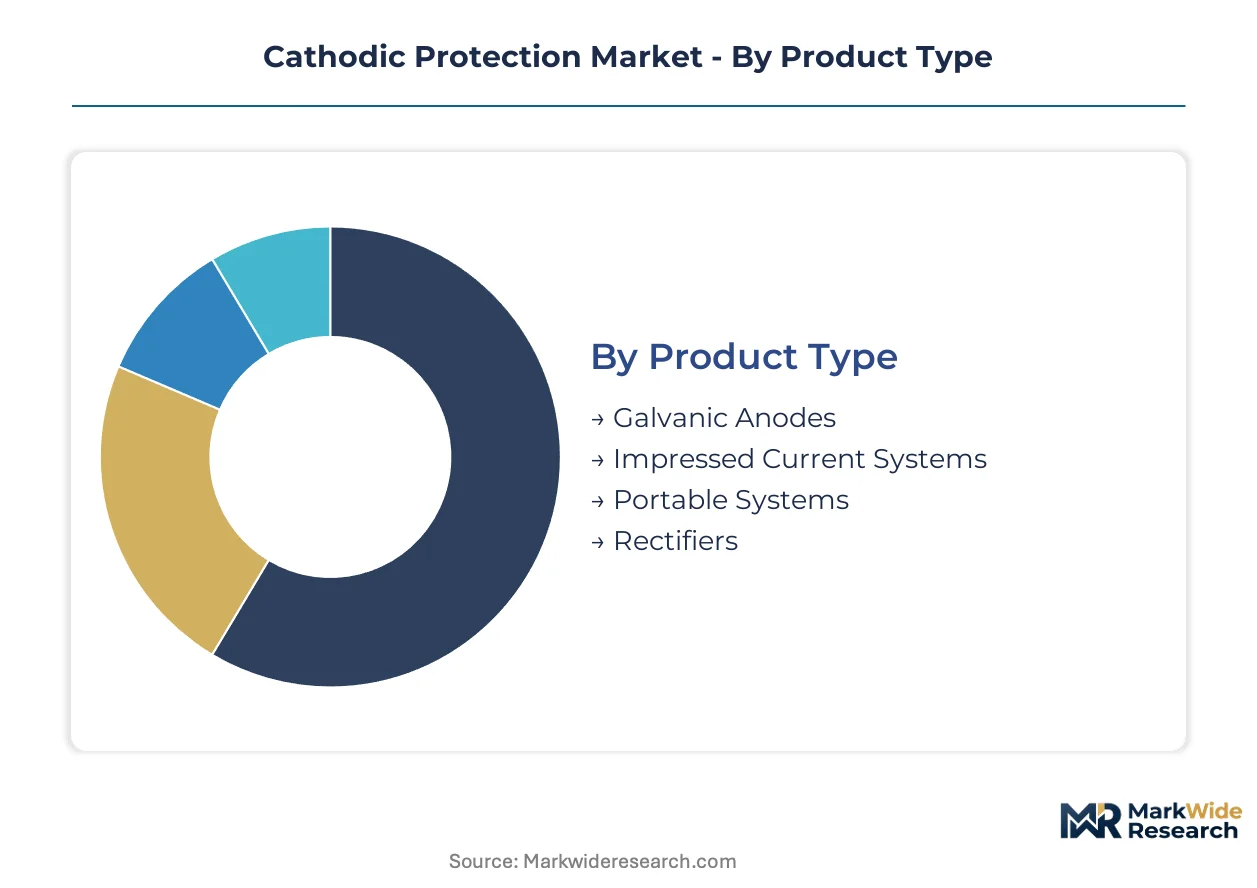
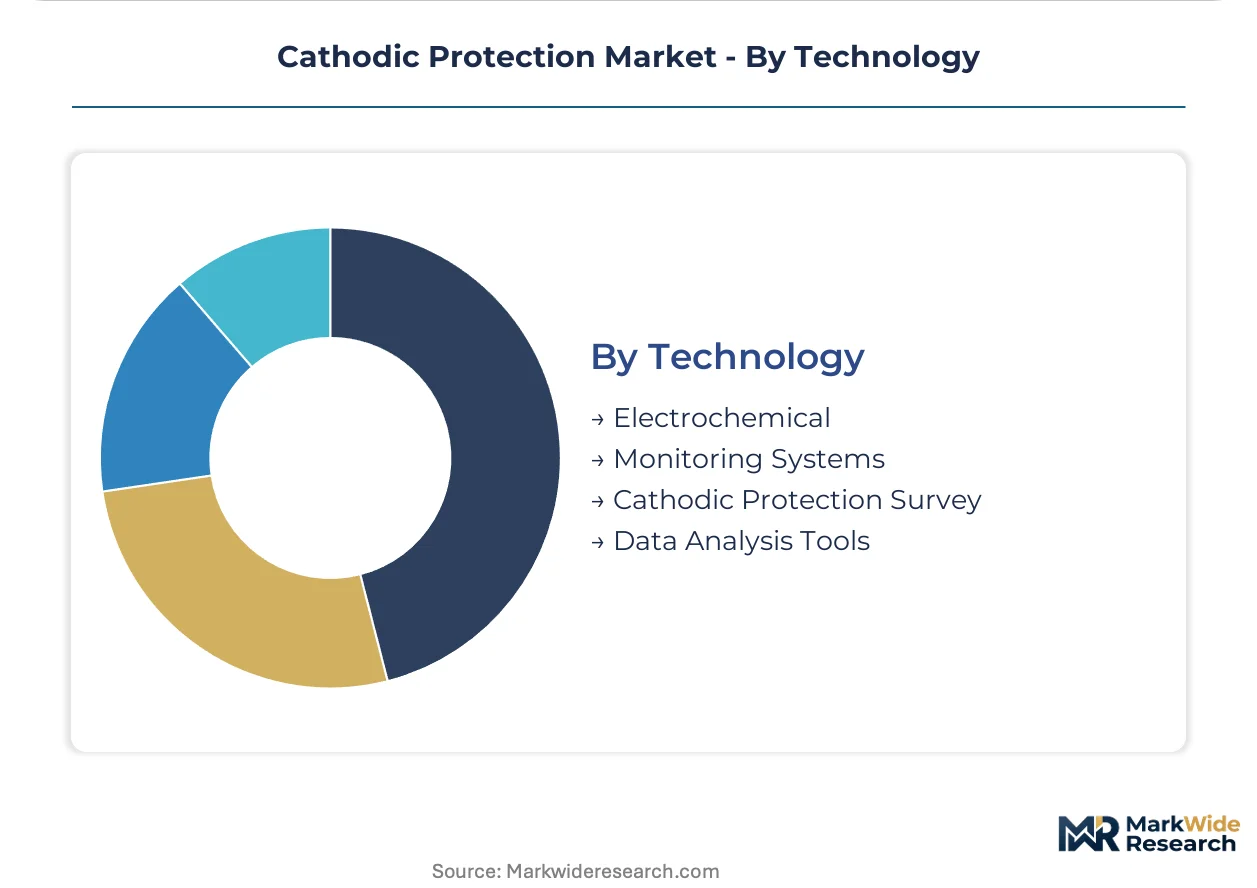
Cathodic protection procurement patterns diverge sharply across product architectures, installation environments, and operational technologies. Supply concentration in aluminum alloy refining and impressed current rectifier manufacturing shapes competitive positioning within each segment tier.
Product Type:
Supply concentration in anode alloy production and rectifier electronics manufacturing concentrates margin capture among integrated suppliers.
- Galvanic Anodes:These self-powered sacrificial metal assemblies utilize aluminum-zinc-indium or magnesium compositions to generate protective current through natural electrochemical potential differential. Offshore pipeline operators in Brazil's pre-salt basin and the Gulf of Mexico specify these for subsea installations below 500 meters where impressed current power delivery proves impractical.
- Impressed Current Systems:Externally powered configurations employing transformer-rectifier units and inert anodes deliver adjustable current densities for large-diameter pipelines and marine structures with high surface-area requirements. US PHMSA integrity mandates accelerate replacement cycles across interstate natural gas transmission networks, sustaining engineering service demand.
- Portable Systems:Mobile cathodic protection units serve temporary construction-phase protection and emergency remediation scenarios.
- Rectifiers:Power conversion equipment transforms AC grid supply to controlled DC output for impressed current groundbed circuits.
Today's leader: Impressed Current Systems. Tomorrow's challenger: Galvanic Anodes.
Application:
Installation environment dictates material specification, accessibility constraints, and regulatory compliance intensity.
- Pipeline Protection:Buried steel transmission lines require continuous cathodic protection coverage along rights-of-way, with design current densities varying by soil resistivity and coating quality. US interstate networks face accelerated retrofit timelines under federal integrity management rules.
- Marine Structures:Offshore platforms, wind turbine foundations, and port facilities demand specialized deepwater anode specifications and dynamic loading accommodation. North Sea operators integrate SCADA-connected reference electrodes for real-time potential monitoring.
- Storage Tanks:Aboveground petroleum and chemical containment vessels utilize impressed current systems for floor and shell protection.
- Underground Tanks:Buried fuel storage installations at retail and industrial sites employ galvanic anodes where power availability remains limited.
Pipeline Protection commands current volume leadership. Marine Structures exhibit the steepest expansion trajectory.
End User:
Customer procurement sophistication and technical specification authority vary substantially across industrial sectors.
- Oil & Gas:Integrated majors and midstream operators maintain dedicated corrosion engineering teams specifying complex impressed current designs for production facilities and transmission infrastructure. Brazil's ANP mandates drive standardized subsea equipment procurement across Petrobras-led developments.
- Water Utilities:Municipal and regional water authorities apply cathodic protection to buried distribution mains and treatment plant structures, with budget constraints favoring galvanic anode solutions.
- Power Generation:Thermal and nuclear facilities protect cooling water intake structures and buried fuel oil lines.
- Marine:Ship operators and port authorities specify hull and dock protection systems with classification society approval requirements.
Oil & Gas dominates specification authority. Water Utilities present the largest untapped retrofit opportunity.
Technology:
Digital instrumentation and predictive analytics are compressing traditional inspection intervals while extending asset design lives.
- Electrochemical:Fundamental cathodic protection implementation through controlled current application maintains the negative potential threshold of minus 850 millivolts against copper-copper sulfate reference.
- Monitoring Systems:Telemetry-equipped reference electrodes and data loggers transmit potential readings to shore-based control centers, automating compliance documentation. North Sea operators now specify integrated data loggers as standard equipment.
- Cathodic Protection Survey:Manual and remote-sensing inspection protocols verify system performance and coating integrity across distributed asset portfolios.
- Data Analysis Tools:Predictive algorithms process historical potential data to forecast anode consumption and optimize replacement scheduling.
Electrochemical foundations remain indispensable. Monitoring Systems are capturing the fastest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf of Mexico offshore corridor anchors cathodic protection demand through its dense concentration of aging subsea pipelines and platform infrastructure requiring life-extension interventions.
United States
The US Pipeline and Hazardous Materials Safety Administration mandates accelerated replacement cycles for legacy impressed current systems across interstate natural gas transmission networks. PHMSA integrity management rules create recurring compliance expenditure that sustains engineering service demand. Houston-based contractors dominate retrofit procurement for Gulf of Mexico offshore assets.
Brazil
Petrobras-led pre-salt basin developments drive specialized aluminum-zinc-indium anode specifications for deepwater production equipment. The national petroleum regulator ANP mandates cathodic protection coverage for all subsea installations. Rio de Janeiro engineering clusters concentrate procurement authority for floating production system contracts.
Norway
North Sea offshore pipeline operators expand sacrificial anode deployments as aging infrastructure reaches design life limits. Norwegian regulators enforce strict coating integrity standards under offshore facility guidelines. Stavanger and Bergen engineering centers specify SCADA-integrated monitoring systems as standard equipment.
United Kingdom
Decommissioning delays extend cathodic protection obligations for mature North Sea oil and gas assets beyond original design horizons. The Health and Safety Executive oversees corrosion management compliance for offshore installations. Aberdeen service providers capture integrity management contracts for platform life-extension programs.
China
Indium refining capacity concentration exposes anode manufacturers to raw material supply chain vulnerabilities. The Ministry of Ecology and Environment implements dual carbon goals that influence industrial coating formulations. Shandong and Jiangsu smelter clusters control critical alloying element availability for global anode production.
Cathodic Protection Market Vendor Landscape
Global majors compete with regional champions across engineering services and alloy supply, producing a tiered structure where integrated corrosion management providers face pressure from specialized anode fabricators and telemetry specialists. The vendor base separates into three strategic archetypes: full-service engineering contractors, dedicated anode manufacturers, and digital monitoring platform developers. M&A activity concentrates among engineering firms acquiring regional survey capabilities, while strategic partnerships link alloy suppliers with offshore installation contractors.
Within the integrated engineering-services tier, Aegion Corporation exemplifies the full-service model spanning pipeline and marine contracts. MATCOR, Inc. occupies a position among specialists in custom-designed impressed current systems. Farwest Corrosion Control Company anchors the distributor-coverage archetype across North American industrial corridors. These three representations illustrate how competitive positioning stratifies between bundled service provision and component specialization.
| Leading Market Players |
|---|
| Aegion Corporation |
| MATCOR, Inc. |
| BAC Corrosion Control Ltd. |
| Corrpro Companies Inc |
| Farwest Corrosion Control Company |
| Cathodic Protection Co. Ltd. |
| Savcor Group Ltd. |
| Imenco AS |
| CMP Europe |
| Others |
Supply Flow & Price Mechanics
Electrochemical modeling specialists concentrated in Houston and Aberdeen engineering clusters command wage premiums that compress margin spreads between premium engineering-procurement-construction bundles and standard equipment-only supply tiers.
Pricing Analysis
Input-cost pass-through from indium and aluminum alloy volatility shapes pricing dynamics across anode manufacturing tiers. Project-based contracting dominates, with price differentiation resting on certification grade (NACE SP0169 compliance versus basic ISO standards) and after-sales telemetry bundling. Pricing pressure stems from Chinese smelter concentration in indium supply, forcing Western fabricators to absorb margin compression or risk volume loss. Water utilities exhibit highest price sensitivity due to municipal budget constraints, while offshore oil and gas operators prioritize technical specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by Petrobras and major North Sea operators force anode manufacturers to qualify secondary alloy suppliers beyond their primary Chinese indium sources. Supply concentrates in China for indium refining, Norway and Germany for specialized marine engineering, and the United States for transformer-rectifier electronics. Raw material dependencies span aluminum-zinc-indium alloy feedstock, rare earth elements for rectifier components, and REACH-compliant coating chemistries. Single-source vulnerability in Chinese indium smelters exposes the entire anode fabrication tier to disruption. Distribution runs through engineering-procurement-construction contractors who bundle equipment with installation services for offshore projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cathodic protection market functions as a stable compounder, with regulatory compliance mandates across pipeline and subsea infrastructure generating recurring expenditure cycles that resist cyclical downturns.
For Market Incumbents: Deepen backward integration into indium alloy supply through offtake agreements with Chinese smelters or alternative sourcing development, insulating margin structures from raw material shocks. Expand telemetry platform subscriptions to capture recurring revenue streams as asset owners unbundle monitoring from hardware supply. Defend against specialized digital entrants by embedding SCADA integration capabilities into core engineering contracts. For New Entrants and Emerging Players: Begin with floating offshore wind foundation protection in the North Sea and Gulf of Maine, where dynamic loading specifications create specification gaps that incumbent pipeline specialists have not fully addressed. Target water utility retrofit opportunities in North American municipal markets, where budget constraints favor innovative galvanic anode designs over full impressed current system replacements. Establish credibility through certification to NACE SP0169 and ANP subsea standards before scaling. For Investors and Strategic Acquirers: Engineering-procurement-construction contractors with offshore installation capabilities are the most active acquirer in this space, seeking to add cathodic protection design expertise to integrated service portfolios. The market supports long-term viability through infrastructure life-extension demand rather than greenfield expansion, favoring asset-light telemetry specialists and regional survey service providers as acquisition targets. Watch indium price volatility and Chinese export policy shifts as the critical inflection signal for anode manufacturer margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Indium Supply Security Program | Backward integration into Chinese or alternative smelter offtake agreements protects margin structures from alloying element price shocks. |
| SCADA-Integrated Monitoring Platform Launch | Telemetry subscriptions capture recurring revenue as Petrobras and North Sea operators unbundle integrity management from hardware supply. |
| Floating Wind Foundation Specialization | Dynamic loading expertise for jacket structures and mooring chains addresses specification gaps in emerging North Sea and Gulf of Maine developments. |
| NACE SP0169 Certification Investment | Compliance credentialing opens PHMSA-mandated retrofit procurement across US interstate natural gas transmission networks. |
| Water Utility Galvanic Anode Innovation | Cost-optimized designs for municipal budget constraints penetrate the largest untapped retrofit segment in North American infrastructure. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with corrosion engineering directors at pipeline operators, procurement leads at Petrobras and major North Sea asset owners, and technical directors at anode manufacturing facilities with secondary validation. Secondary sources included US PHMSA incident and compliance databases, ANP subsea equipment specifications, NACE International standards documentation, and customs trade data for aluminum alloy and indium flows. Bottom-up equipment shipment tracking and top-down infrastructure investment analysis were triangulated against regulatory mandate timelines.
The forecast window anchored to historical replacement cycles for impressed current systems and sacrificial anode consumption patterns in mature offshore basins. Segmentation modeling spanned product architecture (galvanic versus impressed current), installation environment (pipeline, marine structure, storage facility), end-user industry (oil and gas, water utility, power generation), and technology tier (electrochemical baseline versus integrated monitoring). CAGRs were derived from regression analysis against infrastructure age profiles and regulatory compliance expenditure patterns. Industry-specific inputs included subsea well count trajectories in Brazil's pre-salt basin and PHMSA integrity management enforcement intensity.
Several conditions sit outside the modeled scope, including abrupt shifts in Chinese indium export policy, unanticipated decommissioning accelerations in the North Sea, and breakthroughs in alternative corrosion protection technologies such as advanced coating systems. Forecasts reflect documented assumptions about regulatory enforcement continuity and alloy chemistry specification stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
North America Valves Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Servo Valves Market
Valves
Cryogenic Valve Market
Valves
Oil Drain Valves Market
Valves
US Water & Wastewater Valves Market
Valves
Valve Manifold Box (VMB) Market
Valves
North America Irrigation Valves Market
Valves
Hot Blast Valves Market
Valves
Sand Control System Market
Valves
Three Way Ball Valve Market
Valves
Compressor Valves Market
Valves
Pup Joint Market
Valves
Pipeline Equipment Market