
 Global Fluid Management Systems Market | 2026-2036
Global Fluid Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluid Management Systems Market Foresight
Pharmaceuticals Manufacturing is decoupling from traditional batch-processing fluid methods as continuous manufacturing adoption accelerates. Baxter International leverages its dialysis fluid platform expertise to sustain leadership in biopharma sterile fluid pathways. Stryker Corporation anchors its position through surgical irrigation systems that dominate orthopedic fluid management. Fresenius Medical Care competes via end-to-end renal fluid therapy integration across clinical and home settings.
Fluid management systems encompass integrated hardware and control architectures that regulate the transport, measurement, and conditioning of liquids across industrial and clinical environments, typically operating at pressures from vacuum to 10,000 psi with accuracy thresholds of ±0.5% full scale. Their primary purpose centers on ensuring process repeatability, contamination control, and real-time volumetric accountability in precision-dependent operations. Hydraulic Systems occupy the largest installed base across heavy manufacturing, though Metering Pumps generate disproportionate margin pools in pharmaceutical dispensing where pulsation-free dosing commands premium positioning. Electromagnetic flow measurement leads technology adoption in conductive fluid applications, while Ultrasonic sensing extends into non-invasive medical and food-grade channels where sensor contact risks contamination.
FDA 510(k) pathways and EU MDR technical documentation requirements are extending product development timelines for fluid-contacting medical devices, compelling manufacturers to front-load biocompatibility and sterility assurance testing. ISO 13485 quality system mandates and REACH substance restrictions on polymer additives further shape material selection and supply qualification protocols. Stakeholders must monitor how dual-use fluid technologies migrate between clinical and industrial domains, as regulatory jurisdiction ambiguity creates both compliance risk and first-mover positioning opportunities for firms with cross-certified product architectures.
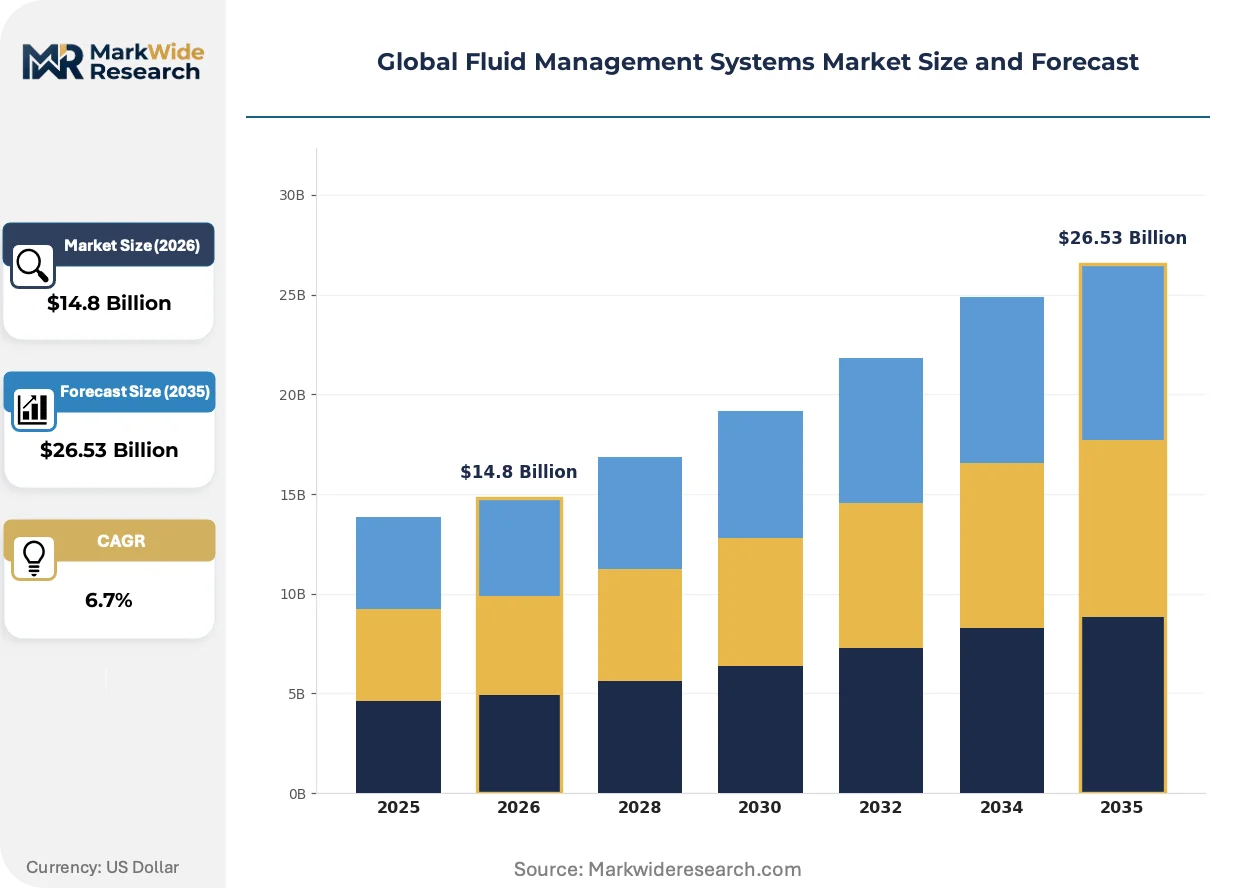
Market Dynamics
Closed-loop irrigation architectures are compressing installed system footprints while forcing incumbent hardware suppliers to requalify legacy pump and sensor portfolios under tightened FDA 510(k) and EU MDR biocompatibility protocols.
Growth Catalysts
- EU MDR compliance mandates:Sterility assurance documentation requirements are accelerating replacement cycles for pre-2017 fluid-contacting devices across German and French surgical centers.
- Continuous manufacturing adoption:Pharmaceutical producers are abandoning batch fluid processing in favor of real-time volumetric control systems that enable inline quality verification.
- Home-based renal therapy expansion:Fresenius Medical Care and Baxter International are scaling portable dialysis fluid platforms into patient residences, creating pull-through demand for compact metering pumps.
Market Restraints
- Polymer additive restrictions:REACH substance limitations on phthalates and bisphenols are constraining material options for disposable fluid-contacting components, elevating raw material qualification costs.
- Precision sensor supply concentration:Electromagnetic flowmeter cores and ultrasonic transducer substrates depend on specialized German and Japanese component suppliers, creating single-source vulnerability.
- Substitution by passive gravity systems:Low-acuity surgical settings in cost-constrained markets are reverting to simple gravity-fed irrigation, displacing powered fluid management platforms.
Strategic Opportunities
- India's CDSCO fast-track pathway:Streamlined medical device registration for fluid management systems meeting ISO 13485 standards opens underpenetrated surgical infrastructure in tier-2 hospital clusters.
- AI-enabled predictive maintenance:Machine learning algorithms applied to pump vibration and flow variance data are integrating with existing hardware to create service revenue streams.
- Point-of-care diagnostic fluidics:Microfluidic sample preparation modules for molecular diagnostics represent an adjacent application with limited incumbent competition.
Industry Challenges
- Cross-functional talent scarcity:Engineers combining fluid dynamics, embedded systems, and regulatory science expertise command premium compensation, constraining R&D scaling.
- Legacy system integration friction:New closed-loop platforms must interface with 15-20 year-old hospital building management systems lacking digital protocol compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluid Management Systems Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Systems, Pneumatic Systems, Metering Pumps, Flow Sensors, Level Controllers Technology: Electromagnetic, Ultrasonic, Positive Displacement, Volumetric, Magnetic Flow Application: Chemical Processing, Food & Beverage Production, Pharmaceuticals Manufacturing, Oil & Gas Operations, Water & Wastewater Treatment End User: Manufacturing Plants, Laboratories, Petroleum Refining, Agricultural Facilities, Municipal Utilities |
| Companies Covered | Baxter International, Stryker Corporation, B. Braun Melsungen AG, Medtronic, Fresenius Medical Care, Cardinal Health, Smith & Nephew, Ecolab, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluid Management Systems Market Shifts & Advancements
Digital twin architectures are migrating from process industries into clinical fluid management, enabling real-time simulation of pump performance degradation before hardware failure.
Smart sensor arrays with embedded edge computing are integrating pressure, flow, and temperature data into unified control loops. Orthopedic surgical centers in Germany and the United States are deploying these systems to eliminate manual flow adjustments during arthroscopy. The technology is integrating predictive algorithms that autonomously modulate irrigation pressure based on tissue resistance feedback.
EU MDR technical documentation requirements are extending sterile fluid pathway validation timelines by 12-18 months for manufacturers lacking prior notified body relationships. Device firms are front-loading biocompatibility testing and clinical evaluation reports to preempt regulatory queries. Renal therapy platforms face the most stringent scrutiny given their chronic patient contact duration.
Hospital procurement departments are consolidating fluid management system vendors to reduce qualification overhead and service contract fragmentation. Multi-year performance agreements with guaranteed uptime metrics are displacing transactional equipment purchases in academic medical centers. This concentration is most visible in the United States, where health system mergers have created purchasing entities spanning 200-plus facilities.
Global Fluid Management Systems Market Segmentation
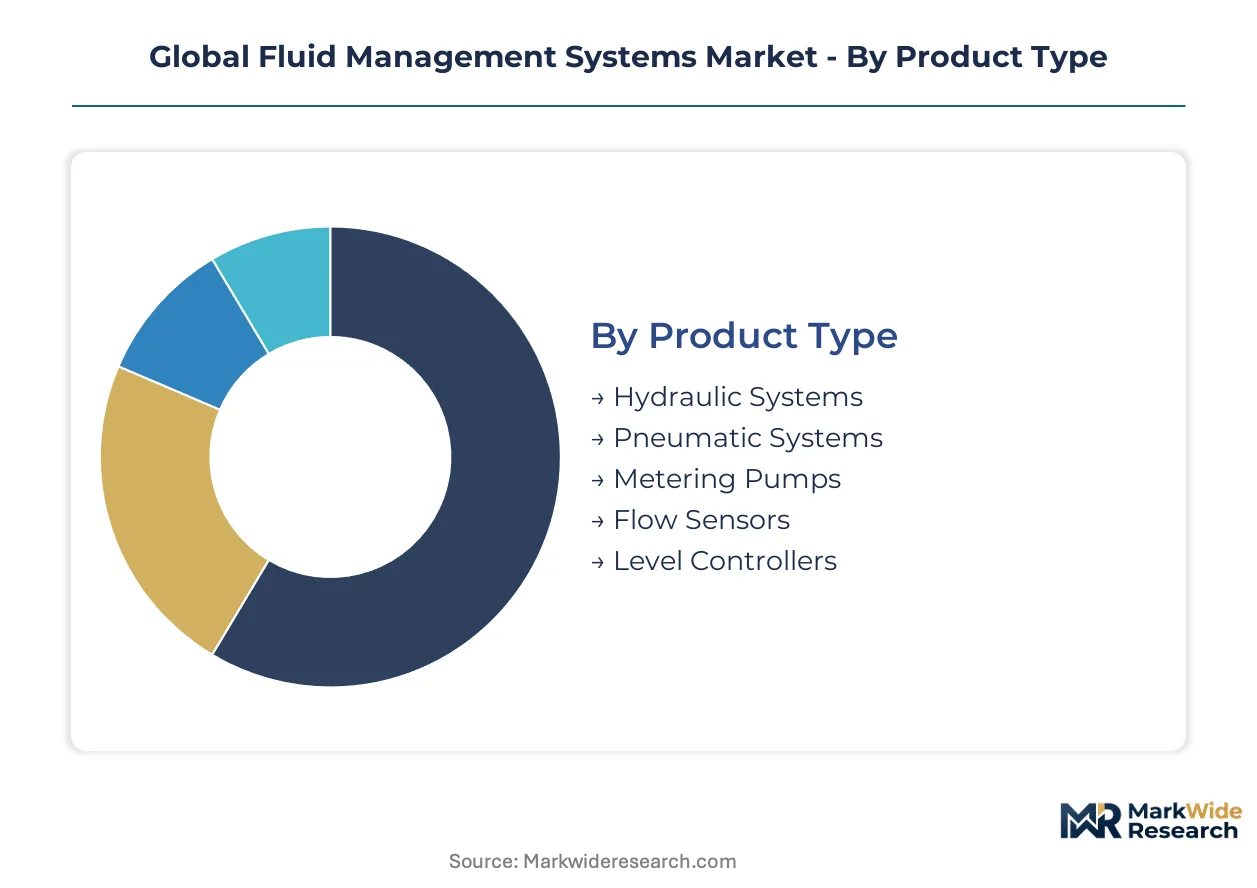
Fluid management systems fragment across four dimensions that determine procurement criteria, certification pathways, and margin structures. Product type dictates hardware complexity and replacement cycles. Technology selection hinges on fluid conductivity and contamination risk. Application verticals impose distinct regulatory regimes. End-user scale shapes service contract economics and integration requirements.
Product Type:
FDA 510(k) clearance applies to Metering Pumps and Flow Sensors in medical fluid pathways, while Hydraulic Systems face machinery directive compliance in industrial deployments. EU MDR technical documentation demands intensify for devices contacting sterile fluids in surgical settings.
- Hydraulic Systems:High-pressure fluid power architectures operating up to 10,000 psi dominate heavy manufacturing and construction equipment. German automotive stamping plants and Japanese machine tool builders anchor replacement demand amid energy efficiency retrofit mandates.
- Metering Pumps:Pulsation-free positive displacement mechanisms deliver pharmaceutical dosing accuracy within ±0.5% variance. Continuous manufacturing adoption across FDA-inspected biopharma facilities in Massachusetts and North Carolina accelerates demand for multi-channel precision dispensing units.
- Pneumatic Systems:Compressed air-driven fluid handling serves explosion-sensitive chemical environments where electrical ignition risks preclude motorized alternatives.
- Flow Sensors:Real-time volumetric measurement devices integrate with building management systems for leak detection and consumption accounting.
- Level Controllers:Reservoir monitoring hardware prevents pump cavitation and overflow events in bulk storage applications.
Leading the category by volume: Hydraulic Systems. Growing fastest: Metering Pumps.
Technology:
Cost tiering separates premium non-contact measurement from commodity mechanical alternatives. Electromagnetic and Ultrasonic platforms command 3-5x pricing multiples over Positive Displacement mechanisms due to sensor substrate precision and signal processing complexity.
- Electromagnetic:Faraday's law-based conductive fluid measurement achieves ±0.2% accuracy without flow obstruction. Water utilities in Singapore and Netherlands deploy these for non-revenue water reduction programs.
- Ultrasonic:Transit-time and Doppler variants measure non-conductive and slurry flows through pipe wall coupling. Food-grade dairy processing in Wisconsin and Bavaria favors clamp-on configurations eliminating product contact.
- Positive Displacement:Gear, piston, and diaphragm mechanisms deliver precise volumetric capture for custody transfer and batching operations.
- Volumetric:Direct capacity measurement systems serve pharmaceutical tablet coating and chemical reactor feed control.
- Magnetic Flow:Specialized electromagnetic variants with ceramic-lined tubes withstand abrasive mining slurries and pulp stock.
Highest margin tier: Ultrasonic. Steepest volume expansion: Electromagnetic.
Application:
Customer maturity varies sharply across verticals. Pharmaceuticals Manufacturing demands ISO 13485 and FDA 21 CFR Part 11 validation documentation. Chemical Processing operates under EPA Risk Management Plan and OSHA Process Safety Management protocols with less stringent equipment traceability.
- Pharmaceuticals Manufacturing:Sterile fluid pathways for bioreactor media and chromatography buffers require USP Class VI materials and gamma-stable polymers. Continuous processing adoption at Merck and Roche facilities drives real-time analytical integration.
- Oil & Gas Operations:High-pressure hydraulic fracturing and subsea production systems operate in H2S-corrosive environments. Permian Basin operators in Texas and North Dakota prioritize API 6A certification for wellhead control systems.
- Chemical Processing:Aggressive acid and caustic handling demands Hastelloy and titanium wetted components.
- Food & Beverage Production:3-A Sanitary Standards and EHEDG compliance govern CIP/SIP-compatible designs for dairy and brewing.
- Water & Wastewater Treatment:Municipal disinfection and sludge dewatering applications favor cost-optimized electromagnetic metering.
Most stringent certification burden: Pharmaceuticals Manufacturing. Fastest upgrade cycle: Oil & Gas Operations.
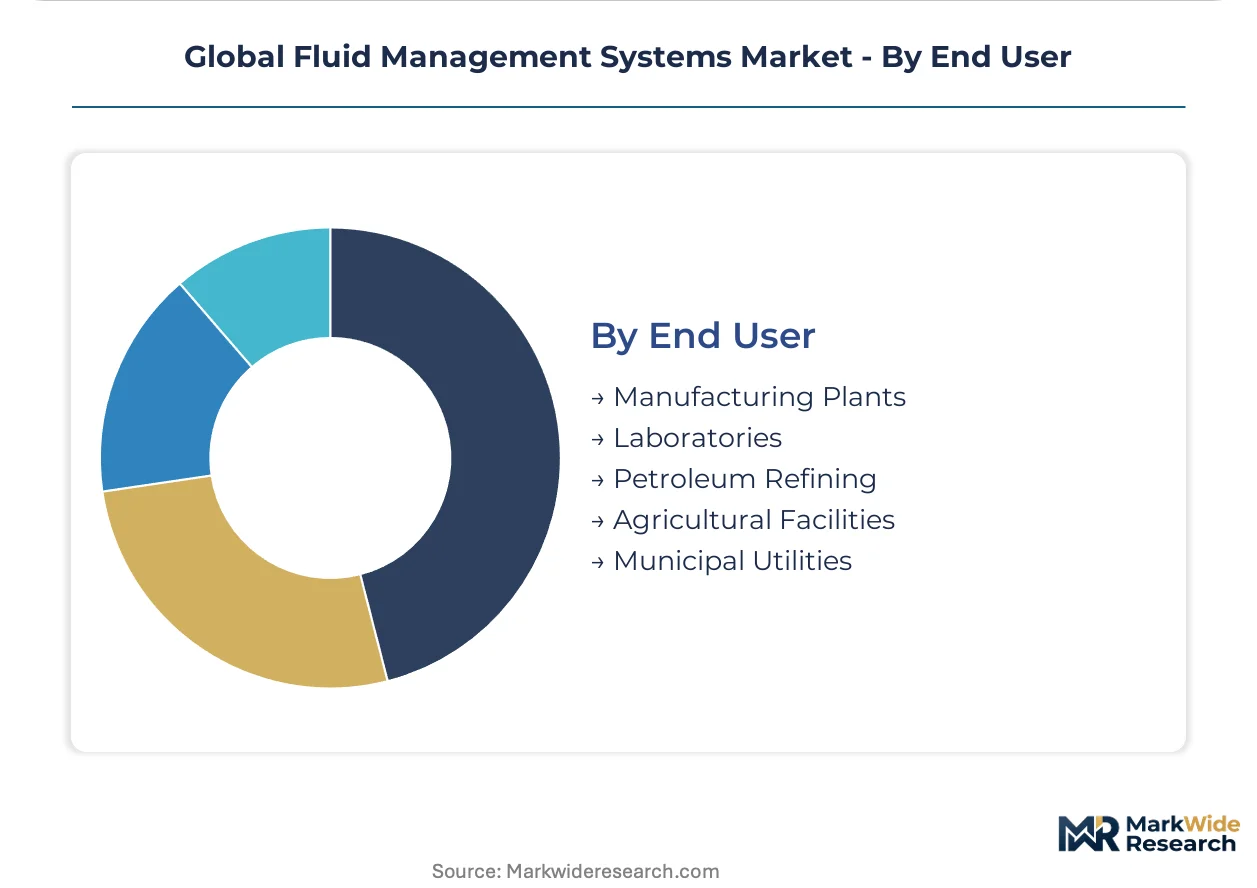
End User:
Procurement concentration separates enterprise-scale manufacturing from fragmented municipal purchasing. Petroleum Refining and Manufacturing Plants negotiate multi-year framework agreements with uptime guarantees. Agricultural Facilities and Municipal Utilities rely on distributor networks with limited technical specification influence.
- Manufacturing Plants:Discrete and process automation environments integrate fluid management with MES and SCADA architectures. German automotive OEMs specify predictive maintenance interfaces for stamping press hydraulics.
- Municipal Utilities:Drinking water treatment and distribution networks face AWWA and EPA Safe Drinking Water Act compliance. California's urban water districts prioritize AMI-enabled flow monitoring for drought response.
- Laboratories:Research and quality control settings demand gravimetric calibration traceability and LIMS connectivity.
- Petroleum Refining:FCCU and hydrocracker units require high-temperature alloy construction for catalytic feed systems.
- Agricultural Facilities:Irrigation and fertigation systems operate in remote locations with limited technical service access.
Dominant procurement scale: Manufacturing Plants. Emerging specification influence: Municipal Utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision fluid control manufacturing while the United States drives surgical platform consumption. China scales domestic metering pump capacity for pharmaceutical applications. Japan maintains ultrasonic sensor substrate leadership amid supply chain recalibration.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria anchor hydraulic system production for automotive stamping presses. EU MDR sterility assurance documentation compels surgical device manufacturers to requalify fluid-contacting components. Stuttgart-based automation OEMs specify predictive maintenance interfaces for closed-loop irrigation platforms.
United States
Academic medical centers across Massachusetts and North Carolina deploy continuous manufacturing fluid systems for biopharma production. FDA 510(k) clearance pathways extend validation timelines for renal therapy platforms facing chronic patient contact scrutiny. Texas Permian Basin operators prioritize API 6A certification for high-pressure hydraulic fracturing control systems.
China
Domestic pharmaceutical producers in Jiangsu and Zhejiang provinces accelerate adoption of pulsation-free metering pumps for bioreactor media handling. NMPA medical device registration reforms streamline approval for ISO 13485-certified fluid management systems. Shanghai-based automation integrators build localized supply chains for electromagnetic flowmeter assembly.
Japan
Ultrasonic transducer substrate fabrication concentrates in Nagoya and Osaka industrial corridors. METI energy efficiency mandates drive retrofit demand for compact hydraulic units in machine tool applications. Yokohama precision component suppliers face capacity constraints amid German and US sensor orders.
India
Tier-2 hospital clusters in Maharashtra and Karnataka create pull-through demand for surgical irrigation platforms. CDSCO fast-track pathways for ISO 13485-compliant devices accelerate market entry for fluid management system vendors. Ahmedabad pharmaceutical manufacturers invest in continuous processing fluid control for export-oriented API production.
Global Fluid Management Systems Market Competitive Landscape
Top-tier vendors anchor multi-platform fluid therapy integration, while mid-cap specialists concentrate on single-modality precision dispensing. The vendor base stratifies across three archetypes: diversified medical technology conglomerates with renal and surgical portfolios, pure-play surgical irrigation specialists, and industrial fluid control fabricators with medical crossover capabilities. M&A activity targets electromagnetic sensor substrate suppliers and microfluidic diagnostic module developers. Geographic expansion focuses on CDSCO-registered entities for Indian hospital procurement.
Among diversified medical technology conglomerates, Baxter International and Fresenius Medical Care exemplify end-to-end renal fluid therapy integration across clinical and home settings. Stryker Corporation occupies a position within surgical irrigation system supply to orthopedic centers. These three entities represent distinct competitive vectors: dialysis platform expertise, surgical fluid control specialization, and chronic therapy home delivery infrastructure.
| Leading Market Players |
|---|
| Baxter International |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Medtronic |
| Fresenius Medical Care |
| Cardinal Health |
| Smith & Nephew |
| Ecolab |
| CONMED Corporation |
| Others |
Supply & Pricing Matrix
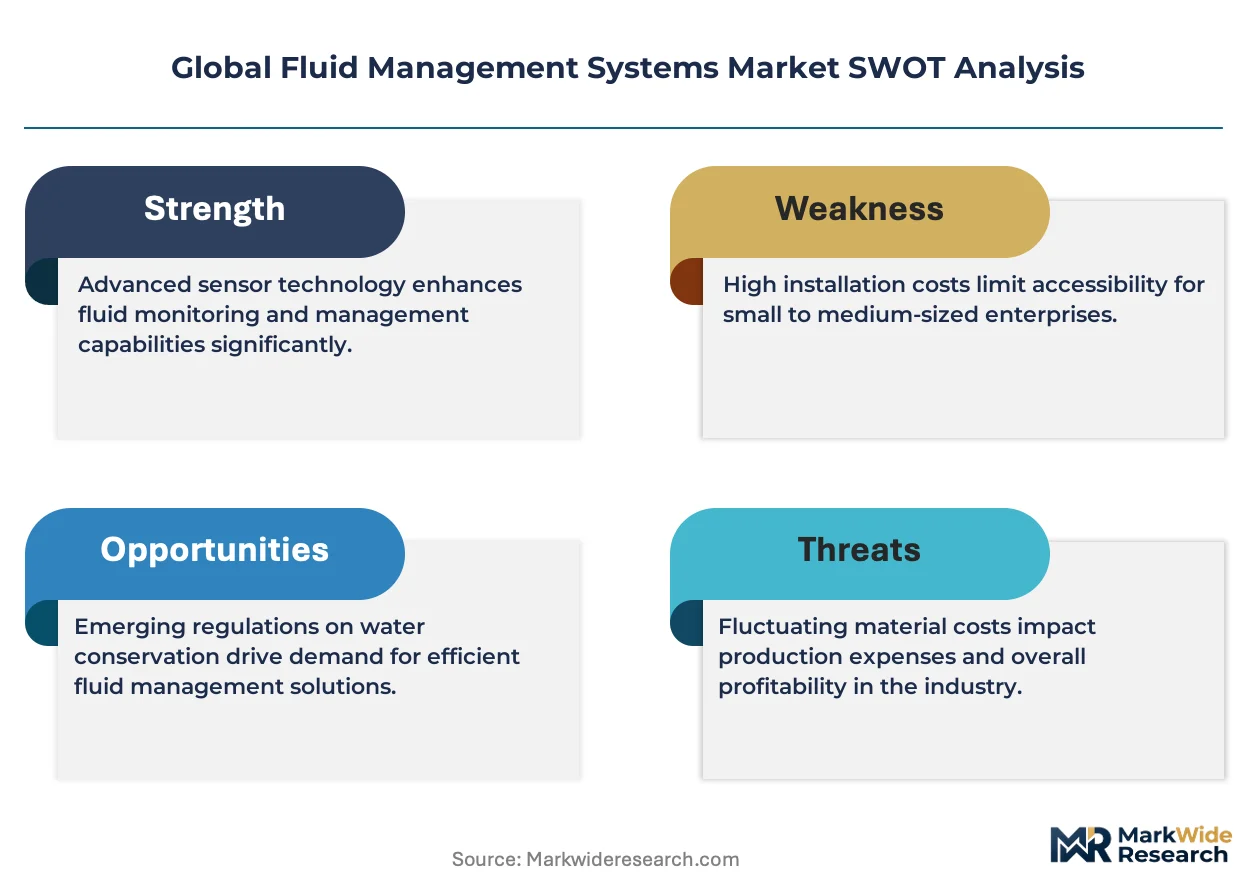
Specialized polymer feedstock indices for medical-grade fluoropolymers and gamma-stable thermoplastics cascade through three pricing tiers, compressing margins for disposable component suppliers while concentrating margin capture with electromagnetic flowmeter core manufacturers in Germany and Japan.
Pricing Analysis
Cost-down pressure on standard-grade metering pumps accelerates because REACH substance restrictions on phthalates and bisphenols force raw material reformulation. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared surgical platforms from industrial hydraulic systems and gravity-fed alternatives. ISO 13485 certification tier and after-sales service bundling drive price differentiation. Municipal utilities in cost-constrained markets exhibit highest price sensitivity, while German orthopedic surgical centers demonstrate lowest sensitivity due to guaranteed uptime contracting.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Singapore, and Cleveland orchestrate hub-and-spoke patterns for precision sensor substrates and sterile fluid-contacting components. Manufacturing concentrates in Germany for hydraulic systems, Japan for ultrasonic transducer substrates, and China for electromagnetic flowmeter assembly. Supply chains rest on niobium-doped piezoelectric ceramics, medical-grade fluoropolymer resins, and rare-earth magnetic cores. Single-source vulnerability for electromagnetic flowmeter cores creates structural risk. Distribution runs through authorized distributor networks with technical specification influence for manufacturing plants and GPO-aggregated procurement for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR sterility assurance documentation functions as a cost-of-compliance moat, elevating replacement cycles for pre-2017 fluid-contacting devices and advantaging manufacturers with established notified body relationships.
For Market Incumbents:Cement market position by acquiring electromagnetic sensor substrate suppliers in Nagoya and Osaka corridors to secure single-source component access. Expand ISO 13485-certified production capacity in Baden-Württemberg to capture EU MDR-driven replacement demand. Passive gravity system substitution in emerging markets represents the primary volume threat requiring defensive pricing protocols.
For New Entrants and Emerging Players:Distributor partnerships with Ahmedabad-based pharmaceutical automation integrators unlock tier-2 Indian hospital clusters through CDSCO fast-track pathways. Target underpenetrated point-of-care diagnostic fluidics for molecular diagnostics sample preparation, where incumbent competition remains limited. Pursue white-label manufacturing arrangements with German precision component suppliers to bypass capital-intensive cleanroom infrastructure requirements.
For Investors and Strategic Acquirers:Distressed-cycle entries favor microfluidic diagnostic module developers with NMPA registration progress in Jiangsu province. Five-to-ten year viability hinges on cross-certified product architectures spanning clinical and industrial domains. Monitor AI-enabled predictive maintenance algorithm adoption rates as the inflection signal for service revenue stream maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Extends sterility validation timelines by 12-18 months for manufacturers lacking notified body relationships. |
| Electromagnetic Sensor Substrate Acquisition | Secures niobium-doped piezoelectric ceramic supply from Nagoya precision component suppliers facing capacity constraints. |
| CDSCO Registration Fast-Track Utilization | Accelerates market entry for ISO 13485-compliant systems into Maharashtra and Karnataka tier-2 hospital clusters. |
| AI Predictive Maintenance Platform Development | Integrates pump vibration and flow variance data into service revenue streams for orthopedic surgical centers. |
| Continuous Manufacturing Fluid Control Partnership | Aligns with Merck and Roche facilities abandoning batch processing for real-time volumetric control systems. |
Research Methodology
Independent corroboration across FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, and electromagnetic flowmeter customs records underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital GPO contracts managers, pharmaceutical manufacturing executives, and precision component procurement leads combined with secondary validation from SEC 10-K filings, ISO certification registries, and REACH substance restriction updates. Bottom-up demand modeling across product type, technology, application, and end-user segments triangulates against top-down market sizing.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product hardware complexity, fluid measurement technology conductivity requirements, regulatory certification tier, and end-user procurement scale. CAGRs derive from installed base replacement cycles, continuous manufacturing adoption curves, and home-based renal therapy penetration patterns. Forecast inputs incorporate EU MDR compliance deadline impacts and NMPA registration reform implementation timelines.
Caveats apply where REACH substance restriction scope expansion or electromagnetic sensor substrate supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory implementation pace and hospital capital expenditure continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Insulation Flanges Market
Valves
Explosion Isolation Valves Market
Valves
Diaphragm Valve Market
Valves
Gas Equipment Market
Valves
Flanges Market
Valves
Asia Pacific Pipeline Maintenance Market
Valves
Emergency Venting System Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Pipeline Equipment Market
Valves
Degassing Valves Market
Valves
Pipeline and Process Services Market
Valves
Valve Cover Gasket Market
Valves
Industrial Safety Valves Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Pinch Valve Market
Valves
Subsea Valves Market