
 Solar Hydrogen Panel Market | 2026-2036
Solar Hydrogen Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Hydrogen Panel Market Outlook
Utility-scale power purchasers is collapsing as the dominant buyer archetype for solar hydrogen panels, while industrial off-takers in chemicals and steel are gaining share. Siemens Energy leverages its PEM electrolyzer expertise to anchor European project pipelines. Jinko Solar competes on module cost structure, extending its photovoltaic dominance into integrated hydrogen systems. Thyssenkrupp AG specializes in alkaline electrolysis scale-up, positioning its engineering base for heavy-industry deployment.
A solar hydrogen panel combines photovoltaic energy capture with integrated or coupled electrolysis to produce hydrogen gas directly from sunlight and water, typically operating at system efficiencies of 15-25% solar-to-hydrogen conversion depending on cell architecture and catalyst loading. Its primary purpose is to deliver storable, transportable renewable fuel for sectors where direct electrification proves technically or economically constrained. Photovoltaic Systems dominate installed base value, though Hybrid Systems capturing both electricity and hydrogen output command margin premiums in off-grid industrial configurations. PEM Electrolysis leads technology deployments for responsive, high-purity hydrogen production, while Alkaline Electrolysis sustains cost advantages in large baseload installations where grid stability supports continuous operation.
The EU Green Deal and Germany's national hydrogen strategy shape product certification requirements, mandating renewable origin guarantees that filter market access for non-compliant equipment. The EPA's emerging hydrogen production tax credit framework in the United States and Japan's METI hydrogen roadmap similarly steer capital toward electrolyzer-integrated solar configurations meeting strict carbon-intensity thresholds. Stakeholders must monitor how regulatory differentiation between gray, blue, and green hydrogen certifications reshapes equipment procurement criteria across jurisdictions.
Market Dynamics
Industrial hydrogen procurement is pivoting from centralized utility-scale tenders to distributed on-site generation, driven by electrolyzer cost compression and renewable hydrogen certification mandates under the EU Green Deal.
Growth Catalysts
- EU Green Deal Certification:Renewable origin guarantees for green hydrogen are filtering equipment procurement toward integrated solar-to-hydrogen systems that meet strict carbon-intensity thresholds.
- Steel Sector Decarbonization:German producers in the Ruhr industrial corridor are piloting solar hydrogen integration to replace coking coal in direct reduction processes.
- PEM Electrolyzer Cost Decline:Responsive, high-purity hydrogen production technology is reaching cost parity with alkaline systems for mid-scale industrial deployments.
Market Restraints
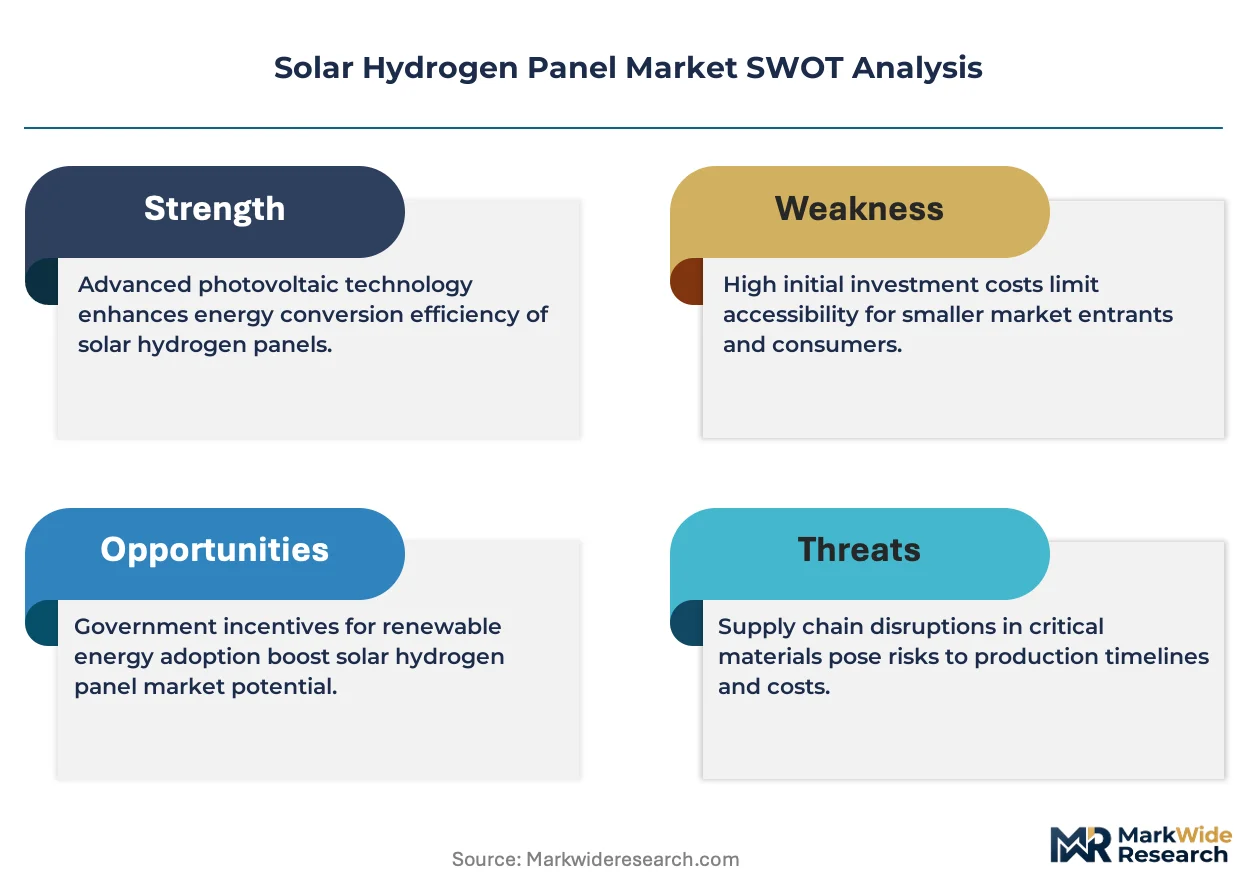
- Platinum Group Metal Dependency:Catalyst loading requirements for PEM electrolysis create exposure to South African and Russian supply concentration for iridium and platinum.
- Grid Interconnection Queues:Utility-scale solar hydrogen projects face 18-36 month delays for transmission access in Germany and Japan, compressing project IRRs.
- Alkaline Electrolyzer Inertia:Established baseload installations resist retrofit for variable renewable coupling, locking in continuous-operation economics against solar intermittency.
Strategic Opportunities
- Off-Grid Industrial Configurations:Remote mining and ammonia production sites in Australia and Chile are deploying hybrid systems capturing both electricity and hydrogen output.
- Japan's METI Hydrogen Roadmap:Import infrastructure subsidies are creating demand for containerized solar hydrogen production units at port industrial zones.
- Photoelectrochemical Convergence:Direct solar-to-hydrogen conversion without separate electrolyzer stacks is approaching 20% STH efficiency in laboratory demonstrations.
Industry Challenges
- Electrolyzer-Catalyst Integration:Mismatch between photovoltaic DC output profiles and electrolyzer optimal operating windows degrades system lifetime and warranty coverage.
- Renewable Hydrogen Certification Timelines:Third-party verification of additionality and temporal matching requirements under CertifHy and TÜV schemes extends project commissioning by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Hydrogen Panel Market |
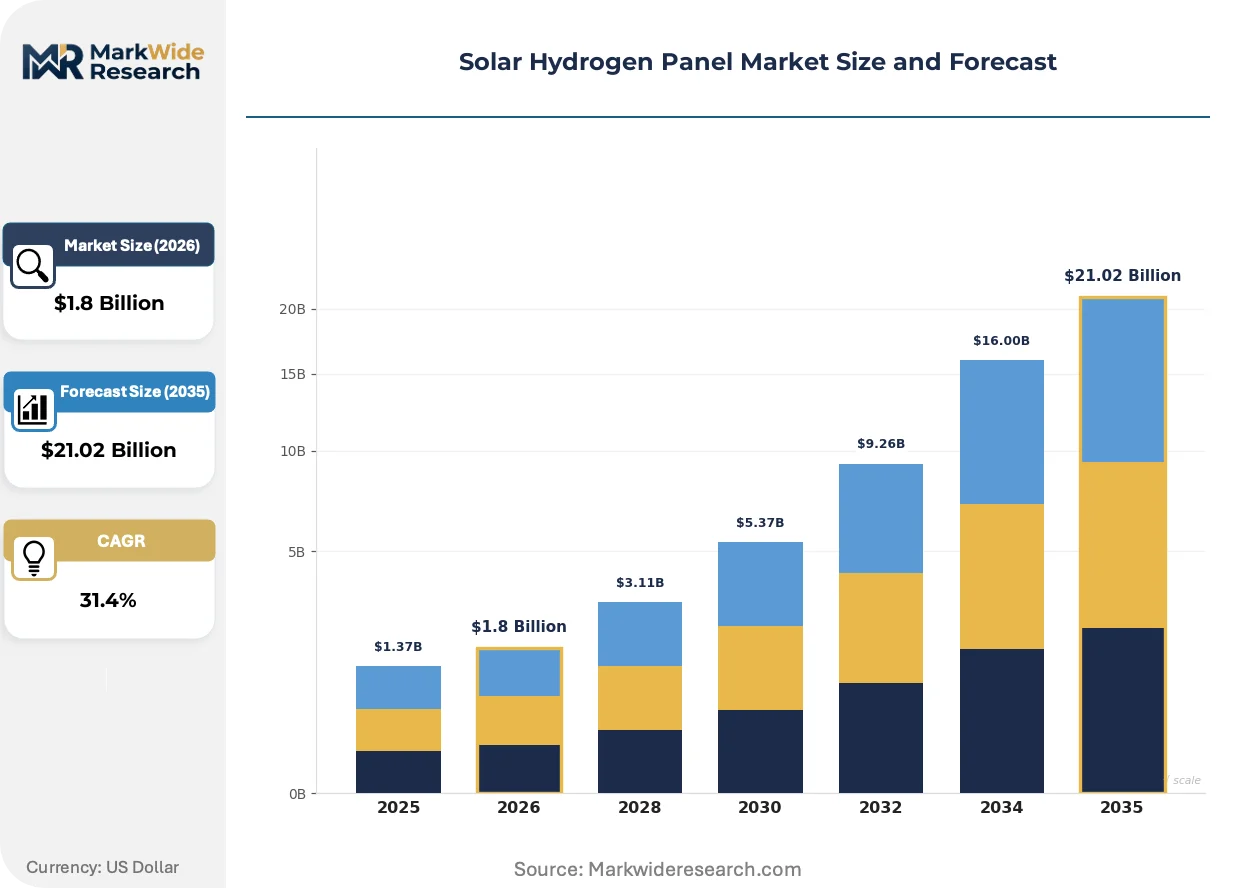
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $21.02 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Electrolyzer Units, Hybrid Systems, Fuel Cells Technology: Photovoltaics, Alkaline Electrolysis, PEM Electrolysis, Solar Thermal End Use: Transportation, Power Generation, Industrial Applications, Residential Use Installation Type: Ground Mounted, Rooftop, Portable, Utility Scale |
| Companies Covered | Sun Hydrogen Inc, Suzhou GH New Energy Co. Ltd., Flux50, SunPower Renewables, Jinko Solar, Siemens Energy, Linde plc, ITM Power plc, Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Hydrogen Panel Market Strategic Shifts
System architecture is fragmenting between centralized utility-scale arrays and modular distributed units, with divergent technology stacks emerging for each deployment mode.
Tandem photovoltaic-electrolysis architectures are bifurcating between integrated monolithic designs and physically separated but electrically coupled systems. Chemical producers in Germany's industrial corridor are adopting the latter for maintenance accessibility and component upgrade flexibility. This technology pathway is compressing the addressable market for traditional alkaline electrolyzer vendors while expanding margins for semiconductor-grade stack suppliers.
The EU Green Deal's Delegated Act on renewable hydrogen has triggered mandatory temporal correlation requirements between renewable generation and hydrogen production. Industrial off-takers must now demonstrate hourly matching rather than annual averaging, forcing equipment redesign toward responsive PEM stacks with rapid ramp capabilities. German steel and chemical producers are front-loading capital deployment to secure grandfathered certification status before 2028 phase-in deadlines.
Long-term hydrogen offtake contracting is displacing spot market exposure for project developers. Steel mills in Japan and chemical complexes in the Netherlands are locking in 10-15 year take-or-pay agreements with fixed escalators, transferring volume risk to end-users. This contracting evolution is most visible in Germany's Ruhr region, where Thyssenkrupp and BASF have established template power purchase agreements for solar hydrogen supply.
Solar Hydrogen Panel Market Segmentation
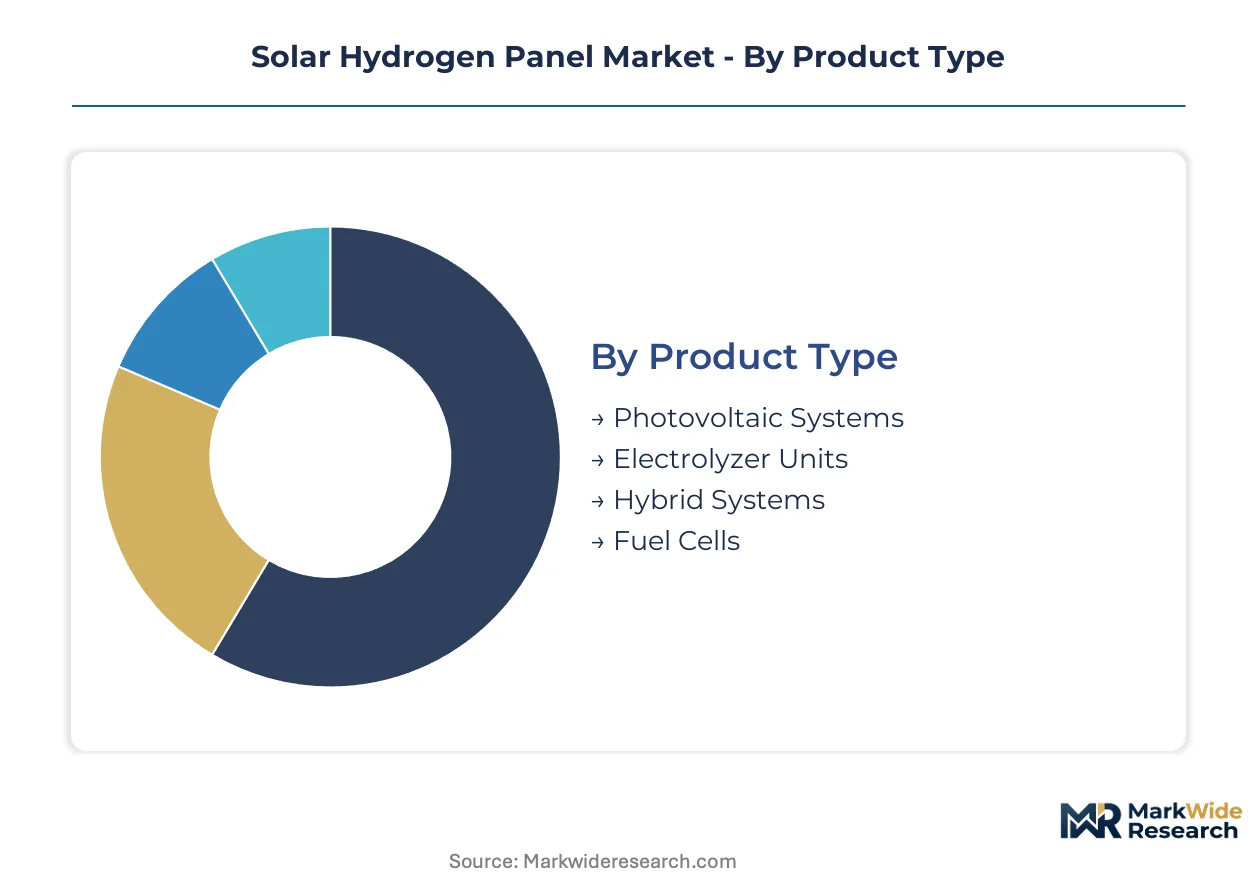
Solar hydrogen panel market segmentation reveals divergent margin structures across product architectures and deployment modes. Technology choices determine electrolyzer integration costs, while end-use applications dictate certification requirements and offtake contract structures.
Product Type:
Margin pools concentrate in systems that capture multiple revenue streams from electricity and hydrogen output rather than single-purpose equipment.
- Photovoltaic Systems:Standard crystalline silicon modules configured for DC coupling to external electrolyzer stacks dominate current installed value. German steel producers in the Ruhr corridor deploy these for grid-export fallback when hydrogen demand fluctuates.
- Electrolyzer Units:Standalone PEM and alkaline stacks sold for retrofit integration command lower margins than bundled systems. Japanese port industrial zones under METI subsidies are absorbing containerized units for import infrastructure pre-positioning.
- Hybrid Systems:Integrated architectures capturing both electricity and hydrogen output from shared photovoltaic arrays earn margin premiums in off-grid mining and ammonia sites across Australia and Chile.
- Fuel Cells:Reversible solid oxide systems enabling bidirectional hydrogen-to-power conversion occupy niche stationary backup roles where grid reliability constraints apply.
Photovoltaic Systems hold installed capacity. Hybrid Systems are rotating up the share rankings.
Technology:
Technology selection tracks end-use purity requirements and ramp-rate specifications rather than capital cost minimization alone.
- Photovoltaics:Tandem cell architectures with optimized spectral splitting for water splitting applications are approaching 20% solar-to-hydrogen conversion in pilot deployments. Chemical producers favor these for maintenance accessibility.
- PEM Electrolysis:Proton exchange membrane stacks with rapid response capabilities align with EU Green Deal hourly matching mandates. Thyssenkrupp and Siemens Energy anchor European project pipelines with this technology.
- Alkaline Electrolysis:Mature liquid electrolyte systems sustain cost advantages in large baseload configurations where grid stability supports continuous operation rather than solar-coupled variable output.
- Solar Thermal:Concentrating solar power with thermochemical water splitting avoids platinum group metal dependencies but requires high direct normal irradiance locations.
Alkaline Electrolysis holds installed capacity. PEM Electrolysis is rotating up the share rankings.
End Use:
End-use segmentation reflects divergent certification stringency and offtake contract duration across application categories.
- Industrial Applications:Steel direct reduction and ammonia synthesis drive procurement of certifiable renewable hydrogen with 10-15 year take-or-pay contracting. German and Dutch chemical complexes front-load capital deployment before 2028 grandfathering deadlines.
- Transportation:Heavy trucking and maritime fuel cell applications require high-purity hydrogen meeting ISO 14687 specifications, filtering toward PEM-based production systems.
- Power Generation:Grid-balancing and seasonal storage applications tolerate lower purity thresholds, opening cost advantages for alkaline electrolyzer integration.
- Residential Use:Distributed micro-CHP systems remain pre-commercial in most jurisdictions, constrained by building code integration and safety certification timelines.
Industrial Applications hold installed capacity. Transportation is rotating up the share rankings.
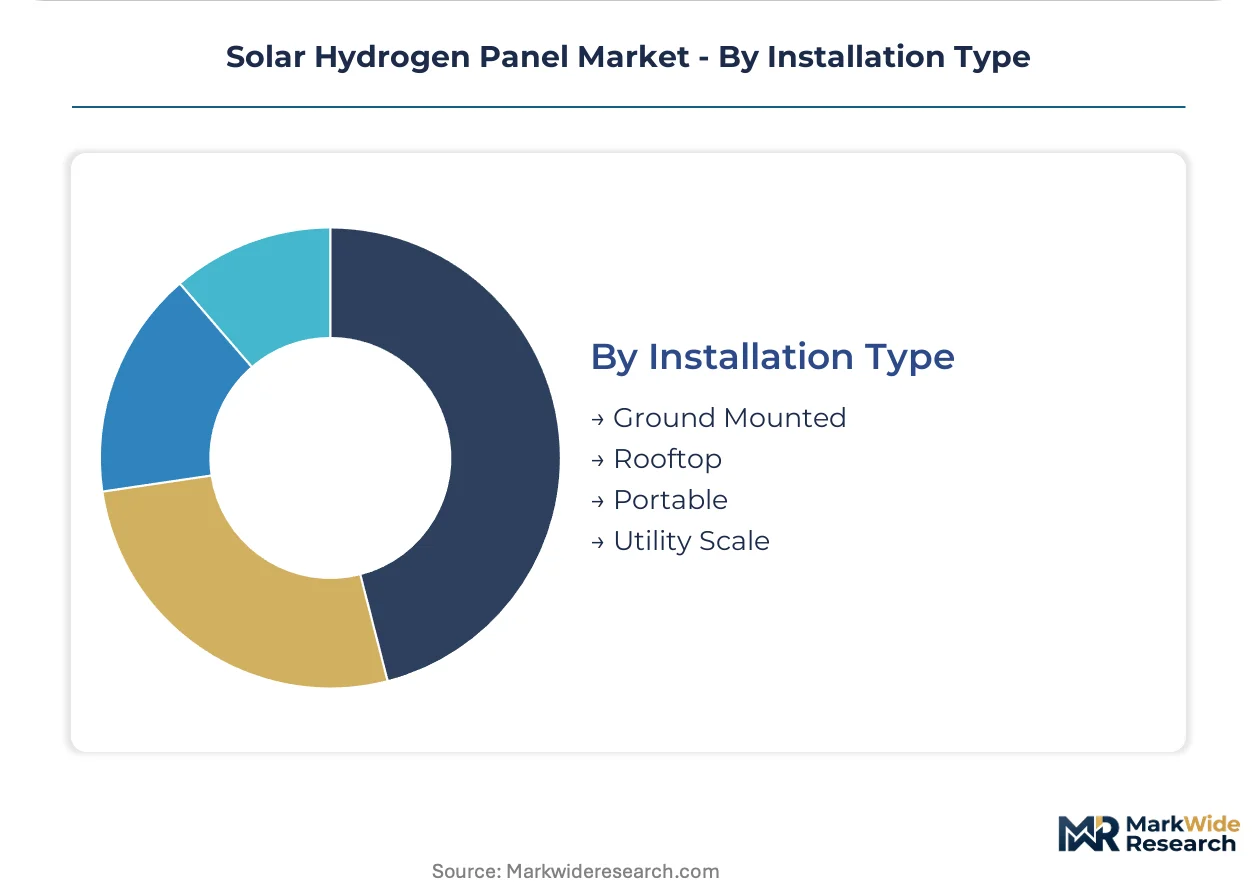
Installation Type:
Installation mode determines interconnection queue exposure and land use permitting complexity.
- Ground Mounted:Fixed-tilt and tracking arrays on dedicated land parcels dominate utility-scale project economics. German transmission access queues of 18-36 months compress project IRRs for this category.
- Utility Scale:Centralized arrays above 10 MW capacity with dedicated substations face the longest grid interconnection delays but achieve lowest levelized hydrogen costs through scale.
- Rooftop:Commercial and industrial building-integrated systems avoid land permitting but face structural load constraints and distributed energy resource interconnection standards.
- Portable:Containerized and skid-mounted units for remote deployment or emergency response trade capital efficiency against logistics flexibility.
Ground Mounted holds installed capacity. Utility Scale is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SoutH2 corridor pipeline anchors Germany's position as Europe's hydrogen distribution hub, while Japan's Kobe liquefied hydrogen import terminal underwrites Asia-Pacific demand. The United States leverages Gulf Coast hydrogen infrastructure, and Australia's Pilbara Energy Transition Hub concentrates export-oriented production. Chile's Atacama Desert solar irradiance underwrites South American project economics.
Germany
Ruhr industrial corridor steel and chemical producers pilot solar hydrogen integration for direct reduction processes. The EU Green Deal's Delegated Act mandates hourly temporal matching between renewable generation and hydrogen production from 2028. Thyssenkrupp and BASF in North Rhine-Westphalia have established template power purchase agreements for solar hydrogen supply.
Japan
Port industrial zones under METI subsidies absorb containerized solar hydrogen production units for import infrastructure pre-positioning. The country's hydrogen roadmap steers capital toward electrolyzer-integrated solar configurations meeting strict carbon-intensity thresholds. Kobe and Yokohama port clusters host pilot deployments for maritime fuel cell applications requiring ISO 14687 purity specifications.
United States
The EPA's emerging hydrogen production tax credit framework steers capital toward electrolyzer-integrated solar configurations. Texas and California industrial clusters face 18-36 month transmission interconnection queues that compress project IRRs for utility-scale deployments. Gulf Coast petrochemical complexes explore solar hydrogen for ammonia synthesis and refinery decarbonization.
Australia
Remote mining and ammonia production sites in Western Australia deploy hybrid systems capturing both electricity and hydrogen output. The Pilbara Energy Transition Hub concentrates export-oriented production for Asian offtakers. High direct normal irradiance locations favor concentrating solar power with thermochemical water splitting pilots.
Chile
Atacama Desert solar irradiance underwrites South American project economics for export-oriented green hydrogen. Mining operations in Antofagasta Region pilot solar hydrogen for heavy machinery fuel cell conversion. The country's national mining regulator coordinates safety certification for hydrogen integration at copper extraction sites.
Solar Hydrogen Panel Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized electrolyzer engineering firms. The vendor base spans three tiers: integrated energy majors with captive project pipelines, pure-play electrolyzer stack suppliers, and photovoltaic module incumbents extending into hydrogen systems. Strategic moves center on backward integration into semiconductor-grade catalyst supply and forward integration into long-term hydrogen offtake contracting.
Within the electrolyzer engineering tier, Thyssenkrupp AG and Siemens Energy anchor European project development. Jinko Solar represents photovoltaic incumbents extending module dominance into integrated hydrogen configurations. Among specialized hydrogen technology developers, ITM Power plc and Sun Hydrogen Inc occupy positions as pure-play stack suppliers.
| Leading Market Players |
|---|
| Sun Hydrogen Inc |
| Suzhou GH New Energy Co. Ltd. |
| Flux50 |
| SunPower Renewables |
| Jinko Solar |
| Siemens Energy |
| Linde plc |
| ITM Power plc |
| Thyssenkrupp AG |
| Others |
Value Chain & Pricing Dynamics
Alkaline-to-PEM technology substitution in electrolyzer procurement is redrawing supplier geography from Chinese manufacturing clusters toward European semiconductor-grade stack producers, compressing price premiums for responsive systems while elevating logistics costs for iridium catalyst sourcing.
Pricing Analysis
Volume-discount tiering structures separate utility-scale offtakers securing 10-15 year take-or-pay contracts from distributed industrial buyers facing spot-equivalent pricing. Price differentiation rests on certification grade under EU Green Deal Delegated Act compliance and electrolyzer ramp-rate specifications. Cost compression in alkaline systems is intensifying because Chinese manufacturers are scaling production for grid-coupled baseload installations. Chemical producers in Germany's Ruhr corridor exhibit lowest price sensitivity due to grandfathering deadlines, while remote mining operators in Australia and Chile face acute capital constraints.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg is elevating inbound logistics costs for containerized PEM electrolyzer stacks arriving from South Korean and Japanese fabrication facilities. Manufacturing concentration centers on China for alkaline systems, Germany for precision-engineered PEM stacks, and South Africa for iridium and platinum catalyst feedstock. Raw material dependencies encompass iridium from South African mining operations, platinum group metals from Russian suppliers under sanction exposure, and semiconductor-grade titanium for bipolar plates. Single-source vulnerability concentrates in catalyst supply, where South African refining capacity dominates global output. Distribution runs through EPC contractors with captive relationships to steel and chemical majors in North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial buyer consolidation around Thyssenkrupp, BASF, and Siemens Energy long-term offtake agreements is shifting negotiating leverage toward volume-committed purchasers and away from project developers.
For Market Incumbents: Compound electrolyzer-catalyst integration capabilities through backward integration into iridium recovery and recycling operations. Defend project pipelines against photoelectrochemical convergence threats by front-loading PEM stack deployments before laboratory-scale direct conversion reaches commercial viability. Prioritize certification investment under TÜV and CertifHy schemes to lock in grandfathered status for existing installations. For New Entrants and Emerging Players: Differentiate on containerized modular architectures for Japan's port industrial zones under METI subsidy windows. White-space targets include remote ammonia synthesis sites in Western Australia and Chilean mining operations seeking heavy machinery fuel cell conversion. Pursue joint development agreements with established EPC contractors lacking in-house electrolyzer engineering competence. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play stack suppliers holding ITM Power-type technology positions but lacking captive offtake channels. Five-to-ten year viability hinges on electrolyzer cost curves sustaining decline trajectories against alkaline system inertia. Acquisition target archetype: semiconductor-grade catalyst coating specialists with iridium thrifting intellectual property. Signal to watch: hourly temporal matching enforcement acceleration under EU Green Deal implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Recovery | Iridium recycling capabilities insulate Thyssenkrupp and Siemens Energy from South African supply concentration. |
| Long-term Hydrogen Offtake Contracting | Steel mills in Japan and chemical complexes in the Netherlands transfer volume risk through 10-15 year take-or-pay structures. |
| Containerized Modular System Deployment | Skid-mounted units address Japan's Kobe and Yokohama port clusters under METI import infrastructure subsidies. |
| PEM Electrolyzer Cost Compression | Responsive stack technology reaches parity with alkaline systems for mid-scale industrial deployments in Germany's Ruhr corridor. |
| Green Certification Program Investment | TÜV and CertifHy compliance secures market access under EU Green Deal renewable hydrogen mandates. |
Study Parameters
The analysis maps photovoltaic system architectures, electrolyzer technology stacks, hybrid system configurations, and fuel cell integration pathways, each validated through project developers at IPPs, EPC contractors, utility planning officers, and industrial procurement leads at steel and chemical complexes. Primary fieldwork combined structured interviews with secondary validation against EIA hydrogen production databases, IEA technology roadmaps, FERC interconnection queue filings, and EU Green Deal delegated act documentation. Bottom-up project pipeline aggregation triangulated against top-down market sizing from equipment shipment records.
Consistency checks validated volume and value outputs against external benchmarks including electrolyzer manufacturing capacity announcements and announced offtake contract volumes. The analytical framework modeled technology segmentation across PEM and alkaline electrolysis, product architecture across integrated and coupled systems, end-use applications across steel, ammonia, and transportation fuel, and installation scale across utility and distributed configurations. CAGRs were derived from equipment cost curve trajectories and policy mandate implementation schedules. Forecast inputs encompassed electrolyzer learning rate assumptions and renewable hydrogen certification timeline acceleration.
Decision-makers should treat outputs as directional under base assumptions of sustained electrolyzer cost decline and EU Green Deal enforcement continuity; material deviation in catalyst supply disruption or regulatory grandfathering extension would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
Partial Oxidation Blue Hydrogen Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Hydrogen Production Electrolyser Market